
 Middle East and Africa Hybrid Electric Vehicle Battery Market | 2026-2036
Middle East and Africa Hybrid Electric Vehicle Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hybrid Electric Vehicle Battery Market Insights
South Africa's nascent cell assembly corridor is fragmenting as multiple industrial zones compete for anchor tenants. LG Energy Solution leverages its cylindrical cell expertise to supply premium passenger vehicle programs. Samsung SDI anchors regional demand through partnerships with European OEMs exporting into African markets. BYD Company Limited dominates commercial bus electrification with its blade cell architecture.
Hybrid electric vehicle batteries combine electrochemical storage modules with internal combustion engine management systems, typically employing lithium-ion cells with nickel-manganese-cobalt cathode formulations rated for 300-800 volt architectures and 5-15 kilowatt-hour usable capacities to enable regenerative braking capture and torque-assist functions. The battery type dimension shows Li-ion chemistry commanding the premium segment while NiMH retains cost-sensitive fleet applications. Application segmentation reveals commercial vehicles generating the fastest procurement velocity as logistics operators seek fuel hedging against volatile diesel pricing across the region.
South Africa's carbon tax regime and the UAE's MOHAP-backed green procurement standards are tightening emissions accountability for fleet operators, while EMA-aligned CE marking requirements govern imported battery systems from European suppliers. Saudi Arabia's SFDA and SASO technical regulations are converging on thermal runaway testing protocols for desert climate operation. Stakeholders must monitor which regulatory cluster—Gulf standardization, South African fiscal policy, or Moroccan EU trade alignment—sets the dominant compliance baseline for cross-border battery shipments.
Market Dynamics
Dubai's RTA electrification mandates are compressing procurement cycles for heavy-duty hybrid powertrains, while South Africa's carbon taxation recalibrates fleet total cost of ownership calculations across municipal and logistics operators.
Growth Catalysts
- Carbon Taxation Regimes:South Africa's carbon tax mechanism penalizes diesel-intensive fleets, accelerating hybrid powertrain adoption among commercial vehicle operators seeking fuel cost hedging.
- Municipal Electrification Mandates:Dubai's RTA procurement specifications now require hybrid or zero-emission powertrains for new bus fleet additions, creating guaranteed demand anchors for battery suppliers.
- Blade Cell Architecture:Advanced lithium iron phosphate cell-to-pack designs are reducing thermal management complexity and enabling faster integration into high-utilization commercial platforms.
Market Restraints
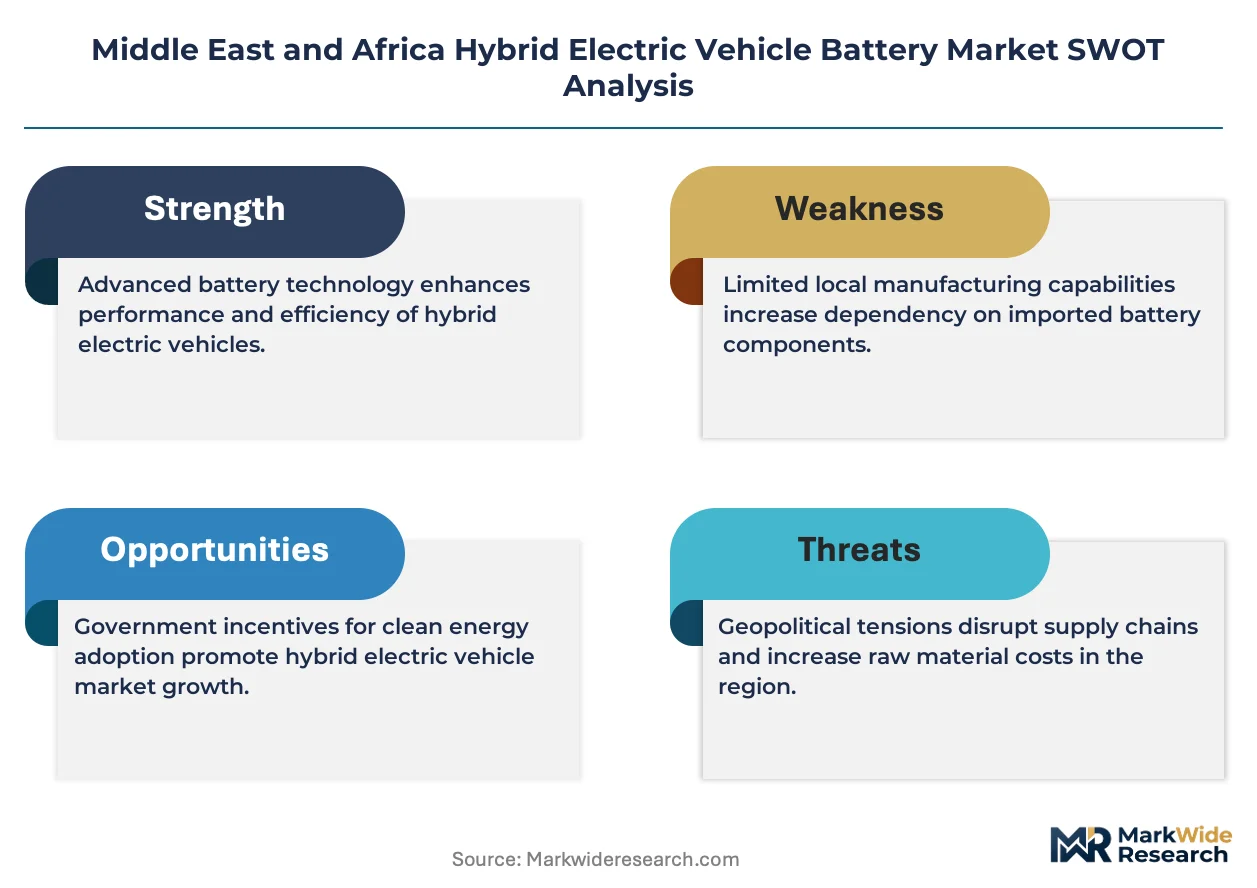
- Lithium Price Volatility:Spodumene concentrate and lithium carbonate spot market fluctuations are compressing cell manufacturer margins and destabilizing long-term supply agreements with African assemblers.
- Desert Climate Thermal Runaway Risks:Ambient temperatures exceeding 50°C in Gulf Cooperation Council territories necessitate enhanced battery cooling architectures that add cost and weight penalties.
- Second-Life Battery Competition:Repurposed electric vehicle battery packs from European and East Asian markets are entering African secondary markets as lower-cost alternatives for stationary storage applications.
Strategic Opportunities
- Morocco's EU Trade Alignment:Casablanca-Tangier industrial corridor positioning as CE-marked battery assembly hub for re-export into European aftermarket channels.
- Renewable-Integrated Charging Infrastructure:Solar-hybrid microgrid installations at Saudi Arabian logistics hubs enabling off-grid fleet charging and reducing diesel generator dependency.
- EMA-Aligned Technical Standards:CE marking requirements for imported battery systems are creating certification-service revenue streams for regional testing laboratories.
Industry Challenges
- Cell Chemistry Expertise Scarcity:Regional universities lack specialized programs in electrochemical engineering, forcing manufacturers to import technical talent from East Asian battery clusters.
- Desert-Specific Validation Timelines:SASO thermal runaway testing protocols require extended accelerated aging studies under extreme temperature cycling, stretching product certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hybrid Electric Vehicle Battery Market |
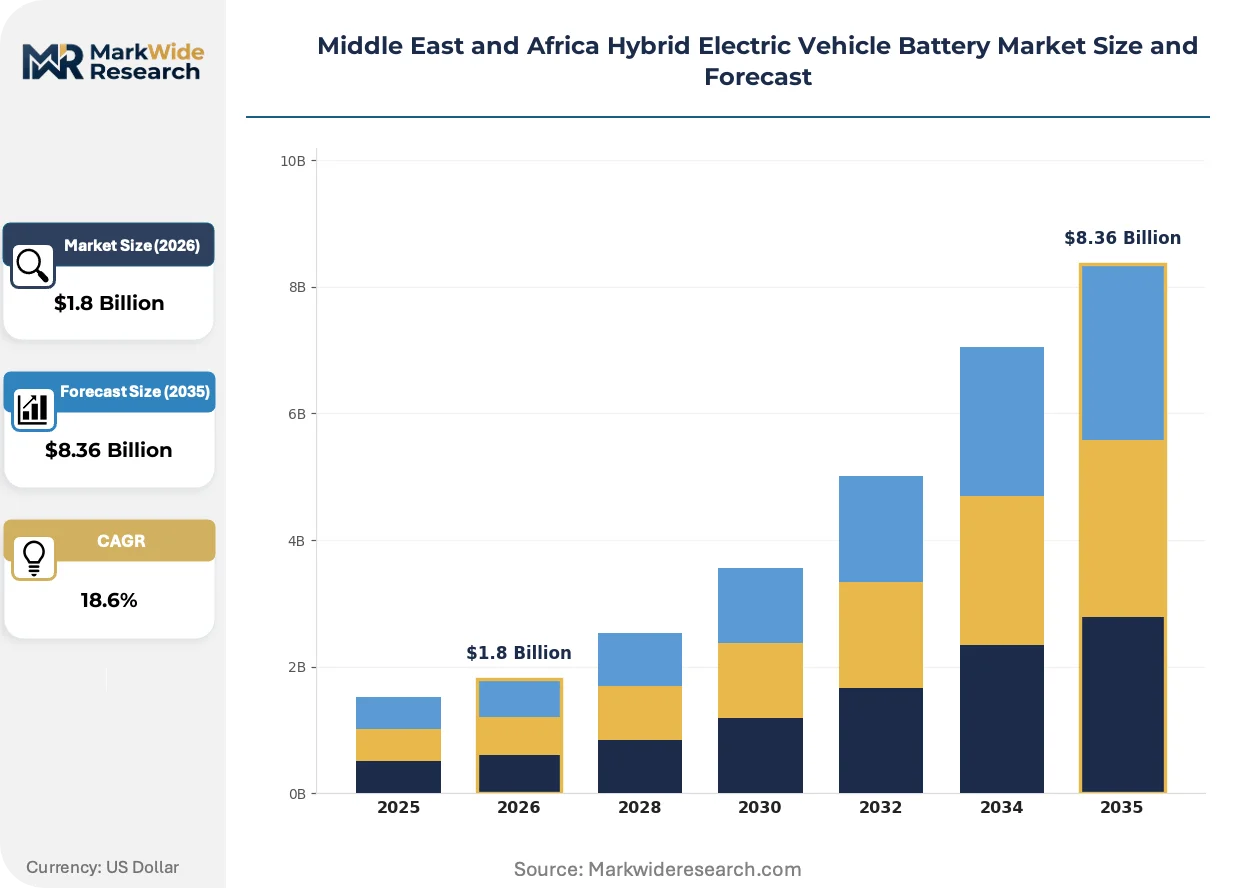
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Li-ion, NiMH, Lead Acid, Others Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Buses End User: OEMs, Fleet Operators, Retail Customers, Government Agencies Charging Infrastructure: Fast Charging, Standard Charging, Home Charging, Public Charging |
| Companies Covered | LG Energy Solution, Samsung SDI, Contemporary Amperex Technology, Panasonic Corporation, BYD Company Limited, Exide Industries Ltd., Amara Raja Batteries Ltd., Middle East Battery Company, East Penn Manufacturing Co. Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hybrid Electric Vehicle Battery Market Trends and Innovations
Active materials research and pack architecture redesigns are converging to address the unique thermal and duty-cycle demands of Middle Eastern and African operating environments.
Solid-state electrolyte development is hybridizing conventional lithium-ion manufacturing lines, with sulfide-based ceramic separators enabling higher nickel cathode loadings without compromising cycle stability. Saudi Arabian research institutes are piloting these formulations for next-generation bus powertrains. The technology is hybridizing regional supplier strategies by forcing parallel investment in both incumbent liquid electrolyte capacity and solid-state pilot lines.
UAE's MOHAP-backed green procurement standards now mandate lifecycle carbon disclosure for imported battery systems, creating compliance documentation requirements that favor suppliers with vertically controlled supply chains. European OEMs exporting into African markets are accelerating CE marking alignment to satisfy both EU origin requirements and Gulf standardization convergence. Commercial vehicle segments face the steepest compliance cost escalation as they source from multiple regulatory jurisdictions.
Fleet operators are consolidating procurement authority into centralized technical committees that specify cell chemistry, warranty terms, and second-life recovery obligations in single-tender packages. This pattern displaces fragmented purchasing by individual depot managers. Logistics operators in South Africa and the UAE are most advanced in this transition, using scale concentration to extract performance guarantees that smaller municipal fleets cannot replicate.
Middle East and Africa Hybrid Electric Vehicle Battery Market Segmentation
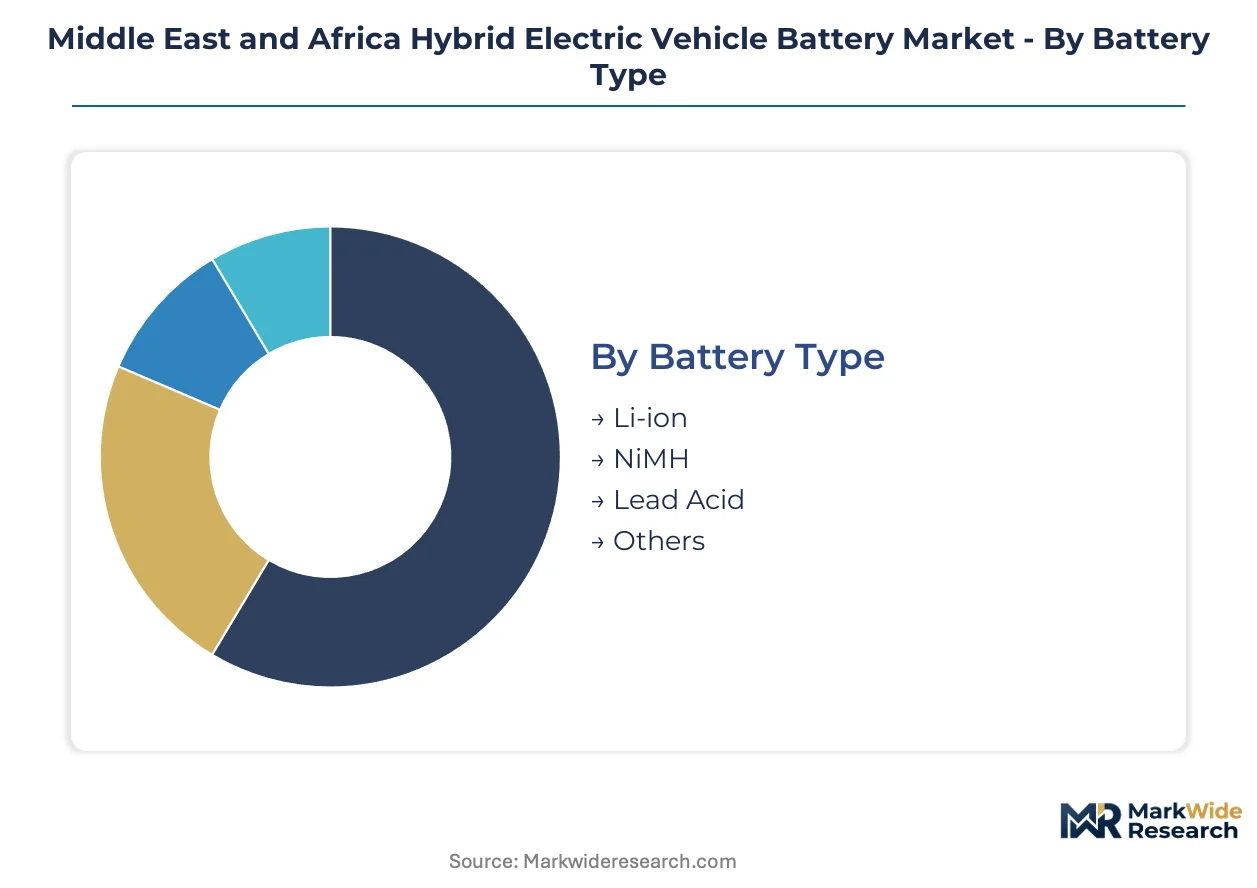
Segmentation in the Middle East and Africa hybrid electric vehicle battery market reveals divergent procurement patterns across climate-stressed operating environments and regulatory jurisdictions. Battery chemistry selection and application targeting determine supplier positioning in a region where municipal mandates and commercial fleet economics pull demand in distinct directions.
Battery Type:
Powertrain architects select cell chemistries based on thermal tolerance thresholds and duty-cycle intensity across Gulf and sub-Saharan operating conditions.
- Li-ion:Nickel-manganese-cobalt cathode formulations dominate premium passenger and commercial platforms, with 300-800 volt architectures enabling regenerative braking capture. Procurement concentrates in the UAE, where Dubai's RTA electrification mandates specify high-voltage hybrid powertrains for municipal bus networks.
- NiMH:Cost-sensitive fleet operators favor proven nickel-metal hydride systems for their established recycling infrastructure and lower thermal management complexity. South African logistics operators hedging against carbon taxation-driven fuel costs anchor regional demand for this chemistry in medium-duty commercial applications.
- Lead Acid:Absorbent glass mat variants serve auxiliary power functions and mild-hybrid starter-generator systems in price-constrained markets.
- Others:Sodium-ion pilot programs and solid-state electrolyte research initiatives are emerging in Saudi Arabian research institutes for next-generation bus powertrains.
Established volume favors NiMH; emerging adoption favors Li-ion.
Application:
Vehicle platform segmentation tracks fuel cost volatility exposure and regulatory compliance intensity across municipal, commercial, and consumer use cases.
- Commercial Vehicles:Logistics operators seeking diesel price hedging drive the steepest procurement velocity, with hybrid powertrains specified for long-haul routes across South Africa's carbon-tax-regulated corridors. Fleet-scale procurement enables performance guarantees and second-life recovery obligations that individual buyers cannot negotiate.
- Buses:Municipal electrification mandates in Dubai and Riyadh create guaranteed demand anchors for heavy-duty hybrid powertrains. Blade cell architectures from BYD dominate this segment due to simplified thermal management and cell-to-pack integration.
- Passenger Vehicles:European OEMs exporting into African markets supply premium hybrid platforms, with CE-marked battery systems satisfying both EU origin requirements and Gulf standardization convergence.
- Two-Wheelers:Last-mile delivery fleets in congested urban centers are piloting compact hybrid powertrains, though penetration remains constrained by upfront cost premiums versus conventional motorcycles.
Procurement scale concentrates in buses; margin expansion targets commercial vehicles.
End User:
Customer-type segmentation reflects consolidation of technical authority and warranty negotiation leverage across fragmented purchasing environments.
- Fleet Operators:Centralized technical committees in South Africa and the UAE now specify cell chemistry, warranty terms, and second-life recovery in single-tender packages. This pattern displaces fragmented depot-level purchasing and extracts performance guarantees from suppliers.
- OEMs:European manufacturers exporting into African markets anchor regional demand through EMA-aligned CE marking requirements, while BYD supplies commercial bus platforms directly.
- Government Agencies:Green procurement standards backed by UAE's MOHAP mandate lifecycle carbon disclosure for imported battery systems, favoring suppliers with vertically controlled supply chains.
- Retail Customers:Individual hybrid vehicle purchasers represent the smallest procurement volume, with battery replacement demand concentrated in premium passenger segments.
Contract structure complexity favors fleet operators; standardization pressure targets OEMs.
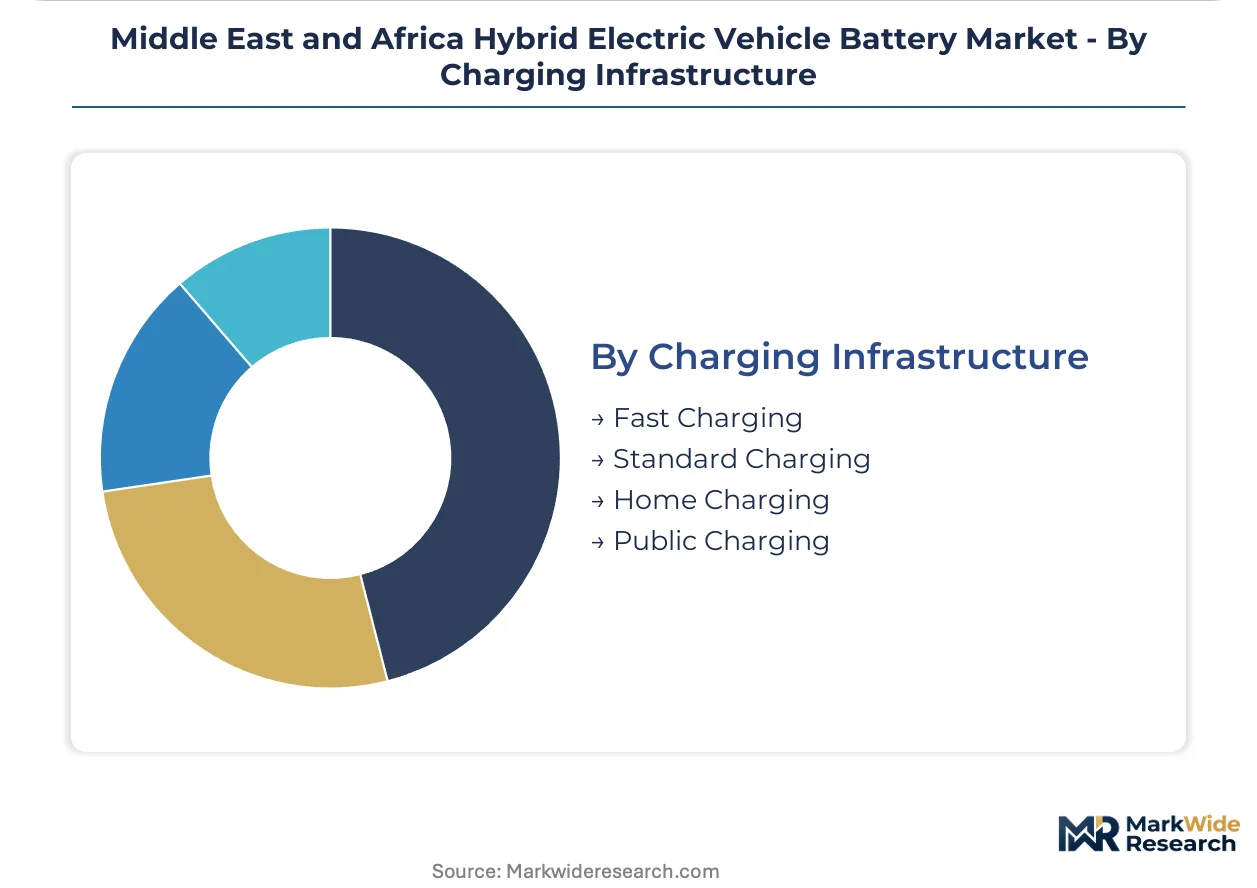
Charging Infrastructure:
Charging modality selection intersects with grid reliability constraints and renewable integration opportunities across the region's divergent electrical infrastructure.
- Public Charging:Solar-hybrid microgrid installations at Saudi Arabian logistics hubs enable off-grid fleet charging, reducing diesel generator dependency for commercial operators.
- Fast Charging:High-power DC infrastructure serves intercity commercial routes and municipal bus depots with scheduled downtime windows.
- Standard Charging:AC Level 2 systems dominate residential and workplace installations where dwell time accommodates slower replenishment.
- Home Charging:Limited grid access in peri-urban African markets constrains residential hybrid charging to affluent consumer segments with reliable electrical supply.
Grid independence favors public charging; cost minimization drives home charging adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell assembly capacity clusters along the Gulf's logistics corridors and South Africa's automotive belt, with regulatory divergence between carbon-tax regimes and municipal electrification mandates fragmenting procurement patterns.
United Arab Emirates
Dubai's RTA electrification mandates specify hybrid powertrains for municipal bus fleet additions, compressing procurement cycles for heavy-duty battery systems. MOHAP-backed green procurement standards now mandate lifecycle carbon disclosure for imported battery systems. Industrial activity concentrates in Dubai's Jebel Ali corridor, where logistics operators pilot solar-hybrid microgrid charging infrastructure.
Saudi Arabia
SASO thermal runaway testing protocols for desert climate operation are stretching product certification cycles for cell suppliers. The SFDA and SASO technical regulations are converging on extreme temperature cycling requirements. Riyadh's King Abdullah Financial District anchors demand from corporate fleet operators consolidating procurement authority.
South Africa
Carbon taxation mechanisms penalize diesel-intensive logistics fleets, recalibrating total cost of ownership calculations for hybrid powertrain adoption. The national treasury's carbon tax regime tightens annually, accelerating commercial vehicle electrification. The Eastern Cape automotive belt hosts nascent cell assembly corridor competition between Coega and East London industrial zones.
Morocco
Casablanca-Tangier industrial corridor positioning leverages EU trade alignment for CE-marked battery assembly re-export into European aftermarket channels. EMA-aligned technical standards govern imported systems from European suppliers. Tangier Med port infrastructure supports cross-border battery shipments with streamlined customs processing.
Israel
Research institutes pilot solid-state electrolyte formulations for next-generation bus powertrains, hybridizing conventional lithium-ion manufacturing investments. National innovation authority grants support electrochemical engineering talent development. Tel Aviv metropolitan fleet operators consolidate technical procurement committees to negotiate performance guarantees.
Middle East and Africa Hybrid Electric Vehicle Battery Market Competitive Landscape
Korean and Chinese battery specialists split the market against European OEM-anchored suppliers, with tiered competition emerging between premium cylindrical cell providers and cost-optimized prismatic pack assemblers. The vendor base organizes around three strategic archetypes: vertically integrated cell-to-pack specialists, modular system integrators serving European export channels, and regional assemblers leveraging trade alignment for re-export positioning. Capacity expansion and strategic partnerships dominate competitive moves, with certification-service alliances and desert-climate validation partnerships gaining traction.
Within the premium cylindrical tier, LG Energy Solution and Samsung SDI anchor Korean supply positioning, while BYD Company Limited exemplifies the integrated cell-to-pack model for commercial bus platforms. These three represent divergent geographic origins—Korean chaebol-backed battery divisions versus Chinese vertically integrated automotive-battery conglomerates—each occupying distinct archetype positions without overlapping segment targeting.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| Contemporary Amperex Technology |
| Panasonic Corporation |
| BYD Company Limited |
| Exide Industries Ltd. |
| Amara Raja Batteries Ltd. |
| Middle East Battery Company |
| East Penn Manufacturing Co. Inc. |
| Others |
Pricing and Supply Chain Analysis
Spodumene concentrate flows from Australian hard-rock mines and Chilean brine evaporation ponds anchor cell manufacturer cost structures, with lithium carbonate spot volatility transmitting directly into pack-level margin pools across Gulf and sub-Saharan assembly operations.
Pricing Analysis
SASO thermal runaway testing protocols dictate the pricing tier structure across the Middle East and Africa hybrid electric vehicle battery market. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European systems from Gulf-standardized regional packs and uncertified aftermarket imports. Cost compression in the standard tier is intensifying because lithium carbonate spot fluctuations are destabilizing long-term offtake agreements. Fleet operators in South Africa's carbon-tax-regulated corridors exhibit the highest price sensitivity, while Dubai's RTA municipal procurement committees prioritize performance guarantees over unit cost.
Supply Chain Analysis
Export-control regimes limiting cathode precursor technology transfers from South Korean and Japanese suppliers are fragmenting regional cell sourcing strategies. Manufacturing gravity centers on China for lithium iron phosphate cathodes, South Korea for nickel-manganese-cobalt formulations, and Japan for solid-state electrolyte pilot lines. The supply chain draws from spodumene concentrate, cathode precursor chemicals, and separator membranes as critical inputs. Single-source vulnerability concentrates in Chinese lithium refining capacity. Distribution runs through Jebel Ali logistics corridors for Gulf markets and Tangier Med port infrastructure for European re-export channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical engineering talent scarcity constrains regional manufacturing scale-up, with specialized cell chemistry expertise concentrated in East Asian battery clusters and desert-climate validation capabilities limited to a handful of certification laboratories.
For Market Incumbents: Pre-empt second-life battery competition from European and East Asian repurposed pack imports by establishing certified refurbishment corridors in Morocco's Casablanca-Tangier industrial zone. Secure backward integration into lithium carbonate offtake agreements with Australian spodumene producers before spot volatility compresses margins further. Anchor defensive positioning through SASO thermal runaway certification partnerships that extend product validation timelines for challengers. For New Entrants and Emerging Players: Build out solar-hybrid microgrid charging infrastructure at Saudi Arabian logistics hubs as a differentiated entry vector, targeting commercial fleet operators seeking diesel generator independence. Focus initial penetration on South Africa's carbon-tax-regulated logistics corridors where fuel hedging economics accelerate procurement cycles. Deploy outcome-based performance contracting that transfers thermal management risk from fleet operators to battery suppliers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional assemblers in Morocco's EU trade alignment corridor that have secured CE marking pathways but lack cell chemistry R&D depth. Long-term viability hinges on differentiation through desert-climate validation capabilities rather than commodity pack assembly. Watch for inflection signals in Saudi Arabian solid-state electrolyte pilot program announcements that would obsolete incumbent liquid electrolyte capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Desert-Climate Validation Partnership | SASO thermal runaway certification accelerates product approval timelines for Gulf Cooperation Council markets. |
| Backward Integration into Lithium Carbonate | Australian spodumene offtake agreements hedge against spot market volatility compressing cell manufacturer margins. |
| CE Marking Alignment Investment | EMA-aligned technical standards enable Moroccan re-export positioning into European aftermarket channels. |
| Solar-Hybrid Microgrid Deployment | Off-grid charging infrastructure at Saudi logistics hubs reduces diesel generator dependency for commercial fleets. |
| Second-Life Recovery Obligation Structuring | Centralized fleet procurement committees now mandate battery end-of-life recovery in single-tender packages. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, SASO technical regulation filings, and IEA energy transition reports. Primary interviews engaged cell manufacturer procurement directors, fleet operator technical committees, and certification laboratory program managers. Secondary validation drew from EMA CE marking registries, Dubai RTA electrification mandate documentation, and South African National Treasury carbon tax policy circulars. Bottom-up demand modeling triangulated against top-down market sizing across battery chemistry and application dimensions.
Forecast inputs span vehicle platform electrification mandates, carbon taxation trajectory scenarios, and lithium carbonate price band assumptions across the projection horizon. Segmentation dimensions modeled include battery chemistry type, vehicle application class, end-user procurement structure, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement velocity indicators and policy implementation timelines. Desert-climate degradation curves and second-life battery competition intensity served as industry-specific forecast modifiers.
Stress conditions across lithium carbonate spot price volatility, SASO certification timeline extensions, and European second-life battery import volumes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding policy implementation pacing and technology cost reduction curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market