
 Electric Vehicle on Board Charger Market | 2026-2036
Electric Vehicle on Board Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle on Board Charger Market Analysis
Modular charger packaging is hardening as the dominant product-configuration pattern, with automakers bundling power electronics into integrated drivetrain modules rather than standalone units. BorgWarner leverages its powertrain integration expertise to anchor high-volume contracts with legacy OEMs transitioning to electric platforms. Infineon Technologies differentiates through silicon carbide semiconductor leadership, sustaining margin pools in premium efficiency tiers. Valeo competes on thermal management co-design, extending its climate-system footprint into charger cooling architectures.
An electric vehicle on-board charger converts alternating current from the grid into direct current for battery storage, typically operating at power levels from 3.3 kW to 22 kW with efficiency targets exceeding 94 percent. Level 2 Charger configurations occupy the largest installed base among passenger cars, while DC Fast Charger integration into commercial vehicles generates the fastest growth trajectory as fleet operators demand shortened depot dwell times. Wireless Charger installations remain nascent but concentrate margin pools in luxury passenger car segments where consumer willingness to pay for convenience peaks.
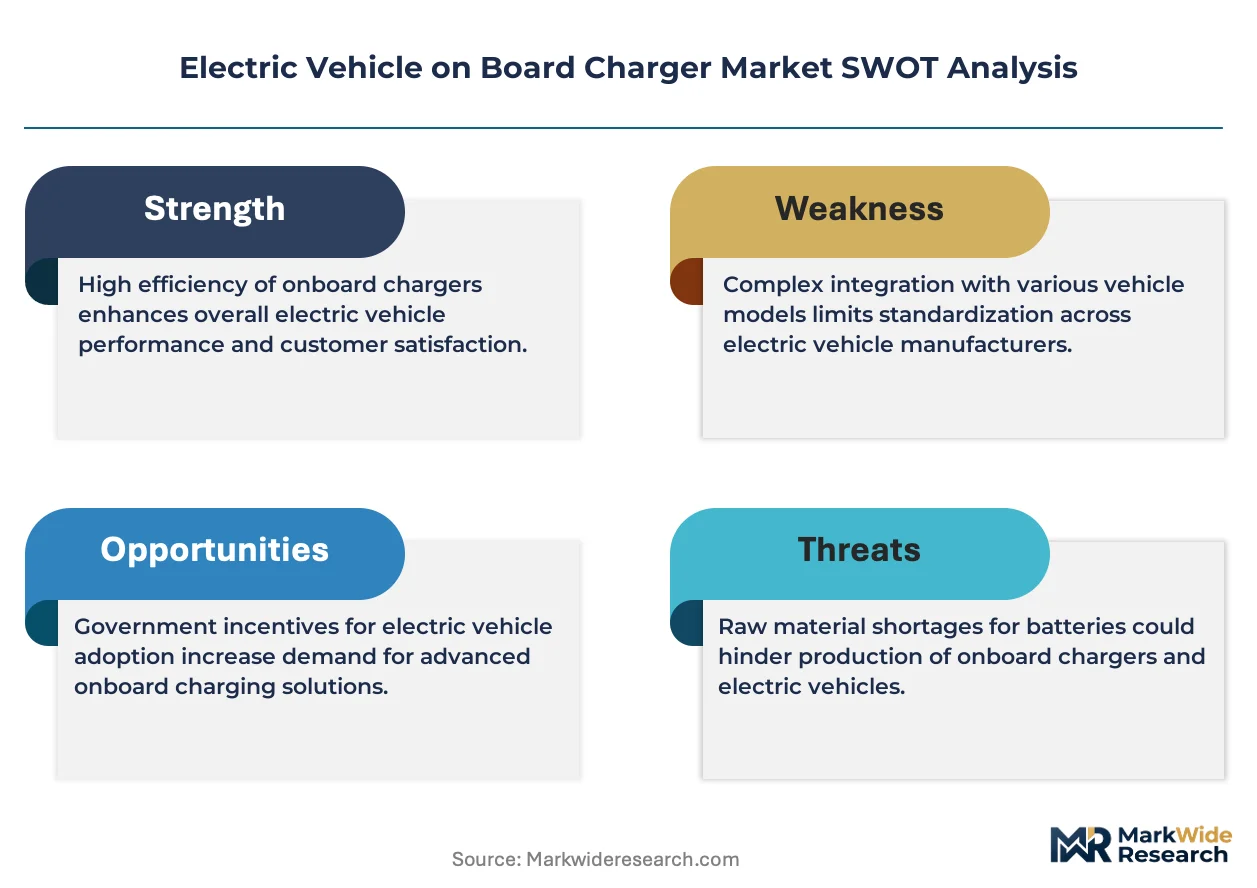
NHTSA and EPA rules in the United States tighten electromagnetic compatibility and efficiency minimums, while EU Green Deal frameworks and CE marking requirements shape product access across European markets. China's GB standards and MIIT technical directives enforce domestic content ratios that redirect supply chain localization decisions. Stakeholders must monitor how semiconductor export controls and evolving efficiency benchmarks reshape component sourcing strategies without assuming regulatory stability across any single jurisdiction.
Market Dynamics
Silicon carbide semiconductor adoption is compressing thermal management requirements while elevating efficiency benchmarks across passenger and commercial vehicle platforms.
Growth Catalysts
- Fleet electrification mandates:California's Advanced Clean Trucks regulation and EU Green Deal emissions targets compel logistics operators to replace diesel depots with electrified infrastructure.
- GB standard localization:China's MIIT technical directives enforce domestic content ratios that accelerate local supply chain maturation around Shanghai and Shenzhen manufacturing corridors.
- Bidirectional charging integration:Vehicle-to-grid capability is hardening as a procurement requirement for utility fleet contracts and residential energy arbitrage applications.
Market Restraints
- Silicon carbide substrate scarcity:Wafer supply concentrates among limited semiconductor foundries, creating input cost volatility for power module manufacturers.
- Electromagnetic compatibility certification:NHTSA and FCC testing timelines extend product validation cycles, compressing margin recovery windows for new entrants.
- Copper winding cost exposure:Magnet wire pricing fluctuates with commodity markets, pressuring cost structures in high-power charger architectures.
Strategic Opportunities
- Wireless charging luxury penetration:Inductive pad systems command premium positioning in German and Japanese passenger car segments where convenience willingness-to-pay peaks.
- Commercial vehicle DC fast integration:Depot dwell time reduction is driving 22 kW and above power level adoption among North American and European fleet operators.
- Thermal management co-design:Climate system integration with power electronics cooling creates white space for tier-one suppliers extending into charger architectures.
Industry Challenges
- Power electronics talent scarcity:SiC device characterization and gate driver design expertise concentrates among experienced semiconductor engineers, constraining hiring pipelines.
- Multi-jurisdiction certification parallelism:Simultaneous NHTSA, CE marking, and GB standard compliance requires redundant testing protocols, extending time-to-revenue.
- Legacy vehicle integration complexity:Retrofit charger compatibility with existing battery management systems demands custom firmware adaptation, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle on Board Charger Market |
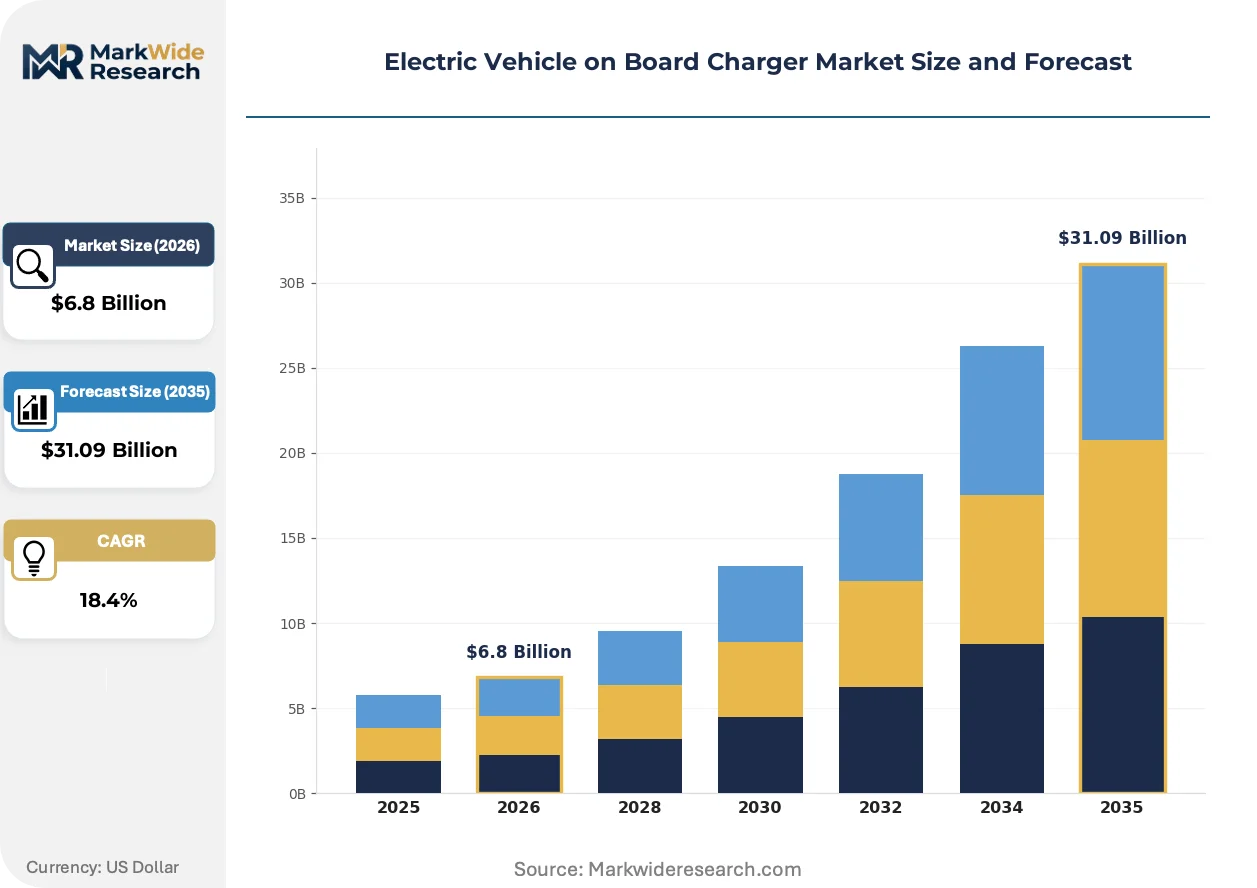
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level 1 Charger, Level 2 Charger, DC Fast Charger, Wireless Charger Installation Type: Wall-Mounted, Portable, Embedded, Commercial Vehicle Type: Passenger Cars, Commercial Vehicles, Buses, Two-Wheelers End User: Individual Consumers, Fleet Operators, Ride-Sharing Services, Government Entities |
| Companies Covered | BorgWarner, Delta Electronics, Infineon Technologies, Eaton, BRUSA Elektronik, Toyota Industries, Bel Fuse, Valeo, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle on Board Charger Market Emerging Trajectories
Power semiconductor material transitions and thermal architecture convergence are redefining competitive differentiation. Procurement patterns now prioritize efficiency tier certification over standalone unit cost.
Silicon carbide MOSFETs are replacing silicon IGBTs in high-frequency switching applications, delivering superior thermal performance and reduced cooling system mass. Premium passenger car and commercial vehicle platforms are adopting these devices at accelerated procurement cadences. The technology is modularizing into standardized power stages that compress development timelines for multi-platform vehicle programs.
EU Green Deal frameworks and CE marking requirements are tightening electromagnetic compatibility and efficiency minimums for market access. These rules are forcing hardware redesigns that prioritize conducted emissions suppression and power factor correction. Commercial vehicle segments face the steepest compliance burden, with fleet operators demanding pre-certified charger modules to avoid depot deployment delays.
Service-unbundled procurement is displacing bundled drivetrain supply contracts among legacy OEMs transitioning to electric platforms. Tier-one power electronics specialists are capturing direct relationships previously intermediated by integrated drivetrain suppliers. This pattern is most visible in North American and European passenger car programs where platform electrification timelines compress supplier selection windows.
Electric Vehicle on Board Charger Market Segmentation
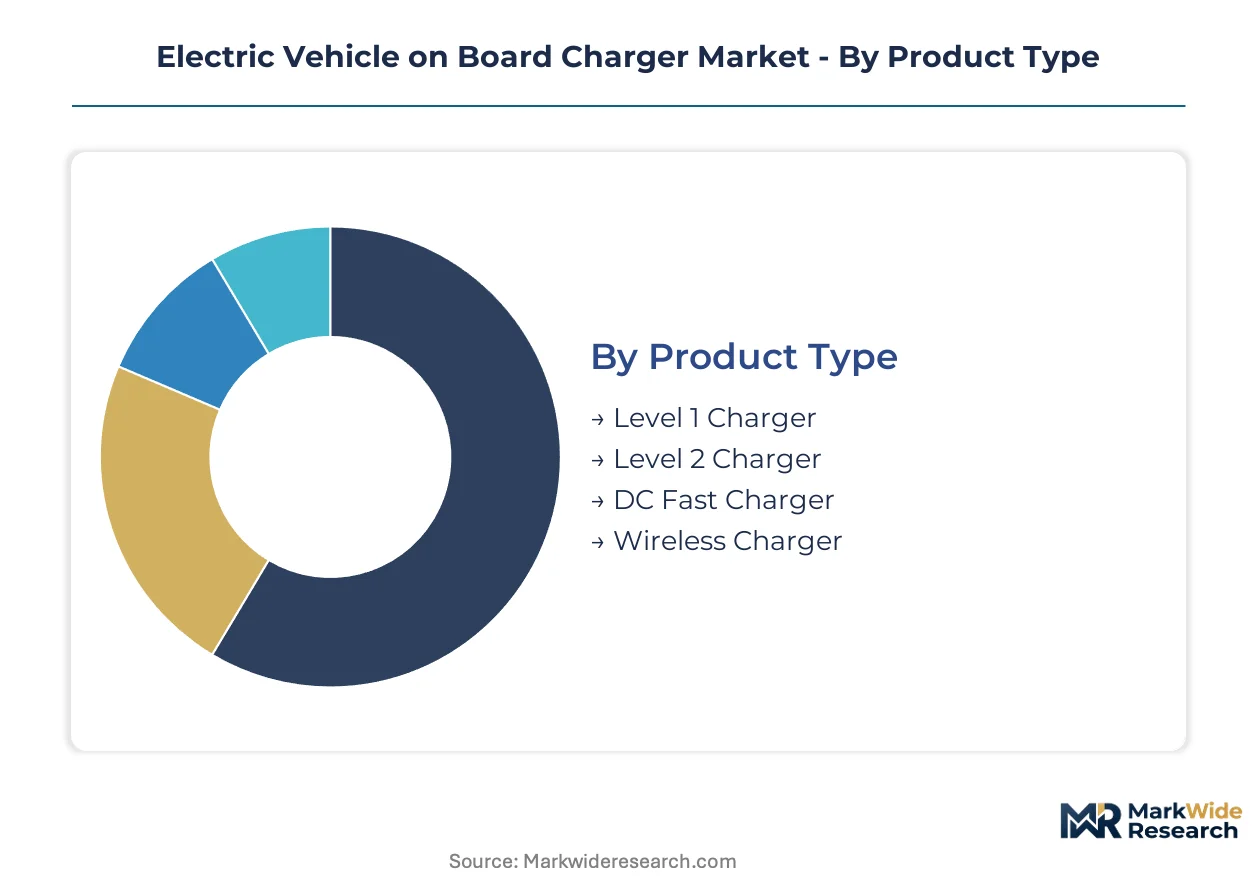
Segmentation in the Electric Vehicle on Board Charger Market reveals how procurement patterns diverge across power levels, installation contexts, and fleet-scale deployment models. Understanding these splits exposes where margin pools concentrate and which technical specifications dominate contract negotiations.
Product Type:
Fleet procurement teams prioritize charging speed against depot dwell time constraints when selecting power electronics tiers.
- Level 2 Charger:These units operate between 3.3 kW and 19.2 kW, serving as the default specification for residential and workplace installations across North American and European passenger car fleets. Demand concentrates among individual consumers in suburban United States markets where overnight charging meets daily commute requirements without infrastructure upgrades.
- DC Fast Charger:High-power architectures exceeding 22 kW enable sub-one-hour charging cycles for commercial vehicle depots. Logistics operators in California and Germany specify these units under fleet electrification mandates that penalize vehicle downtime.
- Level 1 Charger:Basic 1.4 kW units plug into standard household outlets, appealing to cost-sensitive two-wheeler owners in India and Southeast Asian urban markets.
- Wireless Charger:Inductive pad systems eliminate connector wear, commanding premium positioning in German and Japanese luxury passenger segments where convenience willingness-to-pay peaks.
Volume sits with Level 2 Charger configurations; growth tilts toward DC Fast Charger integration.
Installation Type:
Physical mounting decisions reflect property ownership patterns and grid access constraints across deployment contexts.
- Embedded:Factory-integrated units within vehicle drivetrain modules dominate new electric platform procurement from legacy OEMs transitioning production lines. Automakers in China and Germany favor this approach for warranty consolidation and thermal management co-design.
- Commercial:Standalone high-power installations serve fleet depots and public charging plazas with dedicated electrical infrastructure. North American logistics operators specify these under California's Advanced Clean Trucks regulation and EPA emissions targets.
- Wall-Mounted:Fixed residential units attach to garage infrastructure, prevalent among single-family homeowners in United States suburbs.
- Portable:Detachable units travel with vehicle owners, addressing apartment dweller needs in dense European and Asian urban cores without dedicated parking.
Embedded configurations capture the largest manufacturing volumes; commercial installations are climbing the fastest as fleet operators scale electrified logistics.
Vehicle Type:
Power electronics specifications scale with battery capacity and duty cycle intensity across mobility applications.
- Passenger Cars:Sedans and SUVs dominate installed base volumes, with 7-11 kW onboard chargers standardizing across mid-range battery electric platforms from manufacturers in China, Germany, and the United States.
- Commercial Vehicles:Delivery vans and light trucks require 22 kW and above power levels to compress depot dwell times. European Union Green Deal emissions rules and urban low-emission zones in London and Paris accelerate procurement.
- Buses:Municipal transit operators in Shenzhen and Los Angeles specify high-power overnight charging systems with bidirectional capability for grid stabilization.
- Two-Wheelers:Scooters and motorcycles utilize compact 1-3 kW units, with removable battery designs prevalent in Indian and Vietnamese markets.
Passenger cars anchor current production volumes; commercial vehicles show the steepest expansion trajectory as logistics electrification mandates tighten.
End User:
Contract scale and standardization requirements separate consumer procurement from institutional purchasing patterns.
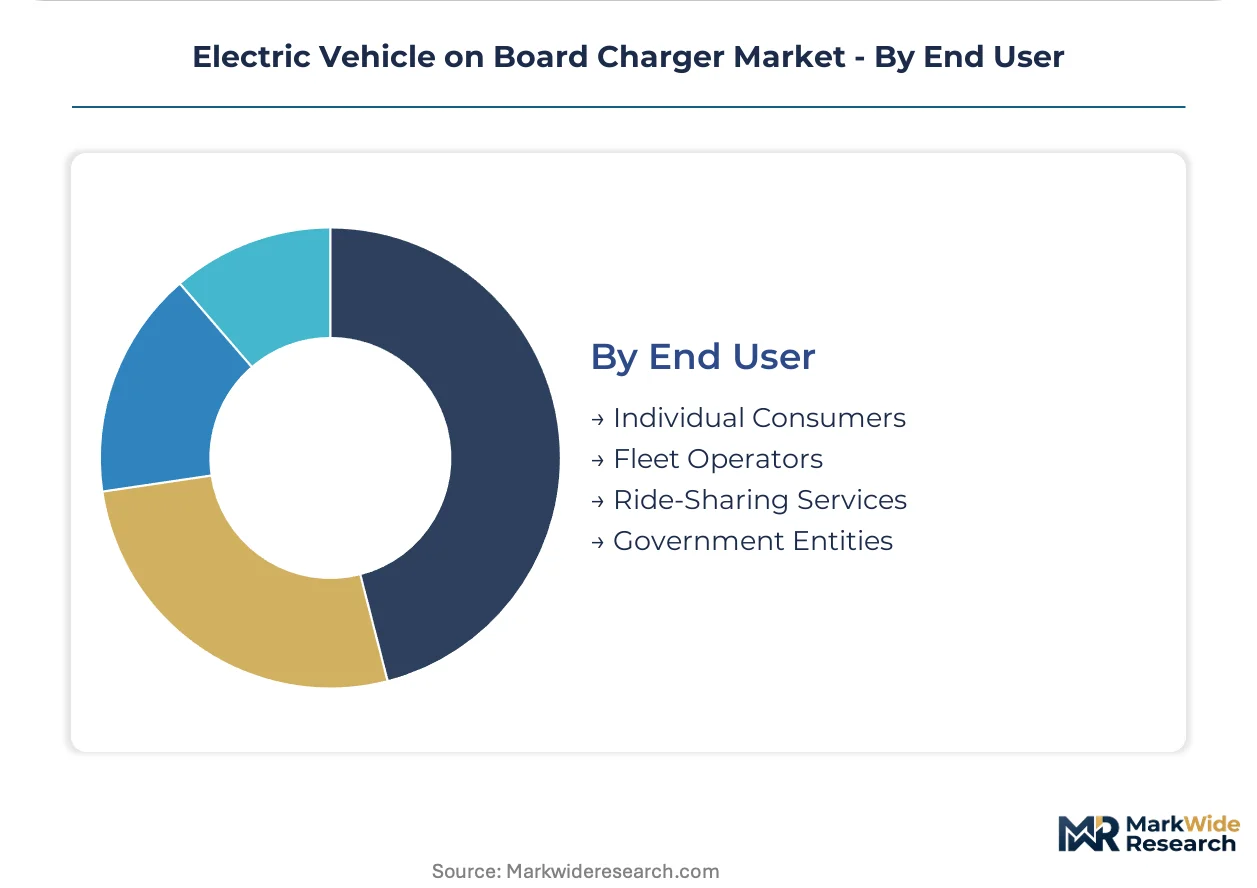
- Fleet Operators:Logistics companies negotiate multi-thousand-unit contracts with standardized specifications, pre-certified for NHTSA electromagnetic compatibility and EU CE marking to avoid deployment delays. Amazon, DHL, and regional postal services in Germany and the United States drive this segment.
- Individual Consumers:Retail purchasers prioritize purchase price and installation simplicity over efficiency tier certification, typically selecting through dealer channels or aftermarket retailers.
- Ride-Sharing Services:Uber and Lyft driver-owners in United States metropolitan areas and Didi operators in China demand rapid charging capability to maximize vehicle utilization hours.
- Government Entities:Municipal procurement favors domestic content compliance, with China's MIIT technical directives and India's PLI scheme influencing supplier selection for public fleet conversions.
Fleet operators command the largest contract values; ride-sharing services are gaining share fastest as platform driver counts expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of onboard charger power electronics while the United States and Germany absorb premium-tier volumes through fleet electrification mandates. This production-consumption divide shapes supply chain localization decisions and regulatory compliance investments across major automotive corridors.
United States
California's Advanced Clean Trucks regulation and EPA emissions targets compel logistics operators to electrify depot infrastructure. NHTSA electromagnetic compatibility testing extends product validation timelines for suppliers seeking federal highway safety certification. Detroit and Austin manufacturing clusters host assembly operations for integrated drivetrain modules serving domestic OEM electrification programs.
Germany
Luxury passenger car manufacturers specify high-efficiency silicon carbide architectures for premium battery electric platforms. EU Green Deal frameworks and CE marking requirements enforce stringent electromagnetic compatibility minimums for market access. Stuttgart and Munich engineering centers concentrate power electronics R&D talent alongside thermal management co-design capabilities.
China
Domestic EV manufacturing corridors around Shanghai and Shenzhen generate concentrated demand for localized power module production. MIIT technical directives and GB standards enforce domestic content ratios that redirect foreign supplier investment toward joint ventures. BYD and CATL supply chain integration creates captive demand for high-volume charger component fabrication.
Japan
Automotive semiconductor specialists anchor silicon carbide device characterization expertise for next-generation switching applications. METI industrial policy supports domestic foundry capacity expansion to reduce wafer import dependency. Nagoya and Tokyo metropolitan areas concentrate power electronics engineering talent within tier-one supplier headquarters.
South Korea
Battery electric platform launches from Hyundai and Kia drive procurement of compact onboard charger architectures. National emissions reduction commitments accelerate public fleet conversion timelines for municipal bus operators. Seoul metropolitan manufacturing clusters integrate power electronics assembly with adjacent battery pack production facilities.
Electric Vehicle on Board Charger Market Vendor Landscape
The competitive structure tilts toward integrated powertrain specialists and semiconductor component suppliers rather than standalone charger fabricators. Tier-one automotive suppliers with existing OEM relationships capture embedded configuration contracts through warranty consolidation and thermal co-design capabilities. Two strategic archetypes dominate: power electronics integration houses leveraging drivetrain expertise, and semiconductor specialists commanding premium efficiency tiers through silicon carbide leadership. Capacity expansion and strategic partnerships constitute the primary competitive moves, with foundry relationships and thermal management alliances displacing pure product differentiation.
Among diversified industrial conglomerates with automotive electronics divisions, Eaton and Delta Electronics occupy positions spanning power conversion and thermal infrastructure. BorgWarner and Valeo exemplify the integration-house archetype, anchoring high-volume relationships through powertrain module bundling. Infineon Technologies and STMicroelectronics represent the semiconductor-tier vector, supplying switching devices across multiple charger fabricator customer bases without direct vehicle-level integration exposure.
| Leading Market Players |
|---|
| BorgWarner |
| Delta Electronics |
| Infineon Technologies |
| Eaton |
| BRUSA Elektronik |
| Toyota Industries |
| Bel Fuse |
| Valeo |
| STMicroelectronics |
| Others |
Supply Flow & Price Mechanics
Silicon carbide efficiency certification tiers split procurement contracts between premium automotive platforms and cost-optimized fleet specifications, with NHTSA electromagnetic compatibility testing and EU CE marking requirements forcing divergent supply chain localization investments across United States, German, and Chinese manufacturing corridors.
Pricing Analysis
Margin tightening in standard-efficiency silicon IGBT tiers reflects commodity magnet wire cost exposure and copper winding price volatility, while silicon carbide premium architectures command value-based pricing anchored to 94 percent-plus efficiency benchmarks. Three-tier pricing structure across premium SiC-certified, standard silicon-based, and economy Level 1 configurations segments buyer willingness-to-pay, with fleet operators exhibiting lowest price sensitivity due to total cost of ownership framing and individual consumers in Southeast Asian markets driving hardest unit-cost negotiations.
Supply Chain Analysis
GB standard qualification and NHTSA electromagnetic compatibility certification gate access to Chinese, United States, and European vehicle programs, forcing redundant testing protocol investments. Wafer fabrication concentrates in Japan and South Korea, with power module assembly tethered to Shanghai and Shenzhen EV manufacturing corridors. Silicon carbide substrate scarcity and single-source foundry dependency present structural supply risk. Distribution runs through tier-one drivetrain integrators rather than standalone charger fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide wafer capacity constraints prop pricing power for qualified suppliers, with semiconductor foundry bottlenecks extending lead times across premium efficiency tiers.
For Market Incumbents: To counter silicon carbide substrate scarcity and foundry allocation rationing, secure long-term wafer supply agreements with Japanese and South Korean semiconductor specialists while deepening backward integration into power module packaging capabilities in China and Germany. For New Entrants and Emerging Players: Fleet operator procurement channels offer the most penetrable entry vector, targeting California and Germany logistics depots with pre-certified 22 kW DC fast charger modules that compress NHTSA and CE marking validation timelines through third-party test house partnerships. For Investors and Strategic Acquirers: Re-rating potential sits with silicon carbide gate driver design specialists given automotive platform electrification timelines accelerating procurement cadences. Long-term viability over a multi-year window favors acquisition targets with captive thermal management co-design capabilities. The signal to watch is tier-one OEM unbundling of drivetrain supply contracts from integrated powertrain specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Foundry Partnership | Wafer supply agreements with Japanese and South Korean semiconductor fabricators secure premium-tier allocation priority. |
| Thermal Management Co-Design Investment | Climate system integration capabilities extend Valeo and BorgWarner relationships into charger cooling architectures. |
| Multi-Jurisdiction Certification Parallelism | Simultaneous NHTSA, CE marking, and GB standard compliance compresses time-to-revenue for fleet contracts. |
| Wireless Charging Luxury Penetration | Inductive pad systems capture German and Japanese passenger car segments where convenience willingness-to-pay peaks. |
| Bidirectional Charging Capability Integration | Vehicle-to-grid functionality hardens as utility fleet procurement requirement across North American and European markets. |
Methodological Framework
Multi-period observation of silicon carbide device adoption rates, fleet electrification mandate implementation timelines, and OEM platform electrification announcements anchored the trend analysis, supplemented by interviews with tier-one supplier procurement directors, OEM platform engineers, semiconductor foundry planning officers, and thermal management system architects. Secondary validation drew from NHTSA electromagnetic compatibility filings, EU CE marking registries, MIIT GB standard compliance databases, and vehicle production registration data. Bottom-up segment sizing and top-down market triangulation cross-checked volume and value outputs.
An input-output matrix framework modeled power electronics procurement across vehicle class, propulsion architecture, charger power level tier, and regional production cluster dimensions over the projection horizon. CAGRs were derived from segment-level growth trajectory blending. Industry-specific forecast inputs included silicon carbide wafer capacity expansion announcements and fleet operator depot electrification capex disclosures.
Caveats apply where semiconductor export control expansion, GB standard domestic content ratio adjustments, or NHTSA efficiency benchmark revisions could materially shift the outlook. Forecasts reflect documented assumptions regarding foundry capacity commissioning schedules and fleet mandate enforcement intensity. A model refresh is warranted upon material change in silicon carbide substrate supply availability or tier-one OEM supply contract unbundling velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Automotive High-Performance Electric Vehicles Market
Electric Vehicles
Peer-To-Peer Electric Vehicle Charging Market
Electric Vehicles
Electric Tricycle Market
Electric Vehicles
Automotive Battery Pack Pressure Equalization Membrane Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Europe Fuel Cell Electric Vehicle Market
Electric Vehicles
Germany Solar E-Bike Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
BEV On-Board Charger Market
Electric Vehicles
Electric Vehicle Speed Reducer Market
Electric Vehicles
Netherlands Solar E-Bike Market
Electric Vehicles
Electric Vehicle Transmission Market
Electric Vehicles
India Electric Bus Market
Electric Vehicles
China Electric Vehicle Market
Electric Vehicles
Electric Tuk-Tuks Market