
 Oman PVC Products Market | 2026-2036
Oman PVC Products Market Size, Share, and Industry Trends Forecast 2026-2036
Oman PVC Products Market Intelligence
Buyer concentration among large construction contractors in Oman is expanding as government infrastructure awards consolidate under fewer master developers. Composite Pipe Industry leverages backward integration into resin compounding to secure feedstock margins. United Gulf Pipe Manufacturing sustains geographic dominance through its Sohar Industrial Port manufacturing base. Muna Noor differentiates via specialized pressure-rated piping systems for desalination utilities.
Polyvinyl chloride products encompass thermoplastic polymer formulations containing 57 percent chlorine by mass, produced through suspension polymerization of vinyl chloride monomer, and serve primarily as corrosion-resistant conduits and structural components across fluid handling and building envelope applications. Pipes and fittings occupy the largest volume share due to municipal water distribution renewal cycles, while films represent the fastest-expanding category as food packaging converters substitute PVC for higher-cost barrier polymers. Construction anchors the dominant application segment driven by Oman Vision 2040 infrastructure commitments, whereas electrical applications concentrate margin pools through halogen-free compound premiums.
Oman's Ministry of Commerce, Industry and Investment Promotion enforces building material conformity assessments under updated technical regulations aligned with Gulf Standardization Organization benchmarks. The Public Authority for Water mandates potable piping compliance with stringent leachate standards that favor certified domestic producers over uncertified imports. Stakeholders must monitor regulatory harmonization negotiations between GCC member states and the proposed EU-GCC free trade framework to anticipate tariff and standard convergence impacts on sourcing strategies.
Market Dynamics
Consolidation among Omani construction contractors is concentrating procurement power, forcing PVC manufacturers to restructure pricing and service models around fewer, larger master developers.
Growth Catalysts
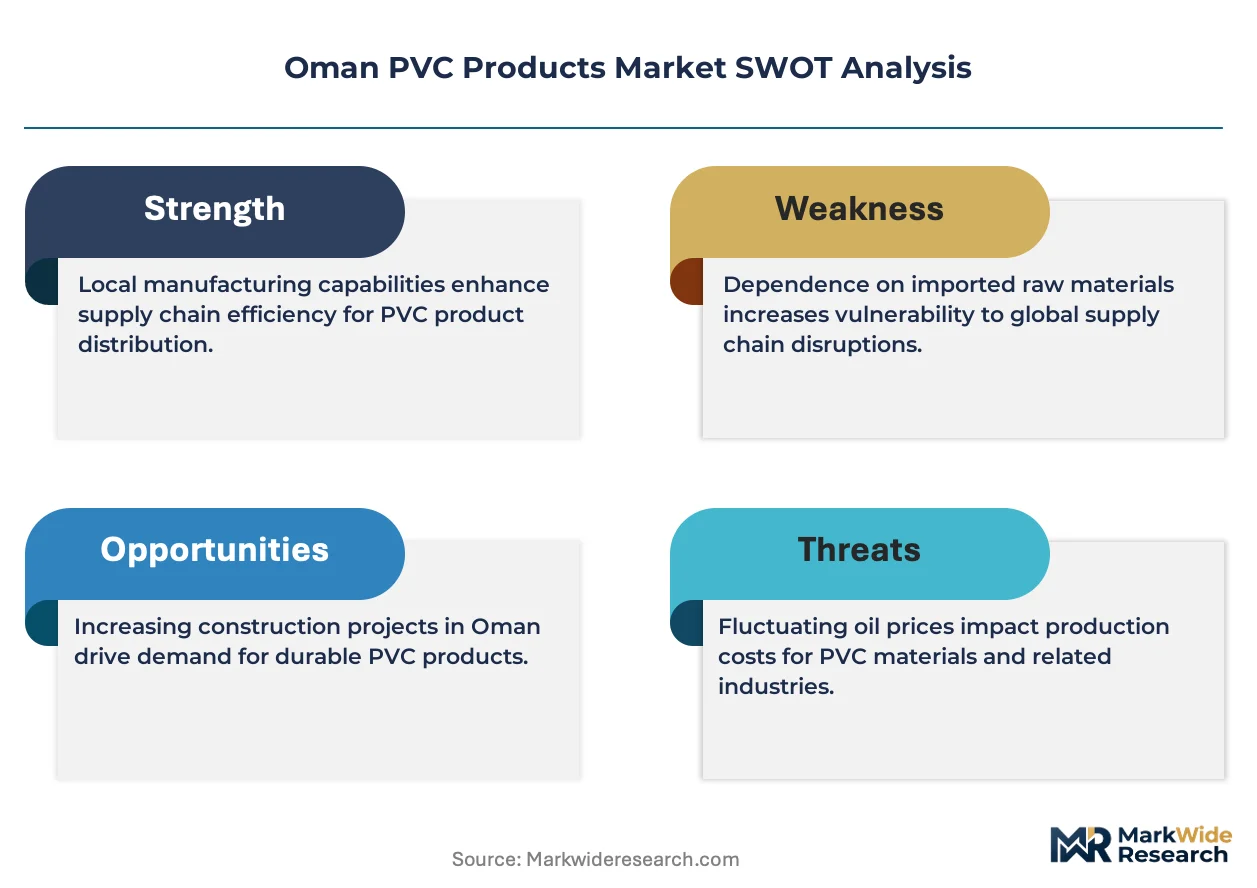
- Oman Vision 2040 infrastructure commitments:Government capital allocation to water distribution networks and desalination plants sustains demand for pressure-rated piping systems across the Batinah coastal corridor.
- Gulf Standardization Organization benchmarks:Harmonized technical regulations reduce certification friction for domestic producers supplying cross-border projects in neighboring GCC states.
- Chlor-alkali feedstock integration:Local petrochemical complexes are securing captive vinyl chloride monomer supply, insulating compounders from import volatility.
Market Restraints
- Ethylene cost volatility:Crude-linked naphtha pricing transmits directly to PVC resin economics, compressing margins during upstream energy spikes.
- Import dependency for specialty additives:Stabilizer and impact modifier supply concentrates among Asian chemical producers, exposing compounders to freight rate swings.
- REACH-aligned substance restrictions:Anticipated GCC adoption of European phthalate limitations threatens legacy plasticizer formulations in flexible film applications.
Strategic Opportunities
- Dhofar region underpenetration:Salalah's emerging industrial zone lacks localized PVC extrusion capacity, creating logistics arbitrage for southern distribution networks.
- Food packaging substitution:Barrier film converters are displacing higher-cost polymers with PVC in modified atmosphere packaging for processed meat exports.
- Halogen-free compound premiums:Electrical conduit specifications for mega-project data centers reward low-smoke formulations with certified performance testing.
Industry Challenges
- Pressure-rating certification timelines:Public Authority for Water approval cycles for potable piping extend 8-14 months, delaying project revenue recognition.
- Legacy extrusion equipment retrofit costs:Converting lines to multi-layer co-extrusion for barrier films demands capital outlays that strain mid-tier processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman PVC Products Market |
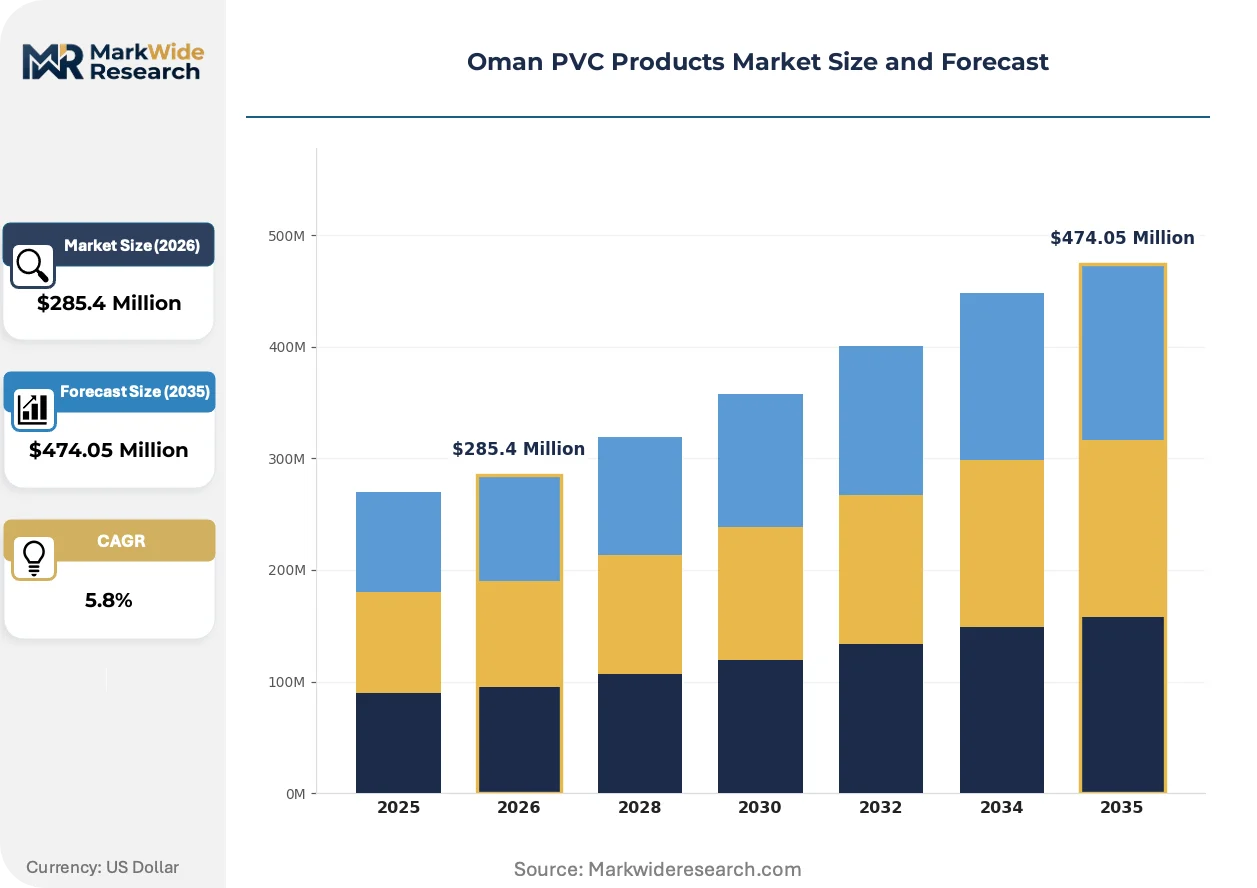
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pipes, Fittings, Sheets, Films Application: Construction, Packaging, Automotive, Electrical End User: Manufacturers, Contractors, Retailers, Wholesalers Distribution Channel: Direct Sales, Distributors, Online, Retail Stores |
| Companies Covered | Composite Pipe Industry, United Gulf Pipe Manufacturing, Muna Noor, KANA Valves Pvt. Ltd., Ledes, Oman Zawawi Est. LLC, Future Plastics LLC, Mcneil Instrument, Amiantit Oman, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman PVC Products Market Strategic Shifts & Innovations
Digitalization of supply chain coordination and material formulation science are compressing product development cycles while raising performance thresholds for infrastructure-grade polymers.
Multi-layer co-extrusion technology is integrating recycled PVC content into core layers while maintaining virgin resin surfaces for regulatory compliance. Pipe manufacturers serving desalination utilities are adopting these structures to meet circular economy procurement mandates. This architecture is integrating sustainability credentials into technical bids without sacrificing pressure-rating performance.
Oman's Ministry of Commerce, Industry and Investment Promotion is enforcing updated conformity assessment procedures aligned with Gulf Standardization Organization benchmarks. Domestic producers gain preferential treatment in public tenders when holding valid product certification marks. Water infrastructure contractors are restructuring supplier qualification protocols to prioritize certified Omani manufacturers over uncertified imports.
Master developer consolidation is compressing vendor lists and extending contract durations for approved material suppliers. Large construction groups are negotiating multi-year PVC supply agreements with fixed-volume escalators and embedded technical service provisions. This concentration is most visible in Muscat metropolitan infrastructure awards where single-source procurement now dominates municipal water network renewals.
Oman PVC Products Market Segmentation
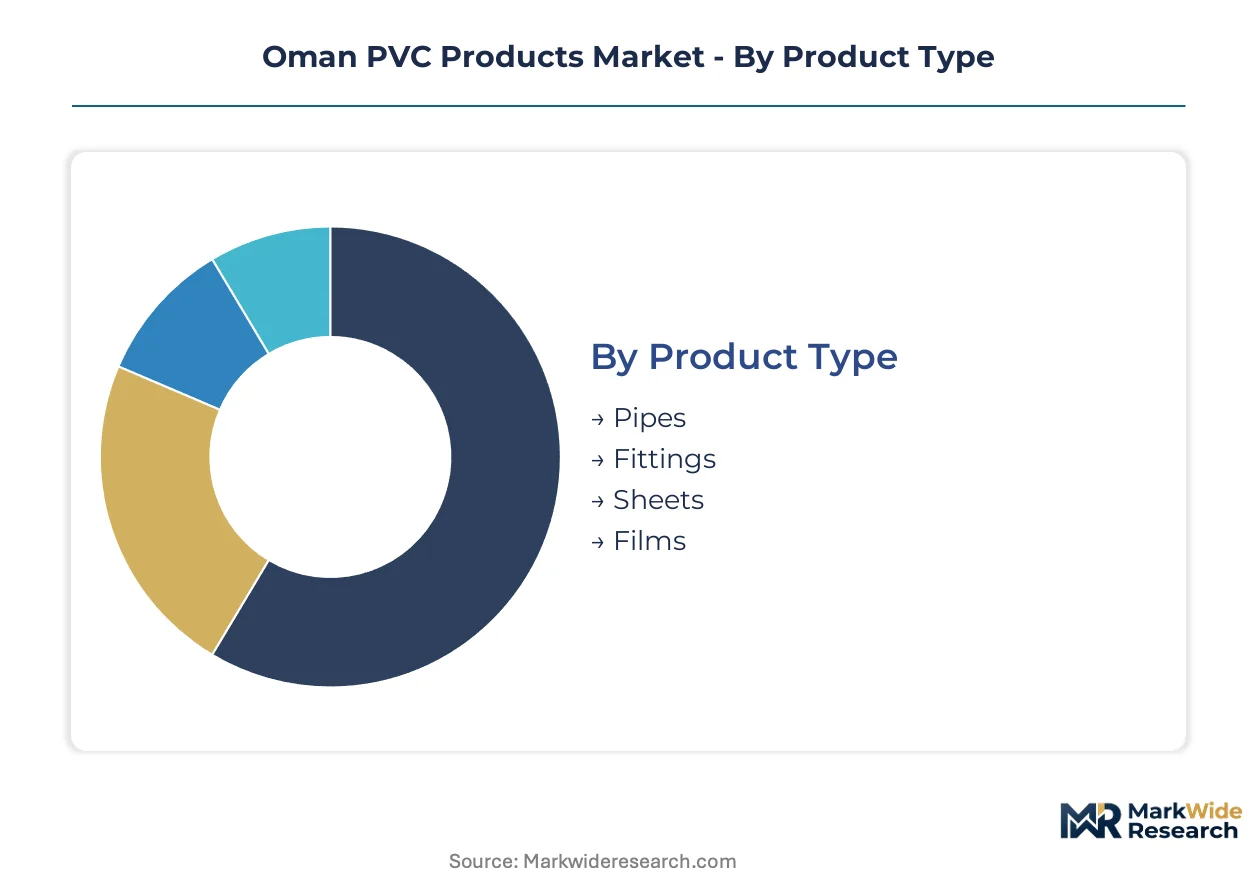
PVC product specifications in Oman diverge sharply across pressure-rating requirements, regulatory compliance tiers, and logistics intensity. Buyers prioritize certified domestic supply for water infrastructure while packaging converters chase barrier performance at lower unit economics than competing polymers.
Product Type:
Procurement specifications for the Batinah coastal corridor's desalination and distribution networks prioritize pressure-rated formulations over commodity grades.
- Pipes:Pressure-rated formulations for water distribution networks dominate procurement volumes from master developers consolidating municipal renewals under Oman Vision 2040. The Public Authority for Water mandates certified leachate compliance that favors domestic producers with established approval cycles.
- Films:Multi-layer co-extrusion technology enables recycled PVC core integration while maintaining virgin resin surfaces for food contact compliance. Modified atmosphere packaging for processed meat exports drives substitution away from higher-cost barrier polymers in Salalah's emerging food processing zone.
- Fittings:Injection-molded pressure-rated components complete system integrity for desalination utility specifications.
- Sheets:Calendered formulations serve building envelope applications with lower regulatory scrutiny than potable water contact grades.
Pipes lead on scale; films lead on momentum.
Application:
End-use economics split between infrastructure-grade certification premiums and packaging volume efficiency.
- Construction:Municipal water network renewals and desalination plant construction anchor demand concentration across Muscat and the northern Batinah corridor. Master developer consolidation forces PVC manufacturers into multi-year supply agreements with embedded technical service provisions.
- Packaging:Barrier film converters in Salalah's industrial zone displace ethylene-based polymers with PVC for modified atmosphere meat packaging targeting GCC export markets. REACH-aligned phthalate restrictions threaten legacy flexible formulations.
- Electrical:Halogen-free compound specifications for mega-project data centers command certified performance testing premiums.
- Automotive:Interior trim and underbody coating applications remain marginal due to lightweighting shifts toward polypropylene.
Construction dominates revenue concentration; packaging climbs the fastest.
End User:
Procurement scale and technical qualification requirements concentrate influence among consolidated master developers.
- Contractors:Large construction groups in Muscat negotiate fixed-volume escalators and multi-year supply agreements that compress vendor lists to certified domestic producers.
- Manufacturers:Food packaging converters in Salalah source barrier films through distributors with technical formulation support.
- Wholesalers:Inventory positions across the Dhofar region bridge logistics gaps where localized extrusion capacity is absent.
- Retailers:Small-diameter drainage and electrical conduit sales serve residential renovation demand with lower certification barriers.
Contractors command pricing power; wholesalers address geographic arbitrage.
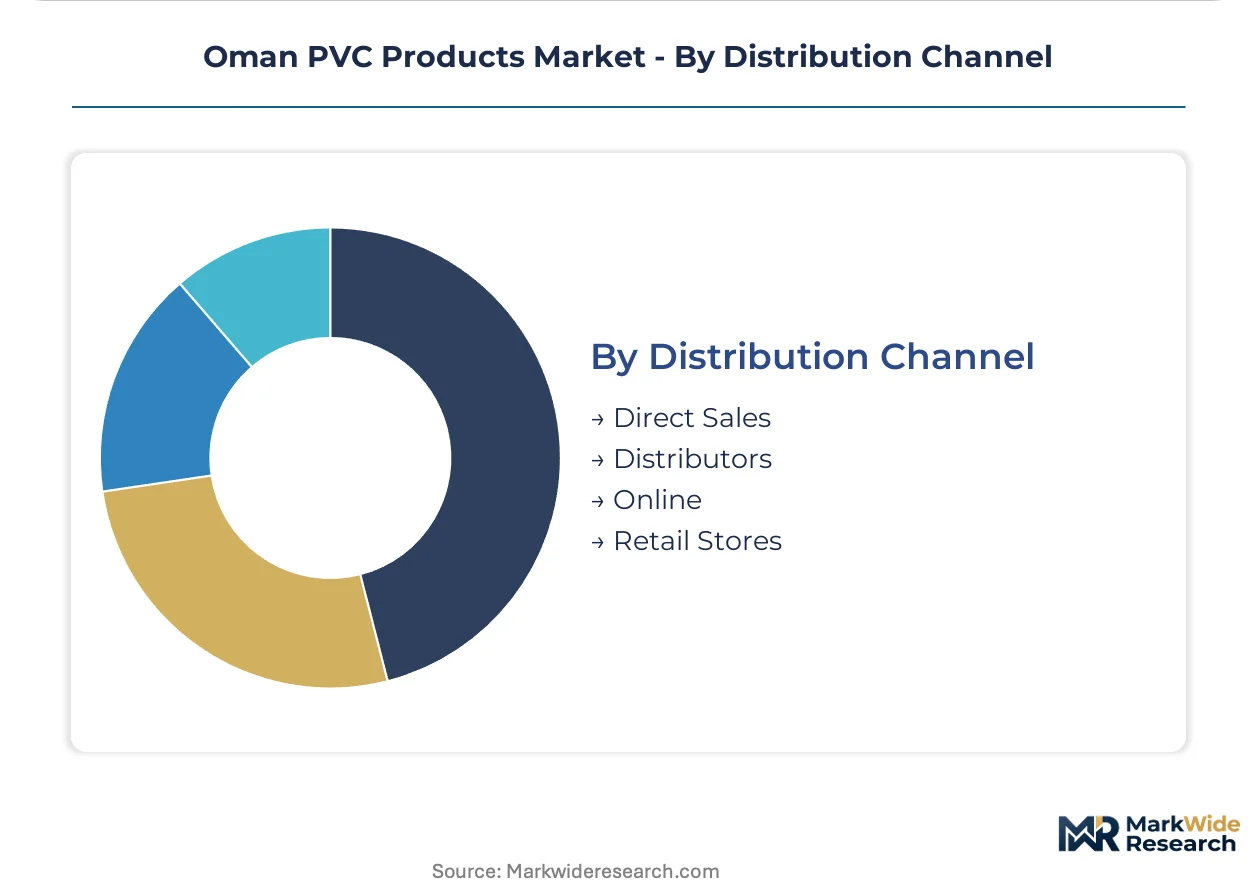
Distribution Channel:
Logistics configuration tracks buyer scale and technical service intensity requirements.
- Direct Sales:Master developers and desalination utilities procure pressure-rated piping systems through manufacturer-direct relationships with embedded application engineering support.
- Distributors:Regional inventory positions serve mid-tier contractors and packaging converters with formulation flexibility and shorter lead times than mill-direct supply.
- Retail Stores:Consumer-grade electrical conduit and drainage products move through building material merchants with limited technical consultation.
- Online:Specification-grade PVC products remain offline due to certification documentation and bulk logistics requirements.
Direct sales capture infrastructure premiums; distributors enable geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia outpaces Oman in PVC consumption scale, yet Oman commands tighter vertical integration between chlor-alkali feedstock and finished pipe extrusion. The Sultanate's northern industrial corridor concentrates capacity advantages that neighboring GCC states struggle to replicate.
Muscat Governorate
Master developers in Muscat consolidate municipal water network renewals under Oman Vision 2040 capital allocations. The Public Authority for Water enforces certified leachate compliance that favors domestic producers with established approval cycles. Rusayl Industrial Estate hosts extrusion facilities serving desalination utility specifications for pressure-rated piping systems.
Al Batinah North Governorate
Sohar Industrial Port anchors chlor-alkali production that feeds downstream PVC compounding operations. The Ministry of Commerce, Industry and Investment Promotion applies Gulf Standardization Organization benchmarks to building material conformity assessments. Liwa and Saham host pipe manufacturing clusters supplying cross-border projects in neighboring GCC states.
Al Batinah South Governorate
Logistics arbitrage opportunities emerge as distributors bridge supply gaps to Dhofar region demand. The Sultanate's technical regulations align with GCC harmonization negotiations to reduce certification friction. Rustaq and Barka serve as consolidation points for wholesale inventory positioning across the northern coastal corridor.
Dhofar Governorate
Salalah's emerging industrial zone lacks localized extrusion capacity, creating distribution network expansion incentives. Food packaging converters in the free zone substitute PVC for higher-cost barrier polymers in modified atmosphere meat exports. Raysut Industrial City attracts processors seeking southern logistics advantages for GCC market access.
Oman PVC Products Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Oman's PVC value chain. The market structure tilts toward consolidation as procurement power concentrates among fewer master developers. Three archetypes dominate: resin-integrated compounders, geographic-focused extruders, and specialized pressure-rated system suppliers. Competitive moves center on backward integration into feedstock and multi-year supply agreement negotiations with infrastructure contractors.
Within the integrated compounder tier, Composite Pipe Industry exemplifies captive resin supply strategies. United Gulf Pipe Manufacturing anchors geographic positioning through its Sohar Industrial Port manufacturing base. Muna Noor occupies the specialized systems vector for desalination utility specifications. These three represent distinct competitive postures rather than interchangeable market participants.
| Leading Market Players |
|---|
| Composite Pipe Industry |
| United Gulf Pipe Manufacturing |
| Muna Noor |
| KANA Valves Pvt. Ltd. |
| Ledes |
| Oman Zawawi Est. LLC |
| Future Plastics LLC |
| Mcneil Instrument |
| Amiantit Oman |
| Others |
Cost & Logistics Intelligence
Chlor-alkali feedstock costs transmit directly from Sohar Industrial Port's integrated petrochemical complexes through three pricing strata: pressure-rated potable piping commands certification premiums, commodity construction grades compete on volume escalators, and flexible film formulations face plasticizer substitution cost pressures. Master developer consolidation in Muscat amplifies buyer leverage, compressing margins on standard grades while insulating specialized desalination system suppliers.
Pricing Analysis
Capacity additions in the Batinah coastal corridor are reshaping price floors for commodity PVC grades. Three-tier pricing structure across premium, standard, and economy levels separates certified pressure-rated piping for Public Authority for Water compliance from uncertified imports and recycled-core formulations. Pricing pressure stems from ethylene cost volatility linked to naphtha pricing, squeezing compounders without captive VCM supply. Small contractors and retail drainage buyers exhibit highest price sensitivity; desalination utilities prioritize certification over unit cost.
Supply Chain Analysis
Scrap PVC collection and reprocessing flows from construction demolition sites feed multi-layer co-extrusion core layers, reducing virgin resin demand. Geographic supply concentrates in Oman, Saudi Arabia, and the UAE, with Sohar Industrial Port anchoring chlor-alkali production. Raw material dependencies span vinyl chloride monomer, calcium-zinc stabilizers, and acrylic impact modifiers sourced from Asian chemical producers. Single-source vulnerability for specialty additives exposes compounders to freight rate volatility. Distribution runs through manufacturer-direct relationships for infrastructure projects and regional distributors for packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's PVC market functions as a geographic-arbitrage play between the Sultanate's integrated chlor-alkali capacity and import-dependent GCC neighbors lacking comparable feedstock integration. Regulatory harmonization under Gulf Standardization Organization benchmarks amplifies cost advantages for certified domestic producers supplying cross-border projects.
For Market Incumbents: Deploy backward integration into captive VCM supply to defend margins against ethylene cost volatility. Secure multi-year offtake agreements with consolidated master developers in Muscat to lock in volume commitments before new extrusion capacity emerges. Invest in pressure-rating certification infrastructure to maintain preferential positioning in Public Authority for Water procurement protocols.
For New Entrants and Emerging Players: Digital distribution platforms targeting Dhofar region wholesalers address the logistics arbitrage created by Salalah's absent extrusion capacity. Target food packaging converters in Raysut Industrial City with technical formulation support for modified atmosphere barrier films. Pursue partnership routes with established distributors rather than greenfield manufacturing given certification timeline barriers.
For Investors and Strategic Acquirers: Consolidation pressure builds where procurement power concentrates among fewer master developers under Oman Vision 2040 infrastructure awards. Long-term viability favors resin-integrated compounders with established certification cycles over pure-play extruders facing margin compression. Monitor Gulf Standardization Organization phthalate restriction adoption timelines as inflection indicators for flexible film segment restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM | Captive chlor-alkali supply insulates Composite Pipe Industry from naphtha-linked ethylene volatility. |
| Multi-Year Supply Agreement | Fixed-volume escalators with Muscat master developers secure revenue visibility across Oman Vision 2040 project cycles. |
| Pressure-Rating Certification Investment | Public Authority for Water compliance creates procurement preference over uncertified GCC imports. |
| Multi-Layer Co-Extrusion Adoption | Recycled PVC core integration meets circular economy mandates without sacrificing desalination utility performance. |
| Dhofar Distribution Network Expansion | Salalah logistics arbitrage captures packaging converter demand lacking localized extrusion capacity. |
Research Approach
Bottom-up construction contractor demand modeling reconciled against top-down chlor-alkali capacity tracking forms the analytical core of this study. Primary interviews with procurement directors at master developers, plant managers at Sohar Industrial Port complexes, and technical sales leads at desalination EPC contractors combined with secondary validation from Gulf Standardization Organization technical regulations, Public Authority for Water certification databases, and Oman Ministry of Commerce customs records. Triangulation across these sources ensured supply-side and demand-side estimates converged.
Input-output matrices mapped vinyl chloride monomer throughput to finished pipe, film, and fitting volumes across the analysis window. Segmentation dimensions encompassed product type, pressure-rating tier, regulatory compliance grade, and end-use application intensity. CAGRs derived from slope-log regression of annual volume estimates, with sensitivity testing around Oman Vision 2040 capital allocation timing and GCC cross-border trade flow assumptions. Feedstock integration rates and certification approval cycle durations served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for mechanical recycling versus chemical depolymerization would alter the outlook for recycled content mandates in core-layer formulations. Forecasts reflect assumptions about Gulf Standardization Organization-EU regulatory convergence timing and chlor-alkali capacity expansion schedules. Practitioners should monitor Public Authority for Water leachate standard revisions and REACH-aligned phthalate restriction announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
South-East Asia Low-Density Polyethylene (LDPE) Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Polyphenylene Oxide (PPO) Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Nylon 66 Market