
 Global Cyclic Olefin Copolymers Market | 2026-2036
Global Cyclic Olefin Copolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cyclic Olefin Copolymers Market Intelligence
The displacement of glass and polycarbonate in high-value medical packaging and diagnostic consumables is consolidating the position of cyclic olefin copolymers (COCs). TOPAS Advanced Polymers specializes in high-purity grades for these sensitive applications. ZEON CORPORATION leverages its extensive polymer chemistry expertise to compete on performance. Meanwhile, Polyplastics Co., Ltd. focuses on developing specific blends for optical and electronic components, differentiating its portfolio for non-medical end uses.
Cyclic olefin copolymers are amorphous polymers synthesized from cyclic monomers and ethene, resulting in exceptional optical clarity and low birefringence. Their primary industrial value comes from high moisture barrier properties and chemical resistance, making them ideal for sensitive applications. Within applications, medical devices and optical films represent the largest segments by value. Injection molding remains the dominant processing technology, required for producing complex geometries in diagnostic cartridges and electronic components.
Material selection is heavily influenced by stringent regulatory frameworks, including biocompatibility standards from the US FDA and the EU's Medical Device Regulation (MDR). Compliance with these standards, along with approvals from bodies like Japan's PMDA, dictates market access for medical-grade polymers. Stakeholders must navigate the trade-off between the high performance of COCs and the cost-effectiveness of incumbent materials in non-critical applications.
Market Dynamics
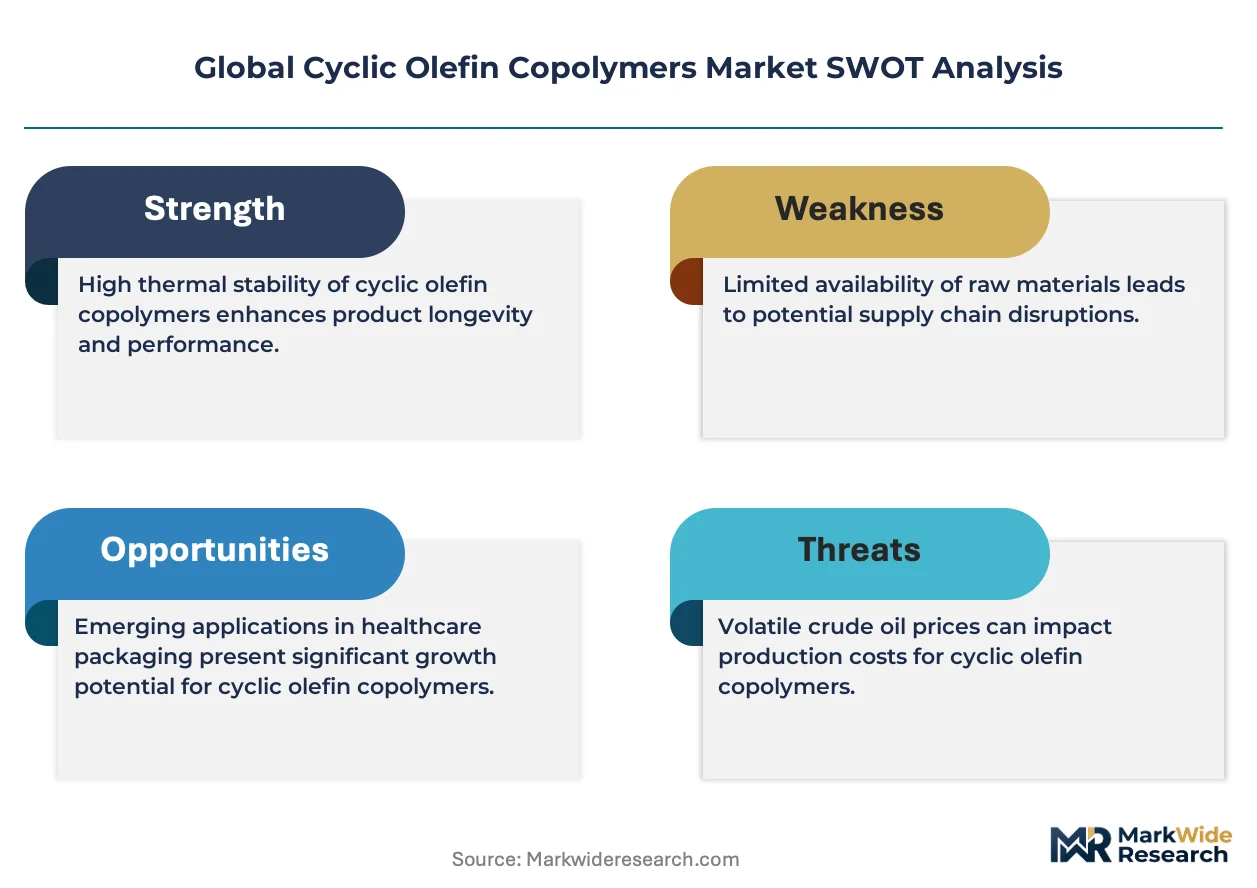
The primary structural force governing the cyclic olefin copolymers market is the stringent regulatory landscape for medical materials. Mandates such as the European Union's Medical Device Regulation (MDR) are compelling a flight to quality, favoring high-purity, biocompatible polymers over traditional materials.
Growth Catalysts
- Medical Device Regulation:The EU's MDR imposes stricter requirements for material biocompatibility and chemical safety, directly favoring the adoption of inert COCs in applications like pre-filled syringes and diagnostic vials over incumbent polymers.
- Diagnostic Miniaturization:Demand for microfluidics in point-of-care testing and lab-on-a-chip devices requires materials with exceptional optical clarity, dimensional stability, and chemical resistance, all hallmark properties of cyclic olefin copolymers.
- Optical Component Advancement:The need for lightweight, high-clarity materials in smartphone camera lenses, automotive heads-up displays, and augmented reality optics drives COC adoption, leveraging its low birefringence and superior light transmission.
Market Restraints
- Premium Cost Structure:The relatively high price of COC resins compared to commodity plastics like polypropylene and established engineering polymers such as polycarbonate restricts its use to high-performance applications where its benefits justify the cost.
- Concentrated Monomer Supply:The supply chain for key cyclic olefin monomers is highly concentrated among a few chemical producers, creating vulnerability to price fluctuations and potential bottlenecks for polymer manufacturers.
- Processing Complexity:Optimizing injection molding processes for amorphous COCs requires specialized technical expertise and equipment to manage melt flow and minimize internal stresses, posing a barrier for some converters.
Strategic Opportunities
- Flexible Display Substrates:The unique combination of optical clarity, low moisture absorption, and flexibility positions COCs as a candidate material for next-generation flexible and foldable electronic display backplanes and encapsulation films.
- Pharmaceutical Packaging in Emerging Markets:Rising quality standards in pharmaceutical manufacturing hubs like India and Brazil present an opportunity for COCs to displace glass in primary packaging for sensitive biologic drugs.
- COC/Polyolefin Blends:Developing alloys of COC with commodity polyolefins offers a path to create cost-effective materials with tailored properties, such as enhanced toughness or flexibility, for packaging and industrial applications.
Industry Challenges
- Specialized Processing Knowledge:A skills gap exists for process engineers and machine operators with deep expertise in molding high-precision COC parts, which can lead to longer cycle times and higher scrap rates during production.
- Lengthy Validation Cycles:Gaining regulatory clearance for new medical-grade COC resins involves extensive and costly testing to comply with standards from the FDA, EMA, and Japan's PMDA, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cyclic Olefin Copolymers Market |
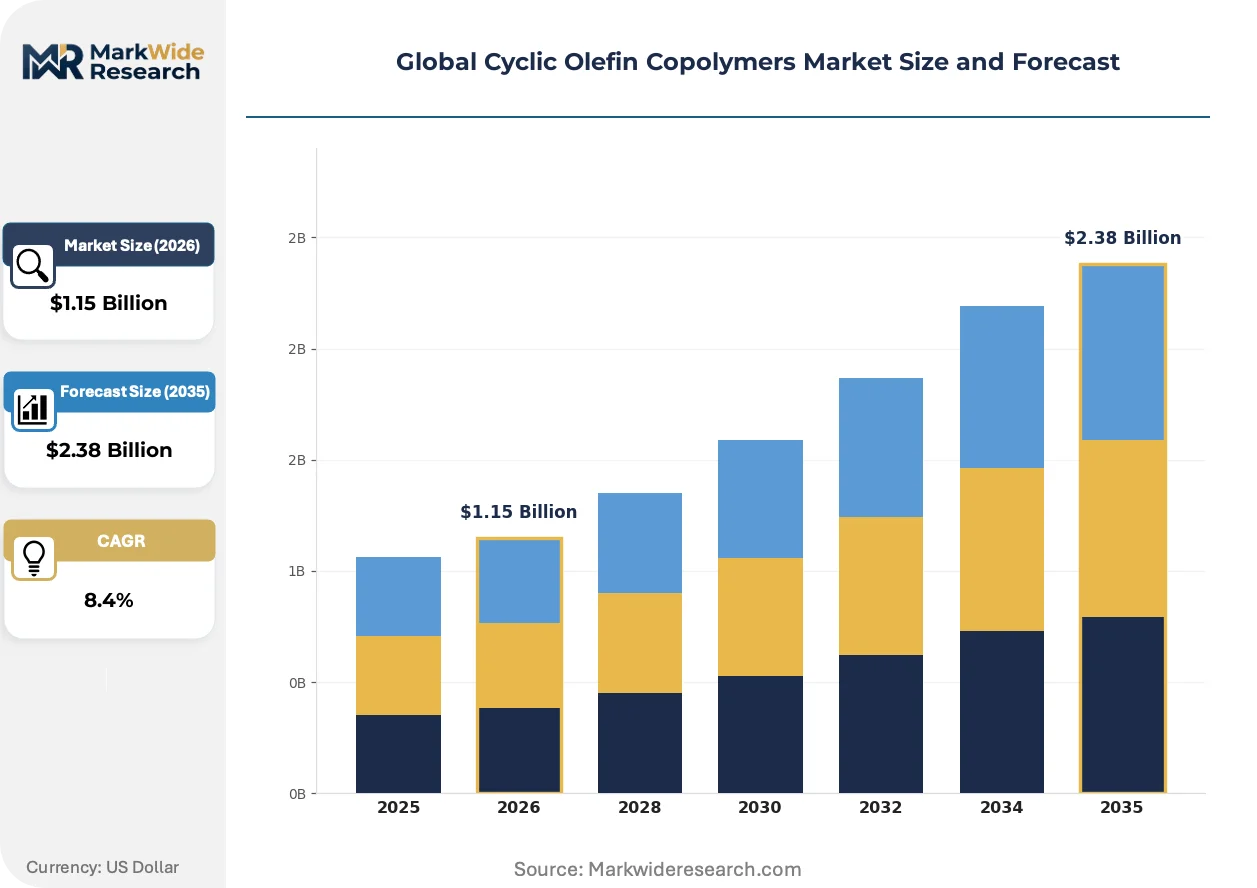
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.38 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Blend, Modified, High-Performance, Specialty Application: Optical Films, Packaging, Medical Devices, Electronics Components, Automotive Parts End User: Pharmaceutical Companies, Electronic Manufacturers, Consumer Goods Producers, Automotive Suppliers, Packaging Houses Processing Technology: Injection Molding, Extrusion, Blow Molding, Thermoforming, Film Casting |
| Companies Covered | Polyplastics Co., Ltd., Sumitomo Chemical Co., Ltd., TOPAS Advanced Polymers, Idemitsu Kosan, JSR Corporation, ZEON CORPORATION, SABIC, Boehringer Ingelheim, Mitsui Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cyclic Olefin Copolymers Market Strategic Shifts & Innovations
Material science advancements are converging with new processing methods, enabling COCs to meet exacting performance criteria. This evolution is most visible in applications demanding superior purity for medical use and pristine optical properties for advanced electronics.
Additive manufacturing of COC is emerging as a critical tool for rapid prototyping. Medical device engineers and academic researchers are the primary adopters, using specialized filaments to create low-volume, high-complexity components for diagnostic and microfluidic systems. This capability is decentralizing the design and testing process, allowing for faster product iteration without reliance on expensive, centralized injection molding facilities.
Regulatory frameworks globally are tightening controls on material purity in drug-contact applications. Japan's PMDA, for example, is increasing its scrutiny of leachable and extractable substances from primary pharmaceutical packaging, pushing material standards higher. This action elevates the value of inherently pure polymers like COC for containing sensitive biologic drugs. Consequently, packaging converters serving the Japanese market are accelerating their qualification of COC vials and syringes.
A distinct behavioral shift is evident in how materials are specified for regulated products. End-users in the medical device sector increasingly prioritize COC grades that come with pre-validated compliance to key biocompatibility standards like ISO 10993 and USP Class VI. This preference for certified materials allows device manufacturers to bypass extensive preliminary screening, compressing development timelines. The trend is most pronounced in the competitive North American diagnostics market, where reducing time-to-market is paramount.
Global Cyclic Olefin Copolymers Market Segmentation
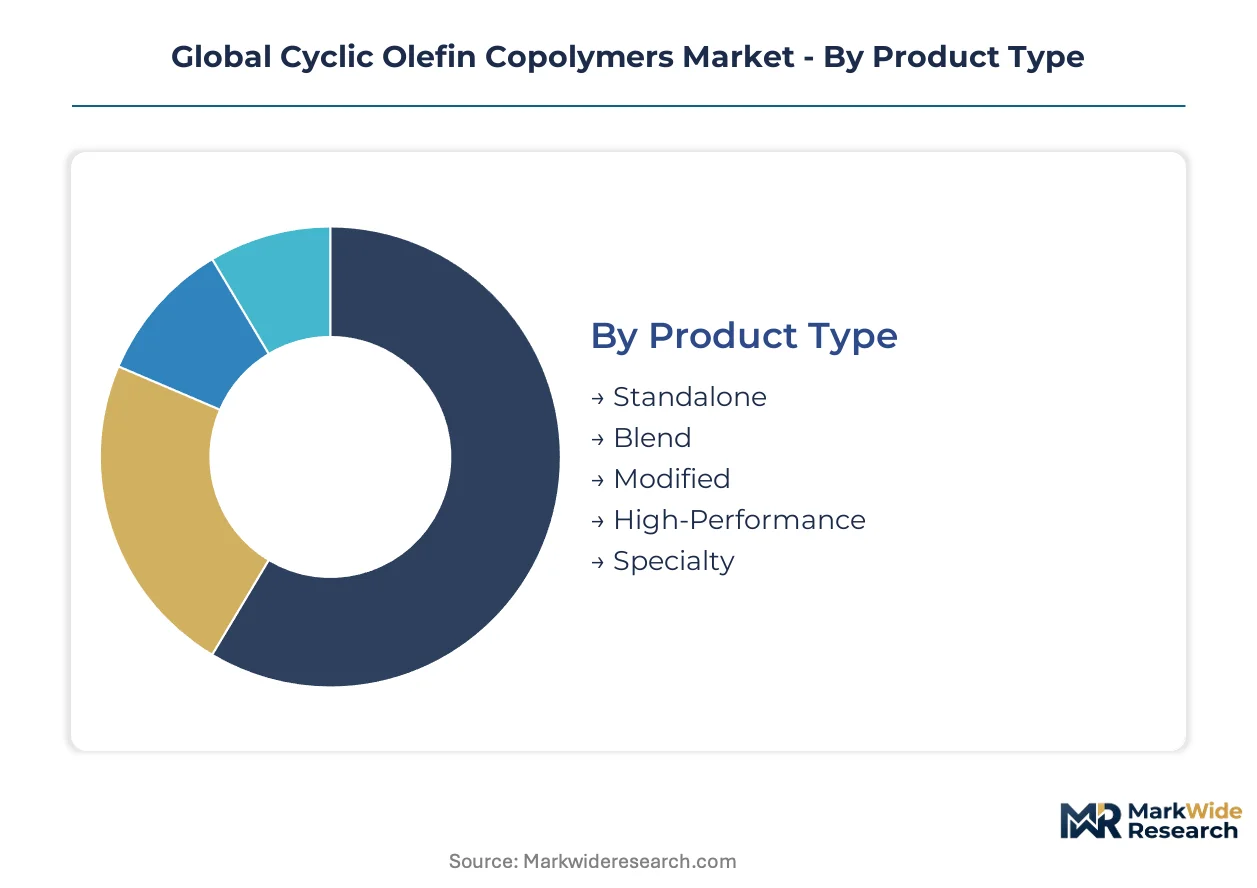
Understanding the segmentation of the cyclic olefin copolymers market reveals the specific value propositions driving adoption across diverse industries. Each segment highlights distinct performance requirements and commercial opportunities for these advanced polymers.
Product Type:
The product type segmentation differentiates cyclic olefin copolymers based on their composition and intended performance, separating high-volume applications from premium, specialized formulations.
- High-Performance:These COC grades offer superior thermal stability, chemical resistance, and mechanical properties, often engineered for demanding applications. Demand concentrates in advanced medical devices and precision optical components where material integrity is paramount.
- Specialty:Tailored COC formulations address niche requirements, such as ultra-low extractables for pharmaceutical packaging or specific dielectric properties for electronics. Japan's PMDA regulations increasingly favor these specialized materials for sensitive drug-contact applications.
- Standalone:This category encompasses general-purpose COC resins used in a broad range of applications that benefit from optical clarity and barrier properties.
- Blend:COC blends combine cyclic olefin copolymers with other polymers to achieve a modified balance of properties, such as enhanced toughness or processability.
- Modified:Chemically altered COC variants provide specific functional enhancements, including improved adhesion or UV resistance for particular end uses.
Today's leader: Standalone. Tomorrow's challenger: High-Performance.
Application:
The market's application landscape reveals where cyclic olefin copolymers deliver their most significant functional advantages, often displacing traditional materials due to superior performance characteristics.
- Medical Devices:COCs are increasingly specified for pre-filled syringes, diagnostic vials, and microfluidic components due to their biocompatibility, chemical inertness, and optical clarity. The EU's Medical Device Regulation (MDR) reinforces the need for these high-purity materials.
- Optical Films:Cyclic olefin copolymers provide exceptional light transmission, low birefringence, and dimensional stability, making them ideal for display films, lenses, and optical sensors. Advancements in augmented reality optics specifically leverage these properties.
- Packaging:Cyclic olefin copolymers offer excellent moisture barrier properties and chemical resistance for pharmaceutical blisters, food packaging, and specialized containers.
- Electronics Components:COCs are used in capacitor films, flexible circuits, and encapsulants for their electrical insulation and low dielectric constant.
- Automotive Parts:These polymers find application in interior components, lenses, and sensors where lightweighting and optical clarity are beneficial.
Medical devices and optical films continue to drive demand for specialized COC formulations.
End User:
End-user segments reflect the diverse industries leveraging COC properties, often driven by specific regulatory or performance needs for their final products.
- Pharmaceutical Companies:These companies adopt COCs for primary drug packaging and medical device components, prioritizing material purity, chemical inertness, and regulatory compliance. US FDA and European EMA guidelines influence material selection significantly.
- Electronic Manufacturers:Manufacturers utilize COCs in displays, camera lenses, and various components, valuing their optical clarity, electrical properties, and dimensional stability. Smartphone and automotive electronics are key growth areas.
- Packaging Houses:These firms process COC resins into films, bottles, and containers for various industries, focusing on barrier properties and aesthetic appeal.
- Automotive Suppliers:Suppliers integrate COCs into vehicle interiors and sensor systems, seeking lightweight and high-performance optical solutions.
- Consumer Goods Producers:Producers use COCs in specialized packaging and durable goods where clarity, chemical resistance, or haptics are critical.
Pharmaceutical companies and electronic manufacturers are rapidly expanding their adoption of COC materials.
Processing Technology:
Processing technologies define the manufacturing versatility of cyclic olefin copolymers, from complex geometries to thin films, impacting the final product's performance and cost structure.
- Injection Molding:This dominant processing method enables the high-precision manufacturing of complex COC parts, including diagnostic cartridges, microfluidic devices, and optical lenses. Optimizing melt flow is critical for maintaining part integrity.
- Film Casting:Producing thin, optically clear COC films for displays, flexible electronics, and high-barrier packaging relies on specialized film casting techniques. This method leverages COC's low birefringence for advanced optical applications.
- Extrusion:Extrusion processes create COC sheets, profiles, and tubing for various industrial and medical applications, valued for their consistent dimensions and barrier properties.
- Blow Molding:This technique forms hollow COC containers and bottles, particularly where excellent moisture barrier and chemical resistance are required.
- Thermoforming:Thermoforming shapes COC sheets into trays and blister packaging, offering cost-effective production for certain applications.
Injection molding remains central to COC production, while film casting enables new applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced manufacturing clusters within Germany and Japan drive significant cyclic olefin copolymers demand. These regions, alongside other industrial powerhouses, prioritize high-purity, biocompatible polymers for sensitive applications. Global market expansion benefits from stringent regulatory frameworks and technological advancements across these key geographies.
Germany
Demand for pre-filled syringes and diagnostic vials drives COC adoption in Germany. The European Union's Medical Device Regulation (MDR) mandates stringent material biocompatibility, favoring high-purity polymers. Advanced manufacturing hubs in Bavaria focus on precision injection molding for complex medical components. Chemical producers in the Rhine-Ruhr region develop specialized COC grades.
Japan
Optical films and pharmaceutical packaging represent major demand areas for cyclic olefin copolymers in Japan. Japan's PMDA rigorously scrutinizes leachable substances from primary drug-contact materials, promoting COC use. Tokyo's electronics industry and Osaka's pharmaceutical sector continuously integrate COCs into advanced products. Material science companies in the Kanto region lead in developing specialty COC formulations.
United States
Diagnostic miniaturization and high-value medical packaging propel COC demand across the United States. The US FDA's biocompatibility standards, including USP Class VI, heavily influence material selection for device manufacturers. Biotech clusters in Boston and San Francisco Bay Area increasingly specify COCs for microfluidic devices. Precision molding facilities in the Midwest support advanced medical component production.
China
Electronic components and pharmaceutical packaging applications are rapidly expanding for cyclic olefin copolymers in China. The NMPA's evolving drug packaging regulations encourage the use of higher-grade, inert materials like COC. Manufacturing centers in the Yangtze River Delta integrate COCs into advanced display technologies. Medical device production in Shenzhen increasingly adopts COC for sensitive diagnostic consumables.
Global Cyclic Olefin Copolymers Market Key Industry Players
Global majors compete with regional champions across material innovation and market reach within the cyclic olefin copolymers sector. The market exhibits a tiered structure, with a few large chemical producers dominating primary resin supply. Strategic archetypes include integrated chemical giants, specialized polymer manufacturers, and regional converters. Competitive moves focus on strategic partnerships for application development and targeted capacity expansions.
Specialized polymer manufacturers like TOPAS Advanced Polymers exemplify the focus on high-purity grades for sensitive medical applications, particularly for pre-filled syringes and diagnostic vials. ZEON CORPORATION, with its extensive polymer chemistry expertise, occupies a strong position in performance-driven segments, leveraging its capabilities in advanced polymer synthesis. Meanwhile, Polyplastics Co., Ltd. represents an archetype of material developers focusing on specific blends for optical and electronic components, differentiating its portfolio for non-medical end uses. These companies collectively anchor the innovation landscape, driving material advancements across diverse applications.
| Leading Market Players |
|---|
| Polyplastics Co., Ltd. |
| Sumitomo Chemical Co., Ltd. |
| TOPAS Advanced Polymers |
| Idemitsu Kosan |
| JSR Corporation |
| ZEON CORPORATION |
| SABIC |
| Boehringer Ingelheim |
| Mitsui Chemicals, Inc. |
| Others |
Cost & Logistics Intelligence
The certification ladder for medical-grade cyclic olefin copolymers creates a distinct tier divergence, manifesting in both premium pricing and specialized supply chain configurations. This bifurcation separates high-purity, regulated materials from more general-purpose grades, influencing supplier focus and customer access.
Pricing Analysis
Raw material costs for cyclic olefin monomers significantly influence the final price of COC resins. The dominant pricing model for high-performance grades is value-based, often incorporating long-term contract-based off-take agreements. Price differentiation stems from certification levels, such as USP Class VI and PMDA compliance, alongside the specific purity grade and customization required. Pricing pressure for medical-grade COCs trends upward due to stringent regulatory compliance and R&D investments. Pharmaceutical companies and medical device manufacturers exhibit the least price sensitivity for critical applications.
Supply Chain Analysis
Single-source vulnerability sits with the concentrated supply of key cyclic olefin monomers among a few global chemical producers. Geographic supply concentration for advanced COC production centers in Japan and Germany, with growing capacity in the United States and China. The supply chain relies heavily on ethene and specialized cyclic monomers as primary inputs. Commodity price volatility for these raw materials represents a significant structural risk. Distribution runs through direct sales channels to large medical device OEMs and specialized converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cyclic olefin copolymers market acts as a regulatory compounder, with the European Union's Medical Device Regulation (MDR) significantly accelerating demand for high-purity materials.
For Market Incumbents: Cement market leadership by focusing on sustained innovation in medical-grade cyclic olefin copolymers. Invest in expanding high-purity production capacity within regulated geographies like Germany and Japan. Pursue upstream control over key monomer supply to mitigate raw material price volatility, countering the threat from cost-effective incumbent materials in non-critical applications.
For New Entrants and Emerging Players: Begin with targeted product development for specific unmet needs in non-medical applications. Focus on developing COC/polyolefin blends to offer cost-effective solutions for packaging houses and industrial applications. The packaging sector in emerging markets like India and Brazil represents a penetrable segment, offering a viable go-to-market angle through partnerships with local converters.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized polymer manufacturers demonstrating deep expertise in medical-grade cyclic olefin copolymers. The market offers strong growth potential over the next decade, driven by regulatory tailwinds and advancing material science. Target acquisition candidates with proprietary synthesis capabilities or extensive biocompatibility certifications. Increased M&A activity among smaller, innovative material science firms is a signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Germany and Japan | Reinforces local supply for regulated medical and pharmaceutical markets. |
| Biocompatibility Certification Investment | Expedites market entry for new medical device and pharmaceutical packaging applications. |
| COC/Polyolefin Blend Development | Unlocks new cost-effective applications in industrial and general packaging segments. |
| Additive Manufacturing Filament R&D | Supports rapid prototyping and low-volume production for microfluidics and diagnostics. |
| Strategic Partnerships with Converters | Expands reach into complex injection molding segments for advanced electronic components. |
Research Approach
Direct dialogue with medical device engineers, pharmaceutical R&D leads, and polymer scientists informed the qualitative grounding. This primary research was triangulated with extensive secondary validation from regulatory filings like those of the FDA, EMA, and Japan's PMDA. Patent databases, industry association reports, and academic literature also contributed to the comprehensive data approach, combining bottom-up and top-down analyses.
The integrated market sizing and forecasting model produced granular volume and value projections across the analysis window. This framework segmented the market by product type, application, end user, processing technology, and regional production hub. Compound annual growth rates were derived from historical trends, regulatory impact assessments, and technological adoption curves, with raw material price trends and medical device approval rates as key forecast inputs.
Caveats apply where unforeseen regulatory changes, new material innovations, or geopolitical supply chain disruptions could materially shift the outlook. Forecasts reflect assumptions regarding market dynamics and technological progression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Polypropylene and High-Impact Polystyrene Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Polyisobutylene (PIB) Market