
 Homopolymer Resins Market | 2026-2036
Homopolymer Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Homopolymer Resins Market Analytics
Direct resin distribution from producers to large compounders is tilting away from traditional distributor networks in North America and Europe. LyondellBasell Industries N.V. leverages its Gulf Coast manufacturing scale to supply injection molders directly, while ExxonMobil Corporation sustains long-term offtake agreements with automotive tier-one suppliers. Braskem S.A. anchors its position through captive feedstock integration at its Brazilian complexes, giving it cost leverage in export markets.
Homopolymer resins consist of polymer chains derived from a single monomer species, with polypropylene homopolymers exhibiting crystallinity levels of 50-70% and melting points near 160°C, making them suitable for rigid packaging and automotive interior components. Polypropylene grades dominate volume flows due to their stiffness-to-weight ratio in automotive underhood applications, while polycarbonate segments command margin pools in electronics housings where optical clarity and heat resistance prove critical. High-temperature grades across the product spectrum are gaining traction as appliance manufacturers redesign components for extended thermal cycling.
EPA emissions standards for polymer production facilities and REACH substance restrictions in Europe are forcing resin producers to reformulate catalyst systems and reduce residual monomer content below 50 ppm thresholds. FDA food-contact notification requirements govern polypropylene and polystyrene grades destined for packaging applications in the United States, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent chemical safety assessments threaten to fragment product specifications and complicate global inventory management.
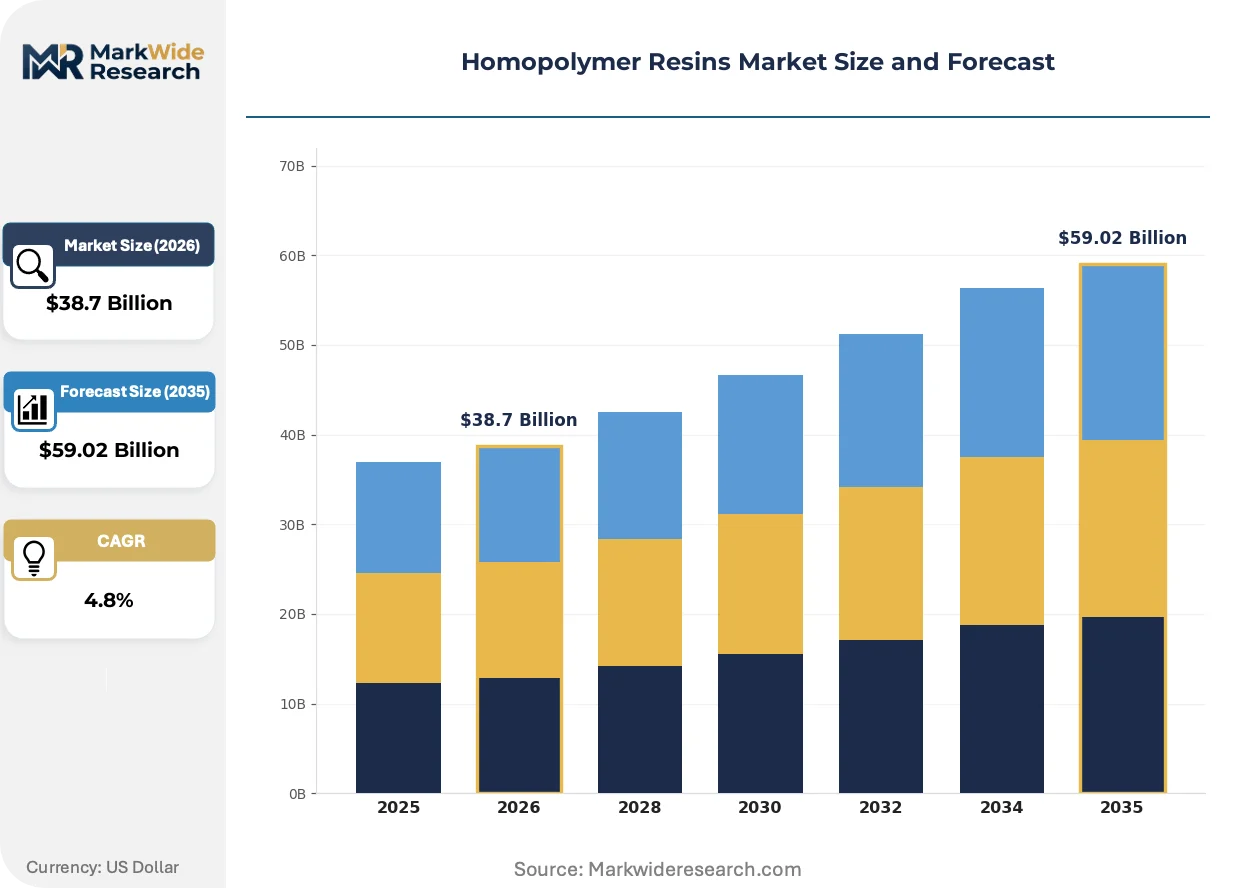
Market Dynamics
Feedstock cost volatility and catalyst technology maturation are compressing margin structures for homopolymer resin producers, forcing operational discipline across polymerization complexes in the United States, Germany, and China.
Growth Catalysts
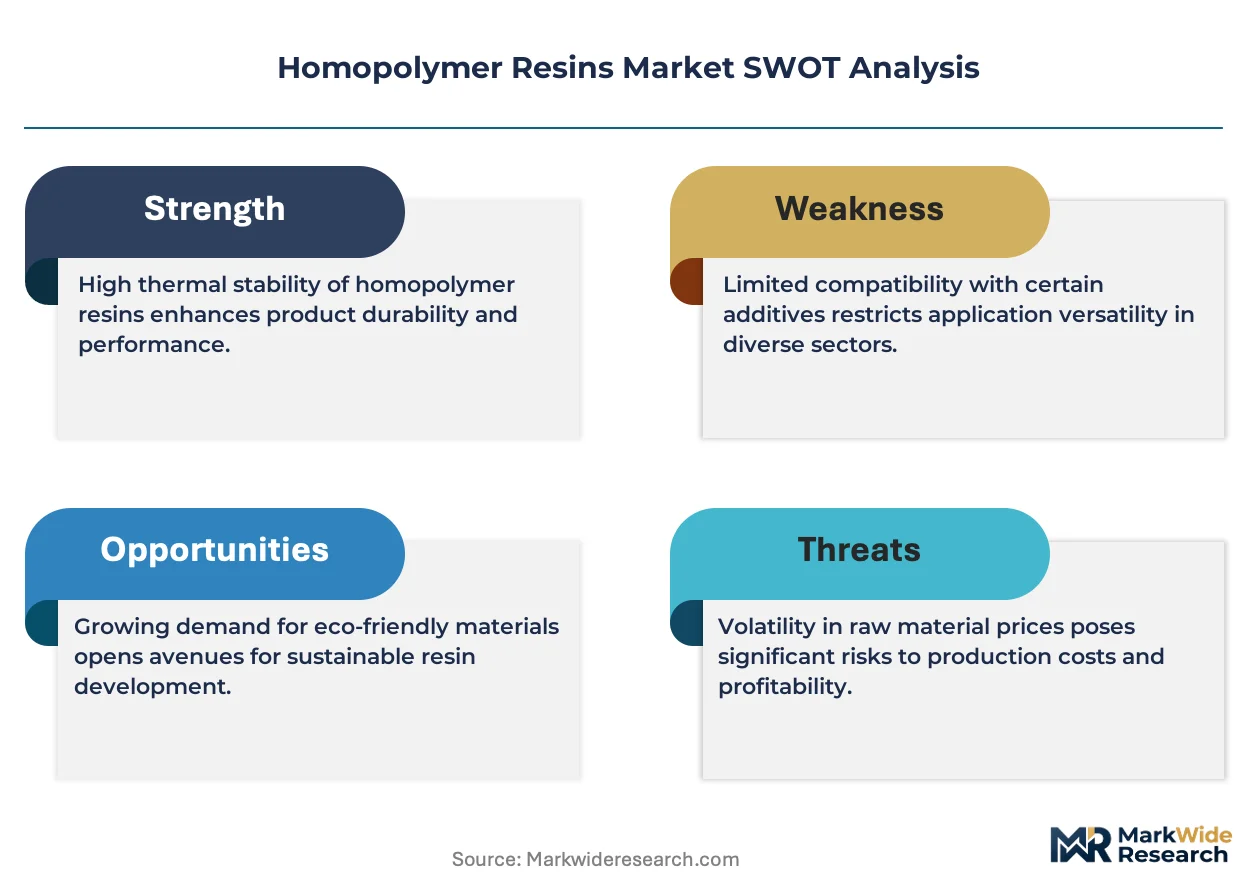
- REACH substance restrictions:European ECHA mandates on residual monomer thresholds below 50 ppm are accelerating purification technology upgrades across polypropylene supply chains.
- Automotive lightweighting:Tier-one suppliers in Detroit and Stuttgart are specifying high-crystallinity homopolymer grades for underhood thermal management components.
- Zhejiang polymer clusters:Downstream compounding concentration in China's eastern coastal provinces is pulling import volumes through Ningbo port infrastructure.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker economics in the US Gulf Coast and Middle East are transmitting price swings directly into homopolymer cost structures.
- Polyethylene substitution:Linear low-density polyethylene from metallocene catalyst systems is capturing flexible packaging applications previously served by homopolymer polypropylene.
- MEE emissions enforcement:China's Ministry of Ecology and Environment is idling polymerization capacity in Shandong province for stack-emission noncompliance.
Strategic Opportunities
- Medical-grade certification:USP Class VI and ISO 10993 biocompatibility standards are creating premium pricing tiers for sterilizable surgical instrument housings.
- Direct compounding partnerships:Resin producers are bypassing traditional distributors to forge toll-manufacturing relationships with automotive injection molders in Bavaria and Michigan.
- Post-consumer recycled feedstock:EU Green Deal circular-economy mandates are opening specification windows for chemically recycled homopolymer grades in food-contact applications.
Industry Challenges
- Phillips and Ziegler-Natta catalyst expertise:Polymerization process engineering talent pools are thinning as veteran technologists retire from European and North American research centers.
- FDA food-contact notification timelines:Polypropylene additive packages face 180-day review cycles that delay new product launches for US beverage packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homopolymer Resins Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polystyrene, Polycarbonate, Polyvinyl Chloride Grade: Standard, High-Impact, Low-Density, High-Temperature Application: Packaging, Automotive, Consumer Goods, Electronics End Use Industry: Construction, Healthcare, Agriculture, Aerospace |
| Companies Covered | LyondellBasell Industries N.V., Reliance Industries Limited, ExxonMobil Corporation, INEOS Group Ltd., Braskem S.A., Borealis AG, BASF, SABIC, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homopolymer Resins Market Evolving Landscape
Digital twin deployment across polymerization assets is compressing batch-to-batch variability, while regulatory chemical-safety assessments are fragmenting global product specifications.
Single-site metallocene catalyst systems are virtualizing molecular-weight distribution control in polypropylene production. Automotive compounders in Stuttgart and Detroit are qualifying these grades for bumper fascias and interior panels at accelerated timelines. The technology is virtualizing quality-assurance protocols by embedding predictive rheology models directly into extrusion line control systems.
EU REACH authorization requirements for boron-containing catalyst residues are forcing reformulation of polypropylene polymerization chemistry. Resin producers are migrating to magnesium chloride-supported catalyst systems that eliminate boron tracing. Food-contact grades destined for European packaging converters face the steepest compliance timelines.
Compounders in Guangdong province are consolidating purchase orders through digital procurement platforms that bypass traditional distributor markups. Large-volume automotive molders in Foshan and Dongguan now transact directly with Singapore-trading resin suppliers. This channel compression is most visible in southern China's export-oriented manufacturing corridors.
Homopolymer Resins Market Segmentation
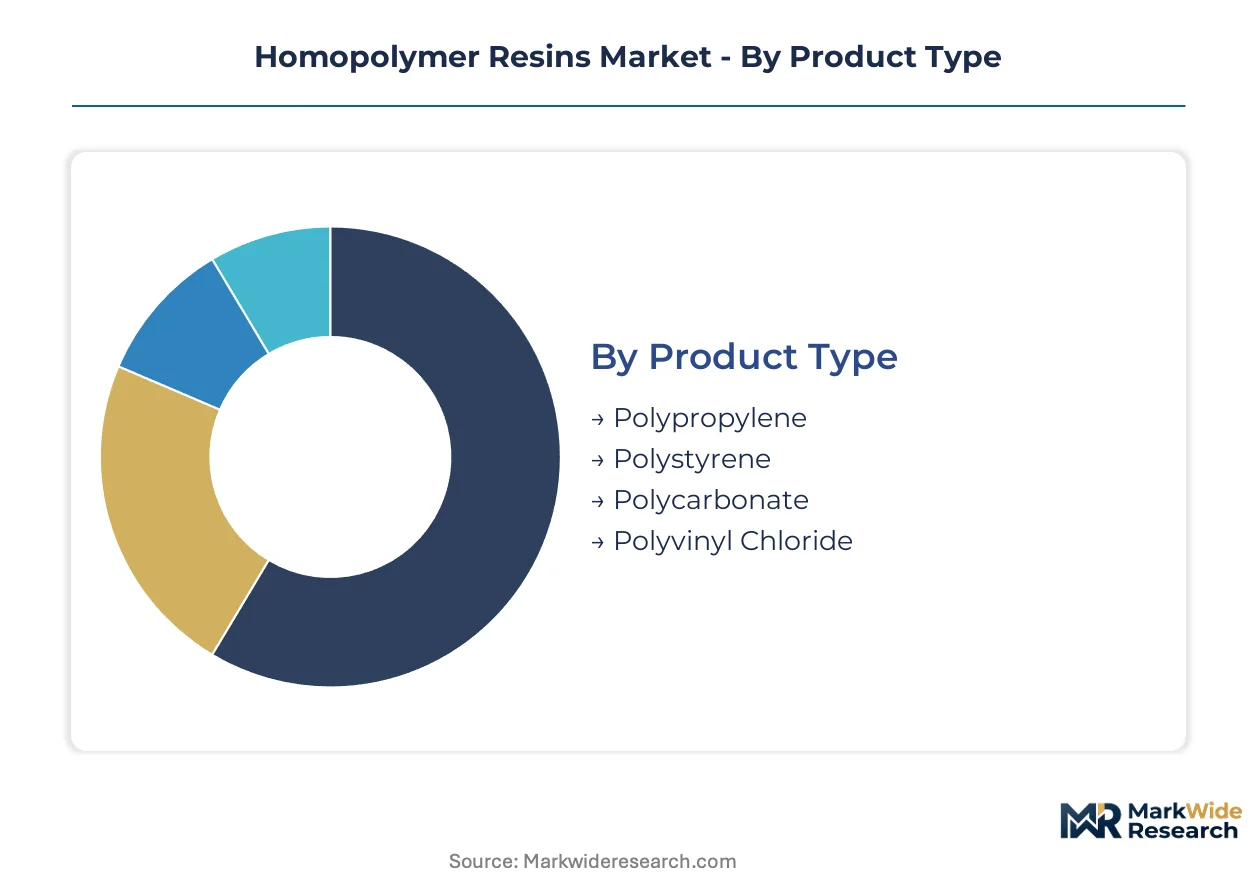
Homopolymer resin procurement cycles vary dramatically by molecular architecture and thermal performance, with commodity grades turning inventory monthly while specialized medical and aerospace certifications lock formulations for years. Understanding these velocity differentials helps producers calibrate catalyst investments against working capital requirements.
Product Type:
Polypropylene commands the shortest specification cycles in automotive supply chains, while polycarbonate qualifications for medical devices extend across multi-year validation protocols.
- Polypropylene:Crystalline thermoplastic with 50-70% crystallinity and melting points near 160°C. Demand concentrates in Zhejiang province injection molding clusters serving automotive underhood components, where REACH-compliant grades with residual monomer below 50 ppm are displacing legacy specifications.
- Polystyrene:Amorphous polymer with glass transition near 100°C, offering clarity and processability in disposable foodservice applications. FDA food-contact notification requirements in the United States are extending qualification timelines for expanded polystyrene alternatives in beverage packaging.
- Polycarbonate:Bisphenol-A derived engineering thermoplastic with optical clarity and heat deflection above 130°C. Medical-grade ISO 10993 certifications for surgical instrument housings command premium pricing tiers in Bavarian and Michigan manufacturing corridors.
- Polyvinyl Chloride:Chlorinated homopolymer with inherent flame resistance and chemical stability. Construction pipe and conduit specifications in Germany and the United States favor rigid PVC grades with enhanced UV stabilization for exterior infrastructure.
Polypropylene dominates installed base. Polycarbonate is where expansion concentrates.
Grade:
Cost tiers separate commodity volumes from specification premiums, with high-temperature grades capturing margin pools that standard grades cannot access.
- Standard:Baseline homopolymer formulations for general-purpose extrusion and injection molding. Packaging converters in Guangdong province source standard polypropylene through direct producer relationships, bypassing traditional distributor markups.
- High-Impact:Rubber-modified grades with enhanced toughness for durable goods applications. Automotive bumper fascia specifications in Stuttgart and Detroit are qualifying metallocene-catalyzed high-impact polypropylene at accelerated timelines.
- Low-Density:Foamed and expanded grades reducing part weight for protective packaging and insulation. Construction applications in the United States specify low-density polystyrene for thermal barrier systems under evolving energy codes.
- High-Temperature:Heat-stabilized formulations with continuous service temperatures exceeding 120°C. Appliance manufacturers in China and Germany are redesigning components for extended thermal cycling, pulling high-temperature polypropylene into motor housings and cooking equipment.
Standard grades anchor volume throughput. High-temperature formulations are climbing the fastest.
Application:
Customer type fragmentation creates divergent service requirements, with automotive molders demanding technical partnership while packaging buyers prioritize logistics efficiency.
- Packaging:Rigid containers, films, and closures for food and beverage supply chains. FDA notification requirements govern polypropylene and polystyrene grades in United States beverage packaging, creating compliance barriers for non-domestic suppliers.
- Automotive:Interior panels, underhood components, and structural parts where stiffness-to-weight ratios prove critical. Tier-one suppliers specify high-crystallinity homopolymer grades for thermal management components in Detroit and Stuttgart assembly plants.
- Consumer Goods:Durable household products and disposable items with cost-sensitive positioning. Direct compounding partnerships between resin producers and injection molders are reshaping procurement patterns in Bavaria and Michigan.
- Electronics:Housings, connectors, and optical media requiring dimensional stability and flame retardance. Polycarbonate segments command margin pools where optical clarity and heat resistance prove critical for device enclosures.
Packaging dominates installed base. Electronics is where expansion concentrates.
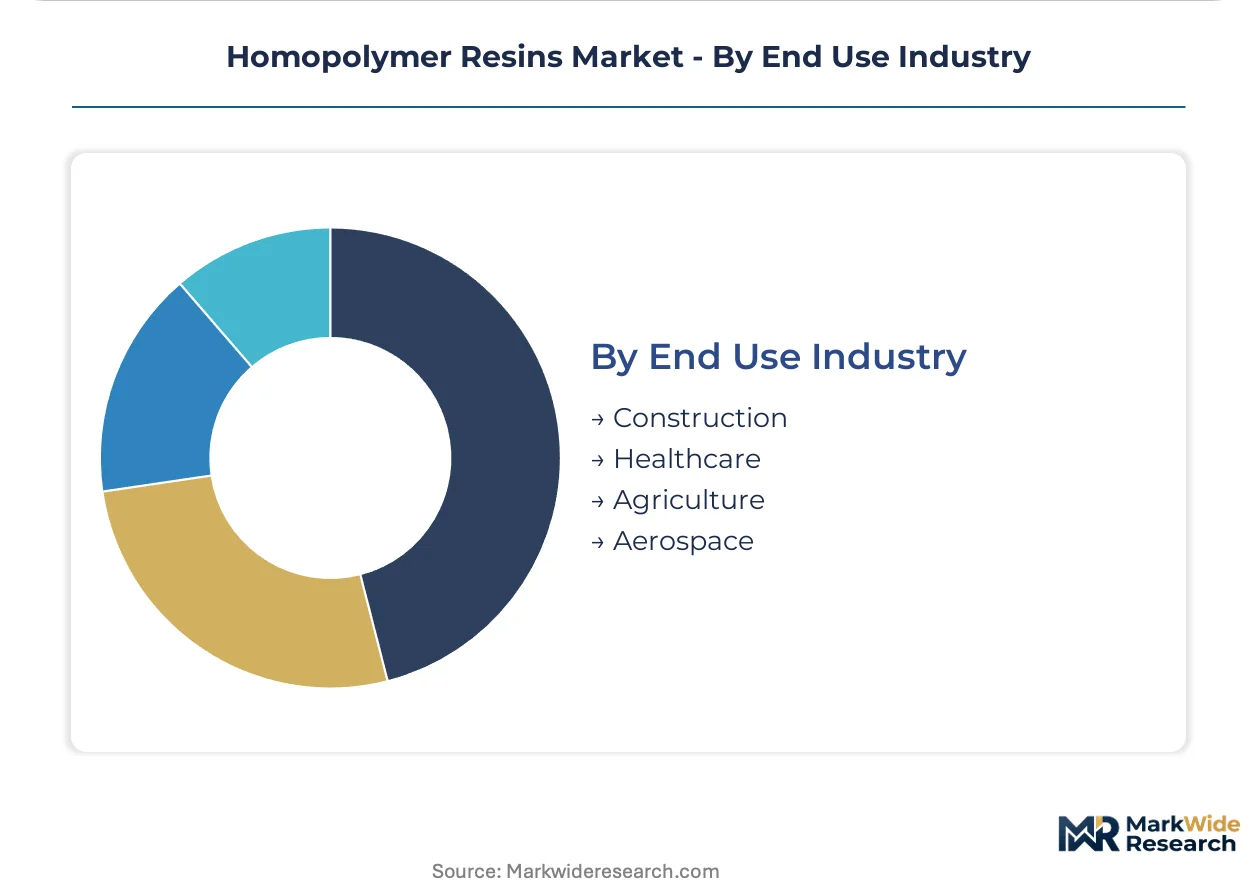
End Use Industry:
Geographic supply concentration aligns with downstream manufacturing gravity, with polymer processing clusters dictating regional procurement flows.
- Construction:Pipe, conduit, siding, and insulation systems with decades-long service life requirements. PVC specifications for exterior infrastructure in Germany and the United States favor enhanced UV stabilization and impact resistance.
- Healthcare:Sterilizable devices, pharmaceutical packaging, and surgical instruments with biocompatibility mandates. USP Class VI certifications for polypropylene surgical instrument housings create premium pricing tiers in medical device manufacturing corridors.
- Agriculture:Greenhouse films, irrigation components, and equipment housings exposed to weathering and chemical exposure. UV-stabilized polypropylene grades serve extended-season greenhouse operations in Shandong province before MEE emissions enforcement idled regional polymerization capacity.
- Aerospace:Interior panels, ducting, and structural components meeting stringent flammability and smoke toxicity standards. Flame-retardant polycarbonate and polyphenylene-based formulations qualify for cabin interior applications under FAA and EASA certification protocols.
Construction dominates installed base. Healthcare is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE enforces stack-emission standards that idle polymerization capacity in Shandong province, while downstream processors in Zhejiang and Guangdong provinces pull import volumes through Ningbo port infrastructure. Residual monomer thresholds below 50 ppm govern trade flows across major manufacturing corridors.
United States
Automotive tier-one suppliers in Detroit specify high-crystallinity homopolymer grades for underhood thermal management components. FDA food-contact notification requirements extend qualification timelines for polypropylene additive packages facing 180-day review cycles. Gulf Coast naphtha-cracker economics transmit propylene price volatility directly into resin cost structures.
Germany
REACH substance restrictions on boron-containing catalyst residues force reformulation of polypropylene polymerization chemistry toward magnesium chloride-supported systems. Bavarian medical device manufacturers demand USP Class VI certified grades for surgical instrument housings. Stuttgart automotive compounders qualify metallocene-catalyzed grades for bumper fascias at accelerated timelines.
China
Downstream polymer processing clusters in Zhejiang and Guangdong provinces concentrate procurement volumes for packaging and automotive applications. MEE emissions enforcement idles regional polymerization capacity in Shandong province for stack-emission noncompliance. Digital procurement platforms in Guangdong enable direct transactions between Foshan molders and Singapore-trading suppliers.
Brazil
Captive feedstock integration at petrochemical complexes provides cost leverage in export markets serving regional compounders. ANVISA biocompatibility standards create compliance pathways for medical-grade resin qualifications. São Paulo-state injection molders source standard grades through direct producer relationships bypassing traditional distributor networks.
Saudi Arabia
Feedstock advantage from associated gas production supports export-oriented polymerization capacity serving Asian and European converters. SABIC anchors regional supply through integrated crackers and derivative units. Red Sea shipping corridors position resin exports for Mediterranean and South Asian manufacturing clusters.
Homopolymer Resins Market Competitive Landscape
Integrated petrochemical majors and regional specialists split the market into distinct capability tiers. Gulf Coast producers leverage scale economies and feedstock access, while European and Asian competitors differentiate through catalyst technology and specification compliance. Three archetypes dominate: integrated oil-to-resin operators with captive feedstock, technology licensors with proprietary catalyst systems, and regional compounders with direct molder relationships. Capacity expansion and direct distribution partnerships constitute the dominant competitive moves reshaping channel structures.
Within the integrated-operator tier, LyondellBasell Industries N.V., ExxonMobil Corporation, and Braskem S.A. exemplify distinct geographic anchoring strategies. LyondellBasell occupies a position representing Gulf Coast manufacturing scale directed toward direct supply of injection molders. ExxonMobil exemplifies the long-term offtake model with automotive tier-one suppliers. Braskem S.A. anchors the feedstock-integrated archetype through Brazilian complex operations serving export markets.
| Leading Market Players |
|---|
| LyondellBasell Industries N.V. |
| Reliance Industries Limited |
| ExxonMobil Corporation |
| INEOS Group Ltd. |
| Braskem S.A. |
| Borealis AG |
| BASF |
| SABIC |
| Formosa Plastics Corporation |
| Others |
Value Network & Pricing Analysis
Zhejiang province polymerization clusters anchor cost structures across Asian homopolymer flows, with Ningbo port throughput dictating regional pricing benchmarks that downstream Guangdong molders reference in direct procurement negotiations.
Pricing Analysis
Gulf Coast-to-Asia price spreads compress during naphtha-cracker turnarounds, while contract-based long-term offtake agreements dominate automotive tier-one relationships. Price differentiation rests on REACH-compliant certification tiers and volume scale commitments from Zhejiang injection molders. Cost compression in standard-grade polypropylene intensifies because metallocene-catalyzed polyethylene captures flexible packaging share. Packaging converters in Guangdong province exhibit highest price sensitivity, while Bavarian medical device manufacturers accept premiums for USP Class VI certified grades.
Supply Chain Analysis
Export-control scrutiny on advanced metallocene catalyst technologies limits technology transfer into certain polymerization complexes, constraining supply elasticity for high-performance grades. Production gravity centers on the United States, China, and Saudi Arabia, with feedstock drawn from Gulf Coast naphtha crackers, Shandong province coal-to-olefins units, and Middle East associated gas streams. Single-source vulnerability concentrates in boron-based catalyst systems facing REACH authorization timelines. Distribution runs through direct producer relationships with large compounders, bypassing traditional distributor networks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Homopolymer resin demand sits in early-cycle expansion as automotive lightweighting protocols penetrate beyond premium vehicle segments into mass-market electric platforms, accelerating specification cycles for high-crystallinity grades.
For Market Incumbents: Entrench catalyst technology leadership through magnesium chloride-supported system investments that eliminate boron tracing ahead of REACH enforcement timelines. Add purification capacity in Zhejiang province to capture downstream cluster procurement volumes. Defend margin pools against polyethylene substitution by qualifying high-temperature grades for appliance motor housings.
For New Entrants and Emerging Players: Establish a beachhead in medical-grade polypropylene certifications where USP Class VI and ISO 10993 standards create defensible premium tiers. Target toll-manufacturing partnerships with Bavarian surgical instrument molders seeking sterilizable resin supply. Pursue direct compounding relationships that bypass entrenched distributor relationships in southern China.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated petrochemical parents seeking to monetize non-core polymerization assets in Europe and Brazil. Five-to-ten year viability hinges on feedstock integration depth and catalyst licensing access. Monitor FDA food-contact notification backlog durations as inflection signal for US market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst System Reformulation | Magnesium chloride-supported systems eliminate boron tracing for REACH compliance in European packaging grades. |
| Direct Compounding Partnership | Toll-manufacturing relationships with Foshan automotive molders bypass distributor markups in Guangdong corridor. |
| Medical-Grade Certification | USP Class VI and ISO 10993 qualifications unlock premium pricing tiers in Bavarian device manufacturing. |
| Backward Integration into Feedstock | Captive propylene supply at Brazilian complexes insulates Braskem from Gulf Coast naphtha price volatility. |
| Post-Consumer Recycled Feedstock | EU Green Deal circular-economy mandates open specification windows for chemically recycled food-contact grades. |
Research Methodology
Initial hypotheses were tested against primary input from polymerization plant managers, automotive tier-one procurement leads, packaging converter technical directors, and medical device regulatory affairs specialists and refined through secondary validation against customs trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and FDA food-contact notification databases. Bottom-up resin demand modeling triangulated against top-down macroeconomic indicators established volume baselines.
Demand-supply balance dynamics across the analysis window shaped the analytical framework, with segmentation across grade tier, end-use industry, application format, and regional production hub informing value projections. CAGRs derived from elasticity-adjusted consumption trajectories incorporated propylene feedstock cost forecasts, catalyst technology adoption curves, and regulatory compliance timeline assumptions specific to REACH and FDA notification pathways.
Macroeconomic conditions sit as an overlay; deviation in naphtha pricing spreads, automotive production schedules, or construction activity indices would shift the trajectory. Material shifts in MEE emissions enforcement intensity or REACH substance restriction timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market