
 Acrylic Paper Market | 2026-2036
Acrylic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Paper Market Outlook
Germany's industrial art materials corridor is rewriting supply dynamics for European acrylic paper distribution. CANSON leverages its heritage papermaking infrastructure to sustain premium positioning across continental Europe. Strathmore anchors North American supply through specialized cotton-blend substrates for heavy-body acrylic applications. Fabriano competes on archival certification standards that differentiate Italian-made sheets in museum-grade segments.
Acrylic paper denotes a heavyweight, textured substrate engineered with acrylic polymer sizing or synthetic fiber reinforcement to withstand water-based acrylic paint absorption without warping or deterioration. The material typically employs acid-free alpha-cellulose or cotton rag bases treated with alkaline buffering agents to maintain pH stability above 7.5 across decades of pigment exposure. Coated Acrylic formulations command the dominant share of current value as artists prioritize controlled absorbency for layered glazing techniques, while Specialty Acrylic grades targeting metallized and iridescent finishes represent the fastest-expanding margin pool among professional buyers. Cast Acrylic substrates occupy the premium tier for plein-air practitioners requiring dimensional stability under humidity variation, whereas Extruded Acrylic lines compete on cost efficiency for educational and hobbyist volume.
EMA chemical safety assessments and REACH substance restrictions govern raw material selection for European acrylic paper manufacturers, while FDA indirect food-contact guidelines shape coating chemistry for U.S.-bound specialty grades. ISO 9706 permanence standards and ASTM D4236 toxicity labeling requirements create compliance thresholds that filter smaller suppliers from archival-certified segments. Stakeholders must monitor evolving PFAS restrictions and bio-based polymer substitutions as regulatory pressure intensifies on petroleum-derived sizing agents.
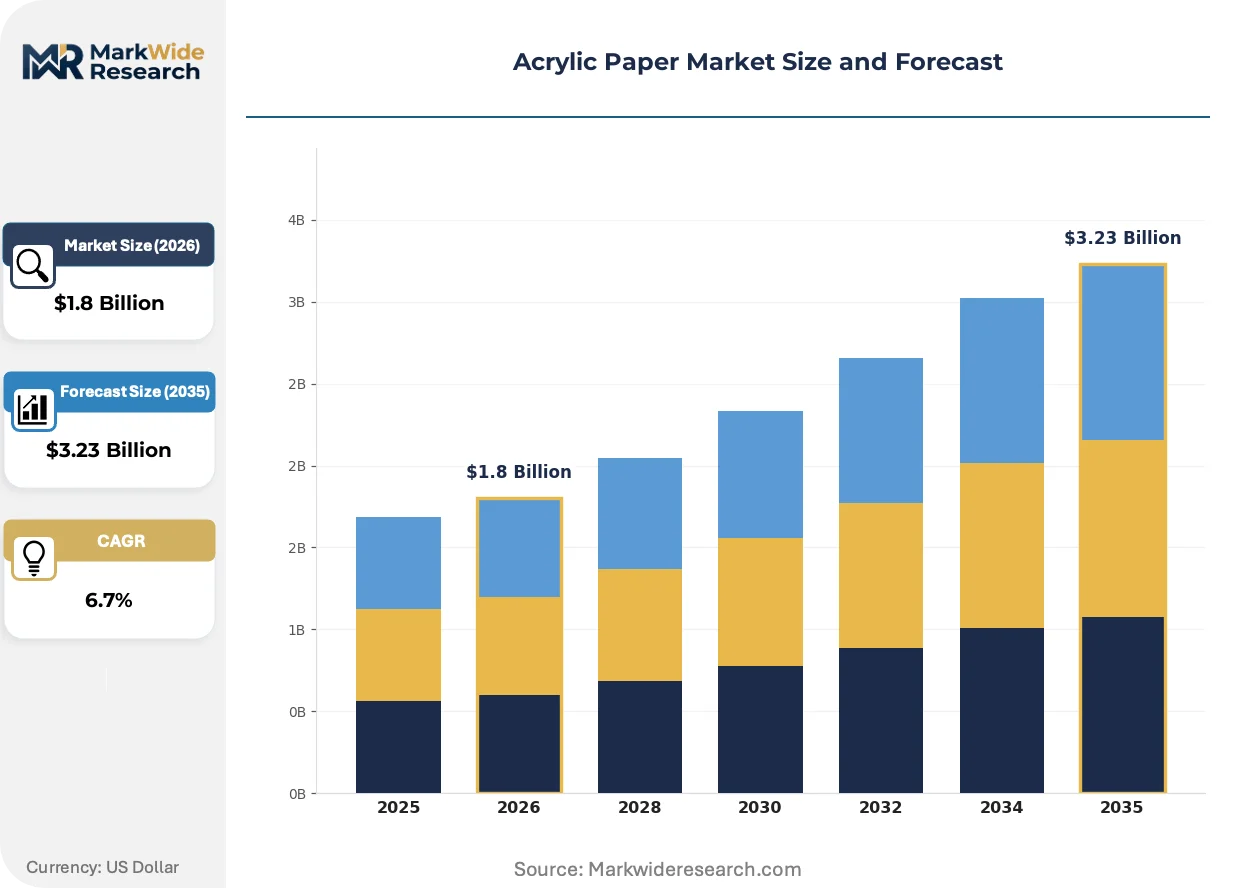
Market Dynamics
REACH substance restrictions and EMA chemical safety assessments are forcing European manufacturers to reformulate acrylic polymer sizing agents, compressing margins for legacy petroleum-based coatings while creating entry points for bio-based alternatives. This regulatory pressure cascades through raw material procurement and archival certification pipelines.
Growth Catalysts
- REACH Compliance Migration:ECHA's evolving PFAS restrictions are accelerating substitution toward bio-derived polymer sizing. German industrial art materials clusters are capturing first-mover advantages in reformulated substrate production.
- Museum-Grade Certification Demand:ISO 9706 permanence standards are becoming mandatory procurement filters for institutional buyers. Italian archival-certified sheets command premium placement in European conservation supply chains.
- Plein-Air Practice Expansion:Cast Acrylic substrates with humidity-stable dimensional properties are displacing traditional canvas for outdoor practitioners. French and Spanish coastal artist colonies are driving specialized substrate volumes.
Market Restraints
- Alpha-Cellulose Input Volatility:Pulp price swings from Nordic suppliers compress margin predictability for mid-tier manufacturers. Cotton rag sourcing faces competing demand from textile and currency paper industries.
- Coating Chemistry Concentration:Specialty acrylic polymer formulation expertise clusters in Germany's Upper Rhine industrial corridor. This geographic concentration creates supply vulnerability for peripheral European converters.
- Digital Surface Substitution:Pressure-sensitive display tablets and stylus-enabled screens are capturing sketch-phase workflows from traditional acrylic paper. Educational institutions are piloting hybrid curriculum models.
Strategic Opportunities
- Eastern European Distribution Gaps:Poland and Czech Republic professional art supply retail networks remain underpenetrated by archival-certified substrate brands. Local logistics partnerships could unlock volume scale.
- Metallized Finish Applications:Specialty Acrylic grades targeting iridescent and metallic pigment compatibility are capturing professional decorative artists. Italian design studios are pioneering mixed-media applications.
- EU Green Deal Alignment:Circular economy action plan incentives favor bio-based polymer development. French papermakers with existing sustainable forestry certifications can access green public procurement channels.
Industry Challenges
- Archival Chemist Talent Scarcity:Formulation expertise combining alkaline buffering with synthetic fiber reinforcement is retiring faster than training pipelines replace it. German technical universities are restructuring materials science curricula.
- Multi-Jurisdiction Labeling Complexity:ASTM D4236 toxicity requirements for U.S. export lots conflict with EU CLP classification systems. Dual-certified production runs require segregated workflow management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Paper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Acrylic, Extruded Acrylic, Coated Acrylic, Specialty Acrylic Application: Advertising Displays, Signage, Furniture, Lighting End User: Retail, Healthcare, Automotive, Construction Thickness: Thin, Medium, Thick, Custom |
| Companies Covered | CANSON, Strathmore, Arteza, U.S. Art Supply, Dick Blick Art Materials, JACKSON'S ART SUPPLIES, Creative Hands Art Materials Pvt Ltd, Ayush Paper, Fabriano, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Paper Market Strategic Shifts
Acrylic paper manufacturing is converging with digital workflow integration and sustainable chemistry substitution. These shifts are compressing traditional supply hierarchies while opening specialized margin pools.
Digital substrate preview technology is virtualizing the traditional sample-based procurement process for institutional buyers. Museum conservation departments and art academies are adopting spectral imaging tools to simulate coating behavior before volume orders. This capability is compressing the role of physical swatch distribution and favoring suppliers with integrated digital asset platforms.
ECHA's expanding PFAS restriction proposals are forcing coating chemistry redesigns across European production facilities. Manufacturers relying on fluorinated sizing agents face reformulation timelines that exceed typical product development cycles. German and Italian archival substrate specialists are accelerating bio-based polymer partnerships to maintain certification continuity.
Professional artists are consolidating purchasing through specialized online supply platforms that bypass traditional brick-and-mortar retailer markups. French and Benelux painter communities are driving this channel migration through social media-facilitated group ordering. Independent art supply stores are responding with private-label substrate partnerships and in-studio technical consultation services.
Acrylic Paper Market Segmentation
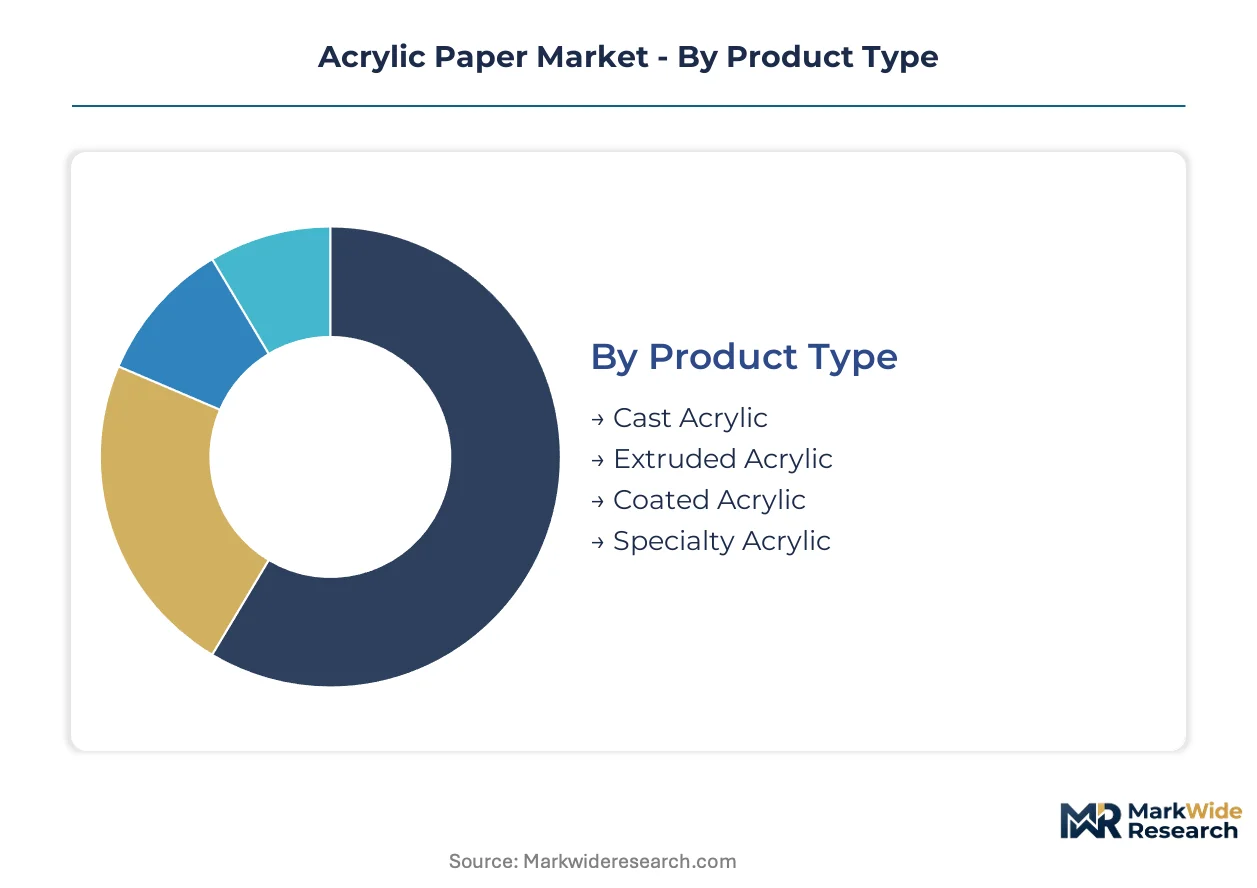
Acrylic paper segmentation reveals divergent production rhythms across substrate grades and thickness profiles. Inventory velocity varies dramatically between commodity extruded lines and specialized cast formulations.
Product Type:
Cast Acrylic substrates command the longest production cycles due to cell-casting polymerization requirements, while Extruded Acrylic lines turn inventory fastest through continuous sheet extrusion.
- Cast Acrylic:Cell-cast polymerization creates molecular chains with superior optical clarity and dimensional stability. Plein-air practitioners in French coastal colonies drive demand for humidity-resistant outdoor substrates.
- Coated Acrylic:Surface-treated substrates with controlled absorbency dominate professional studio workflows. German industrial art materials clusters supply the majority of European coated sheet volumes.
- Extruded Acrylic:Continuous extrusion lines achieve lowest unit costs for educational and hobbyist volume.
- Specialty Acrylic:Metallized and iridescent-compatible grades target decorative mixed-media applications.
Coated Acrylic anchors the volume base while Specialty Acrylic gains share at the steepest rate.
Application:
Application segmentation separates transient promotional use from permanent architectural installation, with advertising displays cycling fastest and furniture applications demanding longest material certification.
- Advertising Displays:Short-horizon promotional graphics prioritize cost efficiency over archival properties. Retail chains in Poland and Czech Republic drive replacement volume.
- Signage:Weather-resistant substrates for outdoor identification systems require UV-stable polymer sizing. Italian archival-certified sheets capture premium exterior monument applications.
- Furniture:Decorative surface laminates and accent panels utilize medium-weight coated grades.
- Lighting:Diffusion-grade substrates with controlled translucency serve LED fixture manufacturers.
Advertising Displays generates the highest shipment frequency while Furniture commands the longest specification timelines.
End User:
End-user segmentation stratifies by procurement sophistication, with healthcare and automotive buyers imposing the most stringent material traceability requirements.
- Retail:Point-of-sale graphics and seasonal promotional materials drive predictable repeat purchasing. Professional art supply retailers in Germany's industrial corridor consolidate volume through specialized distribution.
- Healthcare:Clinical environment graphics require antimicrobial coating compatibility and clean-surface certification. EMA chemical safety assessments filter supplier qualification.
- Automotive:Interior trim and display applications demand dimensional stability across temperature variation.
- Construction:Architectural accent panels and decorative surfacing utilize heavy-body substrate grades.
Retail channels move the highest unit volumes while Healthcare imposes the most restrictive qualification barriers.
Thickness:
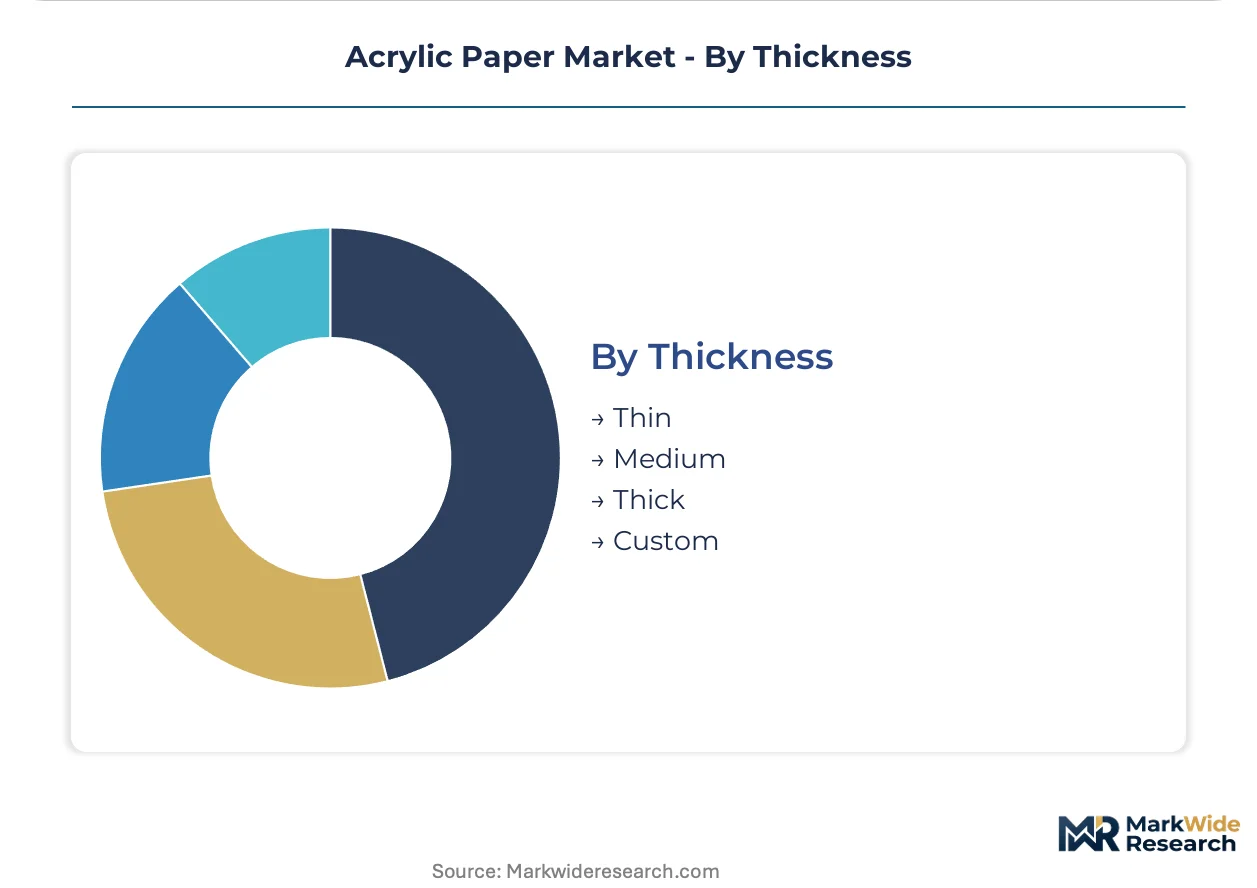
Thickness profiles correlate directly with application durability requirements, with custom specifications extending lead times through specialized slitting and surface treatment.
- Thick:Heavy-body substrates withstand aggressive layering and palette-knife techniques. Museum conservation departments specify thick grades for permanent collection mounting.
- Medium:Versatile weight class balances portability with structural integrity for studio practice.
- Thin:Lightweight sheets suit sketchbook inserts and travel portfolios.
- Custom:Non-standard calipers serve specialized industrial and fine-art fabrication.
Medium thickness dominates standard stock keeping units while Custom specifications expand most quickly among professional fabricators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial art materials clusters concentrate European acrylic paper supply, while North American and Asian demand centers operate through distinct procurement channels. REACH compliance migration and museum-grade certification requirements differentiate competitive positioning across major national markets.
Germany
Professional art supply retailers and institutional conservation departments drive premium substrate demand. ECHA's evolving PFAS restrictions accelerate bio-based polymer sizing reformulation timelines. The Upper Rhine industrial corridor hosts concentrated coating chemistry expertise for archival-certified production.
United States
Heavy-body acrylic practitioners and educational institutions generate volume demand across coated and extruded grades. FDA indirect food-contact guidelines shape specialty coating chemistry for domestic-bound production. Pacific Northwest pulp suppliers feed alpha-cellulose inputs to mid-tier converters.
Italy
Museum conservation supply chains and decorative mixed-media artists prioritize archival certification standards. EU Green Deal circular economy incentives favor papermakers with sustainable forestry credentials. Fabriano's heritage infrastructure anchors premium Italian substrate manufacturing.
France
Plein-air practitioner colonies along coastal regions drive humidity-stable cast acrylic demand. ANSM chemical safety assessments filter healthcare graphics applications. CANSON leverages centuries-old papermaking heritage for continental European distribution.
United Kingdom
Professional artist communities and art academy procurement departments consolidate purchasing through specialized platforms. CLP classification systems create labeling complexity for dual-export production runs. London-based conservation studios specify ISO 9706-certified sheets for permanent collection mounting.
Acrylic Paper Market Competitive Environment
Heritage papermakers and specialized art supply distributors split the market between premium archival positioning and volume accessibility. The vendor base clusters around three strategic archetypes: European heritage manufacturers with centuries-old infrastructure, North American cotton-blend specialists, and agile private-label distributors serving price-sensitive educational segments. Dominant competitive moves include bio-based coating reformulation partnerships and digital substrate preview platform integration.
Among heritage European manufacturers, CANSON and Fabriano exemplify archival-certified premium positioning through sustained papermaking infrastructure investment. Strathmore occupies a position within the North American specialist tier, representing cotton-blend substrate expertise for heavy-body acrylic applications. These three anchors illustrate how geographic papermaking heritage translates into differentiated competitive moats across certification-dependent procurement channels.
| Leading Market Players |
|---|
| CANSON |
| Strathmore |
| Arteza |
| U.S. Art Supply |
| Dick Blick Art Materials |
| JACKSON'S ART SUPPLIES |
| Creative Hands Art Materials Pvt Ltd |
| Ayush Paper |
| Fabriano |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions on PFAS and petroleum-derived sizing agents compress margin predictability while forcing tiered pricing separation between reformulated bio-based grades and legacy formulations. This regulatory chokepoint determines both the premium commanded by German and Italian archival-certified producers and the geographic clustering of coating chemistry expertise.
Pricing Analysis
REACH compliance migration dictates the pricing tier structure across European acrylic paper markets. Three-tier pricing structure across premium, standard, and economy levels separates Italian ISO 9706-certified museum grades from mid-tier coated sheets and volume extruded lines. Price differentiation hinges on archival certification level and volume scale, with educational institutions driving softness in economy tiers while conservation departments absorb premium markups. Cost compression in mid-tier segments is intensifying because Nordic alpha-cellulose pulp volatility feeds directly into converter margins.
Supply Chain Analysis
Extended payment terms from German industrial art materials clusters anchor working capital dynamics for downstream converters. Supply concentrates in Germany, Italy, and France for archival-grade production, with Nordic pulp mills feeding alpha-cellulose inputs and specialty polymer formulators in the Upper Rhine corridor providing sizing chemistry. Raw material dependencies rest on cotton rag sourcing, synthetic fiber reinforcement, and bio-based polymer substitutes. Single-source vulnerability sits with fluorinated sizing agent suppliers facing ECHA phase-out timelines. Distribution runs through professional art supply retailers and specialized online platforms bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic paper markets fragment across certification tiers, creating white-space openings as digital workflow integration and sustainable chemistry mandates splinter procurement channels.
For Market Incumbents: Harden archival certification moats through accelerated ISO 9706 compliance investments before ECHA's expanded PFAS restrictions take full effect. Secure backward integration into bio-based polymer sizing supply through partnerships with German technical universities restructuring materials science curricula. Channel control over professional art supply retailers in underpenetrated Eastern European markets provides defensive depth against private-label distributors. For New Entrants and Emerging Players: Establish a beachhead in Poland and Czech Republic professional art supply networks where archival-certified substrate brands remain scarce. Local logistics partnerships unlock volume scale before heritage European manufacturers extend distribution. A metallized and iridescent finish specialty positioning targets Italian design studios pioneering mixed-media applications, bypassing saturated coated acrylic volume competition. For Investors and Strategic Acquirers: ECHA's evolving PFAS restriction timeline reshapes the acquisition landscape toward bio-based polymer formulation capabilities. Five-to-ten-year viability favors targets with existing sustainable forestry certifications aligned to EU Green Deal circular economy incentives. Watch for bio-based sizing agent partnerships announced by French papermakers as the inflection signal for green public procurement channel access.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Polymer Partnership | Secures coating chemistry continuity under REACH substance restrictions for archival-certified production. |
| Eastern European Distribution Expansion | Captures volume scale in Poland and Czech Republic professional art supply networks before incumbent extension. |
| Digital Substrate Preview Platform | Compresses physical swatch distribution costs for museum conservation departments and art academies. |
| Archival Certification Investment | ISO 9706 permanence standards filter smaller suppliers from institutional procurement channels. |
| Specialty Acrylic Grade Development | Metallized and iridescent-compatible substrates capture margin pools among decorative mixed-media artists. |
Study Parameters
A standing panel of art materials procurement managers, museum conservation department heads, coating chemistry R&D directors, and professional art supply retail buyers provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with archival substrate manufacturers and downstream institutional buyers, validated against customs trade data, SEC filings from publicly listed art supply distributors, ECHA regulatory submission databases, and ISO certification registries. Bottom-up volume triangulation across thickness grades and application segments converged with top-down value estimates derived from regional production cluster analysis.
Scenario-bracketing around regulatory implementation timelines, pulp price volatility bands, and digital substitution rates bounded the projection horizon. Segmentation dimensions modeled include substrate type, thickness profile, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from spline-fitted growth curves anchored to disclosed capacity expansions and conservation department budget trajectories. Industry-specific inputs incorporated ECHA PFAS restriction phase-out schedules and museum-grade certification adoption curves.
Stress conditions across Nordic pulp supply disruptions, ECHA enforcement intensity variations, and digital tablet penetration in educational curricula were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and institutional procurement cycle stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Paper Goods Market
Paper Products
Overlay Paper Market
Paper Products
Global Dye Sublimation Paper Market
Paper Products
Fluff Pulp Market
Paper Products
Paper Core Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Base Paper Market
Paper Products
Europe Coated Paper Market
Paper Products
Chemical Cellulose Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Household Paper Market
Paper Products
Duplex Paper and Board Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Billing Paper Market
Paper Products
Synthetic Paper Market
Paper Products
Latex-Saturated Paper Market