
 South-East Asia Low-Density Polyethylene (LDPE) Market | 2026-2036
South-East Asia Low-Density Polyethylene (LDPE) Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia Low-Density Polyethylene (LDPE) Market Analytics
Flexible food packaging is realigning South-East Asia LDPE consumption patterns as e-commerce fulfillment and processed food exports expand. Dow leverages its Gulf Coast technology licensing to sustain high-pressure tubular reactor output across Thai joint ventures. PTT Global Chemical anchors domestic supply through its Map Ta Phut integrated complex, while PT Lotte Chemical Titan Tbk competes on film-grade specialization for Indonesian flexible packaging converters.
Low-density polyethylene is a branched thermoplastic polymer produced via high-pressure free-radical polymerization, typically exhibiting density between 0.910 and 0.940 g/cm³ and melt index ranges suited for extrusion coating and blown film applications. Film Grade LDPE dominates volume flows across the region, serving moisture-barrier layers in multilayer food packaging structures. Injection Grade applications occupy narrower but higher-margin positions in pharmaceutical closures and precision consumer goods, where lot consistency and low warpage specifications command premium positioning against linear low-density substitutes.
Thailand's Department of Industrial Works, Indonesia's Ministry of Environment and Forestry, and Vietnam's Ministry of Natural Resources and Environment each enforce evolving plastic waste management frameworks that reshape virgin resin demand curves and mechanical recycling feedstock economics. REACH-aligned substance restrictions transmitted through EU-ASEAN trade corridors additionally constrain additive packages in export-oriented film formulations. Stakeholders must monitor regulatory divergence between domestic circular economy targets and import-market compliance obligations to calibrate resin specifications and recycling infrastructure commitments.
Market Dynamics
Flexible food packaging specifications from Indonesia's sustainable packaging mandates and Thailand's BIS-aligned polymer standards are compressing virgin resin demand curves while redirecting capital toward mechanical recycling infrastructure and film-grade reformulation capabilities.
Growth Catalysts
- Indonesia's sustainable packaging mandates:Mandatory recycled content thresholds for flexible food packaging are pulling film-grade LDPE through Indonesian converting operations at elevated specification tiers.
- Thailand's Eastern Economic Corridor petrochemical cluster:Integrated high-pressure tubular reactor capacity anchors regional supply security for export-oriented multilayer film producers serving ASEAN processed food markets.
- E-commerce fulfillment expansion:Moisture-barrier pouch demand from cross-border retail logistics is accelerating blown film consumption across Vietnam and Philippines distribution centers.
Market Restraints
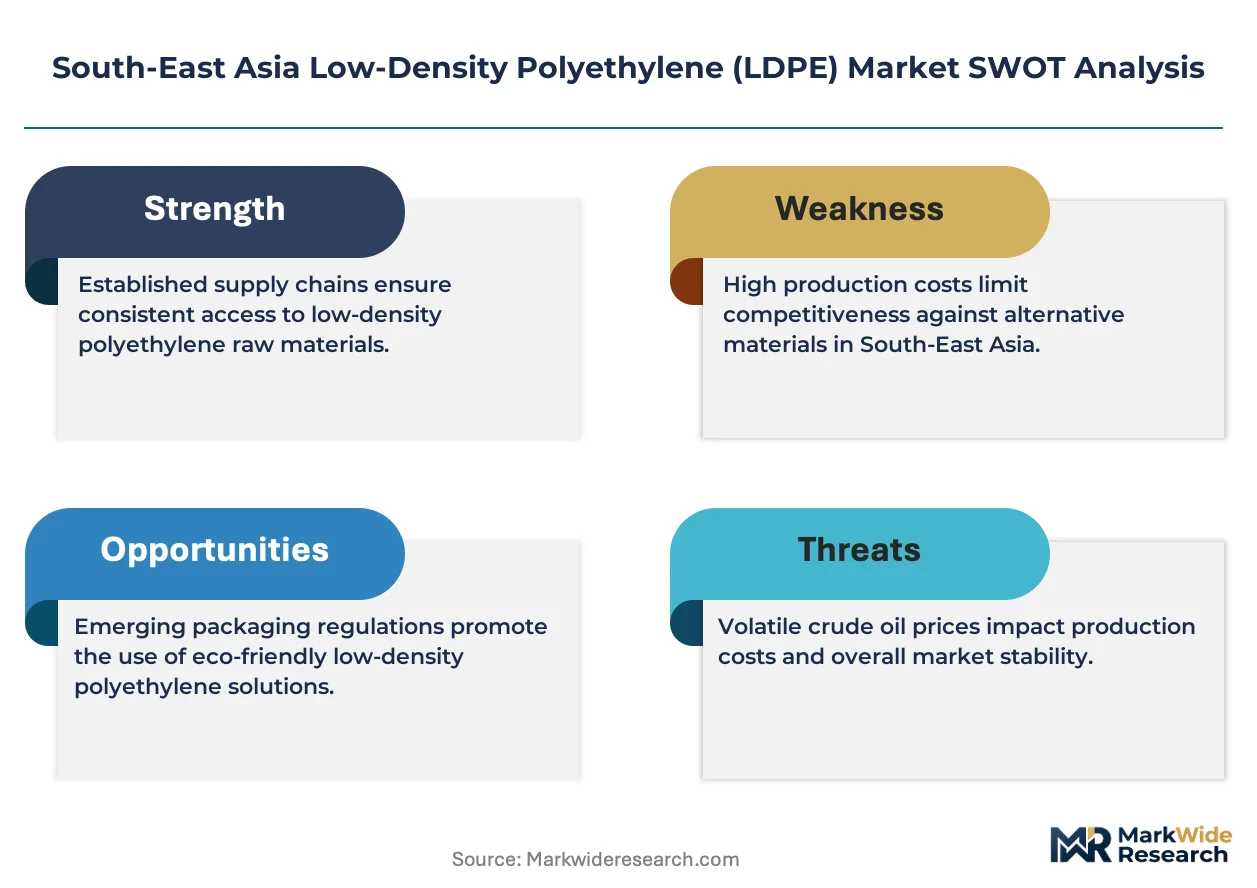
- Naphtha feedstock volatility:Crude-linked input costs for high-pressure free-radical polymerization compress margin stability for non-integrated Thai and Indonesian producers lacking upstream olefin control.
- Linear low-density polyethylene substitution:LLDPE puncture resistance advantages in downgauged stretch film applications are displacing LDPE in secondary packaging layers across Malaysian logistics networks.
- REACH-aligned additive restrictions:EU-ASEAN trade corridor compliance obligations constrain slip agent and antioxidant packages in export film formulations, raising reformulation costs for Indonesian converters.
Strategic Opportunities
- Vietnam mechanical recycling infrastructure:Underdeveloped post-industrial film collection and reprocessing capacity creates first-mover positioning for integrated resin-to-recycle operators in Ho Chi Minh City industrial zones.
- Pharmaceutical closure injection grades:Low warpage specifications for precision pharmaceutical packaging represent uncaptured premium positioning against polypropylene incumbents in Thailand's medical device export sector.
- Biodegradable film additive convergence:Oxo-biodegradable masterbatch integration with conventional LDPE extrusion lines offers compliance pathway for Indonesia's 2025 single-use plastic reduction targets.
Industry Challenges
- High-pressure reactor technician scarcity:Specialized free-radical polymerization process engineering expertise concentrates in Map Ta Phut and Cilegon clusters, constraining brownfield expansion timelines across emerging Vietnamese production sites.
- Multilayer film certification complexity:Food contact compliance documentation for coextruded structures with seven-plus layers extends qualification cycles for Indonesian converters supplying EU retail chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia Low-Density Polyethylene (LDPE) Market |
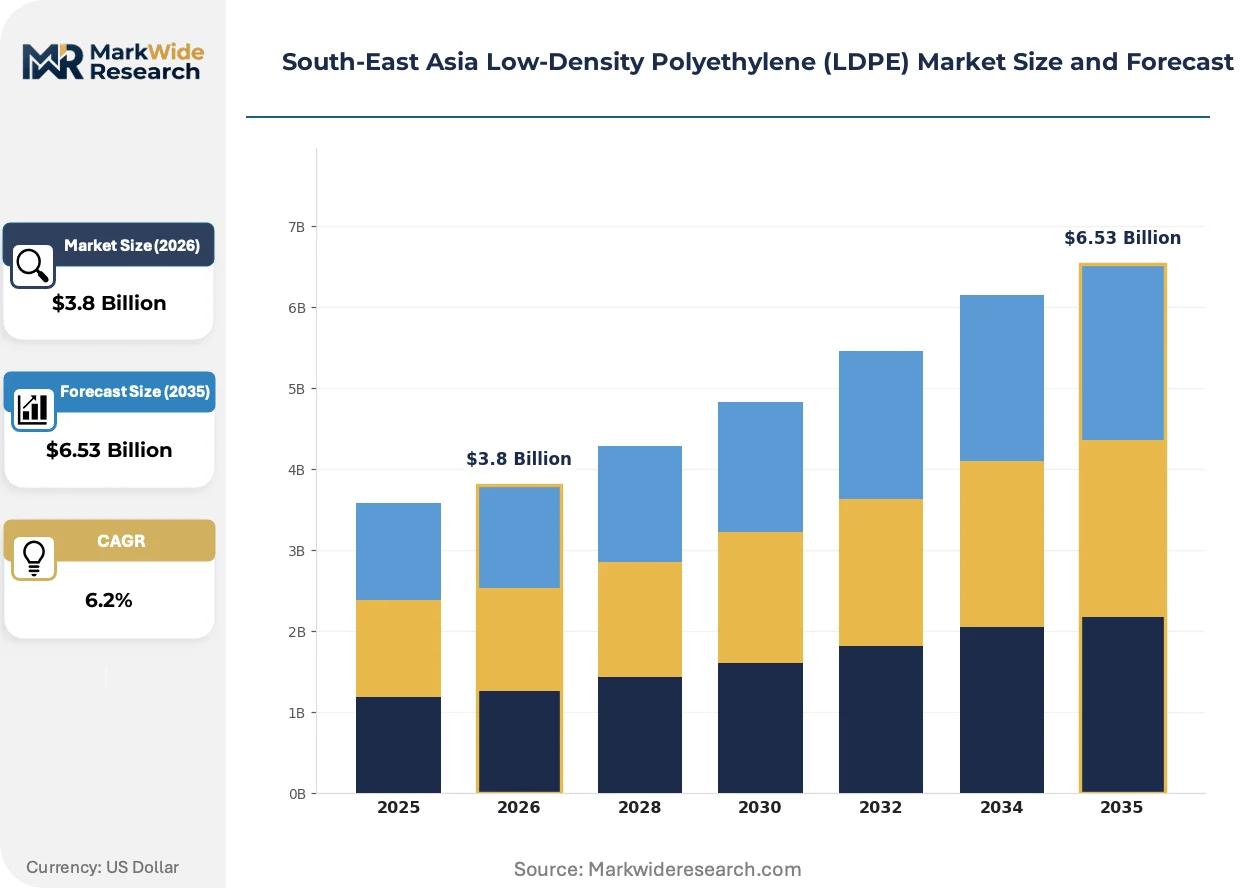
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Grade, Injection Grade, Blown Grade, Coating Grade Application: Packaging, Agriculture, Consumer Goods, Electrical End User: Food Industry, Pharmaceutical, Textile, Construction Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Dow, Chevron Phillips Chemical Company LLC, Formosa Plastics Corporation, PTT Global Chemical Public Company Limited, TORAY INDUSTRIES, INC., China Petrochemical Corporation, LG Chem, Mitsui Chemicals, Inc., PT Lotte Chemical Titan Tbk, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia Low-Density Polyethylene (LDPE) Market Evolving Landscape
Digital printing integration on flexible packaging lines and regulatory pressure on virgin resin specifications are compressing traditional film production cycles while elevating technical service requirements across Thai and Indonesian converter relationships.
Metallocene-catalyzed polyethylene is integrating controlled branching architecture into film-grade formulations, enabling downgauged moisture barriers without sacrificing heat seal integrity. Indonesian flexible packaging converters serving instant noodle and snack exporters are adopting these resins at accelerated qualification pace. The technology is integrating premium positioning into previously commoditized blown film segments across ASEAN food manufacturing corridors.
Thailand's Department of Industrial Works has tightened industrial effluent standards for petrochemical complexes operating in Rayong Province, mandating closed-loop cooling water systems and volatile organic compound capture upgrades. These requirements are elevating capital intensity for high-pressure tubular reactor maintenance and turnaround scheduling. Film-grade producers in the Eastern Economic Corridor are responding by consolidating polymerization train operations to minimize regulatory exposure windows.
Brand-owner sustainability scorecards now dominate resin selection protocols for multinational food companies sourcing from ASEAN co-packers, replacing traditional price-tonnage procurement frameworks. Vietnamese and Malaysian converters serving Nestlé, Unilever, and Mondelez procurement desks must document mass balance certification and recycled content traceability. This behavioral pivot is most visible in Thailand's Chonburi province, where integrated resin-to-film operations have restructured sales organizations around technical account management rather than commodity trading desks.
South-East Asia Low-Density Polyethylene (LDPE) Market Segmentation
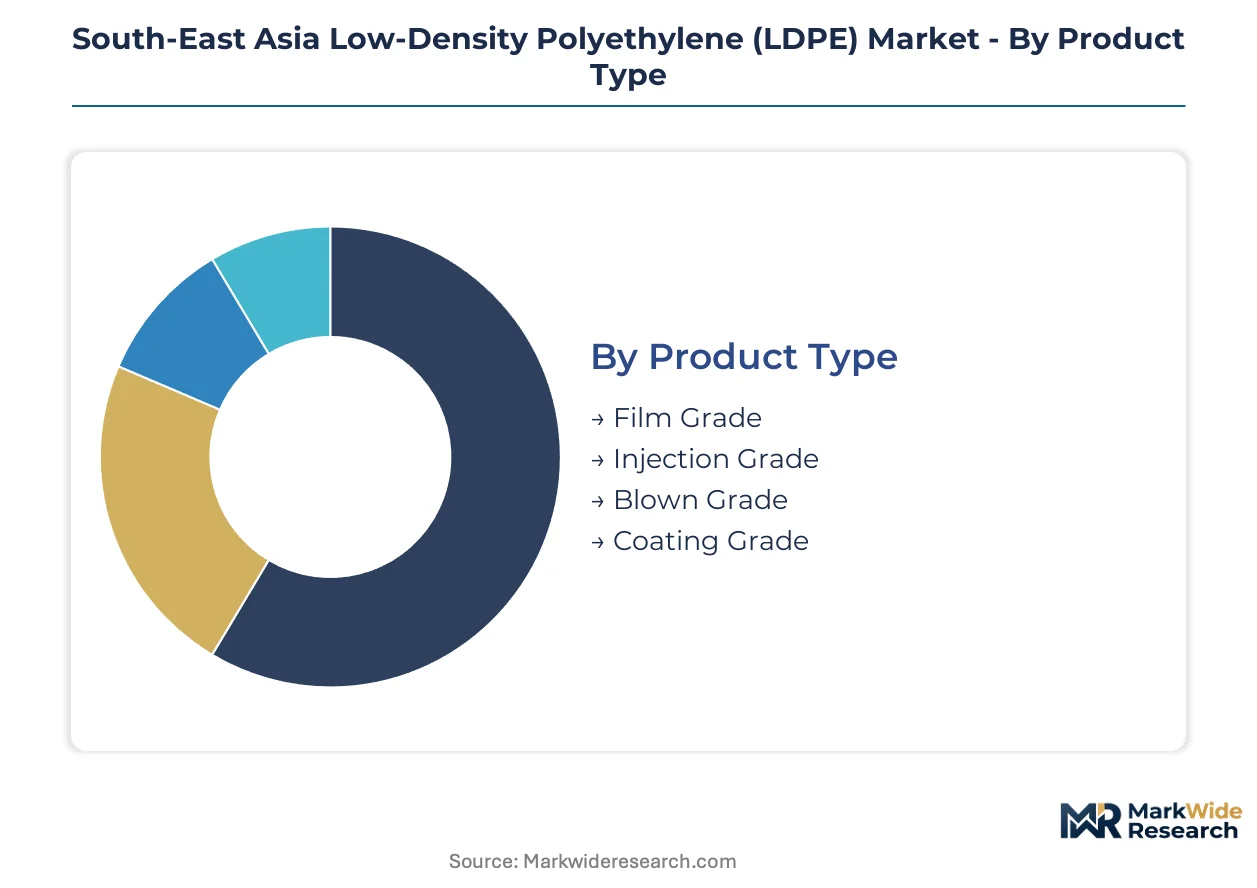
LDPE segmentation in South-East Asia tracks divergent specification requirements across food contact compliance tiers and processing technology clusters. Procurement patterns split between integrated petrochemical buyers seeking bulk film-grade volumes and specialized converters demanding injection-grade consistency for pharmaceutical applications.
Product Type:
Film Grade operates as the embedded backbone of regional supply chains, while Injection Grade commands standalone premium positioning through precision specifications.
- Film Grade:Branched thermoplastic polymer with density ranging 0.910-0.940 g/cm³ and melt index optimized for blown film extrusion. Demand concentrates in Thailand's Eastern Economic Corridor multilayer packaging producers serving ASEAN processed food exports, where moisture-barrier specifications are tightening under Indonesia's sustainable packaging mandates.
- Injection Grade:Narrower molecular weight distribution delivers low warpage and lot consistency for precision molding. Pharmaceutical closure manufacturers in Thailand's medical device export corridor specify these resins for regulatory documentation requirements, creating defensive positioning against polypropylene substitution.
- Blown Grade:Optimized bubble stability for agricultural film and industrial liner applications across Vietnamese delta farming zones.
- Coating Grade:Extrusion coating formulations for paperboard lamination in Indonesian instant noodle packaging supply chains.
Film Grade leads volumes today; Injection Grade is gaining share fastest through pharmaceutical specification premiums.
Application:
Application segmentation reflects cost-tier stratification between commodity packaging volumes and specialized electrical insulation margins.
- Packaging:Flexible food packaging dominates value flows, with moisture-barrier multilayer structures serving e-commerce fulfillment expansion across Vietnam and Philippines distribution networks. Regulatory pressure on virgin resin content is compressing traditional procurement cycles.
- Agriculture:Greenhouse films and mulching sheets for Indonesian palm oil nursery operations and Vietnamese rice cultivation corridors.
- Consumer Goods:Precision injection-molded components for household durables in Malaysian manufacturing zones.
- Electrical:Cable jacketing and wire insulation for Thailand's electronics assembly export sector.
Packaging absorbs the dominant volume share; Agriculture is expanding most quickly through climate-adaptive cultivation investments.
End User:
End user concentration follows customer-type stratification between multinational brand-owner procurement desks and fragmented domestic converter operations.
- Food Industry:Instant noodle, snack, and processed seafood exporters drive film-grade qualification pace. Nestlé, Unilever, and Mondelez sustainability scorecards now mandate mass balance certification and recycled content traceability, restructuring sales relationships around technical account management rather than commodity trading.
- Pharmaceutical:Precision closure and primary packaging specifications for Thailand's FDA-aligned medical device export regulations.
- Textile:Fiber coating and nonwoven applications for Indonesian garment manufacturing clusters.
- Construction:Vapor barriers and geomembranes for Malaysian infrastructure development corridors.
Food Industry anchors current demand; Pharmaceutical is climbing the fastest through regulatory documentation premiums.
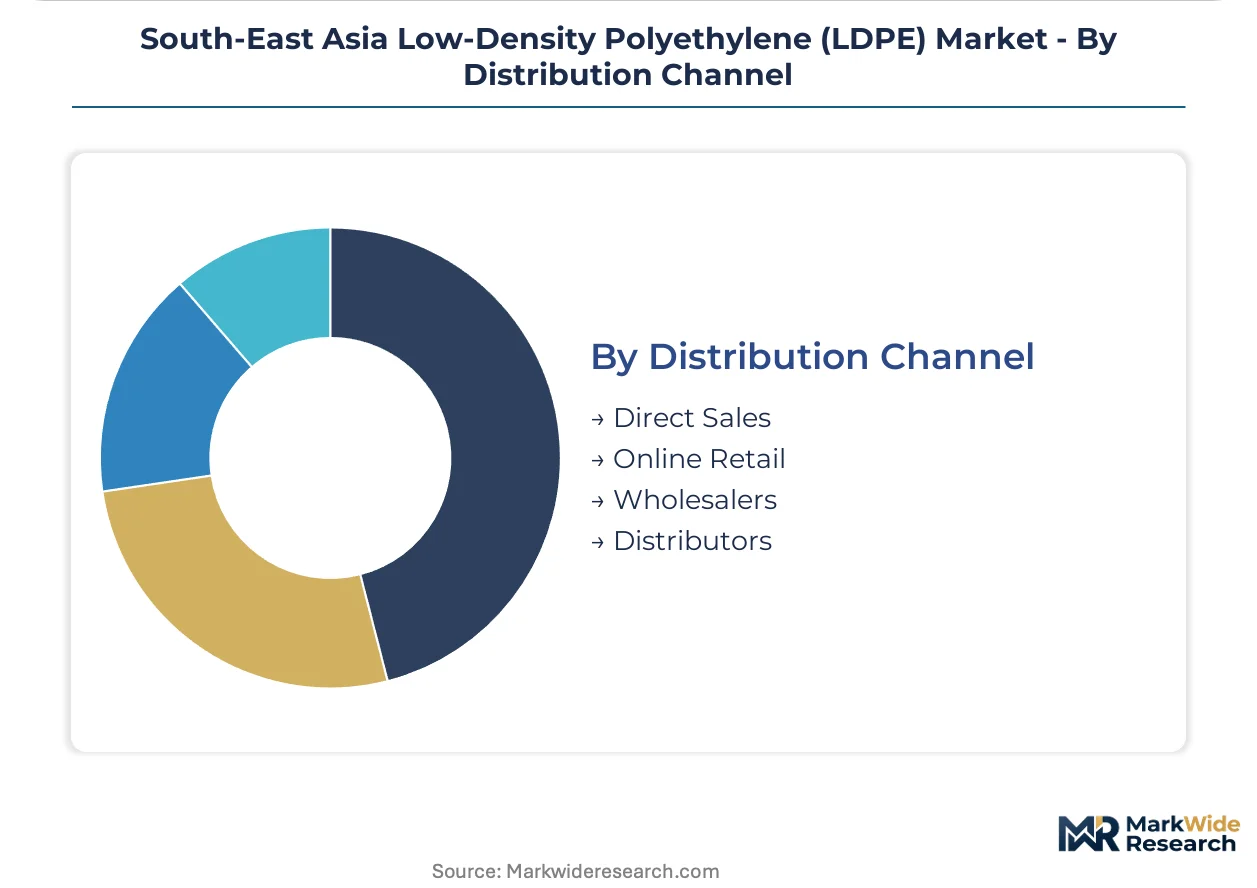
Distribution Channel:
Channel segmentation maps supply concentration against geographic reach requirements, with direct sales dominating integrated converter relationships.
- Direct Sales:Long-term offtake agreements between Map Ta Phut petrochemical complexes and Thai flexible packaging converters. Technical service integration and specification co-development lock in volume commitments across multilayer film qualification cycles.
- Distributors:Regional resin traders serving fragmented Indonesian and Vietnamese converter bases lacking integrated procurement scale.
- Wholesalers:Bulk volume aggregation for agricultural film compounders in Philippine provincial markets.
- Online Retail:Emerging digital procurement platforms for small-batch specialty grade sampling and rapid qualification.
Direct Sales commands the volume lead; Distributors are gaining share fastest through Indonesian converter fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting LDPE production toward jurisdictions with lower compliance costs and integrated feedstock positions. Thailand's Eastern Economic Corridor captures investment flows as Indonesia's sustainable packaging mandates tighten material specifications and elevate reformulation expenses.
Thailand
Map Ta Phut's petrochemical cluster anchors regional supply security through integrated high-pressure tubular reactor capacity. The Department of Industrial Works enforces tightened industrial effluent standards mandating closed-loop cooling water systems across Rayong Province complexes. Dow and PTT Global Chemical operations in the Eastern Economic Corridor consolidate polymerization train scheduling to minimize regulatory exposure windows.
Indonesia
Flexible food packaging exporters drive film-grade qualification pace for instant noodle and snack supply chains. The Ministry of Environment and Forestry mandates recycled content thresholds for flexible food packaging, compressing virgin resin demand curves. Cilegon-based operations face elevated specification tiers as converters serving Nestlé and Unilever procurement desks document mass balance certification.
Vietnam
E-commerce fulfillment expansion accelerates moisture-barrier pouch demand across Ho Chi Minh City distribution networks. The Ministry of Natural Resources and Environment enforces evolving plastic waste management frameworks that reshape virgin resin demand curves. Underdeveloped post-industrial film collection capacity in southern industrial zones creates positioning opportunities for integrated resin-to-recycle operators.
Malaysia
LLDPE substitution pressures displace LDPE in downgauged stretch film applications across logistics networks. BIS-aligned polymer standards tighten material specifications for domestic converters. Penang and Selangor manufacturing corridors concentrate precision injection-molding operations serving electrical insulation and consumer goods segments.
Philippines
Agricultural film consumption concentrates in provincial farming zones for greenhouse and mulching applications. Fragmented converter bases rely on regional resin traders lacking integrated procurement scale. Bulk volume aggregation through wholesale channels serves agricultural compounders outside metropolitan procurement networks.
South-East Asia Low-Density Polyethylene (LDPE) Market Competitive Landscape
Capacity expansion dominates the current landscape as producers consolidate polymerization train operations to capture scale efficiencies. The vendor base clusters around three archetypes: integrated petrochemical majors with captive olefin supply, regional film-grade specialists serving flexible packaging converters, and technology licensors leveraging Gulf Coast process expertise. Strategic partnerships and portfolio diversification represent the dominant competitive moves as players navigate regulatory divergence between domestic circular economy targets and export-market compliance obligations.
Among integrated Thai operators, PTT Global Chemical anchors domestic supply through its Map Ta Phut complex, while PT Lotte Chemical Titan Tbk occupies a specialist position in Indonesian film-grade markets. Dow exemplifies the technology-licensing archetype through its sustained high-pressure tubular reactor output across Thai joint ventures. These three entities represent distinct strategic postures: captive feedstock integration, regional converter proximity, and proprietary process technology transfer.
| Leading Market Players |
|---|
| Dow |
| Chevron Phillips Chemical Company LLC |
| Formosa Plastics Corporation |
| PTT Global Chemical Public Company Limited |
| TORAY INDUSTRIES, INC. |
| China Petrochemical Corporation |
| LG Chem |
| Mitsui Chemicals, Inc. |
| PT Lotte Chemical Titan Tbk |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers across Thailand's Eastern Economic Corridor anchor supply discipline through captive naphtha positions, translating feedstock cost advantages into pricing power over non-integrated Indonesian and Vietnamese converters. Long-term offtake structures between Map Ta Phut complexes and flexible packaging majors compress spot market volatility while elevating contract negotiation leverage for film-grade volumes.
Pricing Analysis
Distributor margins in Indonesian provincial markets absorb 8-12 percentage points above direct sales channels serving Thai integrated converters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with REACH-aligned additive packages commanding 15-20% premiums over domestic formulations. Cost compression in standard film grades intensifies as LLDPE substitution accelerates across Malaysian logistics stretch applications. Small-batch Indonesian converters exhibit highest price sensitivity due to fragmented procurement scale, while pharmaceutical injection-grade buyers prioritize lot consistency over unit economics.
Supply Chain Analysis
Food contact compliance documentation for multilayer structures gates supplier qualification cycles, extending onboarding timelines for Indonesian converters serving EU retail chains. Supply concentrates in Thailand, Indonesia, and Vietnam, with Thailand's Map Ta Phut and Indonesia's Cilegon clusters anchoring high-pressure tubular reactor capacity. Naphtha feedstock draws from Middle Eastern and regional refinery streams, with polymerization catalysts and additive masterbatches sourced from Japanese and European specialty chemical producers. Single-source vulnerability concentrates in metallocene catalyst supply for advanced film grades. Distribution runs through direct sales agreements for integrated Thai converters and regional distributor networks for fragmented Indonesian and Vietnamese buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South-East Asia LDPE functions as a stable compounder anchored by processed food export demand and regulatory-mandated packaging reformulation cycles. E-commerce fulfillment expansion and sustainable packaging mandates generate predictable volume growth without speculative technology disruption.
For Market Incumbents: Hedge naphtha cost exposure through backward integration into olefin production or long-term feedstock hedging instruments. Consolidate polymerization train operations in Rayong Province to minimize Department of Industrial Works regulatory exposure windows. Prioritize mechanical recycling infrastructure investments to capture Indonesian recycled content mandate premiums before competitor capacity materializes.
For New Entrants and Emerging Players: Indonesia's sustainable packaging mandates open a window for integrated resin-to-recycle operators in Ho Chi Minh City industrial zones where post-industrial film collection capacity remains underdeveloped. Target pharmaceutical injection-grade specialization in Thailand's medical device export corridor, where low warpage specifications command defensive positioning against polypropylene substitution. Pursue technical account management relationships rather than commodity trading desk approaches to secure multinational brand-owner procurement desk access.
For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated Indonesian converters lacking film-grade reformulation capabilities but holding established Nestlé and Unilever supply relationships. Five-to-ten-year viability hinges on mechanical recycling infrastructure execution and metallocene catalyst technology access. Monitor Indonesian Ministry of Environment and Forestry enforcement intensity as the inflection signal for recycled content mandate stringency acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Olefin Production | Captive naphtha supply insulates Map Ta Phut operators from crude-linked margin compression. |
| Mechanical Recycling Infrastructure Buildout | Ho Chi Minh City positioning captures Vietnamese post-industrial film collection gap ahead of regulatory tightening. |
| Metallocene Catalyst Technology Licensing | Gulf Coast process expertise transfer enables downgauged moisture barrier qualification for Indonesian instant noodle exporters. |
| Long-term Supply Agreement Restructuring | Technical service integration locks in multilayer film converter volume commitments across ASEAN processed food corridors. |
| Pharmaceutical Grade Certification Investment | Thailand FDA-aligned documentation opens precision closure markets against polypropylene incumbents. |
Research Methodology
Bottom-up flexible packaging demand modeling reconciled against top-down high-pressure tubular reactor capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Thai and Indonesian petrochemical complexes, procurement leads at downstream flexible packaging converters, distribution channel partners, and technical R&D directors at additive suppliers generated operational data. Secondary validation drew from customs and trade flow databases, ASEAN petrochemical association reports, SEC filings of listed producers, and regulatory submissions to Thailand's Department of Industrial Works and Indonesia's Ministry of Environment and Forestry. Cross-referencing bottom-up converter demand estimates against top-down resin production and import statistics ensured triangulation integrity.
Input-output matrices map naphtha feedstock costs through polymerization yields to film-grade and injection-grade price formation across the analysis window. Segmentation dimensions include product grade tier, end-use industry concentration, packaging format complexity, and regional production hub regulatory exposure. CAGRs derive from elasticity-adjusted demand projections against capacity expansion schedules. Forecast inputs incorporate e-commerce fulfillment growth trajectories and evolving recycled content mandate enforcement intensity.
Revisions become necessary when naphtha-crude price correlations break down, Indonesian sustainable packaging mandate timelines accelerate, or Vietnamese plastic waste management frameworks impose unexpected virgin resin restrictions. Forecasts reflect documented assumptions about regulatory enforcement consistency and converter qualification cycle durations. A model refresh is warranted upon material change in ASEAN processed food export demand or metallocene catalyst supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Polymer Ingredients Market