
 Polyacrylic Acid Market | 2026-2036
Polyacrylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Polyacrylic Acid Market Analysis
The EU Green Deal is consolidating demand for biodegradable water treatment chemistries across European industrial clusters. BASF SE leverages its integrated acrylic acid value chain to sustain cost leadership in superabsorbent polymer feedstock. Nippon Shokubai Co. Ltd anchors Asia-Pacific supply through dedicated aqueous solution capacity at its Kashima site. Evonik Industries AG differentiates via pharmaceutical-grade purity standards that command premium positioning in ophthalmic and drug-delivery applications.
Polyacrylic acid is a high-molecular-weight synthetic polymer of acrylic acid monomer, typically manufactured through free-radical aqueous solution polymerization with controlled crosslinking to achieve molecular weights ranging from thousands to millions of Daltons; its carboxylic acid functionality enables pH-responsive behavior, metal chelation, and hydrogel formation for applications spanning water treatment, hygiene products, pharmaceuticals, and construction chemicals. The superabsorbent polymer application dominates value capture due to diaper and adult incontinence product specifications that require exceptional fluid retention capacity under load. Powder and aqueous solution product types split the industrial market, with powder grades preferred for dry-blend cement admixtures and aqueous solutions dominating continuous-process water treatment dosing systems.
EPA effluent limitation guidelines and REACH substance registration requirements are tightening permissible acrylamide residual levels and mandating biodegradability testing for polymer discharge into municipal wastewater systems. FDA oversight of pharmaceutical-grade and food-contact polyacrylic acid specifications creates dual-track compliance burdens that filter out commodity producers lacking analytical validation infrastructure. ISO 9001 and ISO 14001 certifications have become baseline qualifications for supplier qualification at multinational personal care and water treatment OEMs. Stakeholders must monitor evolving state-level PFAS restrictions that could extend regulatory scrutiny to fluorinated polymer alternatives and redirect specification toward polyacrylic acid in certain membrane and coating applications.
Market Dynamics
EPA effluent limitation guidelines and REACH substance registration requirements are tightening permissible acrylamide residual levels across municipal wastewater systems, forcing reformulation investments that reshape competitive economics for polyacrylic acid producers serving water treatment utilities.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal is consolidating demand for biodegradable water treatment chemistries across European industrial clusters, pulling specification toward polyacrylic acid alternatives to conventional flocculants.
- China infrastructure scale:Massive infrastructure investment and industrial water treatment expansion in China create outsized volume pull for polyacrylic acid-based dispersants in cement admixtures and cooling water systems.
- Superabsorbent polymer feedstock:Diaper and adult incontinence product specifications requiring exceptional fluid retention capacity under load sustain premium-grade polyacrylic acid demand in hygiene applications.
Market Restraints
- Acrylic acid feedstock volatility:Propylene price swings transmit directly into polyacrylic acid production economics, compressing margins for non-integrated producers lacking captive monomer supply.
- East Asian supply concentration:Dedicated aqueous solution capacity at coastal Japanese and Korean sites concentrates global supply risk, exposing buyers to logistics disruptions from regional shipping constraints.
- Biodegradability testing mandates:REACH and EPA requirements for polymer discharge biodegradability testing add qualification costs that filter out smaller compounders lacking analytical infrastructure.
Strategic Opportunities
- Pharmaceutical-grade purity standards:Ophthalmic and drug-delivery applications command premium positioning for producers meeting pharmaceutical-grade purity standards, creating margin expansion outside commodity water treatment grades.
- PFAS restriction redirection:Evolving state-level PFAS restrictions in the US extend regulatory scrutiny to fluorinated polymer alternatives, redirecting specification toward polyacrylic acid in membrane and coating applications.
- ISO certification baseline:ISO 9001 and ISO 14001 certifications have become baseline qualifications for supplier qualification at multinational personal care and water treatment OEMs, creating competitive moats for certified producers.
Industry Challenges
- FDA dual-track compliance:FDA oversight of pharmaceutical-grade and food-contact polyacrylic acid specifications creates dual-track compliance burdens that strain quality management systems and extend product launch timelines.
- Free-radical polymerization control:Achieving target molecular weights ranging from thousands to millions of Daltons through controlled crosslinking demands specialized process engineering expertise that concentrates in legacy production sites.
- Legacy dosing system integration:Continuous-process water treatment facilities running aqueous solution dosing systems face reconfiguration costs when upgrading to meet tightened effluent standards, slowing upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyacrylic Acid Market |
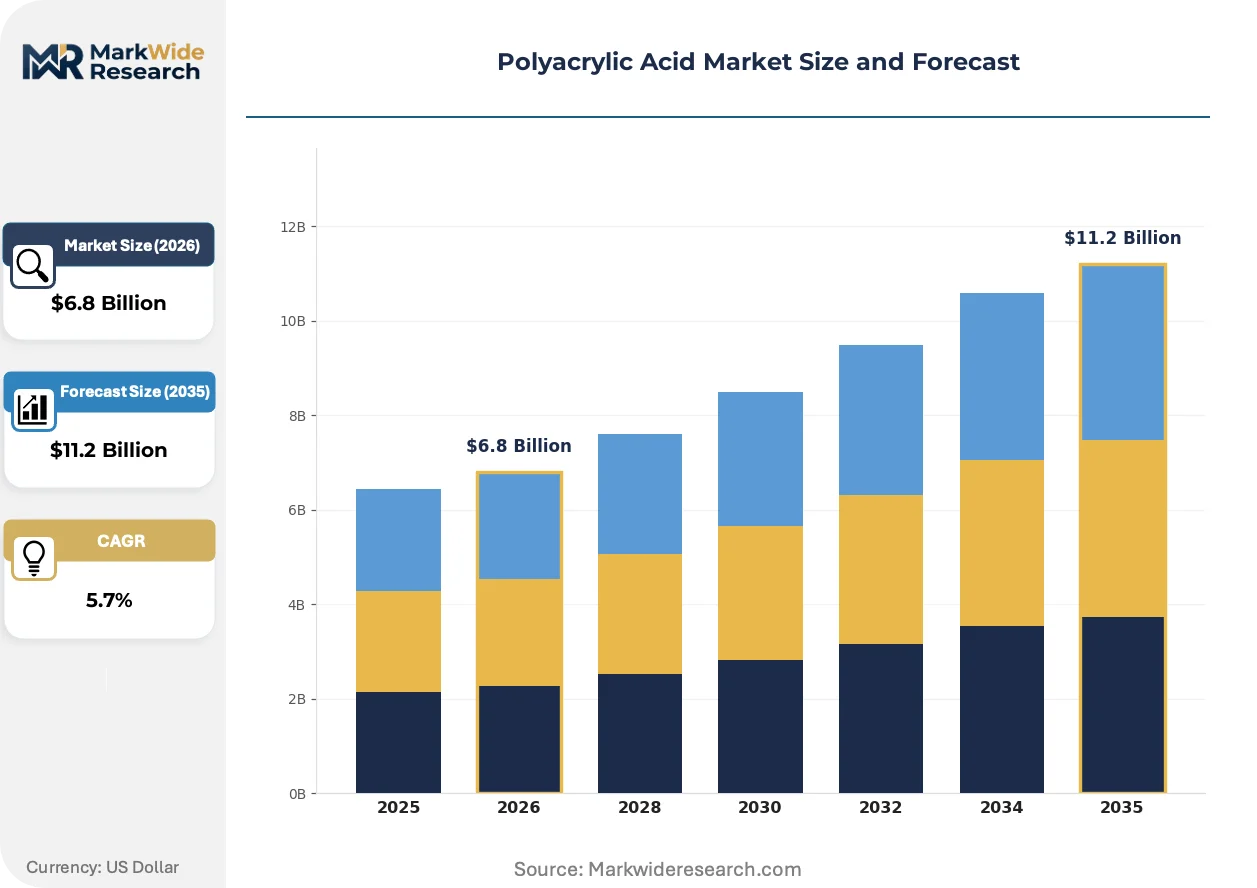
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Solution, Powder, Granule, Gel End Use Industry: Personal Care, Textiles, Agriculture, Construction Application: Thickening Agent, Superabsorbent Polymer, Dispersant, Binder Grade: Industrial Grade, Pharmaceutical Grade, Food Grade, Cosmetic Grade |
| Companies Covered | Evonik Industries AG, Ashland, BASF SE, Sumitomo Seika Chemicals, The Lubrizol Corporation, Arkema, Nippon Shokubai Co. Ltd, LG Chem. Ltd., Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyacrylic Acid Market Emerging Trajectories
Controlled crosslinking technologies and pH-responsive formulation advances are rewriting performance benchmarks across water treatment and pharmaceutical applications, compressing qualification timelines for next-generation grades.
Controlled molecular architecture synthesis is rewriting how producers achieve specified viscosity and chelation performance in metalworking fluids and boiler water treatment. Municipal utilities in Germany and the Netherlands are piloting these grades for phosphate-free scale inhibition programs. The technology is rewriting supplier selection criteria, favoring producers with in-house analytical validation over commodity traders.
REACH substance registration requirements and tightening EPA effluent limitation guidelines are mandating acrylamide residual documentation and biodegradability certification for polymers discharged into municipal wastewater. Industrial compounders in Belgium and Ohio are consolidating formulation lines to reduce qualification burden. Superabsorbent polymer feedstock suppliers face the steepest compliance investment given the volume scale and purity specifications involved.
Specification-driven procurement is consolidating vendor lists at multinational water treatment OEMs and personal care manufacturers, with ISO 9001 and ISO 14001 certifications becoming minimum qualifiers rather than differentiators. Third-party certification bodies in France and California are expanding polymer-specific audit programs to meet this demand. China-based industrial water treatment expansion is absorbing the highest volume of newly qualified suppliers, though pharmaceutical-grade segments remain concentrated among established Western producers.
Polyacrylic Acid Market Segmentation
Polyacrylic acid buyers select grades and formats based on regulatory compliance burdens, dosing system compatibility, and end-use purity requirements. Specification divergence between industrial water treatment and pharmaceutical applications creates distinct procurement channels with minimal overlap.
Product Type:
Procurement teams prioritize handling characteristics and dissolution kinetics when selecting between liquid and solid formats for continuous-process operations.
- Aqueous Solution:Pre-dissolved polymer at controlled solids content eliminates on-site hydration equipment. Municipal wastewater facilities in Germany and the Netherlands specify aqueous solutions for automated dosing skids handling phosphate-free scale inhibition programs.
- Powder:Dry-blend compatibility drives cement admixture and construction chemical formulations. Free-flowing grades with anti-caking additives dominate procurement from concrete additive compounders seeking extended shelf stability.
- Granule:Intermediate particle size reduces dust generation during dry handling while maintaining rapid dissolution kinetics. Agricultural soil amendment applications favor granules for controlled-release nutrient carrier systems.
- Gel:High-viscosity semisolid formulations serve topical pharmaceutical and cosmetic delivery platforms. Crosslinked gel structures enable sustained-release profiles in dermatological applications.
Aqueous solution leads on scale; gel leads on momentum.
End Use Industry:
Regulatory stringency and volume concentration determine margin architecture across downstream sectors.
- Personal Care:Cosmetic-grade specifications for superabsorbent polymers in hygiene products command premium positioning. Adult incontinence product manufacturers in Japan and South Korea drive volume through exceptional fluid retention capacity under load requirements.
- Textiles:Sizing and finishing applications leverage polyacrylic acid as a temporary warp protective and dye leveling agent. Mills in Gujarat and Tamil Nadu absorb industrial-grade volumes for cotton and synthetic fiber processing.
- Agriculture:Hydrogel formulations improve water retention in drought-prone cultivation zones. Soil amendment applications concentrate in California's Central Valley and Australia's Murray-Darling basin.
- Construction:Cement grinding aids and concrete superplasticizers represent the highest-volume industrial outlet. Infrastructure investment in China's provincial cities sustains dispersant-grade consumption in ready-mix concrete operations.
Construction leads on scale; personal care leads on momentum.
Application:
Functional performance requirements dictate molecular weight distribution and crosslink density specifications.
- Thickening Agent:Rheology modification in personal care formulations and industrial coatings depends on precise viscosity build characteristics. Shampoo and lotion manufacturers specify narrow molecular weight ranges for predictable flow behavior.
- Superabsorbent Polymer:Crosslinked sodium polyacrylate structures achieve absorption capacities exceeding hundreds of times their dry weight. Diaper and hygiene product OEMs mandate centrifuge retention capacity and absorbency under load testing protocols.
- Dispersant:Electrosteric stabilization of particulate suspensions in water treatment and mineral processing. Cooling water systems and mining operations deploy low-molecular-weight grades for scale and deposit control.
- Binder:Adhesion promotion in ceramic processing, battery electrode manufacturing, and construction materials. Lithium-ion battery anode coating applications require ultrapure grades with controlled metal ion content.
Superabsorbent polymer leads on scale; binder leads on momentum.
Grade:
Certification burden and analytical validation infrastructure separate qualified suppliers from commodity compounders.
- Industrial Grade:Broad-specification material for water treatment, construction, and mineral processing applications. REACH registration and EPA effluent compliance documentation suffice for qualification at municipal utilities.
- Pharmaceutical Grade:USP-NF and EP monograph compliance with validated residual monomer and endotoxin testing. Ophthalmic and parenteral drug delivery applications command the steepest purity premiums.
- Food Grade:FCC and EU food additive specifications with migration testing for indirect contact applications. Beverage clarification and processing aid uses require batch-specific certification.
- Cosmetic Grade:Personal care ingredient listings with heavy metal and microbial specification. INCI nomenclature compliance enables formulation transparency for European and North American cosmetic brands.
Industrial grade leads on scale; pharmaceutical grade leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemists and process engineers cluster around major acrylic acid production sites and downstream formulation centers. Talent concentration follows integrated petrochemical complexes and specialized compounding facilities.
China
Massive infrastructure investment and industrial water treatment expansion drive dispersant-grade consumption in cement admixtures and cooling water systems. MEE effluent standards tighten permissible discharge limits for polymer residuals. Provincial cities across Shandong and Jiangsu absorb the highest volumes of industrial-grade material for ready-mix concrete operations.
United States
Adult incontinence product manufacturers and municipal wastewater utilities sustain dual demand tracks for superabsorbent and treatment-grade polymers. EPA effluent limitation guidelines mandate acrylamide residual documentation for municipal discharge. Industrial compounders in Ohio and Texas consolidate formulation lines to reduce qualification burden under tightening standards.
Germany
REACH substance registration requirements and EU Green Deal mandates pull specification toward biodegradable water treatment chemistries. Municipal utilities in the Ruhr industrial cluster pilot phosphate-free scale inhibition programs using advanced polymer grades. BASF SE's integrated Ludwigshafen complex anchors European supply chain configuration for superabsorbent polymer feedstock.
Japan
Hygiene product OEMs in the Kansai region command exceptional fluid retention capacity under load specifications for premium diaper applications. METI chemical management frameworks govern residual monomer limits in consumer-facing applications. Nippon Shokubai Co. Ltd's Kashima site concentrates dedicated aqueous solution capacity serving Asia-Pacific demand.
India
Textile mills in Gujarat and Tamil Nadu absorb industrial-grade volumes for sizing and dye leveling applications. BIS standards for construction chemicals create compliance benchmarks for cement grinding aid formulations. Infrastructure investment in Maharashtra and Karnataka sustains dispersant demand from ready-mix concrete producers.
Polyacrylic Acid Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across formulation and application development. The vendor base stratifies between integrated petrochemical majors controlling upstream acrylic acid supply and specialized compounders focusing on downstream grade certification. Three archetypes dominate: integrated monomer-to-polymer producers, pharmaceutical-grade purity specialists, and regional aqueous solution compounders. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure feedstock access and qualification credentials.
Among integrated German chemical producers, BASF SE and Evonik Industries AG occupy positions spanning industrial through pharmaceutical-grade tiers. Nippon Shokubai Co. Ltd anchors Asia-Pacific supply configuration through its Japanese production base. These three exemplify how geographic integration with petrochemical infrastructure and certification depth separate qualified suppliers from commodity traders in procurement decisions at multinational OEMs.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Ashland |
| BASF SE |
| Sumitomo Seika Chemicals |
| The Lubrizol Corporation |
| Arkema |
| Nippon Shokubai Co. Ltd |
| LG Chem. Ltd. |
| Dow |
| Others |
Supply Flow & Price Mechanics
EU Green Deal biodegradability mandates gate qualified supply and premium-tier pricing access for polyacrylic acid producers, filtering out compounders lacking analytical validation infrastructure while concentrating margin capture among certified suppliers serving municipal water treatment utilities.
Pricing Analysis
Product-plus-service bundling versus unbundled commodity supply splits the market between integrated producers commanding long-term offtake premiums and spot-market traders competing on volume. Pharmaceutical-grade purity standards and ISO 14001 certification tiers drive price differentiation, with hygiene product OEMs paying premiums for validated residual documentation. Cost compression in industrial-grade segments intensifies as Chinese dispersant-grade capacity expands. Municipal wastewater utilities exhibit highest price sensitivity due to budget constraints, while ophthalmic drug-delivery applications show lowest sensitivity given specification rigidity.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and coastal China operate hub-and-spoke patterns serving formulation compounders and end-use OEMs. Acrylic acid monomer supply concentrates in China, Germany, and the United States, with propylene feedstock volatility transmitting directly into polymer economics. Production rests on controlled crosslinking reactor technology and aqueous solution compounding infrastructure. Single-source vulnerability concentrates at Japanese and Korean coastal sites serving Asia-Pacific demand. Distribution runs through certified chemical distributors and direct mill-to-plant supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyacrylic acid has entered a late-cycle quality phase where procurement consolidation favors certified suppliers, driven by REACH and EPA mandates pulling specification toward biodegradable, documented grades.
For Market Incumbents: Hedge feedstock exposure through captive acrylic acid supply or long-term propylene offtake agreements to counter margin compression from East Asian volume competition. Deepen certification moats by investing in pharmaceutical-grade analytical infrastructure before FDA dual-track compliance requirements harden further. Prioritize backward integration into monomer production at Ludwigshafen-scale complexes to sustain cost leadership against non-integrated compounders. For New Entrants and Emerging Players: Launch via regional aqueous solution compounding partnerships serving undersupplied Indian textile mills and Middle Eastern water treatment utilities. White-space concentrates in agricultural hydrogel applications for drought-prone cultivation zones in California and Australia, where specification barriers remain lower than pharmaceutical segments. Pursue ISO 14001 certification as minimum market entry credential rather than differentiator. For Investors and Strategic Acquirers: Valuations sit cheapest among regional aqueous solution compounders lacking pharmaceutical-grade certification depth but holding established municipal utility relationships. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale alone. Watch for PFAS restriction expansion in US state legislatures as signal for polyacrylic acid substitution demand inflection in membrane and coating applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive monomer supply insulates margin structure from propylene volatility at Ludwigshafen-scale sites. |
| Pharmaceutical-Grade Certification Investment | USP-NF compliance unlocks premium positioning in ophthalmic drug-delivery applications. |
| Long-Term Municipal Supply Agreement | REACH-compliant offtake contracts reduce qualification burden for German and Dutch water utilities. |
| Green Manufacturing Transition | Biodegradable polymer grades capture EU Green Deal procurement preference in industrial clusters. |
| Joint Venture in Asia-Pacific | Local aqueous solution capacity mitigates logistics risk from Japanese coastal concentration. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with plant managers at integrated petrochemical complexes, procurement leads at water treatment OEMs, distribution channel partners, and technical R&D directors specializing in controlled polymerization. Secondary validation draws from ECHA REACH registration databases, EPA effluent guideline filings, customs trade data, and SEC 10-K disclosures from listed chemical producers. Bottom-up volume estimates triangulate against top-down acrylic acid consumption models.
Granularity extends to grade tier, end-use industry, and regional production hub across the projection horizon. CAGRs derive from segment-level demand elasticity modeling against infrastructure investment cycles and regulatory compliance timelines. Forecast inputs incorporate MEE effluent standard tightening in China, EU Green Deal procurement mandates, and superabsorbent polymer feedstock specification evolution in hygiene applications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under acute propylene price volatility or sudden PFAS restriction acceleration. Outputs reflect documented assumptions around regulatory implementation schedules and infrastructure investment continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market