
 CO2-Based Polycarbonate Polyols for Flexible PU Foam Market | 2026-2036
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market Size, Share, and Industry Trends Forecast 2026-2036
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market Insights
Furniture manufacturers is redrawing procurement priorities away from conventional petroleum-based polyols toward CO2-derived alternatives with verified carbon footprints. Covestro leverages its integrated production complex in Leverkusen to supply certified low-carbon polyols directly to European foam converters. BASF competes through backward integration into captured CO2 feedstock partnerships with industrial emitters. Huntsman anchors its position in North America through specialized technical service teams that reformulate existing flexible foam lines for polycarbonate polyol compatibility.
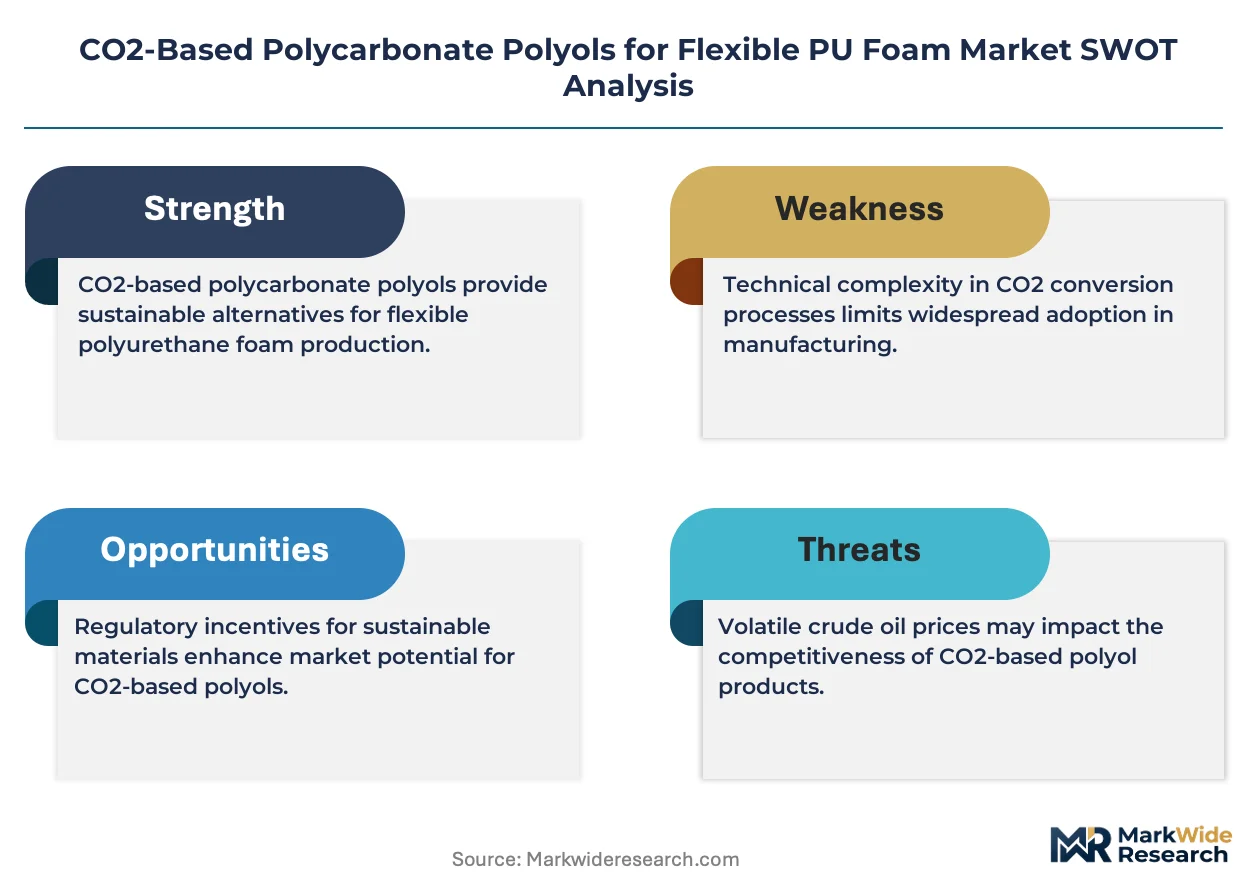
CO2-based polycarbonate polyols for flexible PU foam are aliphatic polyether-carbonate polyols synthesized via copolymerization of propylene oxide with carbon dioxide, typically containing 10-40 wt% incorporated CO2 content and hydroxyl values ranging from 25-160 mg KOH/g depending on targeted foam softness. These polyols replace conventional polyether polyols in flexible polyurethane formulations to reduce cradle-to-gate greenhouse gas emissions while maintaining tensile strength and resilience specifications for comfort applications. High hydroxyl variants dominate current volume owing to their established performance in high-load-bearing mattress cores where rapid demold cycles and dimensional stability command premium positioning. Mattress foam applications are capturing accelerated interest from sleep product makers seeking differentiated sustainability credentials in direct-to-consumer channels. Liquid form factors sustain overwhelming preference among foam producers due to compatibility with existing high-pressure dispensing equipment and reduced handling complexity versus solid or dispersion alternatives.
REACH registration requirements and the EU Green Deal carbon border adjustment mechanism are elevating documentation burdens for imported conventional polyols while creating preference for domestically produced CO2-based alternatives with verified life-cycle assessments. EPA greenhouse gas reporting protocols and California Air Resources Board emission factors are similarly redirecting North American formulation choices toward feedstocks with quantified carbon reduction claims. Foam producers and their downstream customers must now validate that supplier sustainability claims align with evolving third-party certification standards before qualifying polycarbonate polyols for long-term supply agreements.
Market Dynamics
Automotive OEMs are tightening Scope 3 emissions targets and demanding verified carbon footprint documentation from seating foam suppliers, forcing converters to requalify their polyol supply chains around cradle-to-gate greenhouse gas metrics rather than traditional cost-performance benchmarks.
Growth Catalysts
- EU Green Deal carbon border adjustment:Imported conventional polyols face elevated documentation burdens at European ports, redirecting formulation choices toward domestically produced CO2-based alternatives with verified life-cycle assessments.
- Propylene oxide copolymerization advances:Catalyst efficiency gains now enable 30-40 wt% CO2 incorporation without tensile strength degradation, opening high-load-bearing mattress core applications previously closed to polycarbonate polyols.
- California Air Resources Board protocols:Emission factor requirements for upholstered furniture sold in the state are compelling foam producers to source feedstocks with quantified carbon reduction claims.
Market Restraints
- Captured CO2 feedstock concentration:Industrial emitter partnerships cluster around the Rhine-Ruhr corridor and Houston Ship Channel, creating geographic supply vulnerability for converters outside these zones.
- Propylene oxide price volatility:Petrochemical feedstock exposure persists in CO2-based polyol synthesis, limiting cost insulation versus conventional polyether alternatives during olefin market spikes.
- High-pressure dispensing equipment lock-in:Existing foam lines require capital reconfiguration to optimize for polycarbonate polyol rheology, slowing converter migration.
Strategic Opportunities
- Direct-to-consumer mattress channels:Sleep product brands seeking differentiated sustainability credentials are accelerating qualification of certified low-carbon foam for premium positioning.
- REACH registration gaps:Smaller conventional polyol importers face compliance cost barriers, creating white space for domestic European producers with established registration dossiers.
- Aliphatic polyether-carbonate hybrid R&D:Convergence of tunable hydroxyl value architectures with bio-based propylene oxide feedstocks promises next-generation emission reductions.
Industry Challenges
- Third-party certification alignment:Foam producers must validate that supplier sustainability claims meet evolving ISO 14040/14044 life-cycle assessment standards before qualifying polycarbonate polyols for long-term agreements.
- Technical service team scaling:Reformulating existing flexible foam lines for polycarbonate polyol compatibility requires specialized field engineering capacity that outpaces current talent pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CO2-Based Polycarbonate Polyols for Flexible PU Foam Market |
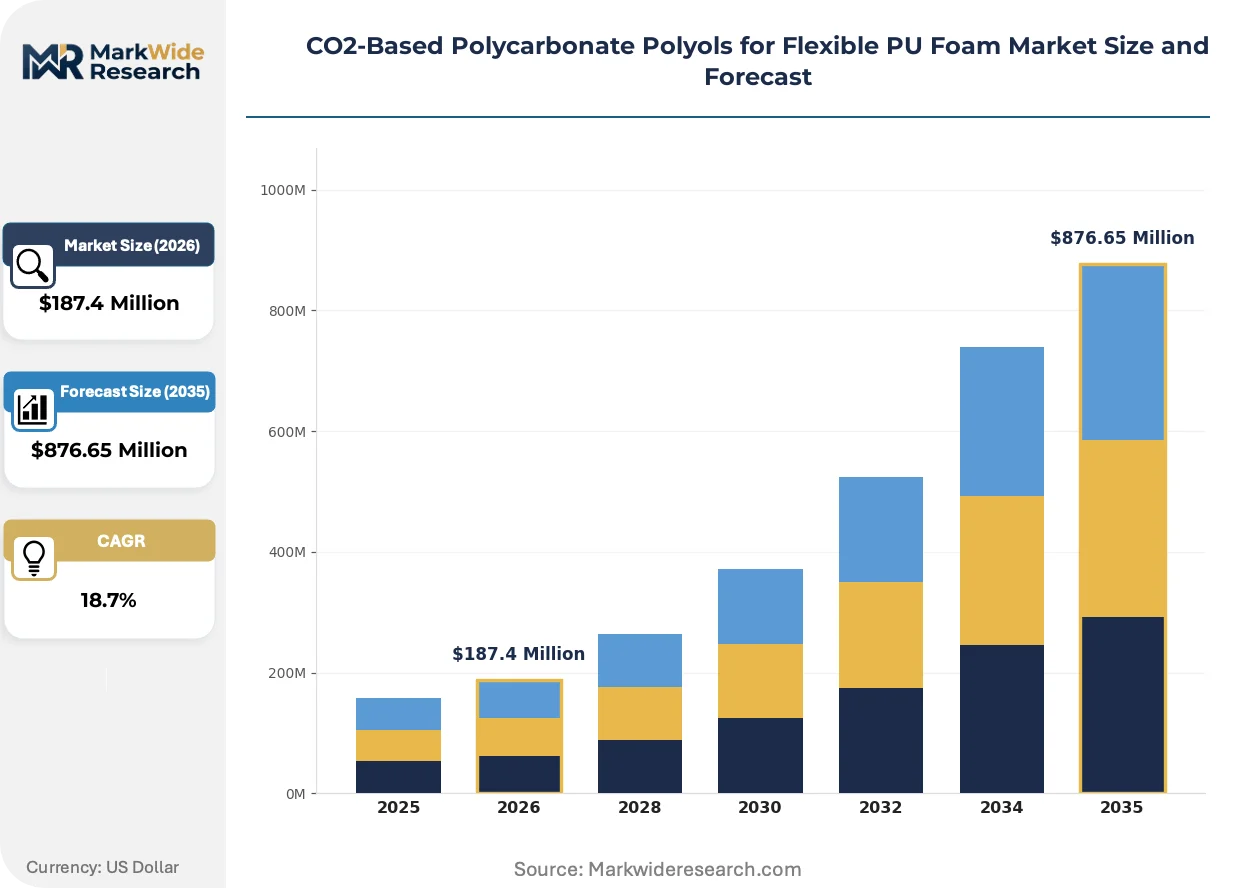
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Hydroxyl, Low Hydroxyl, Medium Hydroxyl, Functionalized Polyols Application: Mattress Foam, Automotive Seating, Furniture Cushions, Acoustic Panels End User: OEMs, Tier-1 Upholstery, Furniture Manufacturers, Sleep Product Makers Form: Liquid, Solid, Blend, Suspended Dispersion |
| Companies Covered | Covestro, Asahi Kasei, BASF, Dow, Mitsui Chemicals, Wanhua Chemical, Huntsman, Repsol, Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market Trends and Innovations
Formulation chemistry is pivoting from petroleum-centric architectures toward CO2-integrated molecular designs that satisfy both performance specifications and emissions accounting requirements. Three interconnected developments are restructuring competitive positioning.
Aliphatic polyether-carbonate polyol synthesis is bifurcating the supplier landscape between integrated petrochemical complexes with captive CO2 partnerships and standalone specialty polyol houses dependent on merchant feedstock. Mattress foam converters with rapid demold cycle requirements are migrating fastest, while automotive seating suppliers lag due to longer OEM qualification timelines. This technology compression is squeezing mid-scale conventional polyether producers without backward integration into captured carbon sources.
REACH registration requirements are elevating documentation burdens for imported conventional polyols while the EU Green Deal carbon border adjustment mechanism creates preference for domestically produced alternatives with verified life-cycle assessments. Foam converters serving European furniture manufacturers now face supplier qualification hurdles that favor incumbent polycarbonate polyol producers with established ECHA dossiers. German foam clusters around Leverkusen and Ludwigshafen are capturing disproportionate share of this regulatory redirection.
Buying patterns among sleep product makers are rotating toward certified low-carbon foam specifications that command premium positioning in direct-to-consumer channels. Traditional distributor-mediated supply chains are compressing as mattress brands establish direct technical relationships with polyol producers for formulation co-development. This channel disintermediation is most visible in Germany and the United States, where DTC mattress startups have achieved sufficient scale to justify dedicated supply agreements.
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market Segmentation
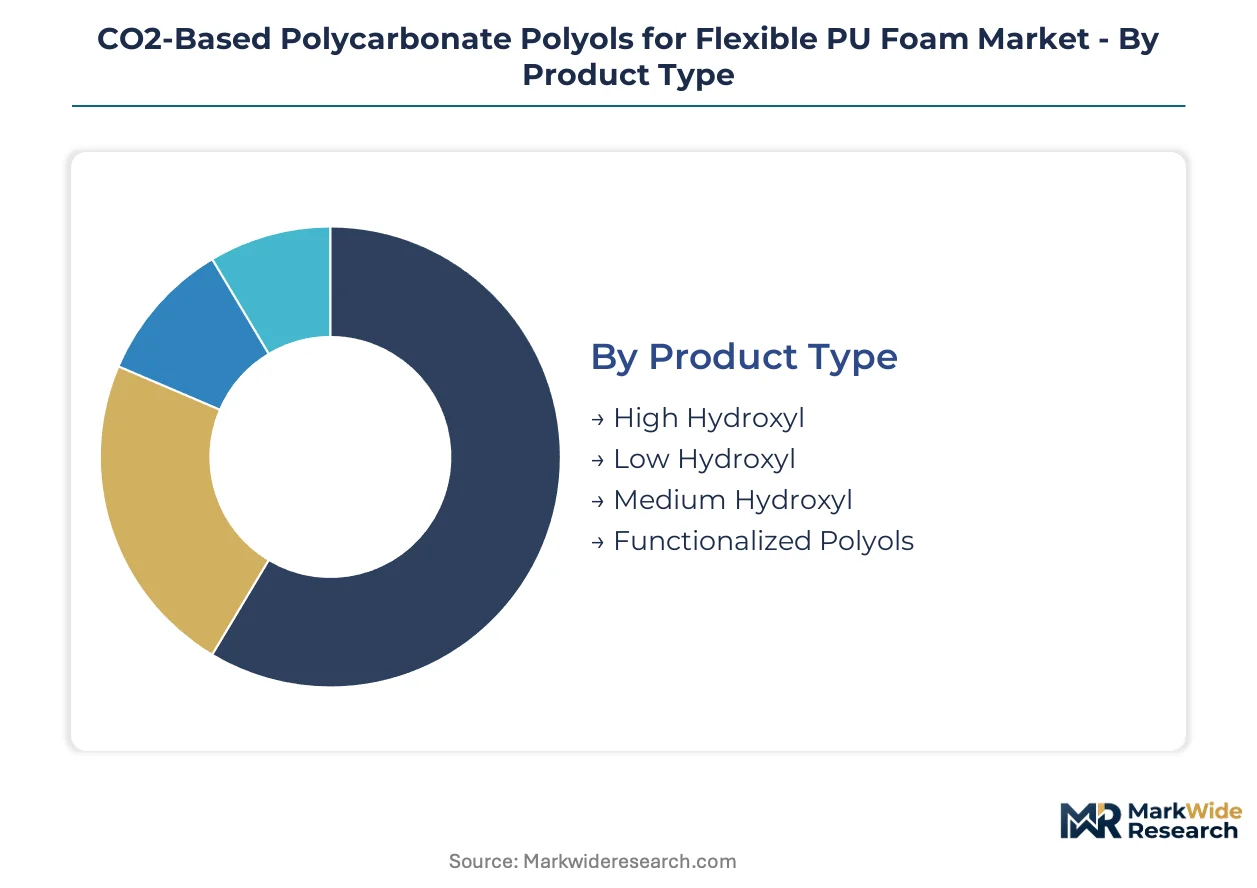
Segmentation in CO2-based polycarbonate polyols reveals how technical specifications and supply chain positioning create divergent margin structures across the flexible foam value chain. Understanding these divisions helps suppliers allocate R&D resources and converters optimize procurement against performance requirements.
Product Type:
Margin pools concentrate in hydroxyl value variants that command premium positioning through demold cycle efficiency and load-bearing performance differentiation.
- High Hydroxyl:These polyols carry hydroxyl values above 100 mg KOH/g, enabling rapid cure rates essential for high-throughput mattress core production. Demand concentrates with German sleep product makers seeking certified low-carbon specifications for DTC channels, though propylene oxide cost exposure compresses margins during olefin spikes.
- Low Hydroxyl:Softer variants below 50 mg KOH/g target comfort-layer applications where resilience and hand-feel dominate purchasing criteria. Automotive seating suppliers in Stuttgart and Wolfsburg are accelerating qualification timelines as OEMs tighten Scope 3 documentation requirements.
- Medium Hydroxyl:Mid-range specifications balance cost and performance for furniture cushion converters serving mass-market retailers.
- Functionalized Polyols:Modified architectures with enhanced flame retardancy or antimicrobial properties capture niche specification premiums.
The dominant share belongs to High Hydroxyl variants, while Low Hydroxyl is closing the gap fastest as automotive requalification timelines compress.
Application:
Application segments diverge sharply in qualification velocity, with direct-to-consumer channels outrunning OEM-mediated supply chains.
- Mattress Foam:Rapid demold cycle requirements and dimensional stability specifications define this segment, where certified low-carbon credentials command price premiums. Sleep product makers in Germany and the United States are establishing direct technical relationships with polyol producers, bypassing traditional distributor channels.
- Automotive Seating:Longer OEM qualification timelines and stringent tensile strength specifications slow migration, though Scope 3 pressure is accelerating converter requalification efforts around cradle-to-gate greenhouse gas metrics.
- Furniture Cushions:Mass-market upholstery applications prioritize cost-performance balance over sustainability credentials.
- Acoustic Panels:Specialized sound-dampening specifications create small-volume, high-margin opportunities in commercial construction.
Mattress Foam holds the revenue concentration lead, though Automotive Seating is expanding most quickly as OEM deadlines harden.
End User:
End user categories reflect procurement sophistication gradients, from technical co-development relationships to price-sensitive volume purchasing.
- OEMs:Direct automotive and mattress brand relationships demand verified life-cycle assessments and ISO 14040/14044 compliant documentation, creating qualification barriers that favor incumbent polycarbonate polyol producers.
- Tier-1 Upholstery:Intermediate converters balance OEM specification compliance with converter-level cost optimization, often requiring specialized technical service support for foam line reconfiguration.
- Furniture Manufacturers:Mass-market producers show accelerating interest in sustainability credentials but remain price-sensitive.
- Sleep Product Makers:DTC-focused brands prioritize certified low-carbon foam for premium positioning, driving fastest adoption velocity.
OEMs dominate procurement value, while Sleep Product Makers are gaining share fastest through channel disintermediation.
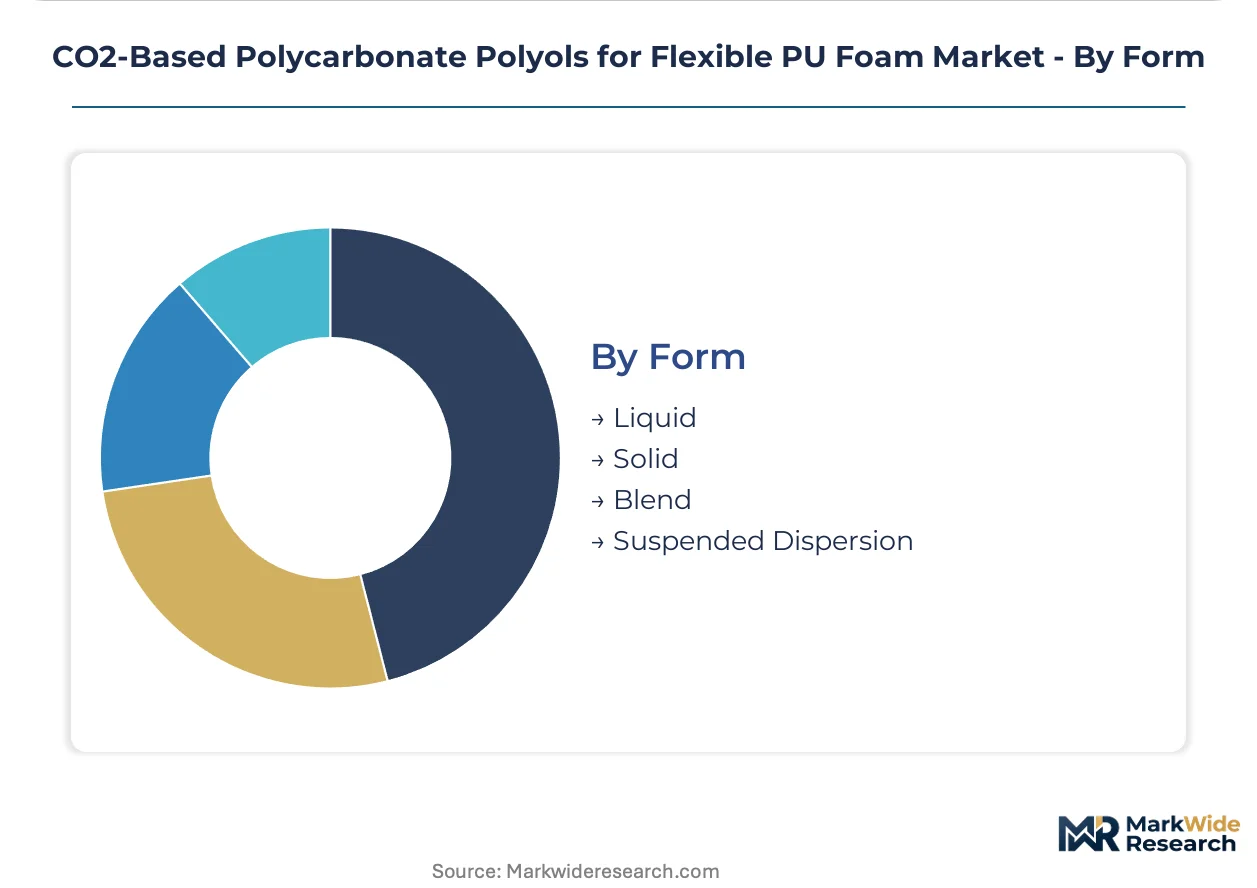
Form:
Form factor selection determines equipment compatibility and handling economics across converter operations.
- Liquid:Standard liquid polyols sustain overwhelming preference due to compatibility with existing high-pressure dispensing equipment and reduced handling complexity versus alternatives.
- Solid:Solid forms serve specialized applications requiring extended shelf stability or reduced shipping volumes.
- Blend:Pre-formulated blends reduce converter mixing steps but limit formulation flexibility.
- Suspended Dispersion:Dispersion formats capture niche applications requiring particulate additive integration.
Liquid forms command the volume majority, while Blend formats are climbing the fastest as converters seek process simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr pipeline corridor and Leverkusen chemical complex anchor European supply for CO2-based polycarbonate polyols, while the Houston Ship Channel petrochemical network underwrites North American feedstock security for flexible foam converters.
United States
California Air Resources Board emission protocols and EPA greenhouse gas reporting requirements are redirecting formulation choices toward feedstocks with quantified carbon reduction claims. The Houston Ship Channel industrial emitter cluster supplies captured CO2 feedstock to polyol producers serving automotive seating manufacturers in Detroit and mattress foam converters in the Southeast. Huntsman maintains specialized technical service teams that reformulate existing flexible foam lines for polycarbonate polyol compatibility.
Germany
REACH registration requirements and the EU Green Deal carbon border adjustment mechanism create preference for domestically produced alternatives with verified life-cycle assessments. The Leverkusen and Ludwigshafen chemical clusters host integrated polycarbonate polyol production facilities serving flexible foam converters. Covestro leverages its Leverkusen complex to supply certified low-carbon polyols directly to European foam converters, while BASF competes through backward integration into captured CO2 feedstock partnerships with industrial emitters.
China
Dual carbon goals and MIIT industrial policy directives are elevating documentation standards for imported conventional polyols while supporting domestic CO2-based alternative production. The Yangtze River Delta chemical corridor concentrates polyol manufacturing capacity serving furniture and automotive seating clusters. Wanhua Chemical operates production facilities supplying flexible foam converters with polycarbonate polyols for mattress and cushioning applications.
Japan
METI carbon neutrality roadmaps and JIS standards for upholstered products are compelling foam producers to source feedstocks with verified emission reductions. The Osaka-Kobe industrial zone hosts chemical producers serving automotive seating suppliers in Toyota City and mattress manufacturers in the Kanto region. Asahi Kasei and Mitsui Chemicals maintain positions supplying polycarbonate polyols to domestic flexible foam converters meeting OEM sustainability documentation requirements.
South Korea
MFDS chemical safety assessments and national carbon neutrality targets are redirecting procurement toward lower-carbon feedstocks with ISO 14040/14044 compliant documentation. The Ulsan petrochemical complex provides integrated production infrastructure for CO2-based polyol manufacturing. Local producers supply flexible foam converters serving the Seoul Capital Area mattress market and automotive seating plants in the Busan-Ulsan corridor.
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market Competitive Landscape
Listed leaders compete with private specialists across integrated production capacity and technical service capabilities. The supplier landscape bifurcates between integrated petrochemical complexes with captive CO2 partnerships and standalone specialty polyol houses dependent on merchant feedstock. Three strategic archetypes dominate: backward-integrated chemical majors with industrial emitter partnerships, mid-scale regional producers with formulation specialization, and technology licensors without manufacturing assets. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure captured CO2 feedstock access and converter technical relationships.
Within the integrated chemical major tier, Covestro, BASF, and Huntsman exemplify contrasting geographic and capability positioning. Covestro anchors European supply through its Leverkusen production complex and direct technical relationships with foam converters. BASF represents the backward-integrated archetype through captured CO2 feedstock partnerships with industrial emitters. Huntsman occupies the North American technical service position with specialized field engineering teams that reformulate existing flexible foam lines for polycarbonate polyol compatibility.
| Leading Market Players |
|---|
| Covestro |
| Asahi Kasei |
| BASF |
| Dow |
| Mitsui Chemicals |
| Wanhua Chemical |
| Huntsman |
| Repsol |
| Tosoh Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at integrated Leverkusen and Ludwigshafen complexes shapes both supply concentration and price floors for CO2-based polycarbonate polyols, as scale economies in captured CO2 feedstock processing compress unit costs below what merchant-dependent producers can match.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified low-carbon specifications from conventional alternatives and unverified imports. Price differentiation rests on ISO 14040/14044 documentation grade and volume scale, with mattress foam converters commanding steepest discounts. Pricing pressure stems from propylene oxide cost volatility that erodes margins during olefin market spikes. Tier-1 upholstery converters show highest price sensitivity, while direct-to-consumer sleep product brands absorb premiums for sustainability credentials.
Supply Chain Analysis
Inventory lead times stretch longest for converters outside the Rhine-Ruhr corridor and Houston Ship Channel industrial emitter clusters. Supply concentrates in Germany, the United States, and China, with raw material dependencies on captured CO2, propylene oxide, and catalyst systems. Single-source vulnerability runs through the concentrated industrial emitter partnerships that feed polyol production. Distribution runs through direct technical relationships between producers and foam converters, bypassing traditional distributor channels for qualified volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by automotive OEM requalification delays, as Scope 3 documentation deadlines force seating foam suppliers to restart converter migration timelines.
For Market Incumbents: Fortify backward integration into captured CO2 feedstock partnerships with industrial emitters along the Rhine-Ruhr corridor and Houston Ship Channel. Expand technical service team capacity to capture automotive seating requalification demand before mid-scale competitors achieve ISO 14040/14044 certification compliance. Defend against merchant-feedstock-dependent entrants by locking long-term supply agreements with sleep product makers. For New Entrants and Emerging Players: Anchor in the low hydroxyl comfort-layer segment where automotive seating suppliers in Stuttgart and Wolfsburg are accelerating qualification timelines. Target furniture cushion converters serving mass-market retailers with price-sensitive procurement profiles. Pursue formulation co-development partnerships with DTC mattress brands seeking certified low-carbon credentials. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chemical majors with captive CO2 partnerships and established ECHA registration dossiers. Long-term viability over a multi-year horizon favors producers with backward integration into industrial emitter networks rather than merchant-feedstock-dependent specialists. Watch for REACH registration compliance acceleration among Tier-1 upholstery converters as an inflection indicator for demand maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captured CO2 Feedstock | Secures supply security against industrial emitter partnership concentration in Germany and the United States. |
| Technical Service Team Expansion | Enables foam line reconfiguration support that accelerates converter migration from conventional polyether polyols. |
| ISO 14040/14044 Certification Investment | Creates qualification barriers for imported conventional polyols under EU Green Deal carbon border adjustment mechanisms. |
| Direct-to-Consumer Channel Partnership | Captures premium positioning demand from sleep product brands seeking differentiated sustainability credentials. |
| Long-term Supply Agreement with Automotive OEMs | Locks in volume commitments as Scope 3 emissions documentation requirements tighten procurement specifications. |
Research Methodology
Operator-level perspectives from polyol plant managers, procurement leads at automotive seating manufacturers, foam converter technical directors, and distribution channel partners anchored the qualitative base. These primary insights combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators to establish market sizing.
Sensitivity analysis across propylene oxide price volatility scenarios, automotive OEM qualification timeline variations, and regulatory enforcement intensity shaped the projection framework. Segmentation dimensions modeled include hydroxyl value tier, application end-use, end user procurement sophistication, and regional production hub. CAGRs derived from regression analysis of historical capacity expansion patterns and forward-looking converter adoption curves. Feedstock cost trajectories and carbon border adjustment implementation schedules served as key forecast inputs.
Material uncertainties — propylene oxide supply disruptions, REACH registration enforcement delays, and automotive OEM Scope 3 target revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about catalyst efficiency gains and industrial emitter partnership expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
GCC Vinyl Flooring Market