
 North America and Europe Phenolic Resin Market | 2026-2036
North America and Europe Phenolic Resin Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Phenolic Resin Market Insights
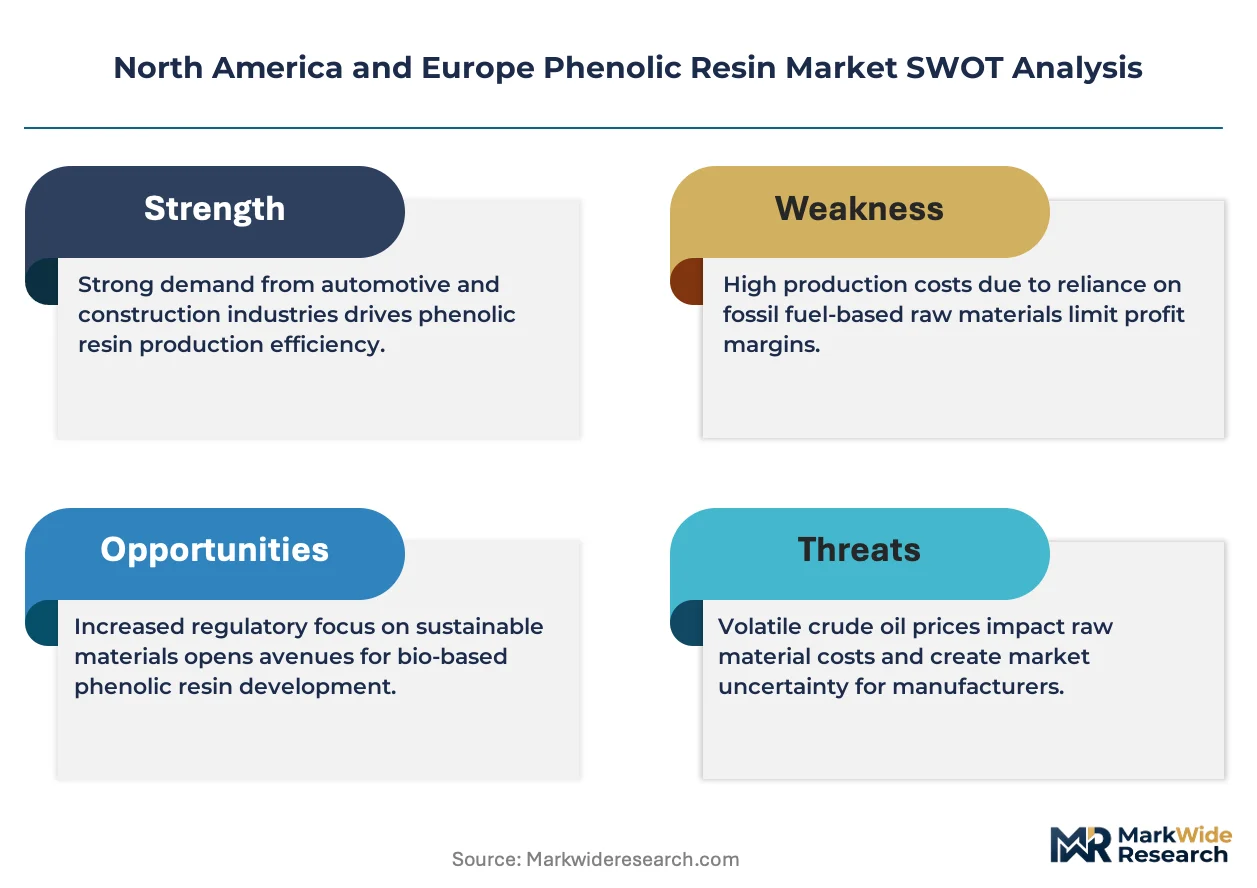
Asset-light toll manufacturing partnerships are reshaping competitive dynamics in the North America and Europe phenolic resin sector. Prefere Resins Holding GmbH leverages captive phenol supply from European refiners to sustain margin stability. Bakelite Synthetics anchors North American distribution through integrated rail-to-plant logistics. Georgia-Pacific Chemicals dominates southern U.S. markets with barge-dependent feedstock access.
Phenolic resins are thermosetting polymers synthesized from phenol and formaldehyde through acid or base catalysis, yielding cross-linked networks with exceptional thermal stability above 300 degrees Celsius and inherent flame retardancy. Their primary purpose centers on high-temperature bonding, insulation, and structural composite matrices where carbonaceous char formation protects underlying substrates. Novolac formulations command the widest formulation flexibility across coatings and electronics applications, while resol resins lead adhesive penetration in engineered wood products. Composites represent the fastest-growing application vector as aerospace OEMs substitute phenolic prepregs for epoxy in interior fire-rated components.
EPA formaldehyde emission standards under the Toxic Substances Control Act and REACH Annex XVII restrictions govern product chemistry across both regions, with ECHA's 2023 reclassification of formaldehyde intensifying substitution pressures. The EU F-Gas Regulation and U.S. OSHA permissible exposure limits further constrain conventional process economics. Stakeholders must monitor bio-based phenol pilot projects and regulatory divergence risk between Brussels and Washington.
Market Dynamics
REACH Annex XVII formaldehyde restrictions and EPA Toxic Substances Control Act emission standards are forcing simultaneous reformulation across both regions, compressing margins while accelerating bio-based phenol pilot investments.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA and U.S. NHTSA fuel-economy targets expand phenolic composite penetration in fire-rated interior panels and underhood applications.
- REACH-driven substitution cycles:ECHA's 2023 formaldehyde reclassification intensifies demand for low-emission novolac systems in electronics encapsulation and coatings.
- Aerospace interior fire standards:FAA and EASA smoke-toxicity regulations position phenolic prepregs as the default matrix for cabin sidewalls and overhead bins.
Market Restraints
- Feedstock cost volatility:Phenol pricing tracks benzene-crude differentials, exposing compounders to Gulf Coast petrochemical corridor supply disruptions.
- Formaldehyde exposure limits:OSHA permissible exposure limits and EU F-Gas Regulation constrain conventional resol production economics.
- Epoxy substitution in structural composites:Toughened epoxy systems with halogen-free flame retardants capture wind blade and rail applications.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Czech Republic automotive clusters offer underpenetrated demand for phenolic brake friction and filtration media.
- Bio-based phenol commercialization:Lignin-derived phenol pilot projects align with EU Green Deal carbon-border adjustment mechanisms.
- Digital formulation platforms:AI-accelerated catalyst screening converges with high-throughput rheometry to compress R&D cycles for custom novolac grades.
Industry Challenges
- Specialized resin chemist scarcity:Cross-linked thermoset formulation expertise concentrates among retiring cohorts at Rhineland and Gulf Coast technical centers.
- REACH registration dossier complexity:ECHA substance evaluation timelines delay new curative systems by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Phenolic Resin Market |
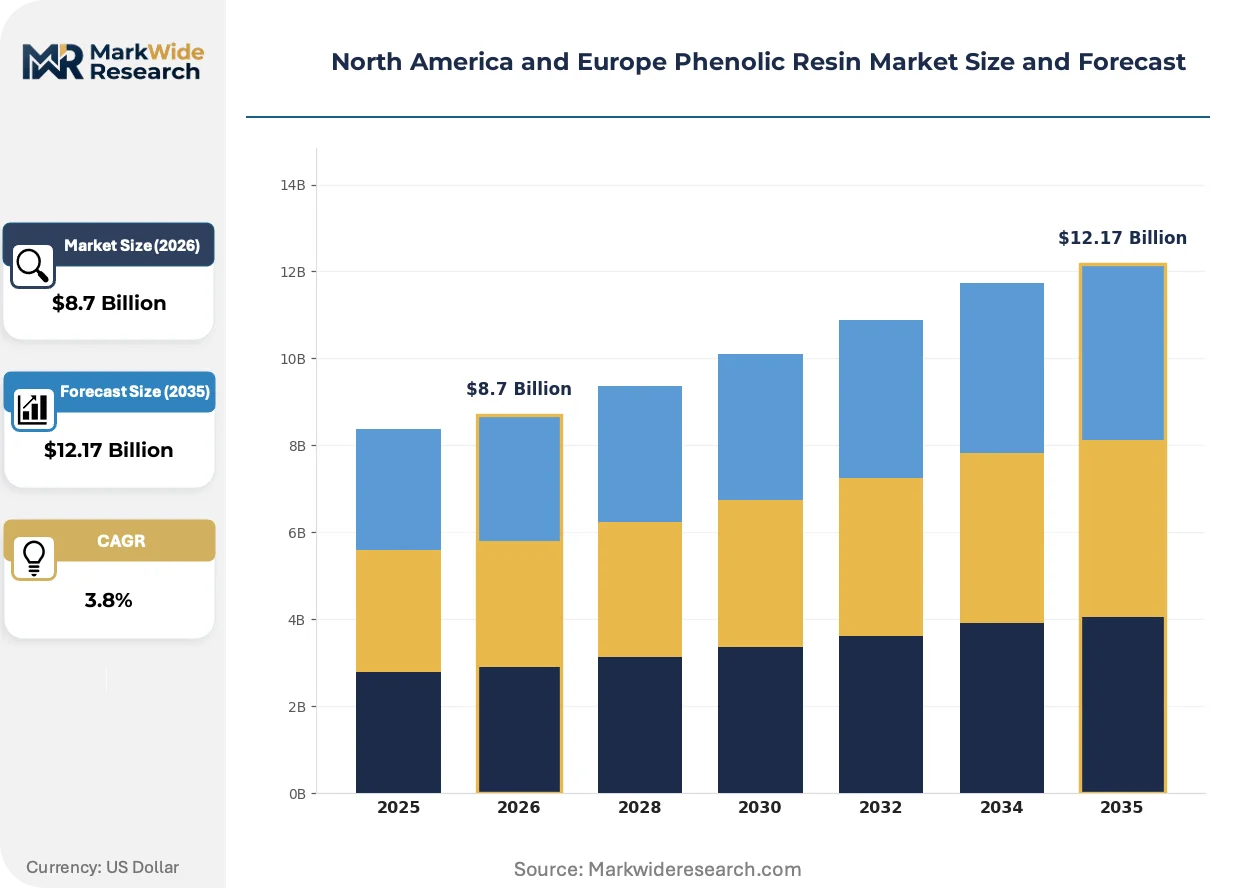
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.17 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Novolac, Resol, Hexamine, Others End User: Aerospace, Automotive, Electrical, Construction Application: Coatings, Adhesives, Composites, Insulation Form: Liquid, Powder, Granules, Sheets |
| Companies Covered | Prefere Resins Holding GmbH, Bakelite Synthetics, Akrochem Corporation, Allnex GMBH, BASF SE, Ashland Global Holdings Inc, ASK Chemicals GmbH, Georgia-Pacific Chemicals, Hexcel Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Phenolic Resin Market Trends and Innovations
Waterborne phenolic dispersion technology and closed-mold injection processes are displacing conventional solvent-based systems across both regions, compressing volatile organic compound footprints while enabling thinner-walled composite geometries.
Bio-sourced lignin phenol substitution is rendering obsolete petroleum-derived feedstock assumptions in European specialty resin production. German automotive Tier-1 suppliers now specify minimum bio-content thresholds for interior trim adhesives. This feedstock pivot is compressing cost premiums against conventional phenol while locking in long-term offtake agreements with Scandinavian pulp mill consortia.
ECHA's 2023 formaldehyde carcinogen classification triggers mandatory downstream user communication obligations across adhesives and insulation segments. German engineered wood producers face reformulation deadlines that favor novolac systems with lower free formaldehyde. French and Italian furniture manufacturers are accelerating pre-qualification of resorcinol-phenol co-condensate alternatives.
Consolidated buying by North American automotive OEMs compresses supplier qualification cycles from 24 months to 12 months. Tier-2 compounders now bypass distributors for direct mill-to-plant phenolic resin contracts. This disintermediation concentrates procurement leverage with Gulf Coast and Rhineland integrated producers who control captive phenol supply.
North America and Europe Phenolic Resin Market Segmentation
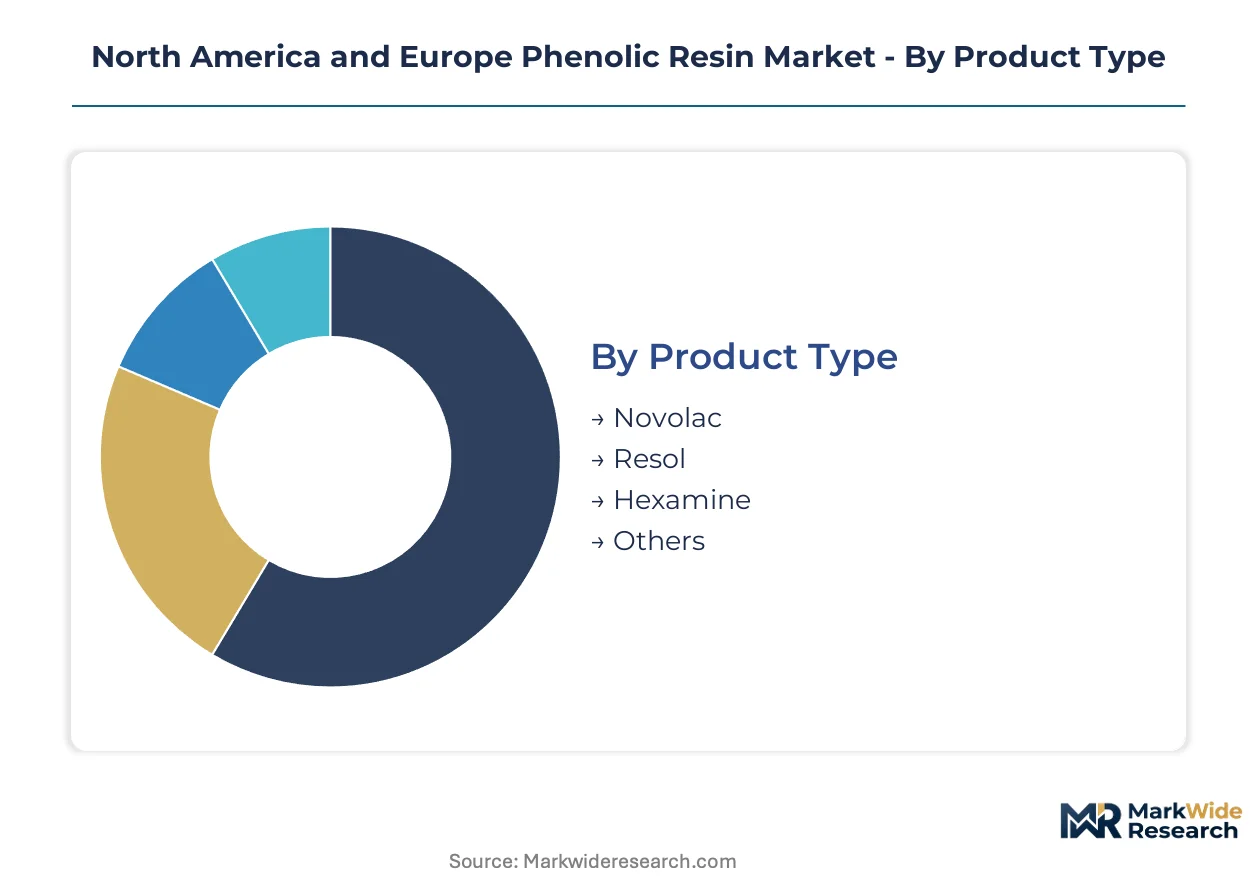
Phenolic resin formulation diversity demands precise segmentation mapping. Product chemistry, end-use specifications, application requirements, and physical form each govern distinct supply chain configurations and margin structures across the North America and Europe corridor.
Product Type:
Acid-catalyzed novolac systems and base-catalyzed resol variants anchor distinct thermal performance tiers and cure kinetics profiles.
- Novolac:Linear thermoplastic precursors requiring hexamine crosslinkers to achieve full thermoset properties. Novolac demand concentrates in Germany's electronics encapsulation sector where ECHA formaldehyde restrictions favor low-emission systems with controlled free phenol content.
- Resol:Self-curing thermosets with methylol-terminated chains enabling single-stage cure cycles. U.S. engineered wood producers along the Gulf Coast specify resol adhesives for OSB and plywood laminates under EPA TSCA emission standards.
- Hexamine:Solid curative additive enabling controlled crosslink density in novolac matrices. Hexamine procurement tracks urea-formaldehyde pricing volatility.
- Others:Modified phenolics including resorcinol-phenol co-condensates and cresol-based specialty grades for high-temperature friction applications.
Novolac commands the established base. The steepest expansion runs through resol systems in engineered wood consolidation.
End User:
Customer concentration patterns split between regulated transportation OEMs and specification-driven industrial fabricators.
- Aerospace:FAA and EASA fire-smoke-toxicity standards mandate phenolic prepregs for cabin interiors. Boeing and Airbus Tier-1 suppliers in Toulouse, Hamburg, and Charleston drive prepreg qualification cycles.
- Automotive:German KBA and U.S. NHTSA lightweighting targets expand phenolic composite penetration in brake friction, underhood thermal shields, and fire-rated interior panels. Volkswagen Group and Ford Motor specifications favor low-density syntactic foams.
- Electrical:Transformer insulation and printed circuit board substrates require novolac-based laminates with precise dielectric constants.
- Construction:Structural insulated panels and mineral wool binders consume resol formulations for thermal and acoustic insulation across Nordic and Central European building codes.
Automotive anchors volume concentration. Aerospace delivers the steepest margin expansion trajectory.
Application:
Functional requirements dictate resin selection across bonding, surface protection, and structural reinforcement use cases.
- Coatings:High-temperature corrosion barriers for industrial equipment and cookware substrates. Waterborne phenolic dispersions are displacing solvent systems under EU VOC directives.
- Adhesives:Engineered wood lamination dominates resol consumption. German producers face reformulation deadlines favoring low-emission novolac-hexamine systems.
- Composites:Phenolic prepregs and sheet molding compounds serve fire-rated transportation interiors. RTM and infusion processes enable thinner-walled geometries than compression molding.
- Insulation:Mineral wool and foam board binders require resol formulations with optimized cure speed for continuous production lines.
Adhesives maintain the volume base. Composites climb the fastest on aerospace and automotive substitution cycles.
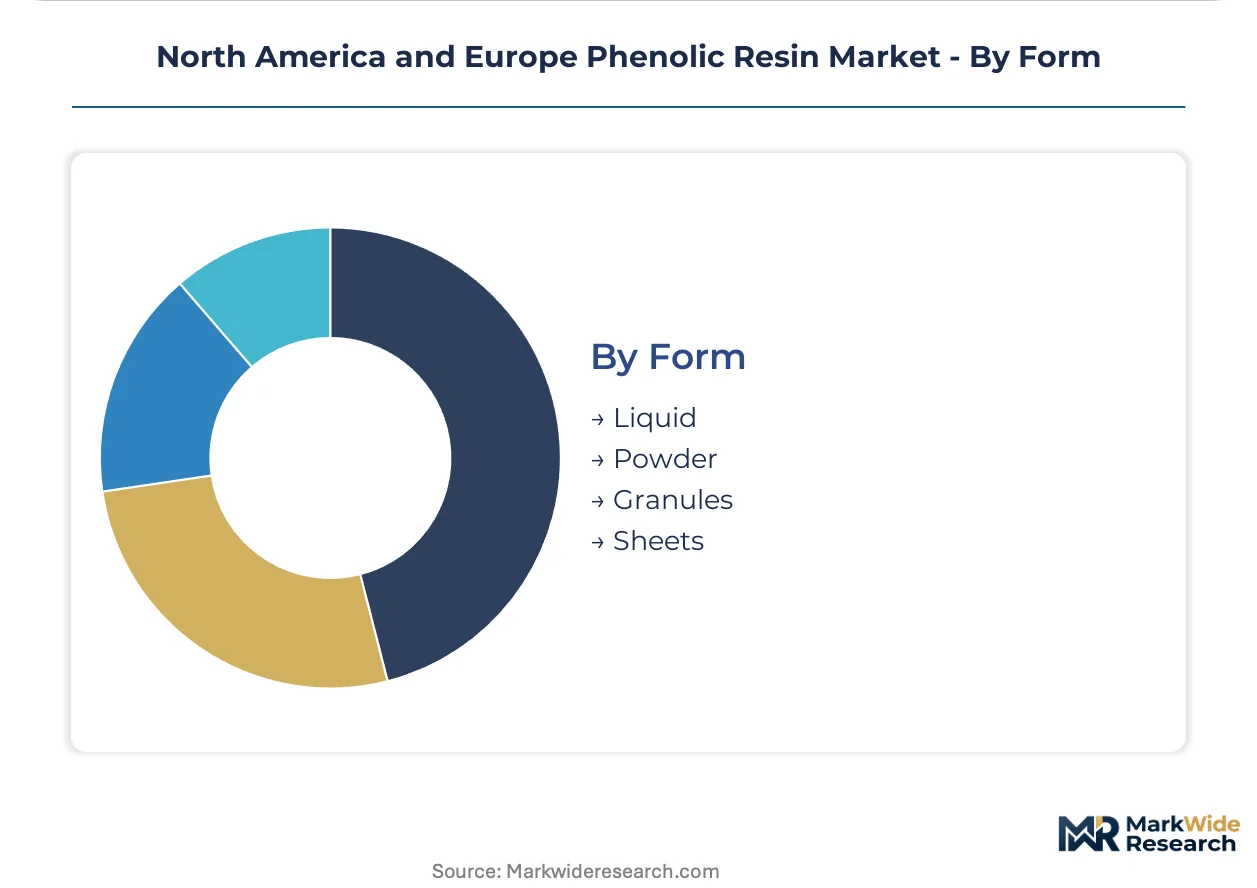
Form:
Physical state determines logistics economics, storage stability, and processing equipment compatibility.
- Liquid:Pumpable resols and novolac solutions for automated spray and roll-coating lines. Bulk tanker delivery minimizes packaging costs for high-volume wood adhesive accounts.
- Powder:Spray-dried novolac grades for dry-blend friction materials and powder coatings. Shelf stability exceeds liquid alternatives.
- Granules:Free-flowing hexamine-cured novolac for automated metering in brake pad and clutch facing production.
- Sheets:Prepreg tapes and fabric layers for aerospace autoclave processing. Cold storage requirements constrain distribution radius.
Liquid formulations dominate tonnage throughput. Sheet prepregs capture the steepest value-per-kilogram trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with Gulf Coast phenol producers while Rhineland refiners face margin compression from EU carbon-border adjustments. This asymmetry reshapes procurement leverage across the Atlantic corridor.
United States
Automotive lightweighting mandates from NHTSA expand phenolic composite demand for brake friction and underhood thermal shields. EPA TSCA formaldehyde emission standards force engineered wood producers toward low-emission resol reformulations. The Gulf Coast chemical corridor from Houston to Lake Charles anchors captive phenol supply for integrated resin producers.
Germany
KBA fuel-economy targets drive phenolic syntactic foam specifications from Volkswagen Group and BMW. ECHA's 2023 formaldehyde carcinogen reclassification triggers mandatory downstream communication obligations across adhesives segments. The Rhineland industrial cluster between Cologne and Ludwigshafen concentrates novolac production for electronics encapsulation.
France
Aerospace OEMs in Toulouse specify phenolic prepregs for cabin interior fire-smoke-toxicity compliance under EASA regulations. ANSM workplace exposure directives tighten formaldehyde limits in furniture manufacturing. The Occitanie region hosts Tier-1 composite fabricators serving Airbus supply chains.
United Kingdom
Construction insulation demand aligns with Building Regulations Part L thermal efficiency standards. HSE permissible exposure limits constrain conventional resol production economics. The Midlands manufacturing belt around Birmingham concentrates engineered wood panel production consuming bulk resol adhesives.
Poland
Automotive cluster expansion near Poznań and Wrocław creates underpenetrated demand for phenolic brake friction and filtration media. EU Green Deal carbon-border mechanisms incentivize bio-based phenol pilot investments. The Silesian industrial region attracts toll manufacturing partnerships from Western European resin producers.
North America and Europe Phenolic Resin Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation flexibility. The vendor base splits between integrated petrochemical giants with captive phenol supply and independent compounders dependent on merchant feedstock. Three archetypes dominate: Gulf Coast phenol-integrated producers, Rhineland refinery-linked specialists, and asset-light toll manufacturers. Consolidation pressure concentrates through backward integration into phenol and forward partnerships with automotive Tier-1s.
Among Rhineland-based integrated producers, Prefere Resins Holding GmbH exemplifies the refinery-linked archetype with captive feedstock access. Bakelite Synthetics represents the North American distribution-anchored model through rail-to-plant logistics control. Georgia-Pacific Chemicals occupies the barge-dependent southern U.S. market position with Mississippi River feedstock access.
| Leading Market Players |
|---|
| Prefere Resins Holding GmbH |
| Bakelite Synthetics |
| Akrochem Corporation |
| Allnex GMBH |
| BASF SE |
| Ashland Global Holdings Inc |
| ASK Chemicals GmbH |
| Georgia-Pacific Chemicals |
| Hexcel Corporation |
| Others |
Pricing and Supply Chain Analysis
The Gulf Coast chemical corridor from Houston to Lake Charles anchors North American phenol capacity, and its concentration of integrated refiners translates directly into procurement leverage for captive resin producers serving engineered wood and automotive OEMs. This geographic clustering of feedstock supply shapes margin structures across the Atlantic corridor, with barge-dependent logistics creating distinct cost tiers against rail-served inland compounders.
Pricing Analysis
Configured-to-order novolac systems for aerospace prepregs command substantial premiums over standard resol grades for engineered wood lamination, with price differentiation tracking certification tier and thermal performance specifications. Three-tier pricing structure across premium, standard, and economy levels reflects ECHA REACH compliance costs, volume scale commitments, and after-sales technical support bundling. Pricing pressure stems from benzene-crude volatility compressing compounder margins, while automotive Tier-1s exhibit lowest price sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement contracts as Gulf Coast phenol suppliers leverage supply-chain finance facilities to manage working capital cycles. Raw material sourcing draws from benzene-refinery outputs in the United States, merchant phenol from Rhineland crackers in Germany, and Scandinavian lignin pilot streams for bio-based grades. Single-source vulnerability concentrates around Houston Ship Channel disruptions, with distribution running through integrated rail-to-plant networks and bulk barge terminals serving southern U.S. markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formaldehyde regulatory divergence between Brussels and Washington fragments formulation standards, creating specialized niches for regional compounders with regulatory dossier expertise. This demand-side shift rewards players who can navigate ECHA substance evaluation timelines while maintaining EPA TSCA compliance.
For Market Incumbents: Entrench position through backward integration into captive phenol supply and accelerated bio-based phenol pilot investments. Defend against lignin-derived substitute entrants by locking long-term offtake agreements with Scandinavian pulp mill consortia. Prioritize REACH registration dossier completion ahead of ECHA evaluation deadlines to preserve formulation flexibility.
For New Entrants and Emerging Players: Poland's automotive cluster expansion near Poznań offers underpenetrated demand for phenolic brake friction and filtration media. Target toll manufacturing partnerships with Western European resin producers seeking eastern manufacturing footprint without capital deployment. Lead with digital formulation platforms offering AI-accelerated catalyst screening to compress R&D cycles for custom novolac grades.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized resin chemist scarcity concentrates expertise among retiring cohorts at Rhineland and Gulf Coast technical centers. Acquisition targets should display captive phenol access or established automotive Tier-1 qualification status. Monitor ECHA formaldehyde reclassification implementation as the inflection signal for substitution-driven demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol | Captive benzene-refinery supply from Gulf Coast producers locks margin stability against feedstock volatility. |
| Bio-Based Phenol Commercialization | Lignin-derived feedstock aligns with EU Green Deal carbon-border adjustments and German automotive bio-content mandates. |
| Digital Formulation Platforms | AI-accelerated catalyst screening converges with high-throughput rheometry to compress custom grade development cycles. |
| Eastern European Manufacturing Expansion | Poland and Czech Republic automotive clusters offer underpenetrated demand for brake friction and filtration applications. |
| REACH Registration Dossier Investment | ECHA substance evaluation timelines favor early movers with complete technical documentation for new curative systems. |
Research Methodology
Operator-level perspectives from plant managers at integrated phenol refiners, procurement leads at automotive Tier-1 suppliers, distribution channel partners serving engineered wood producers, and technical R&D directors at specialty resin compounders anchored the qualitative base. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and ECHA substance registration databases. Bottom-up volume modeling triangulated against top-down macroeconomic indicators to ensure consistency across the analysis window.
Scenario-bracketing framed the analytical approach, with baseline, upside, and downside cases reflecting regulatory implementation speed and feedstock cost trajectories across the projection horizon. Segmentation dimensions modeled included product chemistry tier, end-use industry vertical, physical form factor, and regional production hub clustering. CAGRs derived from historical volume progression adjusted for substitution elasticity and regulatory compliance cost pass-through, with aerospace qualification cycles and automotive lightweighting mandates serving as key demand-side forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in benzene-crude spreads, EU carbon-border adjustment implementation timing, or automotive production schedules would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and bio-based feedstock scale-up rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market