
 ASEAN Superabsorbent Polymers (SAP) Market | 2026-2036
ASEAN Superabsorbent Polymers (SAP) Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Superabsorbent Polymers (SAP) Market Outlook
Regional chemical distribution networks are tilting toward ASEAN manufacturing hubs as multinationals localize SAP sourcing. BASF SE leverages its integrated petrochemical complexes in Malaysia to sustain polymer feedstock advantages. Nippon Shokubai Co Ltd anchors its position through acrylic acid backward integration in Thailand. Sanyo Chemical Industries Ltd competes via specialized high-performance grades for medical applications.
Superabsorbent polymers are cross-linked polyacrylate networks capable of absorbing hundreds of times their dry mass in aqueous fluid, synthesized primarily through aqueous solution or inverse suspension polymerization of acrylic acid neutralized with sodium hydroxide. These materials function as fluid retention and distribution matrices across hygiene, agriculture, and medical end uses. Non-biodegradable SAPs currently dominate installed conversion capacity across ASEAN diaper plants, while biodegradable SAPs represent the fastest-expanding product category as regional sustainability mandates tighten. Personal care applications command the deepest margin pools due to stringent performance certification requirements and long-term supply contracts with multinational hygiene brands.
Thailand's Board of Investment, Indonesia's Ministry of Environment, and Vietnam's Ministry of Industry and Trade each shape SAP demand through diverging chemical safety and green manufacturing standards. REACH-aligned substance restrictions in EU-destined exports cascade into formulation requirements for ASEAN-based producers. Stakeholders must monitor regulatory fragmentation across member states while positioning for anticipated harmonization under the ASEAN Economic Community framework.
Market Dynamics
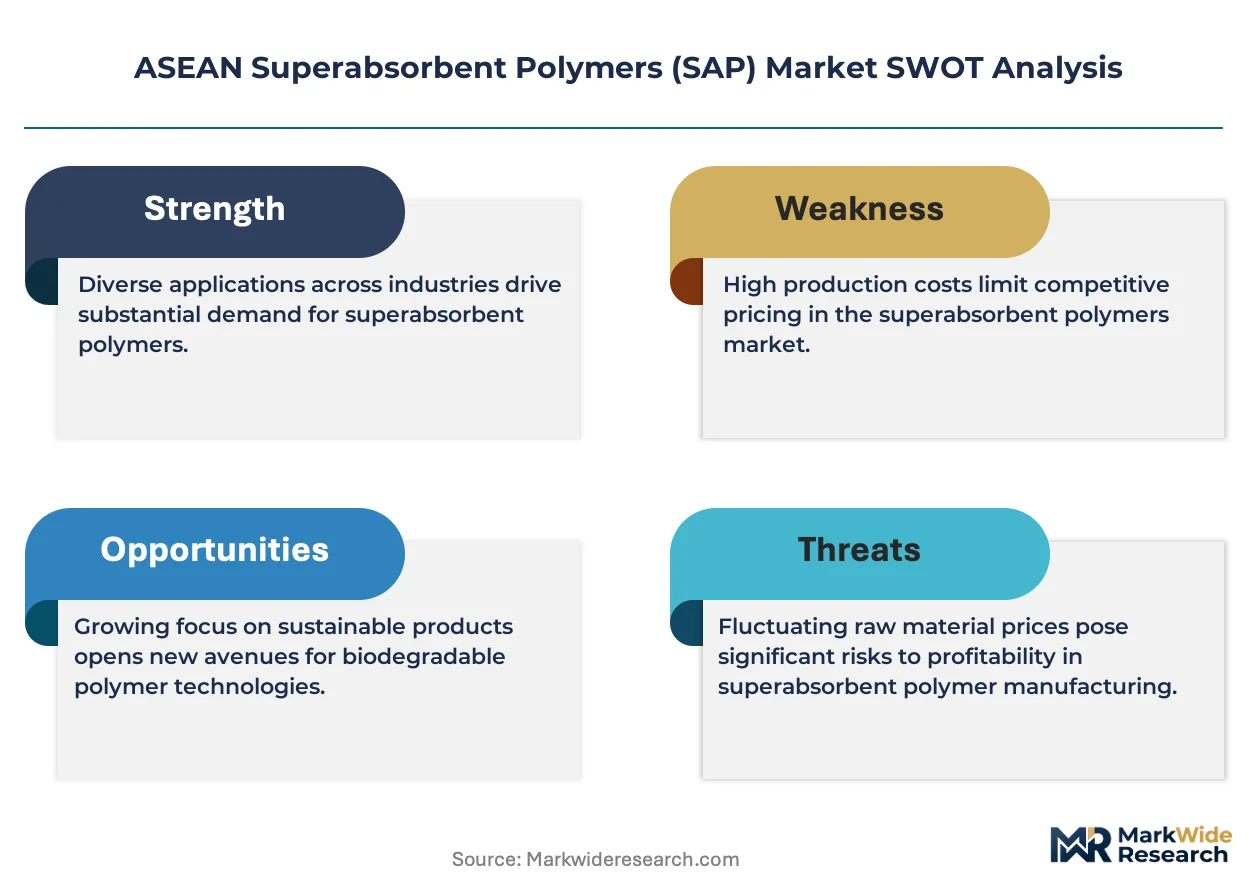
Thailand's Board of Investment green chemistry incentives are accelerating a feedstock transition toward bio-based acrylic acid, forcing polymer producers to reconfigure neutralization and cross-linking processes around renewable carbon streams rather than fossil-derived precursors.
Growth Catalysts
- Diaper Production Clustering:Vietnam's industrial zones near Ho Chi Minh City are attracting adult incontinence and baby diaper manufacturers, concentrating SAP demand within 200-kilometer procurement radii.
- EU REACH Alignment:ASEAN-based exporters to European markets must reformulate SAP grades to meet substance restriction standards, pulling regional production toward higher-certification output.
- Inverse Suspension Advances:Improved particle size distribution control in this polymerization method is enabling medical-grade SAP production with absorption kinetics matching wound-care specifications.
Market Restraints
- Acrylic Acid Feedstock Concentration:Nippon Shokubai's captive production in Thailand creates supply dependency for non-integrated compounders across ASEAN.
- Petrochemical Price Volatility:Propylene oxide and ethylene oxide feedstock costs swing with Singapore refinery output, compressing SAP margin predictability.
- Biodegradation Rate Limitations:Current bio-based SAPs achieve only partial disintegration in tropical soil conditions, constraining agricultural application expansion.
Strategic Opportunities
- Indonesia's Outer Island Manufacturing:Untapped industrial land near Surabaya offers lower-cost conversion capacity for hygiene product exporters.
- Medical Application Certification:ISO 10993 biocompatibility testing protocols for wound dressings create premium pricing tiers for compliant SAP grades.
- Digital Procurement Platforms:B2B chemical marketplaces are disintermediating traditional distributor networks for mid-volume SAP buyers in Malaysia.
Industry Challenges
- Process Engineer Scarcity:ASEAN polymerization facilities face recruitment gaps for aqueous solution reactor operators with acrylic acid handling certifications.
- Legacy Equipment Retrofit Costs:Converting suspension polymerization lines to biodegradable SAP production requires $2-4 million per reactor train in capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Superabsorbent Polymers (SAP) Market |
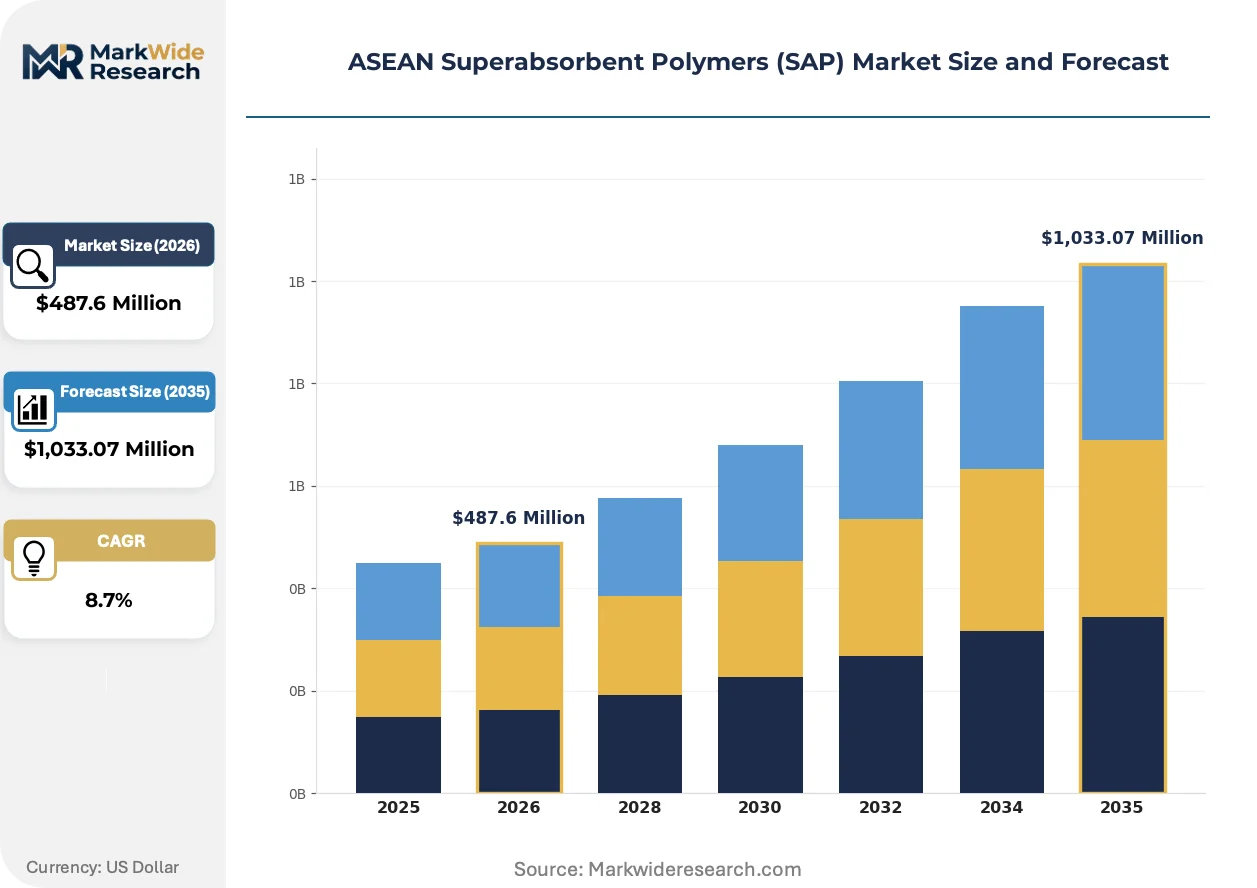
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVA, SAPs, Biodegradable SAPs, Non-Biodegradable SAPs Application: Health Care, Agricultural, Industrial, Personal Care Form: Granular, Powder, Sheet, Gel End User: Manufacturers, Distributors, Retailers, OEMs |
| Companies Covered | BASF SE, Evonik Industries AG, Nippon Shokubai Co Ltd, Kao Corporation, SONGWON, Chinafloc, Asia Resins Co Ltd, Qingdao Soco New Material Co Ltd, Sanyo Chemical Industries Ltd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Superabsorbent Polymers (SAP) Market Strategic Shifts
Digital twin modeling of polymerization kinetics is compressing pilot-to-scale timelines, while regulatory pressure on petrochemical feedstocks and buyer consolidation in hygiene manufacturing are reshaping competitive requirements across the value chain.
Enzymatic hydrolysis pretreatment of starch-backbone SAP precursors is virtualizing the traditional petroleum-dependent synthesis route. Thai research institutes and Malaysian petrochemical complexes are piloting these biocatalytic pathways at 500-liter demonstration scale. The technology is virtualizing capital allocation decisions, as producers weigh fermentation facility investments against conventional acrylic acid cracker expansions.
Thailand's Board of Investment tax holidays for green chemistry investments are mandating renewable content thresholds in SAP formulations. Manufacturers seeking these incentives must demonstrate 30% bio-based carbon content through ASTM D6866 testing. Personal care contract manufacturers in Rayong and Map Ta Phut are restructuring supply agreements to lock in bio-acrylic acid offtake.
Hygiene brand technical buyers are consolidating SAP qualification processes around single-source certification programs. Procter & Gamble and Kimberly-Clark regional procurement teams in Singapore now require simultaneous food-contact and medical-device grade documentation for premium tier supply. This concentration is most visible in Vietnam, where new diaper plants must achieve dual certification within 18 months of commissioning to secure multinational volume commitments.
ASEAN Superabsorbent Polymers (SAP) Market Segmentation
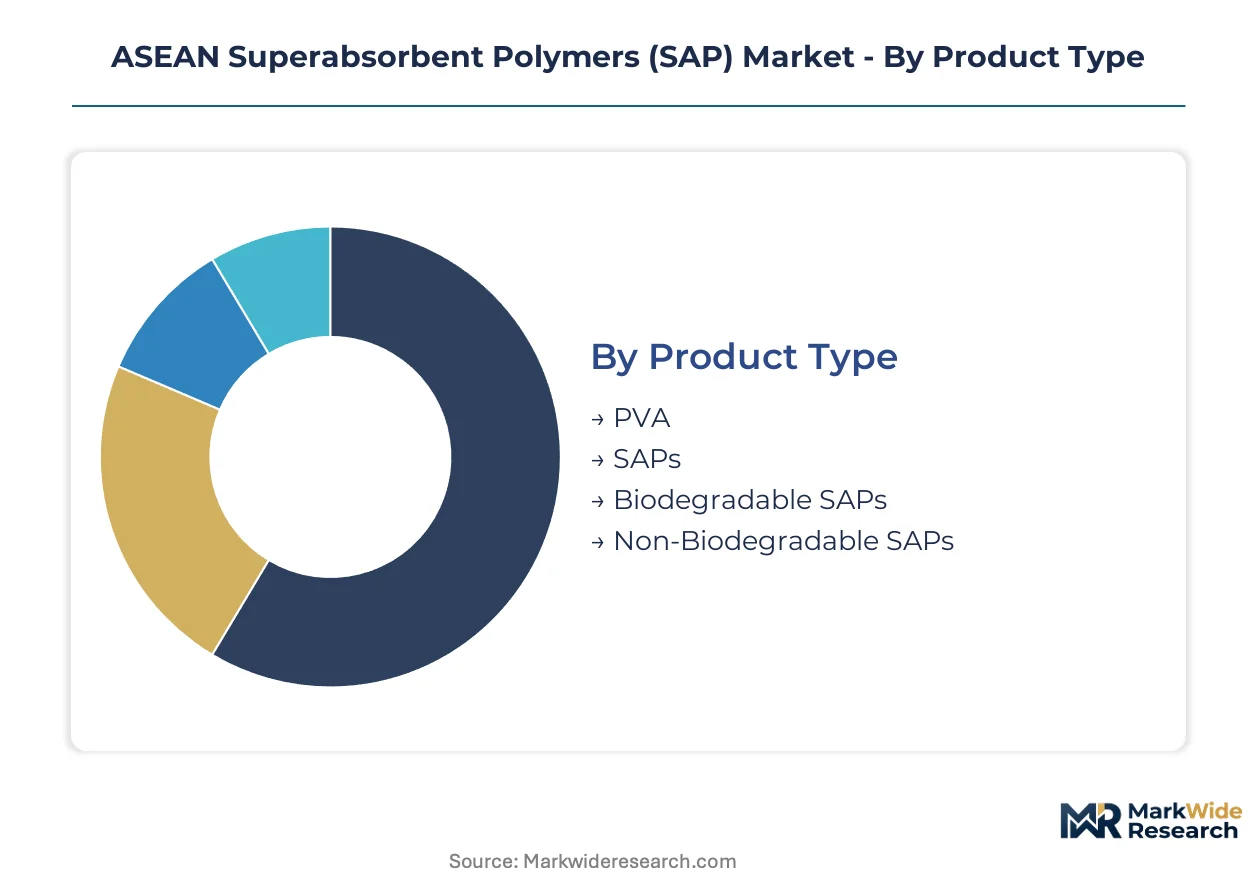
Superabsorbent polymers serve divergent performance requirements across hygiene, agriculture, and medical end uses, necessitating formulation-grade stratification. Segmentation reveals how procurement specifications, regulatory thresholds, and processing constraints partition the ASEAN market into distinct supply tiers.
Product Type:
Product differentiation spans synthetic durability, environmental degradability, and polyvinyl alcohol compatibility, with each chemistry commanding distinct feedstock sourcing and certification pathways.
- SAPs:Cross-linked polyacrylate networks synthesized via aqueous solution or inverse suspension polymerization dominate installed conversion capacity across ASEAN diaper plants. Thai manufacturers in Rayong industrial zones concentrate procurement of standard-grade material for high-volume hygiene contracts.
- Biodegradable SAPs:Starch-backbone and polysaccharide-based formulations achieve partial disintegration in tropical soil conditions, though current generation materials face rate limitations in agricultural deployment. Thailand's Board of Investment mandates 30% bio-based carbon content through ASTM D6866 testing for green chemistry tax incentives.
- Non-Biodegradable SAPs:Petrochemical-derived polyacrylates retain structural integrity across extended wear cycles, anchoring medical and premium personal care specifications where absorption retention outweighs disposal concerns.
- PVA:Polyvinyl alcohol variants offer film-forming characteristics for specialized coating applications, with demand concentrating in industrial moisture-barrier segments rather than fluid-retention uses.
The dominant share belongs to SAPs, while Biodegradable SAPs is closing the gap fastest.
Application:
Application segmentation tracks margin stratification across certification-intensive hygiene markets versus price-sensitive agricultural deployment.
- Personal Care:Diaper and adult incontinence manufacturing in Vietnam's Ho Chi Minh City industrial zones concentrates demand for high-absorption, low-residue grades. Procter & Gamble and Kimberly-Clark procurement teams require simultaneous food-contact and medical-device documentation for premium tier supply.
- Health Care:Wound dressing and surgical pad specifications demand ISO 10993 biocompatibility certification, creating premium pricing tiers for compliant SAP grades with controlled absorption kinetics.
- Agricultural:Soil moisture retention applications in Indonesia's palm oil plantations face constraints from incomplete biodegradation rates in tropical conditions, limiting expansion despite water scarcity pressures.
- Industrial:Cable filling, construction moisture control, and packaging desiccant uses prioritize cost efficiency over absorption precision, sourcing standard-grade material through B2B chemical marketplaces.
Personal Care commands the deepest margin pools, while Health Care is expanding most quickly on certification premiums.
Form:
Physical form determines processing compatibility across diaper conversion lines, agricultural spreading equipment, and medical sterilization protocols.
- Granular:Controlled particle size distribution enables uniform distribution in diaper cores and agricultural soil amendment, with inverse suspension polymerization advances improving medical-grade absorption kinetics.
- Powder:Fine particle grades integrate into compressed tablet and gel-matrix formulations for wound care and specialty packaging applications.
- Gel:Pre-hydrated forms serve medical and cosmetic applications requiring immediate moisture retention without dry-to-wet transition time.
- Sheet:Laminated structures bond SAP layers with nonwoven substrates for direct integration into hygiene product assembly lines.
Granular form holds the largest procurement volumes, while Gel is gaining share fastest on medical application expansion.
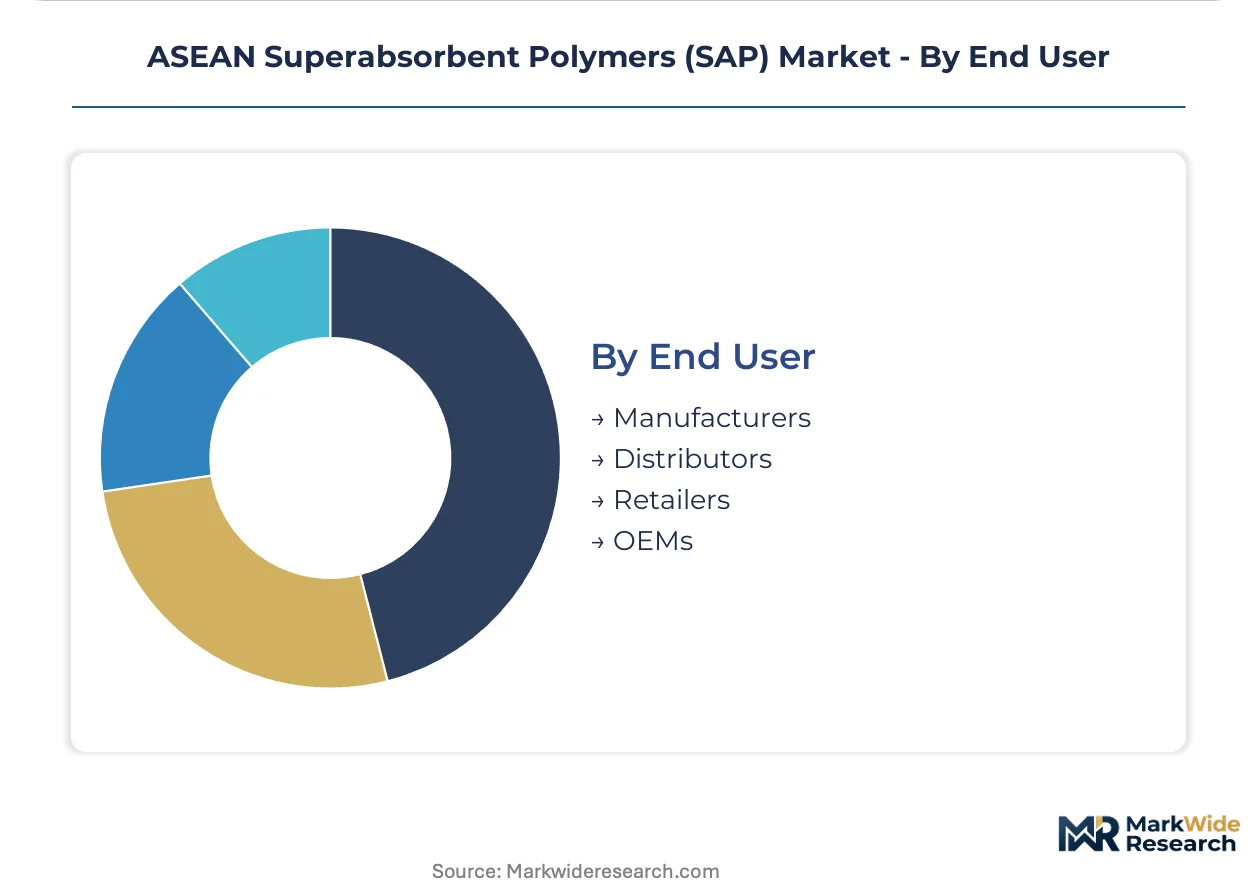
End User:
End user categories reflect supply chain position and volume scale, from integrated hygiene manufacturers to fragmented agricultural distributors.
- Manufacturers:Diaper and adult incontinence producers in Vietnam and Thailand negotiate long-term supply contracts with volume commitments and technical qualification requirements.
- OEMs:Original equipment manufacturers for medical devices and specialty hygiene products demand batch-level certification documentation and traceability protocols.
- Distributors:Regional chemical distribution networks in Malaysia and Indonesia aggregate mid-volume orders from compounders and smaller converters.
- Retailers:Direct-to-procurement sales for agricultural and consumer DIY applications operate through digital B2B platforms disintermediating traditional networks.
Manufacturers capture the dominant procurement share, while OEMs are climbing the fastest on medical-grade specification expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Map Ta Phut deepwater port and integrated petrochemical corridor in Thailand's Eastern Economic Corridor anchors ASEAN's SAP feedstock flows, connecting acrylic acid crackers to polymerization facilities across the region.
Thailand
Rayong and Map Ta Phut industrial zones concentrate the region's largest acrylic acid production base, supplying neutralized polyacrylate feedstock to diaper manufacturers. Thailand's Board of Investment green chemistry tax holidays mandate 30% bio-based carbon content for incentive eligibility, accelerating fermentation-derived acrylic acid pilot projects. BASF SE leverages its integrated petrochemical complex in Port of Laem Chabang to sustain polymer feedstock cost advantages for regional export.
Vietnam
Industrial zones within 200 kilometers of Ho Chi Minh City are attracting adult incontinence and baby diaper manufacturing, clustering SAP demand in the southern economic corridor. Vietnam's Ministry of Industry and Trade enforces chemical safety registration for imported monomers, creating compliance thresholds for non-integrated compounders. Binh Duong and Dong Nai provinces host new diaper plants requiring dual food-contact and medical-device certification within 18 months of commissioning.
Indonesia
Java-based personal care manufacturers in Surabaya and Jakarta are expanding SAP procurement as hygiene product output scales for domestic and export markets. Indonesia's Ministry of Environment imposes industrial wastewater standards on polymerization facilities, affecting process chemistry selection. Untapped industrial land near Surabaya offers lower-cost conversion capacity for hygiene product exporters targeting Australian and Middle Eastern markets.
Malaysia
Kertih and Gebeng petrochemical complexes support specialty SAP grades for medical and industrial moisture-control applications. Malaysia's Department of Environment administers hazardous substance licensing for acrylic acid handling and cross-linker storage. Johor Bahru chemical distribution networks are integrating digital B2B procurement platforms, disintermediating traditional distributor relationships for mid-volume compounders.
Singapore
The city-state functions as regional headquarters and technical qualification hub for multinational hygiene brand procurement teams. Singapore's National Environment Agency regulates chemical substance imports under the Environmental Protection and Management Act, aligning with EU REACH substance restrictions for re-export compliance. Jurong Island chemical traders coordinate bio-acrylic acid offtake contracts linking Thai fermentation pilots to Vietnamese diaper plants.
ASEAN Superabsorbent Polymers (SAP) Market Competitive Environment
On the supply side, the industry is consolidating around integrated petrochemical conglomerates and specialized polymerization specialists, with captive feedstock access determining cost position. Three strategic archetypes dominate: multinational chemical majors with backward integration into acrylic acid, regional compounders with formulation flexibility for mid-tier hygiene contracts, and bio-based technology developers pursuing enzymatic hydrolysis pathways. Competitive intensity centers on capacity expansion in Vietnam's industrial zones and strategic partnerships locking in bio-based feedstock offtake.
Among Germany-based chemical majors, BASF SE and Evonik Industries AG exemplify the integrated archetype with petrochemical complex ownership. Japanese specialists Nippon Shokubai Co Ltd and Sanyo Chemical Industries Ltd occupy positions emphasizing high-performance grades and medical application certification. These companies represent divergent strategic postures: European players leverage scale and feedstock integration, while Japanese competitors focus on technical qualification and premium tier supply relationships.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Nippon Shokubai Co Ltd |
| Kao Corporation |
| SONGWON |
| Chinafloc |
| Asia Resins Co Ltd |
| Qingdao Soco New Material Co Ltd |
| Sanyo Chemical Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Acrylic acid feedstock concentration in Thailand's Map Ta Phut corridor determines both pricing tier spreads and supply chain shape, as Nippon Shokubai's captive production creates single-source dependency that compresses margin predictability for non-integrated compounders across ASEAN.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates SAP procurement, with medical-grade ISO 10993 certified material commanding substantial premiums over diaper-grade standard material and industrial economy tiers. Price differentiation rests on certification level and volume scale, as Procter & Gamble and Kimberly-Clark long-term contracts anchor premium tier stability while mid-volume buyers face heightened price sensitivity. Cost compression in standard-grade material is intensifying because Vietnamese diaper plants are consolidating procurement around dual-certified single sources. Agricultural distributors remain most price-sensitive, sourcing through B2B chemical marketplaces that disintermediate traditional networks.
Supply Chain Analysis
EU REACH substance restrictions limiting re-export flows force ASEAN-based producers to reformulate around higher-certification output, reshaping regional production decisions. Feedstock supply concentrates in Thailand, Singapore, and Malaysia, with propylene oxide and ethylene oxide drawing from Singapore refinery output. Raw material dependencies include acrylic acid monomers, sodium hydroxide neutralizing agents, and cross-linker chemicals. Single-source vulnerability runs through Nippon Shokubai's Thai acrylic acid production. Distribution runs through Johor Bahru chemical networks and digital B2B platforms serving mid-volume Malaysian compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a petrochemical cyclical recovery justified by propylene oxide feedstock price normalization following Singapore refinery output stabilization.
For Market Incumbents: Build backward integration moats through bio-acrylic acid fermentation facility investments that lock in Thailand's Board of Investment green chemistry tax holidays. Defend against emerging bio-based technology developers by accelerating ASTM D6866 certification pipelines. Prioritize capacity addition in Vietnam's Binh Duong province to capture clustering diaper manufacturing demand. Secure long-term supply contracts with Procter & Gamble and Kimberly-Clark regional procurement teams before dual-certification deadlines tighten. For New Entrants and Emerging Players: Indonesia's outer island manufacturing zones near Surabaya represent the most penetrable entry point, offering lower-cost conversion capacity for hygiene product exporters targeting Australian and Middle Eastern markets. Agricultural SAP applications in Indonesian palm oil plantations present secondary white-space despite biodegradation rate limitations. Target digital B2B procurement platforms as primary go-to-market channel to disintermediate established Malaysian distributor networks. For Investors and Strategic Acquirers: Thailand's 30% bio-based carbon content mandate reshapes the acquisition landscape toward fermentation-derived acrylic acid technology developers. Five-to-ten year viability favors integrated producers with captive feedstock and green chemistry certification pathways. Target acquisition archetype: regional compounders with formulation flexibility and existing hygiene brand technical qualifications. Monitor Vietnam Ministry of Industry and Trade chemical safety registration enforcement as inflection indicator for import-dependent compounder distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Acrylic Acid | Thailand's Board of Investment tax holidays reward renewable carbon content thresholds. |
| Dual Certification Investment | ISO 10993 biocompatibility plus food-contact documentation unlocks premium tier pricing. |
| Vietnam Industrial Zone Capacity Expansion | Binh Duong and Dong Nai provinces cluster diaper manufacturing within 200-kilometer procurement radii. |
| Digital B2B Platform Partnership | Johor Bahru chemical networks disintermediate traditional distributor relationships for mid-volume buyers. |
| Long-term Supply Agreement Restructuring | Rayong and Map Ta Phut contract manufacturers lock in bio-acrylic acid offtake for green chemistry incentives. |
Study Parameters
The analysis maps synthetic SAP, biodegradable SAP, and medical-grade formulation sub-sectors, each validated through polymerization plant managers, hygiene product procurement leads, and chemical distribution channel partners. Primary interviews with technical R&D directors at Thai and Malaysian petrochemical complexes combined with secondary validation from customs and trade data, ASEAN chemical industry association reports, and SEC 10-K filings from multinational producers. Bottom-up capacity and demand modeling triangulates against top-down market sizing across the analysis window.
Assumptions held fixed include Thailand's 30% bio-based carbon content mandate and Vietnam's dual-certification procurement requirements, while propylene oxide feedstock costs and biodegradation technology maturation were varied. Segmentation dimensions modeled include product chemistry tier, end-use application, physical form factor, and regional production hub clustering. CAGRs were derived from production capacity buildout timelines and hygiene brand volume commitment trajectories, incorporating enzymatic hydrolysis pilot scale progress and inverse suspension polymerization yield improvements.
Practitioners should monitor Thailand Board of Investment incentive renewal schedules and Vietnam Ministry of Industry and Trade chemical safety registration enforcement for early signals. Forecasts reflect assumptions about bio-acrylic acid fermentation scale-up economics and REACH-aligned substance restriction stability. Material shifts in EU-ASEAN re-export regulatory alignment or breakthrough biodegradation rate improvements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Global Colored PU Foams Market