
 Europe Polycarbonate (PC) Market | 2026-2036
Europe Polycarbonate (PC) Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polycarbonate (PC) Market Insights
Optical-grade polycarbonate specifications is reorganizing procurement priorities across European manufacturing chains. Covestro AG leverages its Dormagen and Antwerp production complexes to sustain captive supply of high-purity resin grades for automotive glazing. SABIC anchors its European position through specialized compounding operations in the Netherlands that serve medical device OEMs. Trinseo S.A. differentiates via dedicated extrusion lines serving safety shield and display case fabricators in France and Italy.
Polycarbonate is a thermoplastic polymer synthesized from bisphenol A and phosgene, featuring glass-like transparency with impact resistance roughly 250 times that of silicate glass and service temperatures extending to approximately 145 degrees Celsius. Its primary industrial purpose centers on substituting glass and metal in weight-critical, impact-sensitive, or optically demanding applications. Solid sheets dominate value capture in architectural glazing and protective barriers where thickness precision and UV stabilization command premium positioning. Multiwall sheets represent the fastest-expanding product category, driven by greenhouse construction in Spain and the Netherlands where thermal insulation requirements intensify. Medical Devices as an end-user segment concentrates margin pools around sterilization-resistant grades that must satisfy EMA and MDR compliance pathways.
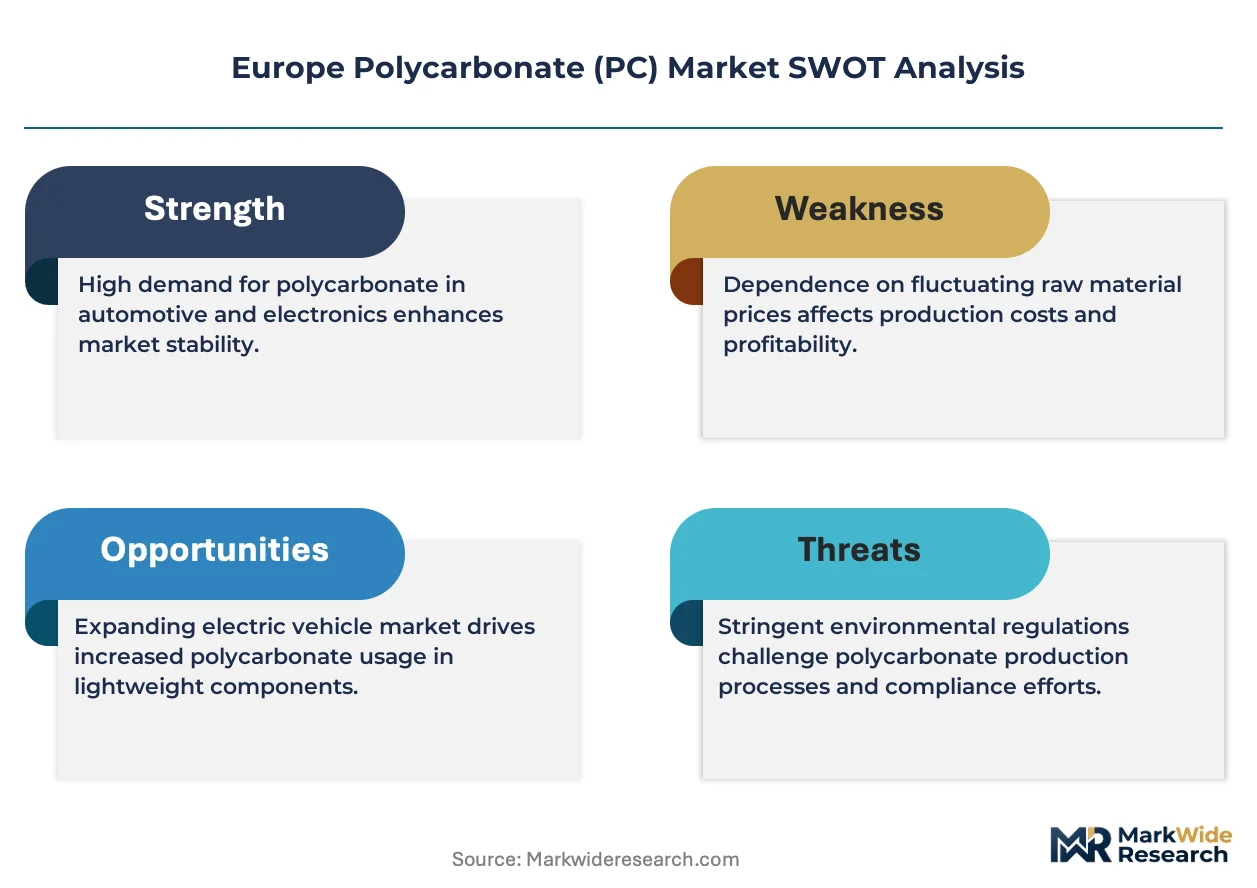
REACH chemical registration requirements and the EU F-Gas Regulation constrain feedstock availability and compel reformulation of flame-retardant additive packages across European polycarbonate supply chains. CE marking under the Construction Products Regulation governs market access for sheet products deployed in building envelopes and public infrastructure. ECHA substance evaluation protocols are tightening scrutiny of bisphenol A alternatives, forcing resin producers to accelerate next-generation copolymer development. Stakeholders must monitor regulatory pre-consultation timelines and position R&D investment ahead of anticipated restriction proposals rather than reacting to enacted measures.
Market Dynamics
The EU F-Gas Regulation and REACH substance evaluation protocols are forcing resin producers to accelerate reformulation of flame-retardant additive packages while simultaneously constraining feedstock availability across European compounding operations.
Growth Catalysts
- Automotive lightweighting mandates:German and French OEM procurement teams are specifying optical-grade polycarbonate for headlamp lenses and panoramic roof modules to meet fleet CO2 reduction targets under EU Green Deal implementation timelines.
- REACH compliance pathways:ECHA pre-consultation timelines for bisphenol A alternatives are creating first-mover advantages for producers with next-generation copolymer R&D pipelines already validated.
- Benelux construction corridors:Multiwall sheet demand from greenhouse operators in the Netherlands and Belgium is absorbing capacity expansion as thermal insulation specifications tighten under national building codes.
Market Restraints
- Phosgene feedstock concentration:European phosgene supply concentrates at a limited number of chlor-alkali complexes, exposing resin producers to input cost volatility and force majeure risk.
- CE marking friction:Construction Products Regulation testing and certification timelines for solid sheet products extend market access cycles by 12-18 months for new entrants.
- Glass substitution economics:Float glass price compression in Southern European markets periodically narrows the total-cost-of-ownership advantage for architectural glazing applications.
Strategic Opportunities
- Spanish greenhouse buildout:Almería and Murcia agricultural zones are expanding protected cultivation acreage, generating demand for UV-stabilized multiwall sheet with customized light-diffusion properties.
- Medical device MDR compliance:Sterilization-resistant grades satisfying EMA and MDR pathways command margin premiums from surgical instrument and drug delivery device OEMs.
- Digital manufacturing integration:Extrusion lines with inline spectrophotometric quality control are enabling lot-size-one production for safety shield fabricators serving Italian machine tool builders.
Industry Challenges
- Specialized compounding talent scarcity:Formulation chemists with expertise in halogen-free flame retardant systems are concentrated at incumbent producers, constraining technical service expansion.
- Legacy equipment retrofit costs:Existing extrusion assets require capital-intensive upgrades to process next-generation copolymers with modified melt rheology profiles.
- Supply chain reconfiguration complexity:Diversifying phosgene sourcing beyond captive production necessitates hazardous materials logistics capabilities that few third-party providers possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polycarbonate (PC) Market |
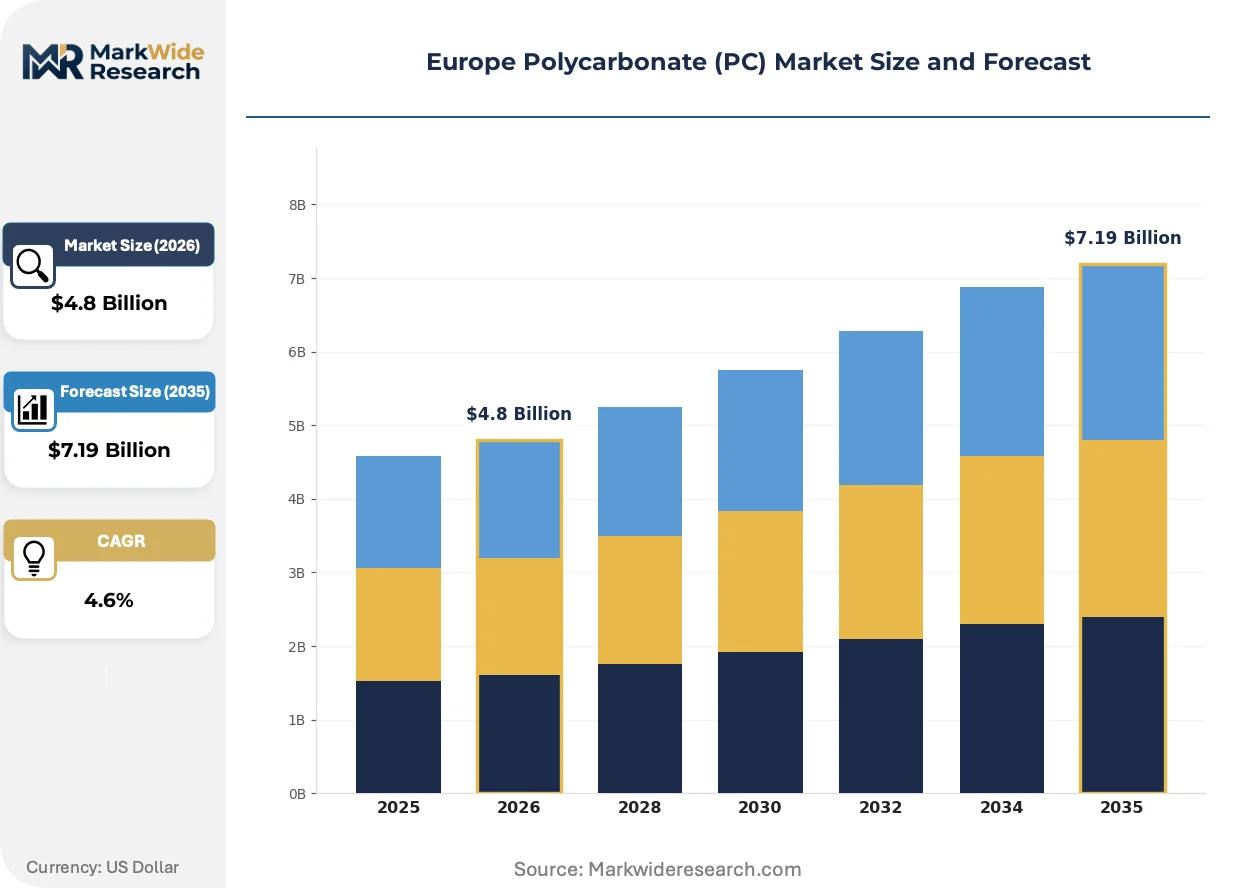
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Sheets, Polycarbonate Films, Multiwall Sheets, Cellular Panels End User: Automotive, Construction, Electrical, Medical Devices Thickness: Thin, Medium, Thick, Ultra-Thick Application: Lighting, Safety Shields, Greenhouses, Display Cases |
| Companies Covered | Covestro AG, SABIC, Trinseo S.A., Teijin Limited, Mitsubishi Chemical Corporation, LG Chem, BASF SE, LOTTE Chemical Corporation, Röchling Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polycarbonate (PC) Market Trends and Innovations
European polycarbonate value chains are reorganizing around three concurrent pressures: feedstock substitution imperatives, digital quality assurance integration, and procurement model compression toward direct mill relationships.
Copolymer formulations with enhanced hydrolytic stability are supplanting standard bisphenol A homopolymers in automotive under-hood applications. Tier-1 suppliers in Stuttgart and Munich are qualifying these grades for battery housing modules and thermal management components. The shift is compressing qualification timelines for conventional resin grades while expanding specification windows for high-purity optical variants.
REACH substance evaluation protocols are tightening scrutiny of halogenated flame retardant additives, compelling compounders to validate phosphorus-based and mineral filler alternatives. ECHA restriction proposals anticipated for 2026-2027 are accelerating pre-submission data generation across Dormagen and Antwerp production complexes. Medical device and electrical housing segments are prioritizing additive packages with existing MDR and RoHS compliance documentation.
Direct mill procurement contracts are displacing distributor-mediated spot purchasing among large automotive and construction OEMs. Safety shield and display case fabricators in France and Italy are consolidating supplier relationships to secure volume commitments and technical co-development access. The concentration is most visible in German automotive clusters, where glazing system integrators now maintain single-source or dual-source resin supply agreements with dedicated extrusion line allocation.
Europe Polycarbonate (PC) Market Segmentation
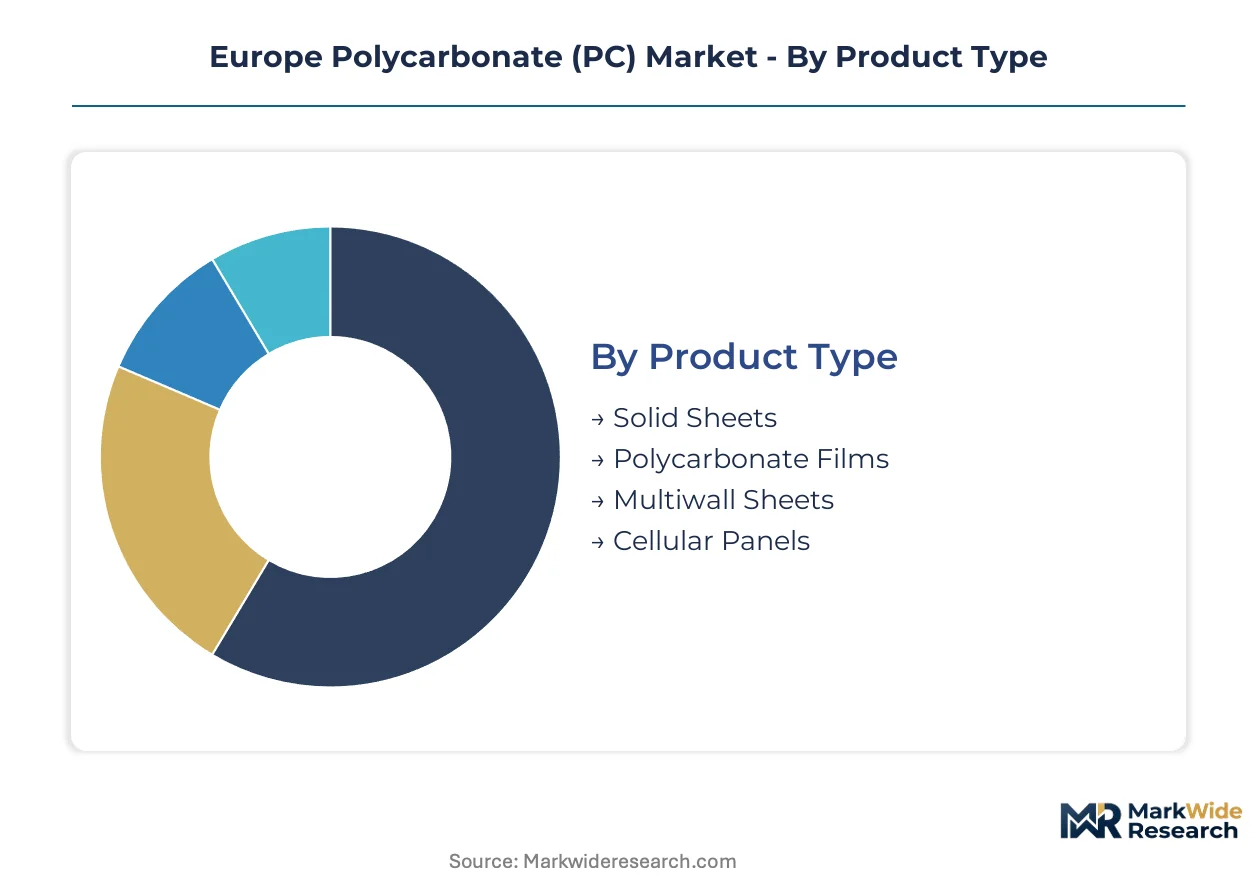
European polycarbonate demand fragments across specification tiers that face divergent substitution pressures from glass, acrylic, and emerging bio-polymers. Procurement teams in German automotive clusters and Benelux construction corridors are compressing supplier lists around segments that demonstrate clear total-cost-of-ownership advantages.
Product Type:
Substitution pressure from float glass and PMMA acrylic concentrates most intensely on commodity sheet grades, while specialized optical and thermal variants defend position through performance differentiation.
- Solid Sheets:Monolithic extruded panels with precise thickness tolerance and UV stabilization packages command premium positioning in architectural glazing and protective barriers. German construction specifiers in Munich and Frankfurt specify these for public infrastructure where impact resistance and optical clarity outweigh glass alternatives despite higher material cost.
- Multiwall Sheets:Twin-wall and triple-wall configurations with internal rib structures deliver thermal insulation values superior to single-layer alternatives. Greenhouse operators in the Netherlands and Almería, Spain specify these for protected cultivation where energy efficiency mandates intensify, driving the steepest capacity absorption among all product categories.
- Polycarbonate Films:Thin-gauge calendered or extruded membranes serve as interlayers and surface protection in automotive interiors and electronic displays.
- Cellular Panels:Macro-cellular structures with enhanced stiffness-to-weight ratios deploy in temporary structures and modular construction systems.
Solid sheets retain volume leadership across European polycarbonate consumption; multiwall sheets hold the steepest expansion curve.
End User:
Margin capture concentrates in segments where regulatory compliance pathways create qualification barriers that filter out commodity suppliers.
- Automotive:Optical-grade specifications for headlamp lenses and panoramic roof modules absorb resin from Dormagen and Antwerp production complexes. Stuttgart and Munich OEM procurement teams specify these grades to meet fleet CO2 reduction timelines under EU Green Deal implementation.
- Medical Devices:Sterilization-resistant grades satisfying EMA and MDR compliance pathways command margin premiums from surgical instrument and drug delivery device OEMs in Germany and Switzerland.
- Construction:Building envelope applications under CE marking requirements drive specification of UV-stabilized solid and multiwall configurations.
- Electrical:Flame-retardant compounded grades serve housing and enclosure applications where RoHS and REACH restrictions on halogenated additives force reformulation.
Construction maintains the broadest volume base; medical devices deliver the highest margin per kilogram.
Thickness:
Processing economics and application requirements stratify demand across gauge ranges that correlate with end-use performance specifications.
- Thin:Films and membranes below 2mm serve laminating, surface protection, and flexible electronics applications where optical clarity and formability predominate.
- Medium:2-6mm gauges balance structural integrity with thermoformability for safety shields and machine guarding in Italian and French industrial equipment markets.
- Thick:6-12mm solid sheets deliver ballistic resistance and acoustic damping for security glazing and transportation infrastructure.
- Ultra-Thick:Extruded plates above 12mm enable machined components for semiconductor handling equipment and precision tooling fixtures.
Medium thickness commands the widest application spread; ultra-thick segments generate the most specialized technical service requirements.
Application:
Customer procurement models diverge sharply between project-based construction demand and program-based automotive supply agreements.
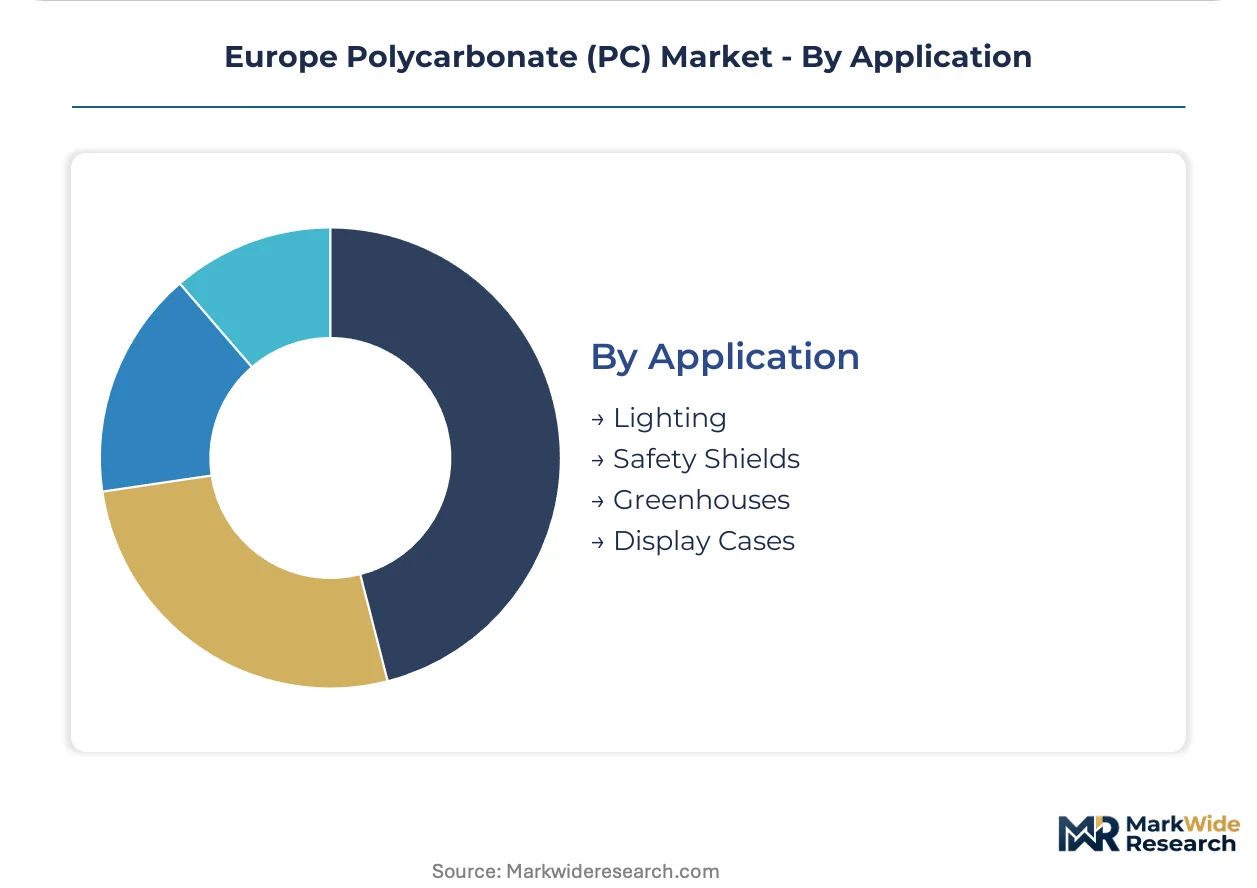
- Greenhouses:UV-stabilized multiwall configurations with customized light-diffusion properties serve protected cultivation expansion in Almería, Murcia, and the Netherlands. National building code thermal efficiency mandates accelerate specification of high-insulation variants.
- Safety Shields:Impact-resistant barriers for machine tools and industrial automation equipment concentrate demand among Italian fabricators serving metalworking and packaging machinery OEMs.
- Lighting:Optical-grade diffusers and lens components compete with PMMA in LED fixture applications where heat resistance provides polycarbonate advantage.
- Display Cases:Museum, retail, and hospitality applications specify anti-reflective and abrasion-resistant surface treatments.
Greenhouse applications absorb capacity expansion fastest; safety shields maintain the most concentrated geographic demand cluster.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosgene supply concentrates at chlor-alkali complexes in Germany and the Netherlands, anchoring resin production capacity near the Rhine-Antwerp corridor. German automotive clusters and Benelux construction corridors absorb the majority of regional output. Regulatory differentiation across member states shapes sub-regional demand profiles.
Germany
Stuttgart and Munich OEM procurement teams specify optical-grade polycarbonate for headlamp lenses and panoramic roof modules. The KBA enforces fleet CO2 reduction timelines that accelerate lightweight material qualification. Covestro AG operates its Dormagen production complex to sustain captive supply of high-purity resin grades for automotive glazing applications.
Netherlands
Greenhouse operators in the Randstad and Brabant regions specify UV-stabilized multiwall sheet with customized light-diffusion properties. National building codes mandate thermal efficiency standards that intensify insulation specifications. SABIC anchors its European position through specialized compounding operations serving medical device OEMs with sterilization-resistant grades.
France
Safety shield and display case fabricators in Île-de-France and Auvergne-Rhône-Alpes consolidate supplier relationships for volume commitments. The EU Green Deal implementation compresses procurement timelines for sustainable material alternatives. Trinseo S.A. differentiates via dedicated extrusion lines serving machine tool builders and museum fixture manufacturers.
Italy
Metalworking and packaging machinery OEMs in Lombardy and Emilia-Romagna source impact-resistant barriers for industrial automation equipment. CE marking under the Construction Products Regulation governs market access for protective glazing in public infrastructure. Italian fabricators maintain concentrated geographic demand for medium-gauge thermoformed safety components.
Spain
Almería and Murcia agricultural zones expand protected cultivation acreage, generating demand for high-insulation greenhouse configurations. National thermal efficiency mandates align with EU F-Gas Regulation substitution timelines for conventional glazing materials. Spanish greenhouse buildout represents the fastest-expanding demand vector for multiwall sheet capacity absorption.
Europe Polycarbonate (PC) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European polycarbonate value chain. Integrated resin producers with captive phosgene supply dominate upstream high-purity grades, while specialized compounders capture margin pools in medical and electrical segments. The competitive terrain stratifies into three archetypes: integrated chemical conglomerates, regional compounding specialists, and downstream extrusion fabricators. Dominant competitive moves include backward integration into feedstock security and strategic partnerships with automotive glazing system integrators.
Among integrated chemical conglomerates, Covestro AG and SABIC exemplify the scale-driven archetype with Rhine-Antwerp production corridor positioning. Trinseo S.A. occupies a specialist tier focused on extrusion-based fabrication serving safety shield and display case markets. These three entities represent the primary competitive anchors around which procurement consolidation and technical co-development relationships are reorganizing across German automotive clusters and Benelux construction corridors.
| Leading Market Players |
|---|
| Covestro AG |
| SABIC |
| Trinseo S.A. |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| LG Chem |
| BASF SE |
| LOTTE Chemical Corporation |
| Röchling Group |
| Others |
Pricing and Supply Chain Analysis
Phosgene-to-resin substitution away from captive chlor-alkali complexes is simultaneously compressing supply geography toward the Rhine-Antwerp corridor and fragmenting pricing power between integrated producers and specialized compounders. This dynamic intensifies margin bifurcation as optical-grade specifications absorb premium positioning while commodity sheet grades face float glass substitution pressure.
Pricing Analysis
CE marking under the Construction Products Regulation dictates the pricing tier structure across European polycarbonate markets. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade sterilization-resistant resin from construction multiwall sheet and commodity film grades. Cost compression in greenhouse multiwall segments is intensifying because Spanish and Dutch operators consolidate volume procurement. Construction OEMs exhibit highest price sensitivity due to project-based bidding cycles, while medical device manufacturers accept premium positioning for MDR-compliant additive packages.
Supply Chain Analysis
Inventory cycles for optical-grade resin extend lead times by 12-18 months for automotive glazing qualification programs. Phosgene feedstock concentrates in Germany and the Netherlands, with compounding operations drawing from chlor-alkali complexes at Dormagen and Antwerp. Raw material dependencies center on bisphenol A, phosgene, and specialized flame-retardant additive packages. Single-source vulnerability pervades phosgene logistics given hazardous materials transport restrictions. Distribution runs through direct mill contracts displacing distributor-mediated spot purchasing among German automotive clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with halogen-free flame-retardant expertise represent the critical capability gap constraining technical service expansion across European compounding operations. This scarcity concentrates margin capture among incumbents with validated R&D pipelines while elevating acquisition premiums for specialized talent pools.
For Market Incumbents: Compound captive phosgene supply advantages through backward integration into additive package manufacturing at Antwerp and Dormagen complexes. Accelerate next-generation copolymer validation ahead of ECHA restriction proposals to defend position against bio-polymer substitution threats in automotive under-hood applications. For New Entrants and Emerging Players: CE marking fast-track services for greenhouse multiwall sheet represent the most penetrable entry vector given Spanish and Dutch capacity absorption trends. Target Almería agricultural zones with UV-stabilized light-diffusion configurations. Pursue technical co-development partnerships with Italian safety shield fabricators seeking lot-size-one extrusion capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized compounders with validated MDR and RoHS compliance documentation. Long-term viability hinges on feedstock security and regulatory anticipation capabilities rather than scale alone. Watch ECHA pre-consultation timelines for bisphenol A alternatives as the inflection signal for copolymer R&D valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive flame-retardant production at Antwerp insulates margin from REACH reformulation cycles. |
| Green Manufacturing Transition | Halogen-free compounding aligns with EU Green Deal procurement timelines for German OEMs. |
| Long-term Supply Agreement | Direct mill contracts with Stuttgart glazing integrators compress distributor intermediation. |
| Joint Venture | Spanish greenhouse buildout partnerships secure volume commitments from Almería operators. |
| Capacity Expansion | Multiwall sheet lines in the Netherlands capture thermal insulation mandate acceleration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs data, Cefic industry reports, SEC filings, and ECHA restriction proposals. Plant managers at Dormagen and Antwerp complexes, procurement leads at Stuttgart OEMs, distribution channel partners in Benelux construction corridors, and technical R&D directors provided qualitative inputs. Bottom-up demand modeling across greenhouse operators and automotive glazing integrators triangulates against top-down resin production capacity assessments.
Segmentation dimensions modeled include product type tier, end-use industry concentration, thickness gauge specification, and regional production hub clustering. Value projections across the analysis window derive from CAGR extrapolation anchored to automotive lightweighting mandate implementation and thermal efficiency building code adoption. Forecast inputs incorporate phosgene supply concentration risk and EMA/MDR compliance pathway timelines for medical device grades.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and REACH substance evaluation timelines; material deviation in regulatory pre-consultation outcomes would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Polyvinyl Chloride Resins Market