
 Terpene Resins Market | 2026-2036
Terpene Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Terpene Resins Market Analysis
Aftermarket formulation services is reconfiguring margin capture across the terpene resins value chain. Eastman Chemical Company leverages its integrated pine-chemical feedstock position to sustain cost advantages in hydrogenated grades. Kraton Corporation anchors North American supply through specialized tackifier operations. Mangalam Organics Limited competes on natural terpene extraction scale from Indian gum rosin sources.
Terpene resins comprise oligomeric compounds derived from alpha-pinene, beta-pinene, and dipentene feedstocks, typically exhibiting softening points between 80°C and 150°C and serving primarily as tackifiers in pressure-sensitive and hot-melt adhesive systems. Natural terpene resins retain preference in food-contact packaging applications where petrochemical alternatives face regulatory scrutiny. Modified terpene resins command premium positioning in high-performance coatings owing to enhanced oxidative stability. Hydrogenated terpene resins represent the fastest-expanding product class as automotive and personal care formulators seek low-color, low-odor binding solutions.
EPA regulations under the Toxic Substances Control Act constrain synthetic monomer pathways in the United States, while REACH registration requirements in Europe elevate compliance costs for imported modified terpene grades. China's GB standards for adhesive emissions and Japan's JIS specifications for rubber compounding materials create divergent certification burdens across manufacturing locations. Stakeholders must monitor feedstock substitution economics as crude turpentine supply fluctuates alongside regional forestry management policies.
Market Dynamics
Feedstock substitution economics and divergent regional certification regimes are restructuring competitive positioning across the terpene resins value chain, as pine-chemical supply volatility forces formulators to recalibrate sourcing strategies.
Growth Catalysts
- Packaging sector expansion:Food-contact adhesive applications in flexible packaging are pulling hydrogenated terpene grades as FDA and EFSA scrutiny tightens on petrochemical alternatives.
- REACH registration completion:European ECHA compliance for modified terpene resins has cleared market access for qualified suppliers, reducing import friction into EU adhesive formulators.
- Automotive interior specifications:Low-odor, low-color binding requirements in vehicle cabin assembly are accelerating specification of hydrogenated terpene tackifiers by Tier-1 suppliers.
Market Restraints
- Crude turpentine price volatility:Forestry management policies in Brazil and Indonesia create raw material cost instability that compresses margin predictability for natural terpene extractors.
- Petrochemical substitute competition:Hydrocarbon tackifiers from C5/C9 streams retain cost advantages in non-food-contact applications, limiting terpene resin price elasticity.
- REACH data requirements:ECHA substance registration dossiers impose six-figure compliance costs that disproportionately burden small-scale gum rosin processors.
Strategic Opportunities
- Personal care formulation white space:Fragrance encapsulation and cosmetic binding applications in South Korea and Japan represent underpenetrated demand for odor-controlled hydrogenated grades.
- China GB standard alignment:Adhesive emission regulations under MEE oversight are creating compliance-driven preference shifts toward bio-based tackifier systems.
- Digital procurement platforms:B2B chemical marketplaces are compressing distributor layers and enabling direct specification relationships between terpene resin producers and mid-size adhesive compounders.
Industry Challenges
- Specialized hydrogenation expertise scarcity:Catalytic process engineering talent for color-stable terpene modification remains concentrated among a limited pool of pine-chemical specialists.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact notification, REACH registration, and China GB testing extends product launch cycles by 18-24 months for modified grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terpene Resins Market |
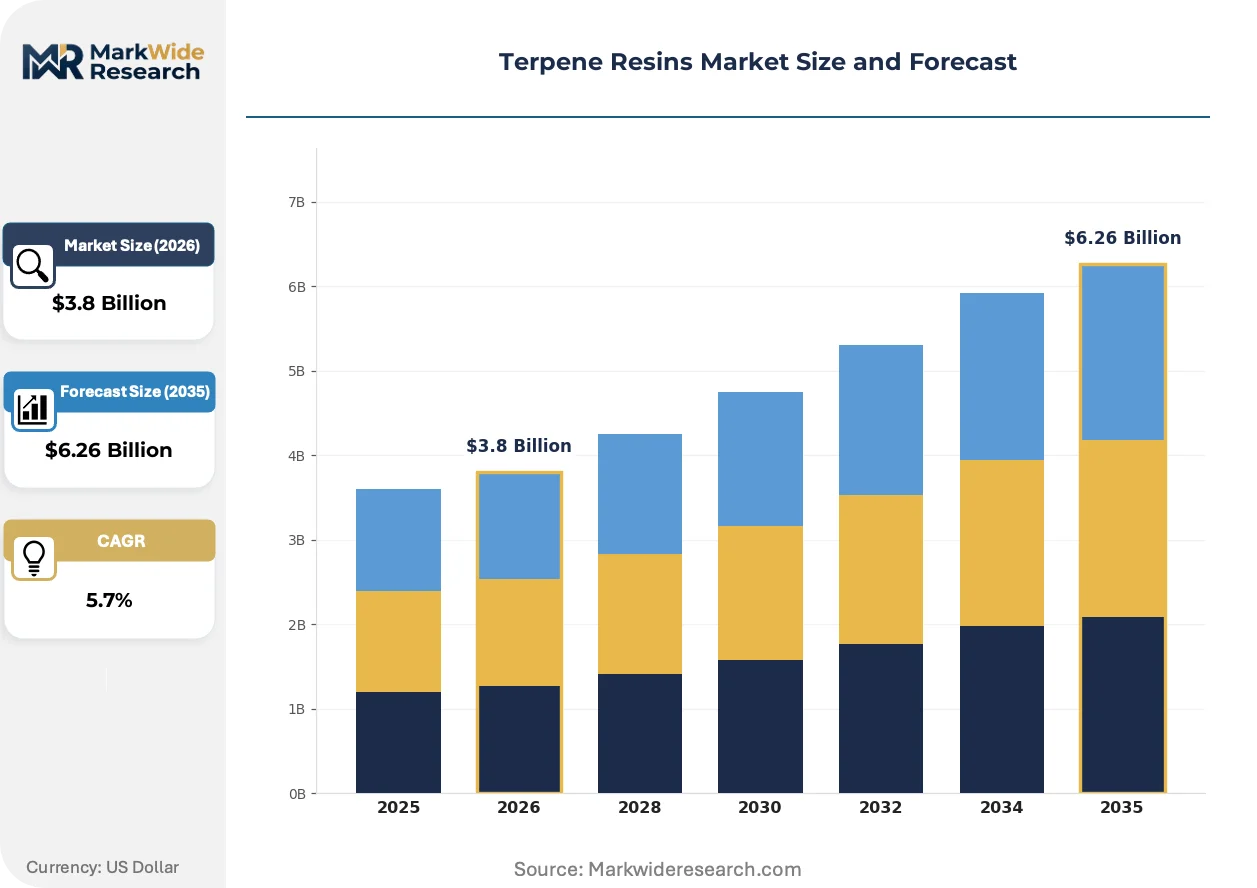
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Terpene Resins, Modified Terpene Resins, Synthetic Terpene Resins, Hydrogenated Terpene Resins Application: Adhesives, Coatings, Inks, Rubber Products End User: Automotive, Packaging, Construction, Personal Care Form: Liquid, Solid, Powder, Granular |
| Companies Covered | Kraton Corporation, Eastman Chemical Company, Mangalam Organics Limited, Mitsui Chemicals, Inc., Yasuhara Chemical Co., Ltd., Arakawa Chemicals, Ingevity, Baolin Chemical Industry Co., Ltd., Lesco Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terpene Resins Market Emerging Trajectories
Formulation chemistry and regulatory compliance frameworks are converging to reshape product development priorities, with sustainability certification and performance specifications now jointly determining specification outcomes.
Hydrogenation technology for terpene resins is migrating from batch catalytic systems toward continuous-flow reactor designs. Automotive and personal care formulators in Germany and Japan are specifying sub-50 APHA color grades at accelerating rates. This technology transition is compressing the viable supplier base to those with capital-intensive hydrogenation infrastructure.
REACH authorization requirements for certain synthetic tackifier precursors are tightening substitution pressure across European adhesive markets. ECHA's evolving SVHC candidate list is elevating bio-based terpene alternatives in pressure-sensitive tape and label formulations. German and French packaging converters are now requiring REACH-compliant tackifier documentation as a standard procurement condition.
Specification authority is concentrating among brand-owner sustainability teams rather than traditional purchasing departments. Consumer goods companies in North America and Western Europe are mandating bio-based content thresholds that displace conventional petroleum-derived tackifiers. This organizational shift is most visible in food and beverage packaging supply chains, where scope-3 emissions accounting now includes adhesive inputs.
Terpene Resins Market Segmentation
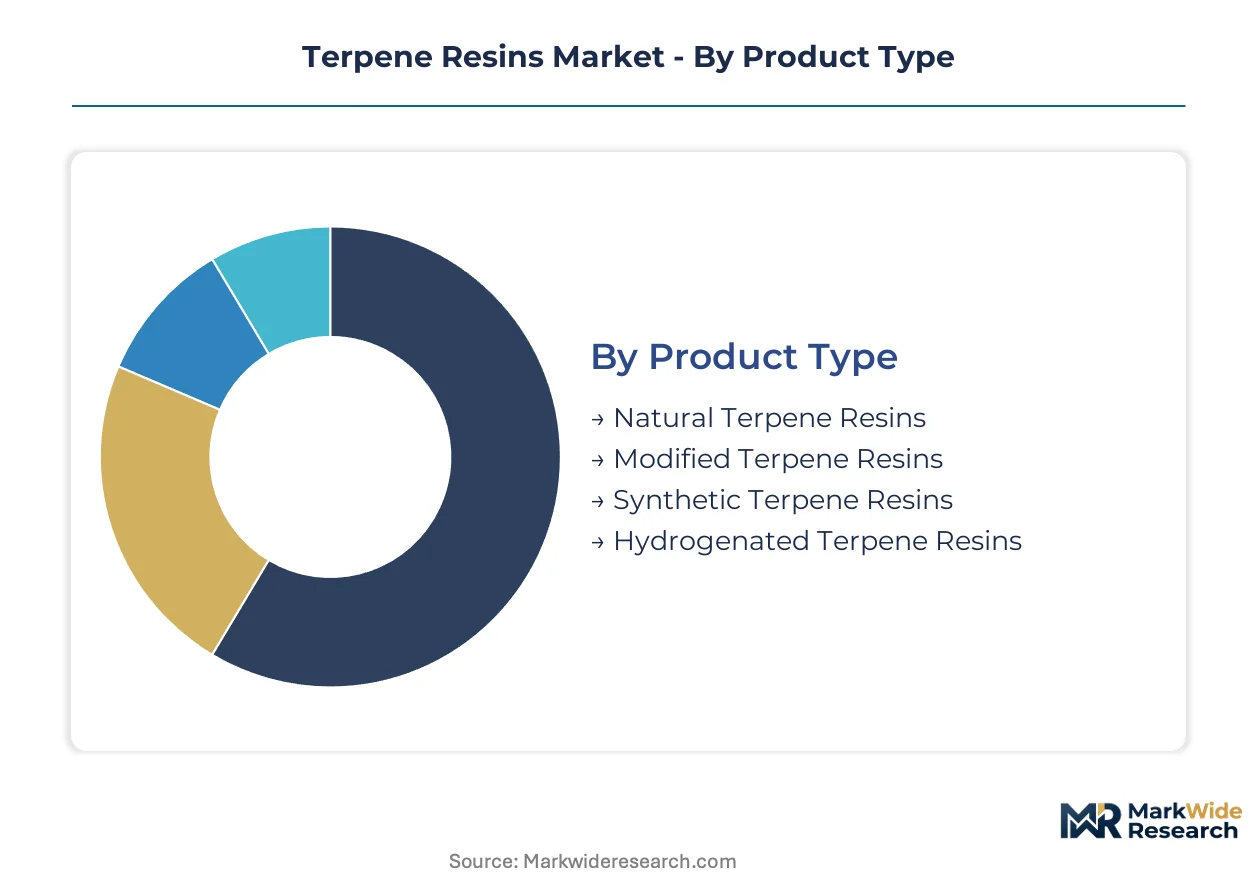
Terpene resin specifications diverge sharply across end-use requirements, with hydrogenation levels, softening points, and odor profiles determining grade selection. Formulators segment procurement by performance tier rather than feedstock origin alone.
Product Type:
Use-case spectrum spans food-contact packaging adhesives requiring natural extraction certificates to automotive interiors demanding sub-50 APHA color stability.
- Natural Terpene Resins:Derived directly from alpha-pinene and beta-pinene feedstocks through cationic polymerization, these grades retain certification preference in FDA and EFSA food-contact applications where synthetic alternatives face regulatory exclusion. European packaging converters in Germany and France specify natural grades for scope-3 emissions compliance.
- Hydrogenated Terpene Resins:Catalytic hydrogenation eliminates conjugated double bonds to achieve oxidative stability and color grades below 50 APHA. Tier-1 automotive suppliers in Japan and Germany specify these for low-odor cabin assembly applications. This segment is gaining share fastest as personal care formulators adopt odor-controlled binding systems.
- Modified Terpene Resins:Esterification or phenolic modification enhances compatibility with polar elastomers and improves heat resistance in pressure-sensitive adhesives.
- Synthetic Terpene Resins:Petrochemical-derived analogues bypass crude turpentine supply constraints but face REACH SVHC scrutiny and limited food-contact approval.
Established volume favors natural grades; emerging adoption favors hydrogenated specifications.
Application:
Cost tier stratification separates premium formulation services from commodity tackifier supply.
- Adhesives:Pressure-sensitive and hot-melt systems consume the majority of terpene resin volume, with hydrogenated grades commanding price premiums in automotive and electronics bonding. Japanese tape manufacturers specify low-odor hydrogenated tackifiers for consumer electronics assembly.
- Coatings:Modified terpene resins enhance gloss retention and drying characteristics in industrial wood and metal finishes. German coatings formulators specify REACH-compliant modified grades to meet EU Green Deal content thresholds.
- Inks:Solvent-based and UV-curable printing systems utilize terpene resins for pigment wetting and adhesion to polyolefin substrates.
- Rubber Products:Tire and industrial rubber compounding employs terpene tackifiers to improve filler dispersion and green strength during processing.
Adhesive applications dominate current procurement volumes; coatings represent the steepest expansion trajectory for modified grades.
End User:
Customer type concentration varies by certification burden, with automotive and packaging buyers driving specification authority.
- Packaging:Flexible food packaging converters in North America and Western Europe mandate bio-based content thresholds that displace petroleum-derived tackifiers. Sustainability teams at consumer goods companies now control adhesive procurement decisions.
- Automotive:Interior assembly specifications for low-VOC, low-odor binding accelerate hydrogenated terpene adoption by Tier-1 suppliers in Germany and Japan.
- Construction:Flooring and carpet backing adhesives utilize terpene tackifiers for moisture resistance and bond durability in high-humidity climates.
- Personal Care:Fragrance encapsulation and cosmetic binding applications in South Korea and Japan represent underpenetrated demand for odor-controlled hydrogenated grades.
Packaging drives current specification volume; personal care offers the most open competitive terrain for hydrogenated grade penetration.
Form:
Supply concentration in solid and liquid forms reflects processing economics and transportation logistics.
- Solid:Flaked and块状 terpene resins dominate bulk adhesive compounding operations, offering thermal stability during melt processing and extended shelf life in ambient storage conditions.
- Liquid:Low-softening-point grades and emulsion forms serve water-based adhesive systems and coating applications requiring cold-process compatibility.
- Powder:Micronized terpene resins enable dry-blend incorporation into powder coatings and certain hot-melt formulations.
- Granular:Pelletized forms reduce dust exposure and improve handling efficiency in automated compounding systems.
Solid forms anchor established industrial procurement; liquid grades align with water-based formulation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and China exhibit acute price sensitivity to crude turpentine fluctuations, while German and Japanese automotive formulators absorb premiums for sub-50 APHA hydrogenated grades without volume elasticity.
China
Packaging converters in Guangdong and Zhejiang provinces drive hydrogenated terpene consumption as MEE adhesive emission regulations tighten. GB standards for volatile organic compound limits in flexible food packaging create compliance-driven substitution away from petroleum tackifiers. The Yangtze River Delta concentration of hot-melt adhesive manufacturers is expanding hydrogenation capacity to serve export-oriented electronics assembly demand.
Germany
Automotive Tier-1 suppliers in Bavaria and Baden-Württemberg specify low-odor hydrogenated grades for cabin interior bonding applications. REACH registration completion for modified terpene resins has reduced import friction for qualified Asian suppliers into EU adhesive formulators. The Cologne-Düsseldorf industrial corridor hosts specialized tackifier blending operations serving packaging converters with scope-3 emissions documentation requirements.
United States
Food-contact packaging converters in the Midwest and Southeast mandate bio-based content thresholds that displace conventional petroleum-derived tackifiers. EPA Toxic Substances Control Act constraints on synthetic monomer pathways elevate terpene resin competitiveness in pressure-sensitive adhesive formulations. The Southeast pine belt concentration of crude turpentine extraction supplies hydrogenation feedstock to Gulf Coast specialty chemical processors.
Japan
Consumer electronics manufacturers in the Kanto region specify ultra-low-odor hydrogenated tackifiers for device assembly adhesives. JIS standards for rubber compounding materials create certification requirements that favor established terpene resin suppliers with documented quality systems. The Osaka-Kobe industrial zone maintains specialized hydrogenation expertise for color-stable terpene modification serving automotive interior specifications.
India
Gum rosin processors in Gujarat and Tamil Nadu compete on natural terpene extraction scale for export markets. BIS certification requirements for adhesive raw materials create domestic compliance barriers that favor integrated producers with in-house testing capabilities. The Mumbai-Pune industrial corridor concentrates pressure-sensitive tape manufacturing pulling imported hydrogenated grades for high-performance applications.
Terpene Resins Market Vendor Landscape
Capability concentration sits with hydrogenation specialists possessing continuous-flow reactor expertise; scale advantage sits with integrated pine-chemical processors controlling crude turpentine supply. The market structures around three tiers: multinational chemical conglomerates with backward integration into forestry feedstocks, mid-cap specialists focused on modified grade customization, and regional extractors competing on natural resin volume. Dominant competitive moves include capacity expansion in hydrogenated grades and strategic partnerships between Asian extractors and European formulators seeking REACH-compliant supply security.
Within the integrated chemical conglomerate tier, Eastman Chemical Company and Kraton Corporation exemplify archetypes combining feedstock control with hydrogenation infrastructure. Mitsui Chemicals, Inc. occupies a position representing Japanese precision in low-color grade production. Mangalam Organics Limited sits within the regional extractor archetype, leveraging Indian gum rosin sourcing for natural grade competitiveness. These three company types collectively illustrate the capability-scale tension defining competitive positioning.
| Leading Market Players |
|---|
| Kraton Corporation |
| Eastman Chemical Company |
| Mangalam Organics Limited |
| Mitsui Chemicals, Inc. |
| Yasuhara Chemical Co., Ltd. |
| Arakawa Chemicals |
| Ingevity |
| Baolin Chemical Industry Co., Ltd. |
| Lesco Chemical Company |
| Others |
Supply Flow & Price Mechanics
Crude turpentine price volatility from Brazilian and Indonesian forestry policy shifts determines both the premium spread between hydrogenated and natural grades and the geographic configuration of extraction assets. Buyers in India and China absorb feedstock cost swings through contract structures, while German and Japanese automotive formulators lock in multi-year offtake agreements at fixed premiums for sub-50 APHA color stability.
Pricing Analysis
Aftermarket formulation services drive lifetime value through technical support contracts and application engineering retainers. Three-tier pricing structure across premium hydrogenated, standard modified, and economy natural grades separates certification-burdened automotive specifications from commodity packaging adhesives. Cost compression in natural grades is intensifying as Indian gum rosin processors compete on extraction scale. Packaging converters in Guangdong province exhibit acute price sensitivity, while Tier-1 automotive suppliers in Bavaria absorb premiums without volume elasticity.
Supply Chain Analysis
Upstream crude turpentine extraction concentrates in Brazil, Indonesia, and the southeastern United States pine belt. Hydrogenation capacity draws from catalytic process engineering expertise concentrated in Germany, Japan, and the Yangtze River Delta. Single-source vulnerability runs through Brazilian forestry concessions subject to environmental licensing volatility. Distribution runs through specialized tackifier blending operations in the Cologne-Düsseldorf corridor and direct procurement relationships via B2B chemical marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among brand-owner sustainability teams that now control adhesive procurement decisions, fragmenting traditional distributor influence across North American and Western European packaging supply chains.
For Market Incumbents: Insulate margin stability through captive crude turpentine supply arrangements in the southeastern United States pine belt and continuous-flow hydrogenation reactor investments that compress the viable supplier base. Hydrocarbon tackifier substitution from C5/C9 streams threatens natural grade volumes in non-food-contact applications. REACH registration completion for modified grades creates a defensive moat against unqualified Asian imports. For New Entrants and Emerging Players: Establish a beachhead in South Korean and Japanese personal care fragrance encapsulation applications where odor-controlled hydrogenated grades remain underpenetrated. Digital procurement platforms enable direct specification relationships with mid-size adhesive compounders, bypassing traditional distributor layers. China GB standard alignment for adhesive emissions creates compliance-driven demand for bio-based tackifier systems. For Investors and Strategic Acquirers: The market sits at a hydrogenation capacity expansion phase that favors integrated pine-chemical processors with backward feedstock control. Long-term viability hinges on continuous-flow reactor expertise scarcity and multi-jurisdiction certification capabilities. Watch for ECHA SVHC candidate list expansion as an inflection signal accelerating bio-based terpene substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Hydrogenation Capacity Expansion | Sub-50 APHA color grades command automotive and personal care premiums in Germany and Japan. |
| Backward Integration into Crude Turpentine Extraction | Southeastern United States pine belt assets insulate against Brazilian forestry policy volatility. |
| REACH Registration Completion for Modified Grades | ECHA compliance clears EU market access and reduces import friction for qualified Asian suppliers. |
| Digital Procurement Platform Partnership | B2B chemical marketplaces compress distributor margins and enable direct specification relationships. |
| Joint Venture with Personal Care Formulators | South Korean and Japanese cosmetic binding applications represent underpenetrated hydrogenated grade demand. |
Methodological Framework
Operator-level perspectives from adhesive formulators, pine-chemical plant managers, automotive Tier-1 procurement leads, and packaging converter sustainability directors anchored the qualitative base. Secondary validation drew from customs and trade data, American Chemistry Council reports, SEC 10-K filings, and ECHA registration dossiers. Bottom-up volume estimates from grade-specific production capacities triangulated against top-down demand aggregation from end-use industry consumption patterns.
Scenario-bracketing around feedstock substitution economics and regulatory authorization timelines framed the projection horizon. Segmentation dimensions spanned hydrogenation level, softening point tier, end-use industry, and regional certification cluster. CAGRs were derived from fitted trend extrapolation adjusted for capacity buildout announcements and REACH registration completion schedules. Crude turpentine price volatility assumptions and automotive interior specification adoption curves served as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in forestry commodity indices, adhesive sector capital expenditure cycles, or EU Green Deal implementation pace would shift the trajectory. Cross-checking against American Chemistry Council production surveys and ECHA registration database updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Soil-Release Functional Polymers for Performance Apparel Care Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market