
 Flexible Packaging Adhesive Market | 2026-2036
Flexible Packaging Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Packaging Adhesive Market Foresight
Brand owners in personal care and cosmetics are unwinding legacy purchasing patterns toward adhesive suppliers with verified sustainable chemistries. Henkel AG & Co. KGaA leverages its European R&D footprint to dominate solvent-free polyurethane development for high-barrier laminates. Dow Inc. anchors North American supply through integrated acrylic emulsion manufacturing at scale. Toyo-Morton Ltd. specializes in gravure-compatible adhesives for Asia-Pacific flexible packaging converters.
Flexible packaging adhesives bond multi-layer polymer films, foils, and papers into laminated structures that resist moisture, oxygen, and mechanical stress during filling, distribution, and shelf life. These formulations typically achieve bond strengths of 2–8 N/15mm depending on substrate combination and curing chemistry, with solvent-free two-component polyurethanes and UV-curable acrylics displacing legacy solvent-based systems in food and pharmaceutical applications. Water-based adhesives lead volume in food packaging where migration limits and organoleptic requirements are most stringent, while UV-curable adhesives represent the fastest-expanding technology segment driven by instant cure speeds and elimination of thermal drying energy. Hot melt adhesives occupy a mature niche in tray sealing and label applications where heat resistance demands remain moderate.
EU REACH and the F-Gas Regulation constrain solvent-based adhesive formulations across European flexible packaging operations, while FDA indirect food additive regulations under CFR 175.105 govern laminate construction for US food contact. China's SAMR enforces GB standards for packaging material safety that directly shape adhesive selection for export-oriented converters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs and supply chain disqualification.
Market Dynamics
Solvent-free polyurethane chemistry is compressing thermal drying requirements across European flexible packaging operations as REACH volatile organic compound limits tighten formulation specifications. This structural shift forces converters to retool lamination lines while adhesive suppliers race to match bond strength parity with legacy solvent-based systems.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases accelerate solvent-free adhesive qualification for high-barrier food laminates across German and Italian converter bases.
- Pharmaceutical serialization:India's CDSCO track-and-trace mandates for exported medicines drive multi-layer blister foil demand in Mumbai-Ahmedabad packaging clusters.
- UV-curable acrylics:Instant cure speeds eliminate thermal drying energy, capturing share in narrow-web label and pouch applications where throughput velocity determines converter economics.
Market Restraints
- Isocyanate feedstock concentration:Aliphatic diisocyanate supply concentrates among three Asian chemical producers, exposing European adhesive formulators to freight cost volatility and allocation risk.
- Bond strength limitations:Water-based acrylics fail to achieve the 6–8 N/15mm peel strength required for retort pouch applications above 121°C sterilization temperatures.
- Capital intensity of line conversion:Solvent-free lamination equipment requires precision metering pump systems that cost 40–60% more than legacy solvent-based coaters.
Strategic Opportunities
- Brazilian food export growth:ANVISA-aligned adhesive qualification for aseptic brick carton laminates opens access to São Paulo dairy and juice packaging converters serving Mercosur trade zones.
- Digital printing convergence:UV-inkjet web printing integrates with UV-curable adhesive coating stations, enabling single-pass laminate production for short-run flexible packaging.
- China dual carbon goals:Provincial MEE enforcement of carbon intensity targets creates procurement preference for water-based systems in Zhejiang and Jiangsu converter clusters.
Industry Challenges
- Formulation chemist scarcity:Polyurethane synthesis expertise concentrates among aging technical workforces in European and Japanese adhesive houses, constraining R&D velocity for solvent-free product pipelines.
- Migration testing timelines:EU 10/2011 food contact compliance requires 6–12 month organoleptic and specific migration limit validation, delaying new adhesive commercialization.
- Legacy equipment retrofit complexity:Gravure press ventilation systems designed for solvent recovery cannot accommodate the higher viscosity and temperature sensitivity of solvent-free two-component adhesives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Packaging Adhesive Market |
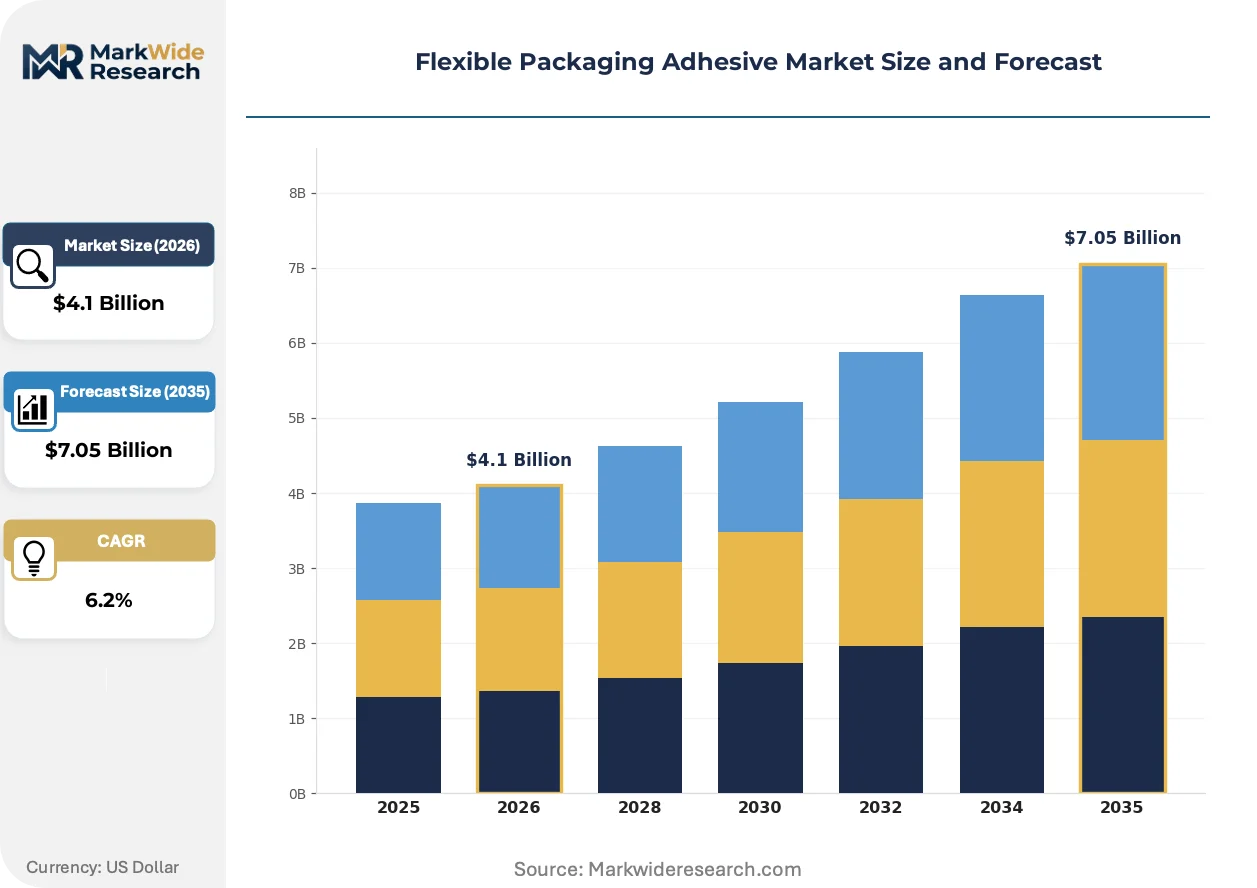
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.05 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Adhesives, Hot Melt Adhesives, Solvent-Based Adhesives, Water-Based Adhesives, UV Curable Adhesives Form: Liquid, Paste, Film, Powder, Gel Application: Food Packaging, Pharmaceutical Packaging, Personal Care Packaging, Household Chemicals Packaging, Electronic Components Packaging End User Industry: Consumer Goods Manufacturers, Pharmaceutical Companies, Electronics Manufacturers, Cosmetics Producers, Chemical Companies |
| Companies Covered | Arkema Group, Sika AG, Henkel AG & Co. KGaA, Ashland Global Holdings Inc., Avery Dennison Corporation, H.B. Fuller Company, Dow Inc., Toyo-Morton Ltd., 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Packaging Adhesive Market Shifts & Advancements
Reactive hot melt and UV-curable chemistries are collapsing cure cycle times from hours to seconds, rewiring converter capital allocation toward inline coating-lamination-printing integration. These advances compress working capital requirements while raising technical barriers for adhesive suppliers.
Electron-beam curable acrylic adhesive technology bonds aluminum oxide-coated polyester films to polyethylene sealant webs without thermal stress. Pharmaceutical cold-chain pouch manufacturers in Germany and Switzerland adopt these systems to eliminate heat-induced barrier degradation. EB chemistry is miniaturizing the distinction between high-performance solvent-based laminates and energy-cured alternatives.
EU REACH Annex XVII restrictions on N-methyl-2-pyrrolidone solvent content force reformulation of polyurethane adhesive hardeners. Adhesive suppliers must qualify alternative co-solvent systems or shift entirely to NMP-free prepolymer architectures. Food packaging converters in Italy and Spain face the tightest compliance timelines as their national chemical agencies front-load enforcement.
Brand owners now mandate adhesive sustainability credentials through third-party certifications rather than supplier declarations. Personal care companies in France and the Netherlands require Cradle to Cradle or equivalent verified chemistries for laminate structures. This specification behavior concentrates procurement volume among adhesive houses with established European R&D and certification infrastructure, marginalizing regional formulators lacking documentation depth.
Flexible Packaging Adhesive Market Segmentation
Adhesive selection in flexible packaging hinges on regulatory thresholds, thermal processing requirements, and substrate compatibility. Each segment category carries distinct compliance obligations and performance trade-offs that shape procurement decisions across converter operations.
Product Type:
EU REACH volatile organic compound limits and FDA indirect food additive regulations under CFR 175.105 create divergent formulation requirements across jurisdictions, forcing technology-specific qualification pathways.
- Solvent-Based Adhesives:Polyurethane and polyester systems dissolved in ethyl acetate or toluene achieve bond strengths of 6–8 N/15mm for high-barrier retort pouches. European converters in Germany and Italy face accelerated phase-out timelines as F-Gas Regulation and REACH Annex XVII restrictions tighten, while legacy equipment in Southeast Asia sustains residual demand.
- Water-Based Adhesives:Acrylic emulsion and polyurethane dispersion systems dominate food packaging volume where migration limits and organoleptic requirements are most stringent. India's pharmaceutical packaging hub around Mumbai and Ahmedabad captures share fastest as CDSCO track-and-trace mandates drive multi-layer blister foil demand.
- UV Curable Adhesives:Photoinitiator-acrylate formulations cure instantly under UV lamps, eliminating thermal drying energy in narrow-web label and pouch applications.
- Solvent-Free Adhesives:Two-component polyurethane systems compress thermal drying requirements across European operations as REACH compliance forces line retooling.
- Hot Melt Adhesives:Ethylene-vinyl acetate and polyolefin block copolymers occupy mature niches in tray sealing where heat resistance demands remain moderate.
Established volume favors water-based systems; emerging adoption favors UV-curable chemistry.
Form:
Physical state determines application equipment compatibility, storage stability, and metering precision on high-speed lamination lines.
- Liquid:Low-viscosity solvent-based and water-based systems feed gravure and flexo coating stations with precise film weight control.
- Paste:High-viscosity formulations suit manual or semi-automated application in specialty pharmaceutical pouch construction.
- Film:Pre-cast adhesive layers enable clean-room pharmaceutical packaging operations requiring particulate-free bonding.
- Powder:Reactive polyurethane hot melt systems in granular form suit bulk handling systems for continuous lamination.
- Gel:Thixotropic formulations maintain position on vertical surfaces during assembly of complex multi-layer structures.
Processing speed drives liquid preference; contamination control elevates film form adoption.
Application:
End-use performance specifications range from ambient shelf stability to aggressive sterilization cycles, segmenting adhesive requirements by thermal and barrier demands.
- Food Packaging:Retort pouches, aseptic cartons, and snack laminates require adhesives surviving 121°C sterilization without delamination or off-odor generation.
- Pharmaceutical Packaging:Cold-chain pouches and blister foils demand aluminum oxide-coated polyester bonding with zero heat-induced barrier degradation.
- Personal Care Packaging:Cosmetics sachets and flexible tubes prioritize aesthetic clarity and fragrance stability over extreme thermal resistance.
- Household Chemicals Packaging:Detergent and cleaner pouches resist surfactant migration and alkaline pH exposure.
- Electronic Components Packaging:Anti-static laminates protect semiconductors from electrostatic discharge during transport.
Regulatory stringency peaks in food and pharmaceutical applications; margin expansion concentrates in electronics protection.
End User Industry:
Procurement sophistication varies from commodity purchasing in consumer goods to validated supplier qualification in pharmaceutical operations.
- Consumer Goods Manufacturers:Food and beverage brand owners mandate third-party sustainability certifications rather than supplier declarations, concentrating volume among adhesive houses with established European R&D infrastructure.
- Pharmaceutical Companies:Serialization mandates and EU 10/2011 food contact compliance require 6–12 month organoleptic and specific migration limit validation, delaying new adhesive commercialization.
- Electronics Manufacturers:Clean-room specifications and ionic contamination limits govern adhesive selection for semiconductor packaging films.
- Cosmetics Producers:French and Dutch personal care companies require Cradle to Cradle verified chemistries for laminate structures.
- Chemical Companies:Aggressive product formulations demand solvent-resistant adhesive interfaces in industrial flexible packaging.
Validation burden favors incumbent suppliers in pharmaceuticals; sustainability credentials reshape cosmetics procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European adhesive distribution, handling specialized chemical imports for lamination line retrofits across northern converter clusters. This maritime infrastructure underwrites Germany's position as the continent's solvent-free technology diffusion center.
Germany
Bavarian converter operations drive solvent-free polyurethane qualification as ECHA REACH Annex XVII enforcement tightens volatile organic compound limits. The country's national chemical regulator front-loads compliance timelines for N-methyl-2-pyrrolidone solvent restrictions. Frankfurt-Rhine-Main packaging clusters retool gravure lines to accommodate higher-viscosity two-component systems.
United States
Midwest dairy pouch manufacturers expand water-based acrylic procurement as FDA CFR 175.105 indirect food additive scrutiny intensifies migration testing protocols. The EPA regulates ethyl acetate emissions from legacy solvent-based coaters. Chicago-Wisconsin converter corridors integrate UV-curable stations with narrow-web label production.
China
Zhejiang and Jiangsu province converter clusters pivot toward water-based systems under MEE carbon intensity enforcement aligned with dual carbon goals. SAMR GB standards for packaging material safety shape export-oriented adhesive selection. Yangtze River Delta flexible packaging operations qualify low-migration formulations for European-bound food laminates.
India
CDSCO pharmaceutical serialization mandates accelerate multi-layer blister foil demand across Mumbai-Ahmedabad packaging hubs. The national pharmaceutical regulator enforces track-and-trace compliance for exported medicines. Gujarat converter clusters expand solvent-free adhesive capacity to serve cold-chain pouch requirements.
Brazil
São Paulo dairy and juice packaging converters seek ANVISA-aligned adhesive qualification for aseptic brick carton laminates serving Mercosur trade zones. The national health surveillance agency regulates food contact material safety for export-oriented operations. Southeastern Brazilian converter investments target solvent-free line conversions ahead of anticipated regulatory convergence with EU standards.
Flexible Packaging Adhesive Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and R&D scale dimensions. The vendor base stratifies into three tiers: integrated chemical conglomerates with captive raw material positions, mid-cap adhesive houses with regional formulation expertise, and niche specialists in energy-cured chemistries. Dominant competitive moves include strategic partnerships for biobased feedstock access and geographic expansion through distributor qualification programs in emerging converter markets.
Within the integrated chemical tier, Dow Inc. and Arkema Group exemplify scale-driven positions anchored in acrylic emulsion and specialty polymer architectures. Henkel AG & Co. KGaA occupies a distinctive position bridging European R&D infrastructure with global sustainability certification depth. Among Asia-Pacific specialists, Toyo-Morton Ltd. represents gravure-compatible formulation expertise aligned with regional converter equipment preferences. These three anchors illustrate how competitive positioning fragments across technology vectors rather than consolidating around unified product portfolios.
| Leading Market Players |
|---|
| Arkema Group |
| Sika AG |
| Henkel AG & Co. KGaA |
| Ashland Global Holdings Inc. |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| Dow Inc. |
| Toyo-Morton Ltd. |
| 3M Company |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for aliphatic diisocyanate feedstock lock in supply access for European adhesive formulators while anchoring price visibility against Asian producer allocation volatility. These arrangements concentrate procurement leverage among integrated chemical conglomerates with captive raw material positions, marginalizing mid-cap formulators exposed to spot-market freight cost swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments flexible packaging adhesives by certification grade and volume commitment. Premium tiers command valuation premiums for EU 10/2011 food contact compliance and Cradle to Cradle verified chemistries demanded by French cosmetics brand owners. Cost compression in standard water-based acrylic tiers intensifies as Indian pharmaceutical converters consolidate procurement around Mumbai-Ahmedabad hubs. Price-sensitive food packaging converters in Southeast Asia sustain residual solvent-based demand, while least-sensitive pharmaceutical cold-chain pouch manufacturers in Germany absorb EB-curable acrylic premiums for zero heat-induced barrier degradation.
Supply Chain Analysis
Inventory buffers for isocyanate hardeners stretch to 8–12 weeks across European formulators as aliphatic diisocyanate production concentrates in China, Japan, and South Korea. Solvent-free polyurethane adhesive synthesis rests on MDI and polyether polyol feedstocks sourced from integrated petrochemical complexes along the US Gulf Coast and Rotterdam-Antwerp refining corridors. Single-source vulnerability concentrates in Asian diisocyanate producers, exposing formulators to allocation risk during regional production curtailments. Distribution runs through specialized chemical distributors qualified for hazardous material handling, with Port of Hamburg anchoring European import logistics for lamination line retrofit chemicals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible packaging adhesive demand is accelerating through a regulatory inflection as EU REACH Annex XVII enforcement front-loads N-methyl-2-pyrrolidone solvent restrictions, collapsing viable formulation pathways for legacy polyurethane hardeners.
For Market Incumbents: Shield solvent-free product portfolios through backward integration into polyether polyol production, capturing margin compression from Asian isocyanate feedstock volatility. Accelerate Cradle to Cradle certification depth to defend procurement concentration among Dutch and French personal care brand owners mandating verified sustainable chemistries. Prioritize R&D velocity in EB-curable acrylic architectures for pharmaceutical cold-chain pouch applications where barrier degradation risks disqualify thermal-cure alternatives. For New Entrants and Emerging Players: EU 10/2011 fast-track validation services for water-based acrylic systems unlock white-space access among Indian pharmaceutical exporters facing CDSCO serialization mandates. Target Gujarat converter clusters expanding cold-chain pouch capacity with solvent-free adhesive qualification support bundled with technical service. Penetrate Brazilian aseptic brick carton laminates through ANVISA-aligned migration testing partnerships with São Paulo dairy packaging operations. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap adhesive houses with established European R&D infrastructure and certification documentation depth, positioned to capture procurement consolidation among sustainability-mandating brand owners. Long-term viability hinges on formulation chemistry transitions completing before REACH enforcement timelines harden. Watch for ECHA NMP restriction enforcement acceleration as the signal indicating margin compression timing for non-compliant formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyether Polyol Production | Captures margin from volatile Asian MDI feedstock pricing while securing solvent-free adhesive supply. |
| EB-Curable Acrylic R&D Expansion | Addresses pharmaceutical cold-chain pouch demand in Germany and Switzerland requiring zero thermal stress. |
| EU 10/2011 Fast-Track Validation Services | Compresses 6–12 month organoleptic testing timelines for Indian pharmaceutical packaging exporters. |
| ANVISA-Aligned Migration Testing Partnerships | Unlocks São Paulo dairy converter access for aseptic brick carton laminate qualification. |
| Cradle to Cradle Certification Investment | Secures procurement preference from French and Dutch personal care brand owners mandating verified chemistries. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, ECHA regulatory filings, SEC 10-K disclosures, and Cefic industry reports to anchor supply concentration and pricing dynamics. Primary interviews engaged adhesive formulation chemists, flexible packaging converter procurement leads, brand owner sustainability officers, and specialized chemical distributors across Germany, India, China, and Brazil. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis and production capacity databases.
Segmentation dimensions modeled span adhesive chemistry type, physical form, end-use application, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted demand projections incorporating converter line retrofit timelines and REACH compliance phase-out schedules. Forecast inputs include ECHA enforcement acceleration scenarios and CDSCO pharmaceutical serialization mandate implementation pacing.
Underlying assumptions cover stable aliphatic diisocyanate supply from Asian producers and sustained EU REACH Annex XVII enforcement trajectory, with deviation risk concentrated in feedstock allocation disruptions or regulatory timeline delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
UV-Curable Adhesives Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
Laser Self-Adhesive Tear Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
South America Waterborne Adhesives Market
Adhesives & Sealants
North America Cyanoacrylate Adhesives Market