
 Global Polyol Market | 2026-2036
Global Polyol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyol Market Analysis
Performance-based service contracts for polyurethane formulations is recalibrating how buyers procure polyol systems, shifting capital expenditure into operational expenditure models. BASF SE leverages its integrated petrochemical complexes in Ludwigshafen and Antwerp to sustain cost-advantaged supply of specialty polyether grades. Covestro AG anchors its competitive position through backward integration into propylene oxide, the critical upstream feedstock for polyether production. Dow Inc. dominates the North American flexible foam segment through its VORANOL product range and deep relationships with tier-one automotive seating suppliers.
Polyols are hydroxyl-terminated oligomers synthesized through alkoxylation of starter molecules with ethylene oxide or propylene oxide, with molecular weights ranging from hundreds to over ten thousand grams per mole, serving primarily as backbone reactants in polyurethane polymerization. Polyether polyols occupy the largest volume position due to their cost efficiency and versatility in flexible foam applications for furniture and automotive seating. Polyester polyols command premium pricing in coatings and adhesives where hydrolytic stability and mechanical strength justify higher formulation costs. Natural oil polyols represent the fastest-growing category as bio-based content mandates from the EU Green Deal and corporate sustainability targets reshape procurement criteria across European appliance and construction markets.
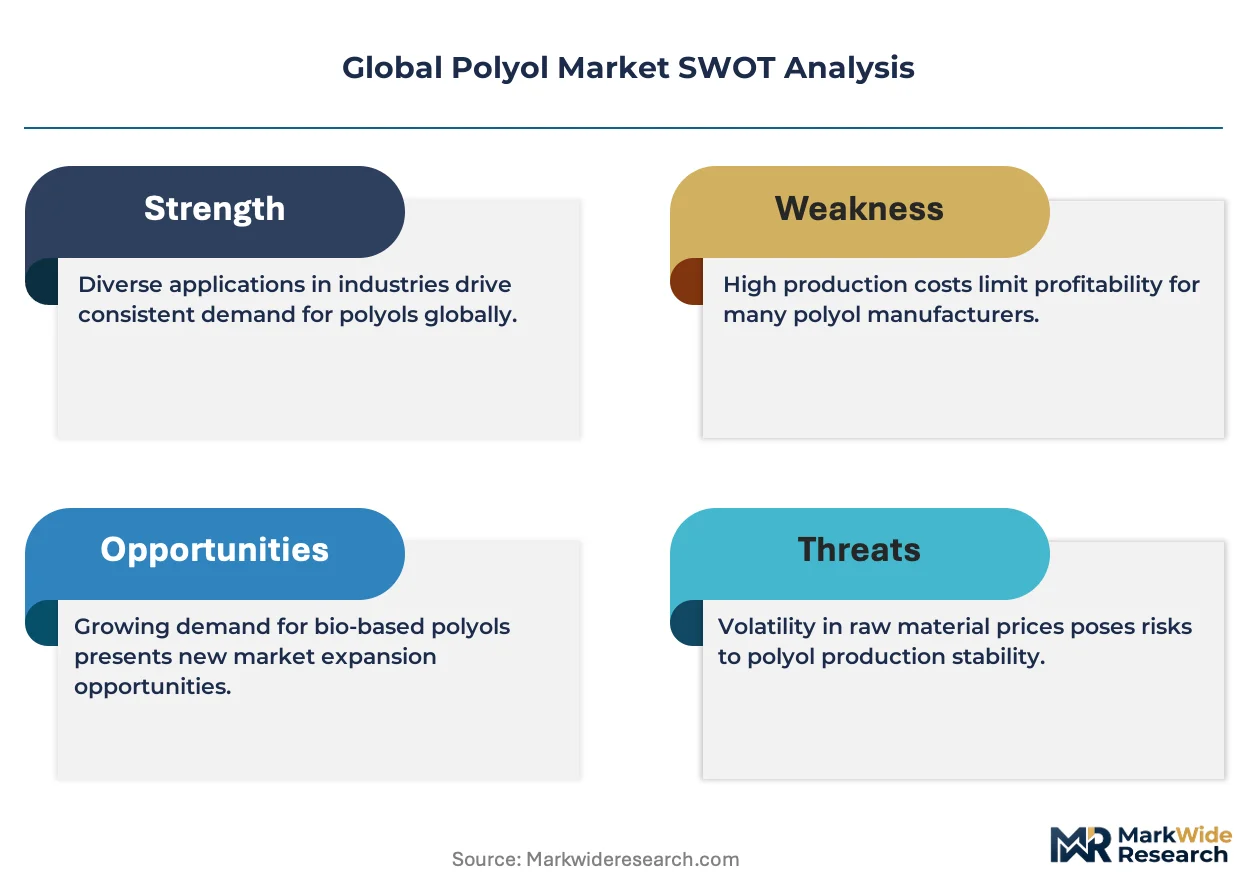
REACH registration requirements enforced by ECHA govern chemical safety documentation for polyol imports into the European Union, while EPA regulations under the Toxic Substances Control Act dictate pre-manufacture notification protocols for novel polyol chemistries in the United States. China's GB standards administered by SAMR establish formaldehyde emission limits for polyurethane foam used in construction and furniture, directly influencing polyol selection criteria for domestic manufacturers. Stakeholders must monitor the trajectory of bio-based feedstock certification schemes and carbon border adjustment mechanisms to anticipate which polyol platforms will retain cost and access advantages through the forecast horizon.
Market Dynamics
Propylene oxide supply concentration among Asian petrochemical complexes is forcing polyether producers to renegotiate long-term feedstock contracts and accelerate alternative starter molecule development.
Growth Catalysts
- EU Green Deal bio-content mandates:Appliance manufacturers across Germany and France now specify minimum renewable carbon content in polyurethane insulation systems, pulling natural oil polyol volumes upward.
- Automotive lightweighting:Seating suppliers in Detroit and Stuttgart are expanding molded foam programs to meet Corporate Average Fuel Economy targets and equivalent EU fleet emission rules.
- China's dual carbon goals:Construction sector procurement guidelines issued by MEE favor low-emission polyurethane systems for building envelope applications.
Market Restraints
- Propylene oxide oligopoly:Five integrated petrochemical groups control over seventy percent of Asian merchant supply, creating feedstock price volatility that compresses polyether margin structures.
- REACH registration burdens:ECHA documentation requirements for novel polyol chemistries impose six-figure compliance costs that deter mid-scale specialty entrants.
- Polyester polyol substitution ceiling:Hydrolytic instability in humid climates limits penetration into tropical construction markets despite superior mechanical properties.
Strategic Opportunities
- India construction acceleration:Bureau of Indian Standards certification for formaldehyde-free insulation creates first-mover positioning for bio-based polyol suppliers.
- Cold chain logistics expansion:Refrigerated transport fleet growth in Brazil and Mexico is generating specification demand for high-performance rigid foam systems.
- Carbon border adjustment mechanisms:EU CBAM implementation is incentivizing Middle Eastern producers to certify product carbon footprints for continued market access.
Industry Challenges
- Alkoxylation process engineering expertise:The specialized knowledge required for molecular weight distribution control in continuous reactors constrains capacity expansion timelines.
- Multi-jurisdiction certification overlap:Simultaneous compliance with EPA pre-manufacture notification, REACH registration, and China's GB standard testing creates duplicative toxicology study costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyol Market |
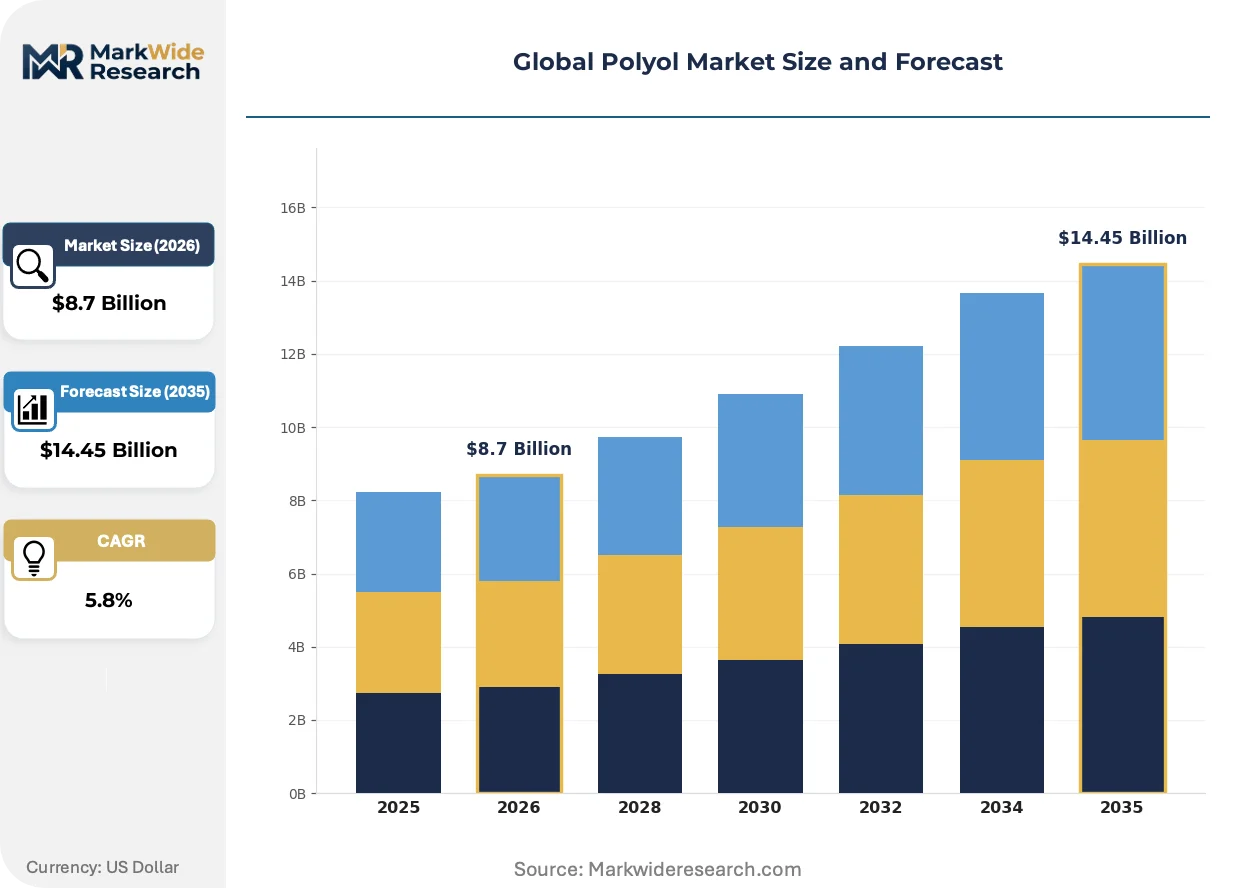
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Polyols, Polyester Polyols, Natural Oil Polyols, High Functionality Polyols End Use Industry: Automotive, Construction, Furniture, Packaging Application: Flexible Foam, Rigid Foam, Coatings, Adhesives Technology: Batch Process, Continuous Process, enzymatic Process, Others |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Shell Chemicals, Huntsman International LLC, Wanhua Chemical Group, Stepan Company, Repsol S.A., LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyol Market Emerging Trajectories
Digital process control systems and bio-based feedstock verification protocols are compressing formulation development cycles while fragmenting traditional supply relationships.
Continuous flow reactor technology is automating alkoxylation operations that previously required batch-wise intervention. Tier-one automotive seating suppliers in Germany and Japan are adopting these systems to reduce lot-to-lot viscosity variation. The technology is automating quality assurance overhead that formerly consumed fifteen percent of plant labor hours.
REACH authorization procedures for Substances of Very High Concern are restricting certain amine catalysts used in polyurethane foam production. European appliance manufacturers are reformulating to meet both emission limits and the EU Green Deal circular economy action plan requirements. Coatings and adhesives segments are absorbing the steepest compliance cost increases due to lower volume tolerance for raw material switches.
Buyers are unbundling technical service from material supply contracts. Large furniture manufacturers in Italy and Poland now retain independent formulation consultants rather than relying on polyol supplier laboratories. This pattern is most pronounced among mid-scale producers seeking to qualify multiple feedstock sources without vendor lock-in.
Global Polyol Market Segmentation
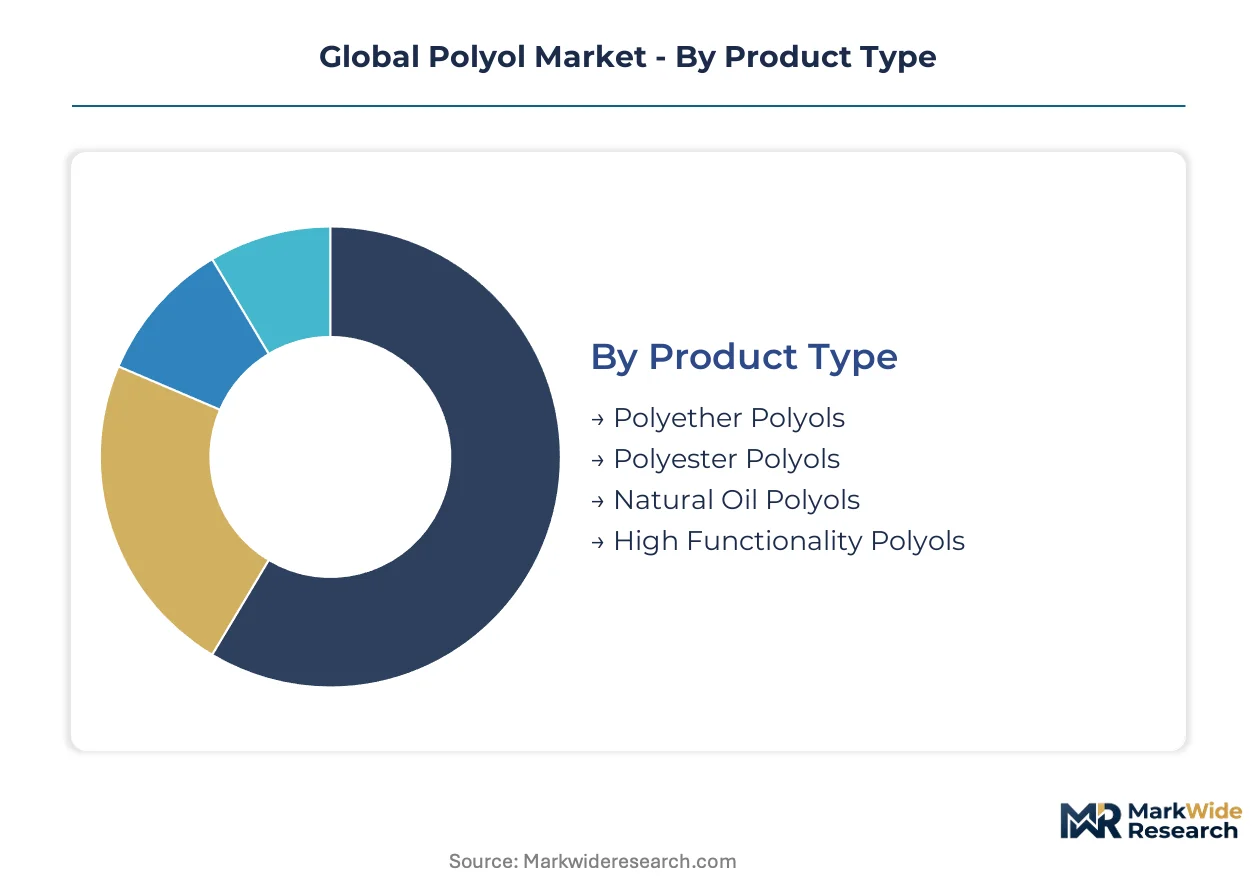
Polyol market segmentation reveals divergent margin structures across product chemistries and application intensities. Understanding volume concentration versus premium capture dynamics enables suppliers to align capacity investments with profit pool positioning.
Product Type:
Volume leadership rests with commodity polyether grades, while specialty and bio-based variants command formulation premiums.
- Polyether Polyols:These oligomers synthesized through propylene oxide alkoxylation of starter molecules dominate flexible foam consumption. Automotive seating programs in Stuttgart and Detroit absorb substantial volumes for molded seat cushions, while furniture manufacturers across Poland and Italy specify these grades for cost-sensitive upholstery applications.
- Polyester Polyols:Ester-linked backbone structures deliver superior hydrolytic stability and mechanical strength in coatings and adhesives. Coatings formulators in Germany and Japan absorb premium-priced volumes for industrial protective systems where durability justifies higher raw material costs.
- Natural Oil Polyols:Bio-based feedstocks including soybean and castor oil derivatives satisfy EU Green Deal renewable content mandates. Appliance insulation specifications across France and Germany now require minimum bio-carbon thresholds.
- High Functionality Polyols:Multi-functional initiator systems with elevated hydroxyl numbers enable rapid-cure rigid foam systems. Cold chain construction in Brazil and Mexico specifies these grades for spray-applied building envelope insulation.
Mature deployment sits with polyether polyols across established automotive and furniture value chains. Newer deployment is concentrated in natural oil polyols as regulatory bio-content mandates reshape procurement criteria.
End Use Industry:
Application pull varies sharply by durability requirements and emission regulations across construction, mobility, and consumer goods sectors.
- Automotive:Seating suppliers pursue lightweighting targets through molded polyurethane systems. Tier-one manufacturers in Japan and Germany specify low-VOC foam grades to meet cabin air quality standards enforced by EPA and EU type-approval frameworks.
- Construction:Building envelope insulation absorbs rigid foam volumes as energy codes tighten. China's MEE procurement guidelines favor low-emission polyurethane systems for wall and roof applications under dual carbon policy implementation.
- Furniture:Upholstery and bedding manufacturers balance cost pressure with flammability compliance. Italian and Polish producers unbundle technical service from material supply to qualify multiple feedstock sources.
- Packaging:Protective foam and adhesive applications serve electronics and consumer goods distribution. Cold chain expansion in Mexico and Brazil generates specification demand for high-performance insulated shipping containers.
Procurement sophistication separates automotive and construction buyers, who retain formulation consultants, from furniture and packaging segments where supplier laboratories still dominate technical service.
Application:
Foam systems capture volume, while coatings and adhesives concentrate value through performance-critical specifications.
- Flexible Foam:Open-cell structures dominate seating and bedding comfort layers. VORANOL-branded product ranges anchor North American supply relationships with Detroit-based automotive seating suppliers.
- Rigid Foam:Closed-cell insulation systems serve construction and refrigeration applications. REACH authorization restrictions on certain amine catalysts are forcing reformulation across European appliance manufacturing.
- Coatings:Polyurethane film formers protect industrial substrates from corrosion and wear. Hydrolytic stability requirements in humid climates limit polyester polyol penetration despite superior mechanical properties.
- Adhesives:Structural bonding systems assemble composite panels and flexible packaging laminates. Lower volume tolerance in this segment amplifies compliance cost burdens from raw material switches.
Flexible foam maintains the deepest supplier-buyer integration through co-development programs. Rigid foam is gaining share fastest as building energy codes tighten across tropical and temperate climate zones.
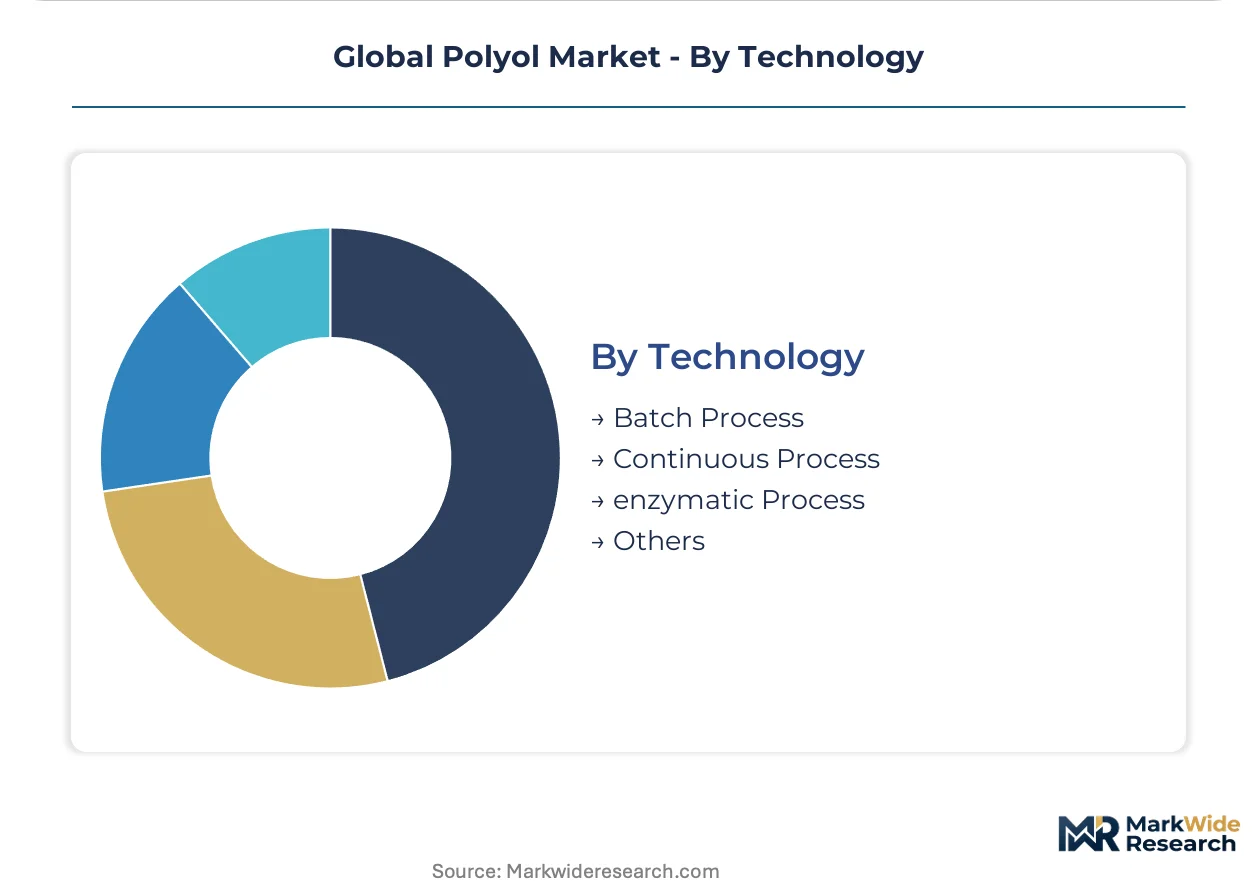
Technology:
Process automation is compressing quality variation while enzymatic routes open bio-based pathways.
- Batch Process:Conventional alkoxylation in stirred-tank reactors serves specialty and small-volume grades. Molecular weight distribution control relies on operator intervention, constraining capacity expansion timelines.
- Continuous Process:Flow reactor technology automates ethylene oxide and propylene oxide addition sequences. German and Japanese automotive seating suppliers adopt these systems to reduce lot-to-lot viscosity variation below three percent.
- Enzymatic Process:Biocatalytic routes convert natural oil feedstocks without harsh chemical conditions. EU Green Deal circular economy requirements are accelerating pilot-scale investments across Belgian and Dutch chemical complexes.
- Others:Hybrid and novel catalytic systems address specific molecular architecture requirements. These approaches remain confined to patent-protected specialty applications.
Continuous process deployment concentrates among integrated petrochemical complexes with captive propylene oxide supply. Enzymatic process expansion is accelerating most quickly as certification schemes for bio-based content mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen anchors European polyol production through integrated petrochemical complexes that feed flexible foam supply chains across Stuttgart and Antwerp. The Rhine corridor concentration shapes procurement patterns for automotive seating and construction insulation.
United States
Detroit-based automotive seating suppliers drive molded foam consumption for Corporate Average Fuel Economy compliance. EPA regulations under the Toxic Substances Control Act govern pre-manufacture notification for novel polyol chemistries. The Gulf Coast petrochemical corridor sustains propylene oxide supply for VORANOL-branded polyether production.
Germany
Appliance manufacturers across Stuttgart and Cologne specify minimum renewable carbon content under EU Green Deal mandates. ECHA enforces REACH registration requirements for chemical safety documentation on all polyol imports. The BASF SE complex in Ludwigshafen delivers cost-advantaged specialty polyether grades to European flexible foam producers.
China
Construction sector procurement absorbs rigid foam volumes for building envelope applications under dual carbon policy implementation. SAMR administers GB standards establishing formaldehyde emission limits for polyurethane foam in furniture and construction. The Yangtze River Delta manufacturing base concentrates appliance production that pulls polyether polyol through domestic supply chains.
India
Bureau of Indian Standards certification for formaldehyde-free insulation creates positioning opportunities for bio-based polyol suppliers. CDSCO oversight of chemical imports intersects with construction sector acceleration in commercial and residential building. The Maharashtra-Gujarat industrial corridor attracts first-mover investments in natural oil polyol distribution infrastructure.
Brazil
Refrigerated transport fleet expansion generates specification demand for high-performance rigid foam systems in cold chain logistics. ANVISA regulates chemical substance registration for polyol formulations used in food-contact applications. The São Paulo industrial basin concentrates polyurethane converters serving Mercosur appliance and packaging markets.
Global Polyol Market Vendor Landscape
Capital-heavy integrated petrochemical producers compete with asset-light specialty formulation houses for differentiated polyol supply relationships. The market structure concentrates upstream propylene oxide supply among Asian merchant producers while fragmenting downstream compounders across regional foam converters. Three archetypes dominate: integrated chemical majors with captive feedstock, specialty polyether houses focused on automotive specification, and bio-based entrants targeting EU Green Deal compliance. Competitive moves center on backward integration into propylene oxide and enzymatic process licensing for natural oil feedstock conversion.
Among German-based integrated producers, BASF SE and Covestro AG exemplify the capital-intensive archetype with upstream control over critical feedstocks. Dow Inc. anchors North American supply relationships through deep integration with Detroit automotive seating programs. Wanhua Chemical Group represents the scale-driven Asian producer expanding merchant polyether capacity.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Shell Chemicals |
| Huntsman International LLC |
| Wanhua Chemical Group |
| Stepan Company |
| Repsol S.A. |
| LANXESS AG |
| Others |
Supply Flow & Price Mechanics
EU Green Deal bio-content mandates for appliance insulation are forcing polyol suppliers to requalify feedstock sources and absorb certification costs that stratify pricing across compliant and non-compliant grades. This demand-side specification shift compresses margins for commodity polyether producers while enabling premium capture for natural oil polyol platforms with verified renewable carbon content.
Pricing Analysis
Cost compression in commodity polyether grades reflects propylene oxide oligopoly pricing power among Asian merchant suppliers. Three-tier pricing structure across specialty, standard, and economy levels differentiates by certification grade and volume scale. Pricing pressure stems from REACH registration cost burdens that deter mid-scale specialty entrants. Furniture manufacturers in Poland and Italy exhibit highest price sensitivity through unbundled technical service procurement, while automotive seating suppliers in Stuttgart and Detroit prioritize lot-to-lot consistency over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle tier-one automotive seating demand, while distributor networks serve fragmented furniture converters across Southern Europe. Supply concentrates in China, Germany, and the United States through integrated petrochemical complexes with captive propylene oxide production. Raw material dependencies rest on propylene oxide, ethylene oxide, and natural oil feedstocks including soybean and castor oil derivatives. Single-source vulnerability around Asian propylene oxide merchant supply creates feedstock price volatility that propagates through polyether margin structures. Distribution runs through regional compounding facilities that blend base polyols with additives for downstream foam converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH registration requirements enforced by ECHA create six-figure documentation barriers that protect established players with existing dossiers.
For Market Incumbents: Deepen backward integration into propylene oxide through long-term offtake agreements with Asian merchant producers to defend against feedstock price volatility. Expand enzymatic process licensing capabilities for natural oil feedstock conversion to capture EU Green Deal premium tiers. Priority lever rests on certifying product carbon footprints ahead of EU CBAM implementation to maintain market access.
For New Entrants and Emerging Players: The price-point gap between premium-certified bio-based grades and economy commodity polyethers creates positioning space for mid-tier hybrid formulations. Target India's Bureau of Indian Standards certification pathway for formaldehyde-free insulation as first-mover white space. Go-to-market angle emphasizes technical service bundling for mid-scale furniture manufacturers seeking multi-source qualification without vendor lock-in.
For Investors and Strategic Acquirers: The window for entry favors specialty polyether houses with automotive specification relationships and existing REACH dossiers. Long-term viability centers on platforms with demonstrated alkoxylation process engineering expertise and backward integration optionality. Signal to watch is propylene oxide contract renegotiation patterns as Asian producers consolidate merchant supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene oxide supply insulates Covestro AG from Asian merchant oligopoly pricing power. |
| Enzymatic Process Licensing | Biocatalytic routes for natural oil conversion accelerate EU Green Deal compliance across Belgian chemical complexes. |
| Long-term Supply Agreement | Fixed-price propylene oxide contracts protect Dow Inc. VORANOL margins against feedstock volatility. |
| Green Certification Program | Product carbon footprint verification enables continued EU market access under CBAM implementation. |
| Joint Venture | Regional compounding partnerships in Maharashtra-Gujarat corridor reduce logistics costs for Indian construction demand. |
Methodological Framework
Document review covered customs and trade data, SEC 10-K filings, and Cefic industry reports, complemented by interviews with plant managers at integrated petrochemical complexes, procurement leads at tier-one automotive seating suppliers, distribution channel partners across European flexible foam markets, and technical R&D directors specializing in alkoxylation process development. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis.
Volume and value trajectories across the analysis window reflect segmented modeling of polyether, polyester, natural oil, and high-functionality grades by end-use industry, application, and regional production hub. CAGRs were derived from regression analysis of historical consumption patterns against macroeconomic drivers and regulatory implementation timelines. Industry-specific inputs included propylene oxide contract pricing indices and REACH registration status databases.
Inputs from ECHA registration databases and SAMR GB standard certification records were available through the study window; gaps in confidential propylene oxide contract terms introduce uncertainty bands around margin compression estimates. Forecasts reflect assumptions regarding EU Green Deal implementation pace and China's dual carbon policy enforcement. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Bio-Based Polypropylene Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Polycide Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Resin Cement for Luting Market