
 Integrated Chemistry Systems Market | 2026-2036
Integrated Chemistry Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Chemistry Systems Market Foresight
A shortage of trained analytical chemists is unwinding traditional laboratory staffing models and pushing facilities toward fully integrated chemistry systems. Danaher Corporation leverages its diagnostics-automation heritage to anchor high-throughput screening workflows for pharmaceutical clients. Thermo Fisher Scientific Inc. sustains competitive positioning through deep manufacturing scale in chromatography-mass spectrometry platforms. Siemens Healthineers AG differentiates via embedded software architectures that bridge clinical chemistry with enterprise data networks.
Integrated chemistry systems combine robotic sample handling, analytical instrumentation, and informatics platforms into unified laboratory workflows capable of processing thousands of samples daily with minimal human intervention. These systems employ liquid-handling robotics with microliter precision, coupled to spectroscopic or electrochemical detectors, to execute standardized protocols for quality control and research applications. Laboratory automation dominates current installed bases due to mature reliability metrics and established service networks, while artificial intelligence integration represents the fastest-expanding technology segment as vendors embed predictive maintenance and autonomous method optimization. Analysis instrumentation commands the deepest margin pools because proprietary detection technologies lock in consumables revenue streams.
The FDA enforces current Good Manufacturing Practice standards that mandate validated analytical methods for pharmaceutical quality control, directly shaping system design priorities for US deployments. REACH and the EU Medical Device Regulation impose substance restriction and clinical evidence requirements that filter market access for European installations. China's NMPA accelerates local type-testing protocols for imported analytical equipment, creating compliance bottlenecks. Stakeholders must weigh regulatory divergence against platform standardization when configuring multi-territory laboratory networks.
Market Dynamics
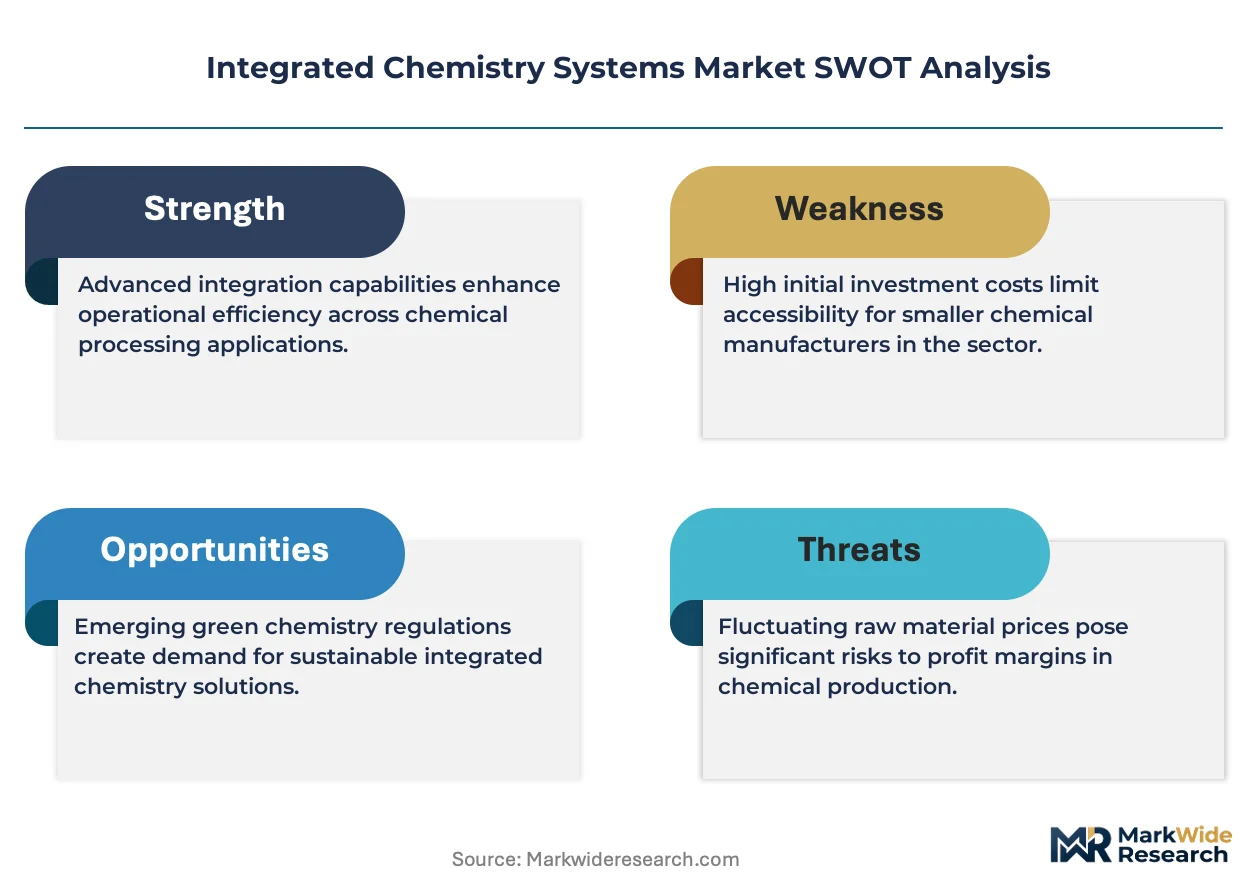
Pharmaceutical manufacturers are compressing analytical timelines through unified robotic workflows, forcing laboratory infrastructure toward end-to-end automation architectures that eliminate manual transfer points between sample prep and detection.
Growth Catalysts
- REACH substance restrictions:European chemical manufacturers must validate trace-level contaminant detection, mandating integrated systems that chain sample prep directly to mass spectrometry without human handling.
- Biologics pipeline expansion:Cell and gene therapy developers require high-throughput potency assays that only robotic liquid-handling platforms can execute at required precision.
- Germany's chemical corridor:Industrial laboratories in Ludwigshafen and Leverkusen are retrofitting legacy workflows, creating concentrated demand for modular automation upgrades.
Market Restraints
- Consumables lock-in costs:Proprietary detection technologies from dominant vendors tether laboratories to expensive reagent contracts that compound operating expenditure.
- Critical component concentration:Precision syringe pumps and optical sensors source predominantly from Japanese and German suppliers, exposing buyers to single-source vulnerability.
- Validation timeline friction:FDA current Good Manufacturing Practice requirements extend system qualification periods, delaying revenue recognition for pharmaceutical quality control deployments.
Strategic Opportunities
- India's contract research expansion:Hyderabad and Bangalore facilities serving multinational pharmaceutical clients lack integrated automation, creating greenfield installation potential.
- Artificial intelligence convergence:Machine learning algorithms embedded within chromatography data systems enable autonomous method optimization and predictive maintenance scheduling.
- China NMPA local type-testing:Accelerated approval pathways for analytical equipment meeting domestic certification standards reward early compliance investment.
Industry Challenges
- Analytical chemist shortage:Universities produce insufficient graduates trained in method development and validation, forcing facilities to operate complex systems with underqualified staff.
- Legacy LIS integration complexity:Hospital and industrial laboratories maintain decades-old laboratory information systems that resist seamless data exchange with modern robotic platforms.
- Multi-site standardization:Pharmaceutical networks struggle to harmonize protocols across facilities when national regulators impose divergent evidence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Chemistry Systems Market |
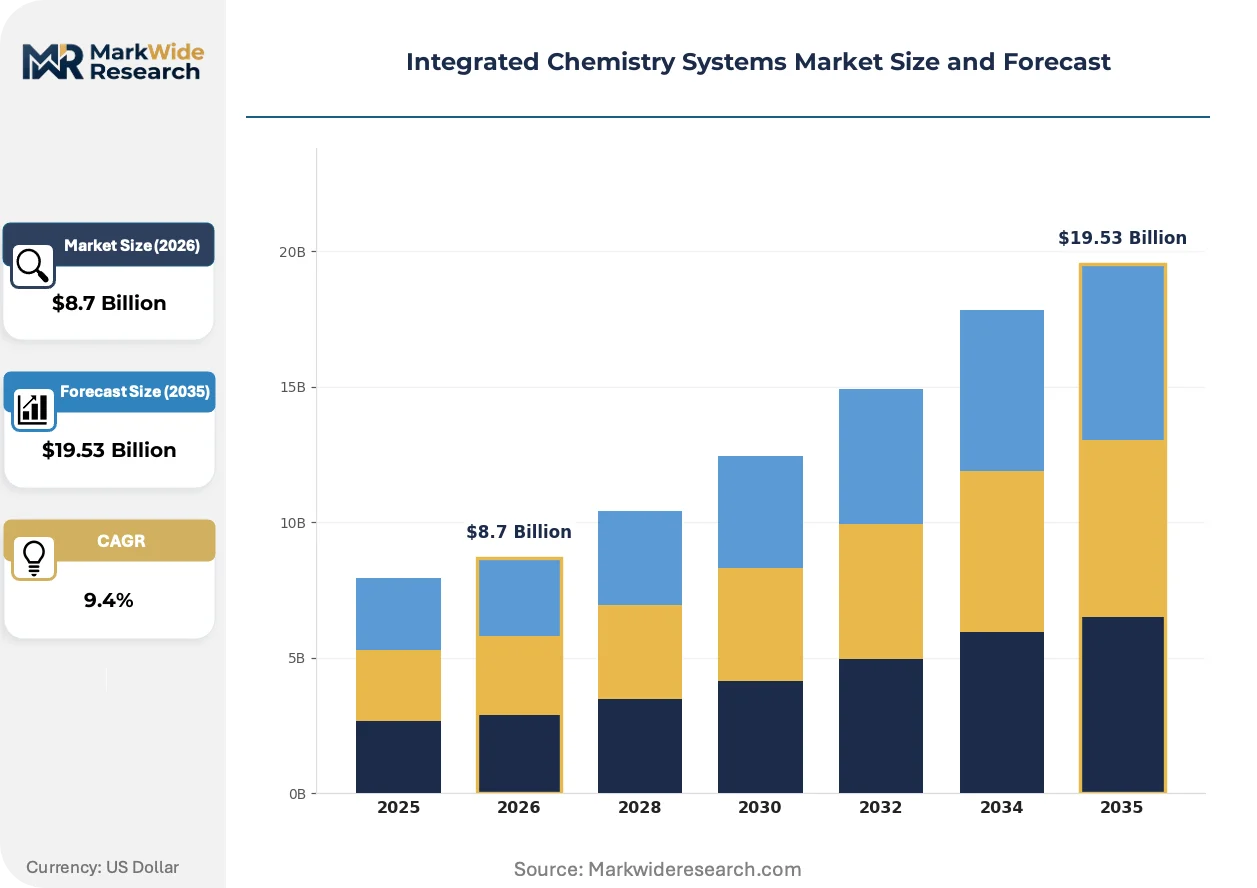
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Automation, Analysis Instrumentation, Sample Management, Data Management End User: Pharmaceutical Companies, Academic Institutions, Environmental Agencies, Chemical Manufacturers Technology: Cloud-Based Solutions, Artificial Intelligence, Robotics, Software Integration Application: Drug Discovery, Quality Control, Research & Development, Environmental Testing |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Danaher Corporation, Thermo Fisher Scientific Inc., HORIBA Ltd., Sysmex Corporation, Hitachi Ltd., Mindray Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Chemistry Systems Market Shifts & Advancements
Automation architectures are fragmenting into modular components that laboratories assemble into customized workflows rather than purchasing monolithic turnkey systems.
Microfluidic sample preparation is decomposing traditional bench-scale chemistry into cartridge-based processing. Biopharmaceutical quality control laboratories are adopting these platforms at accelerating pace to reduce solvent consumption and sample volume requirements. The technology is decomposing capital expenditure structures by shifting costs toward consumable cartridges while compressing method transfer timelines between development and manufacturing sites.
EU Medical Device Regulation clinical evidence requirements are extending validation documentation for analytical systems used in diagnostic workflows. Manufacturers must now generate performance studies demonstrating equivalent accuracy to predicate devices. In vitro diagnostic subsidiaries of diversified life science groups face the steepest compliance burden as they reclassify previously exempt research-use-only platforms.
Service unbundling is separating hardware ownership from method development and regulatory filing support. Mid-sized pharmaceutical companies now lease robotic platforms while purchasing compliance packages from third-party specialists. This pattern concentrates in the United States where contract research organizations build dedicated integration teams that embed within client facilities.
Integrated Chemistry Systems Market Segmentation
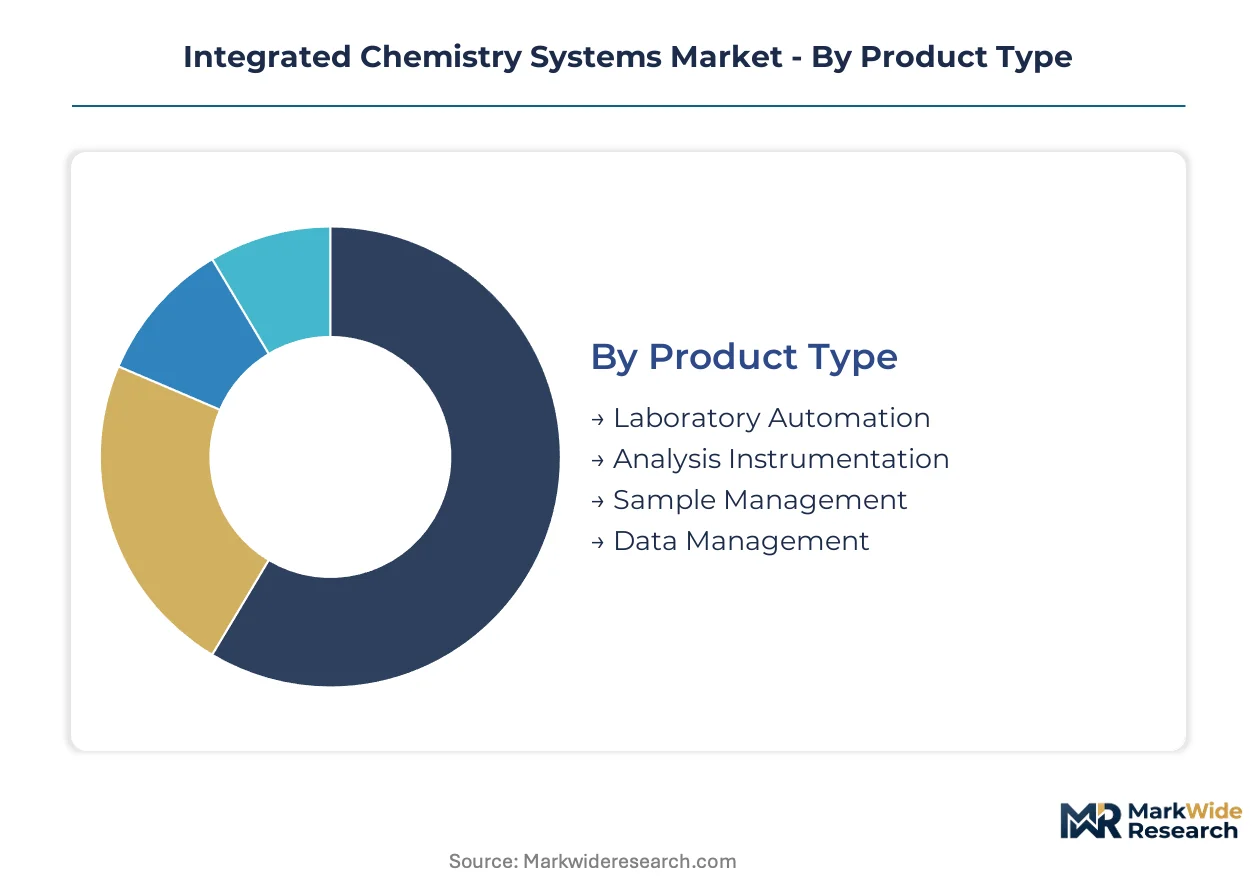
Segmentation in integrated chemistry systems reveals where capital expenditure concentrates and which technology combinations command pricing premiums. Pharmaceutical procurement teams evaluate segments through total cost-of-ownership lenses rather than upfront capital alone.
Product Type:
Laboratory automation faces the most acute substitution pressure as modular robotics vendors displace monolithic platform providers with configurable component architectures.
- Laboratory Automation:Robotic liquid-handling platforms with microliter precision anchor high-throughput screening workflows. Demand concentrates in Germany's chemical corridor where facilities retrofit legacy infrastructure to compress analytical timelines.
- Analysis Instrumentation:Chromatography-mass spectrometry platforms and spectroscopic detectors lock laboratories into proprietary consumables revenue streams. Pharmaceutical quality control laboratories in the United States drive replacement cycles as FDA validation requirements tighten method documentation standards.
- Sample Management:Automated storage and retrieval systems preserve compound integrity across temperature-controlled environments.
- Data Management:Laboratory information systems and chromatography data software bridge analytical output with enterprise networks.
Analysis instrumentation retains volume leadership; laboratory automation holds the steepest expansion curve.
End User:
Cost tier stratification separates pharmaceutical capital deployment from academic procurement constraints, with the former absorbing premium pricing for validated compliance packages.
- Pharmaceutical Companies:Multinational drug manufacturers deploy end-to-end automation architectures to eliminate manual transfer points between sample prep and detection. Investment concentrates in United States and German facilities where REACH and FDA quality system regulations mandate validated analytical methods.
- Chemical Manufacturers:Industrial laboratories in Ludwigshafen and Leverkusen retrofit legacy workflows with modular automation upgrades to meet European substance restriction requirements.
- Academic Institutions:University research laboratories prioritize capital efficiency over throughput specifications.
- Environmental Agencies:Government testing laboratories require standardized protocols for contaminant detection.
Pharmaceutical companies absorb the largest capital share; chemical manufacturers are expanding most quickly.
Technology:
Application specificity determines technology adoption velocity, with artificial intelligence integration outpacing hardware replacement cycles in biopharmaceutical quality control.
- Artificial Intelligence:Machine learning algorithms embedded within chromatography data systems enable autonomous method optimization and predictive maintenance scheduling. Biopharmaceutical developers in the United States deploy these capabilities to reduce method transfer timelines between development and manufacturing sites.
- Robotics:Precision liquid-handling and sample transport systems execute standardized protocols with minimal human intervention.
- Cloud-Based Solutions:Remote data access and multi-site protocol harmonization support distributed pharmaceutical networks.
- Software Integration:Middleware platforms bridge decades-old laboratory information systems with modern robotic architectures.
Robotics commands the deepest installed base; artificial intelligence integration is gaining share fastest.
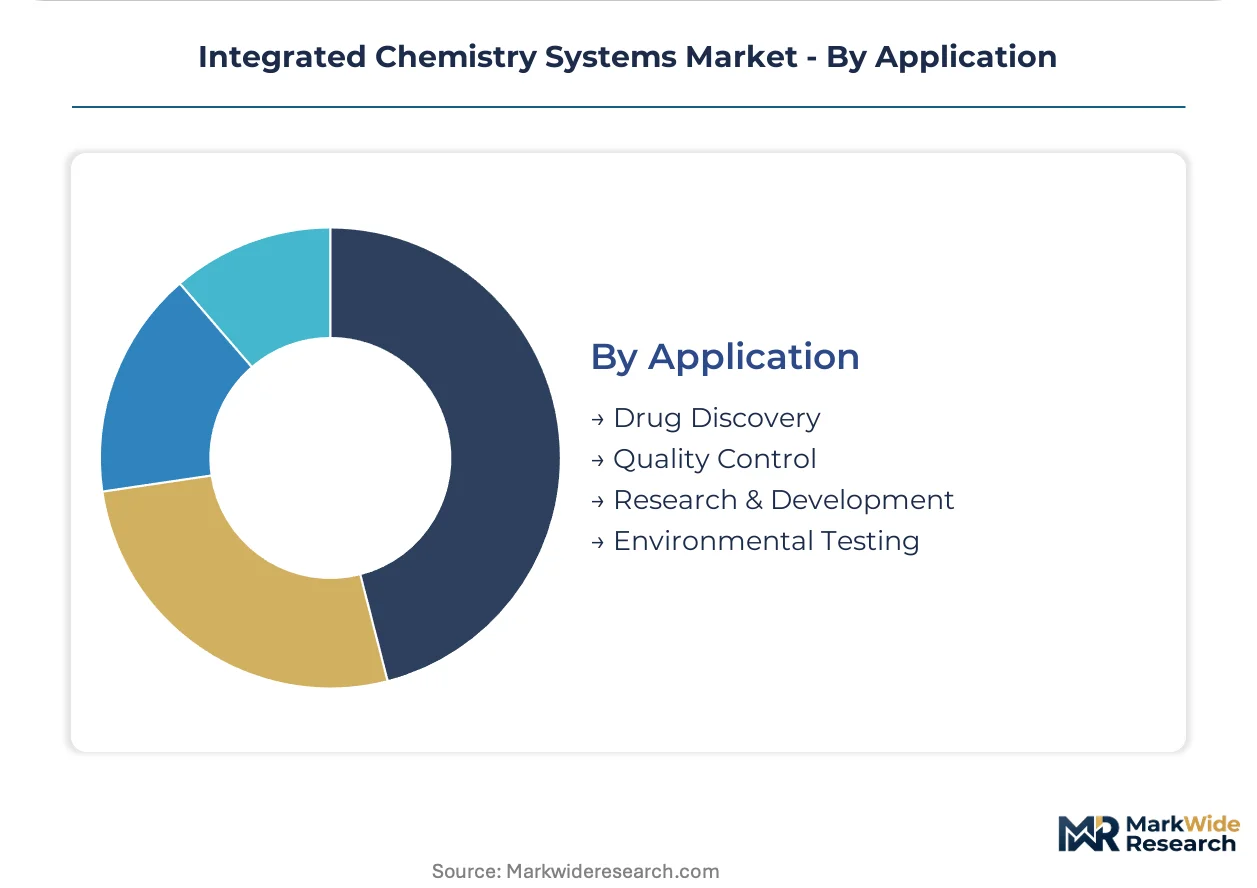
Application:
Customer maturity varies sharply across applications, with quality control demanding validated systems while research environments tolerate experimental configurations.
- Quality Control:Validated analytical methods for pharmaceutical release testing mandate integrated systems that chain sample prep directly to detection without human handling. FDA current Good Manufacturing Practice requirements extend system qualification periods in United States deployments.
- Drug Discovery:High-throughput screening workflows require robotic platforms capable of processing thousands of samples daily.
- Research & Development:Method development environments prioritize flexibility over standardization.
- Environmental Testing:Trace-level contaminant detection for REACH compliance drives demand for mass spectrometry-coupled automation in European installations.
Quality control retains volume leadership; drug discovery holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA quality system regulations in the United States anchor the dominant geography, while REACH substance restrictions in Europe and NMPA certification protocols in China shape multi-territory deployment strategies for integrated chemistry systems.
United States
Pharmaceutical quality control laboratories in Massachusetts and New Jersey drive replacement cycles for chromatography-mass spectrometry platforms. FDA current Good Manufacturing Practice requirements extend system qualification periods, delaying revenue recognition but tightening method documentation standards. Greater Boston hosts contract research organizations building dedicated integration teams that embed within client facilities.
Germany
Industrial laboratories in Ludwigshafen and Leverkusen retrofit legacy workflows with modular automation upgrades to meet European substance restriction requirements. REACH compliance mandates validated trace-level contaminant detection, chaining sample prep directly to mass spectrometry without human handling. The chemical manufacturing corridor concentrates demand for end-to-end automation architectures.
China
Biopharmaceutical developers in Shanghai and Suzhou deploy machine learning algorithms within chromatography data systems to reduce method transfer timelines. NMPA accelerates local type-testing protocols for imported analytical equipment, creating compliance bottlenecks that reward early certification investment. Yangtze River Delta facilities lack integrated automation, creating greenfield installation potential.
India
Contract research facilities in Hyderabad and Bangalore serving multinational pharmaceutical clients require high-throughput potency assays for cell and gene therapy pipelines. CDSCO regulatory convergence with ICH guidelines streamlines validation documentation for imported platforms. Karnataka's biotech corridor is expanding automated liquid-handling capacity to meet precision requirements.
Japan
Precision syringe pump and optical sensor suppliers in Nagoya and Osaka face single-source vulnerability exposure as pharmaceutical manufacturers seek supply chain resilience. PMDA quality management system requirements align with international harmonization initiatives, reducing regulatory friction for validated analytical methods. Kansai region industrial laboratories prioritize predictive maintenance scheduling through embedded software architectures.
Integrated Chemistry Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around diversified life science groups and pure-play automation vendors. The upper tier commands proprietary detection technologies that lock laboratories into consumables revenue streams. Strategic archetypes include diagnostics-automation heritage players, chromatography-scale manufacturers, and embedded software architects. Competitive moves concentrate on M&A for regulatory filing capabilities and strategic partnerships for modular component sourcing.
Among diversified conglomerates with diagnostics roots, Danaher Corporation and Siemens Healthineers AG exemplify the integrated-leader archetype through their automation heritage and embedded software architectures respectively. Thermo Fisher Scientific Inc. occupies a scale-driven position reflecting deep manufacturing presence in analytical detection platforms. These three entities anchor the premium tier where proprietary technologies and service networks create defensive positioning around pharmaceutical quality control workflows.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers AG |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| HORIBA Ltd. |
| Sysmex Corporation |
| Hitachi Ltd. |
| Mindray Medical |
| Others |
Supply & Pricing Matrix
Long-term consumables contracts lock pharmaceutical laboratories into predictable reagent expenditure while securing vendor commitment to validation support and service continuity across multi-year deployments. This contract structure concentrates price visibility in the hands of dominant platform vendors who bundle proprietary detection technologies with mandatory reagent supply agreements.
Pricing Analysis
Contract-based long-term offtake dominates integrated chemistry system procurement, with pharmaceutical quality control laboratories committing to five-to-seven-year reagent supply agreements tied to chromatography-mass spectrometry platforms. Price differentiation rests on certification grade—FDA-validated systems command substantial premiums over research-use-only configurations—and volume scale, where high-throughput screening facilities negotiate tiered discounts based on annual consumables throughput. Cost compression in mid-tier automation is intensifying because modular robotics vendors are displacing monolithic platform providers with configurable component architectures. Academic institutions exhibit the highest price sensitivity due to capital budget constraints, while multinational pharmaceutical manufacturers absorb premium pricing for validated compliance packages.
Supply Chain Analysis
Strategic stockpiling of precision syringe pumps and optical sensors characterizes buyer behavior as pharmaceutical manufacturers buffer against single-source vulnerability from Japanese and German component suppliers. Geographic supply concentration centers on Japan for precision fluidics, Germany for optical detection modules, and the United States for chromatography data system software. Raw material dependencies include high-purity solvents, specialized polymer cartridges for microfluidic sample preparation, and rare-earth-doped optical crystals for spectroscopic detectors. Single-source vulnerability constitutes the dominant structural risk as precision component suppliers in Nagoya and Osaka face limited alternative sourcing. Distribution runs through authorized service networks that embed field engineers within pharmaceutical manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among multinational pharmaceutical consolidators who negotiate enterprise-wide automation contracts spanning multiple manufacturing sites. This consolidation fragments pricing leverage for mid-sized automation vendors.
For Market Incumbents: Shield installed base revenue by embedding predictive maintenance software architectures that increase switching costs for pharmaceutical quality control laboratories. Deepen backward integration into precision fluidics manufacturing to reduce exposure to Japanese component suppliers. Prioritize certification investment for EU Medical Device Regulation compliance to defend against emerging modular robotics vendors. For New Entrants and Emerging Players: Regulatory filing support services represent a critical service-layer gap where incumbents under-serve mid-sized pharmaceutical companies lacking internal validation expertise. Target India's contract research expansion in Hyderabad and Bangalore, where greenfield facilities require integrated automation without legacy system constraints. Pursue compliance-as-a-service bundling to differentiate from hardware-centric incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward embedded software specialists with chromatography data system expertise and established FDA filing track records. Long-term viability hinges on recurring revenue share from consumables and service contracts rather than upfront hardware margins. Watch for inflection when NMPA accelerates local type-testing approvals for imported analytical equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Filing Capability Acquisition | Absorbing specialized validation expertise accelerates FDA submission timelines for pharmaceutical clients. |
| Modular Component Partnership | Strategic alliances with precision fluidics suppliers reduce single-source vulnerability in Japanese supply chains. |
| AI-Enabled Predictive Maintenance Launch | Embedded machine learning algorithms differentiate chromatography data systems in biopharmaceutical quality control. |
| India Greenfield Installation Expansion | Hyderabad and Bangalore contract research facilities lack integrated automation, creating first-mover positioning. |
| Consumables Supply Agreement Restructuring | Unbundling reagent contracts from hardware purchases responds to pharmaceutical procurement cost pressure. |
Research Methodology
A spread of perspectives from pharmaceutical quality control directors, regulatory affairs leads at analytical instrumentation vendors, laboratory automation procurement managers, and contract research organization facility heads converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EMA medical device registrations, SEC 10-K disclosures from diversified life science groups, and chromatography data system patent filings. Bottom-up triangulation across installation base estimates and top-down cross-checks against pharmaceutical capital expenditure disclosures anchored the market sizing.
Segmentation dimensions modeled span product type, end user, technology, and application, with additional granularity across regional regulatory clusters and validation tier. CAGRs were derived from trend extrapolation of replacement cycles, greenfield installation pipelines, and technology substitution rates. Forecast inputs incorporated biologics pipeline expansion trajectories, REACH substance restriction enforcement timelines, and NMPA local type-testing protocol evolution across the analysis window.
Underlying assumptions cover sustained pharmaceutical R&D expenditure, continued regulatory divergence between FDA and EMA requirements, and stable precision component supply from Japanese and German suppliers, with deviation risk concentrated in trade policy shifts affecting analytical instrumentation tariffs. Revision becomes warranted when biologics pipeline attrition crosses thresholds that compress quality control capital deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Sodium Fluorosilicate Market
Chemicals
Phenothiazine Market
Chemicals
United States Construction Chemicals Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Europe Biguanide Market
Chemicals
Aircraft Cleaning Chemicals Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Industrial Odor Management Market
Chemicals
Scouring Agents Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Triisopropanolamine (TIPA) Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
Calcium Hydride Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
1-Methylimidazole Market