
 Photopolymers Market | 2026-2036
Photopolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Photopolymers Market Analytics
The capital-intensity divergence between resin synthesis and downstream formulation is collapsing as integrated producers capture margin pools previously lost to toll manufacturers. BASF SE leverages captive acrylic acid supply to dominate liquid photopolymer feedstock economics. Stratasys Ltd. anchors its hardware-locked resin strategy through proprietary cartridge architectures that limit third-party material substitution. Carbon, Inc. differentiates via programmable liquid crystal elastomer lattices that command premium positioning in medical device prototyping.
Photopolymers are light-activated resin systems that undergo radical or cationic polymerization upon exposure to UV, visible, or electron beam radiation, typically formulated with oligomers, monomers, photoinitiators, and functional additives to achieve tunable viscosity and cure speed. These materials serve as the foundational chemistry for stereolithography, digital light processing, and inkjet-based additive manufacturing where layer-wise photopolymerization builds dimensionally accurate parts. Liquid photopolymers lead volume consumption due to their dominance in vat-polymerization 3D printing platforms, though dry film formulations sustain higher margins in semiconductor packaging and flexible circuit lamination. UV curing technology occupies the largest installed base across coating and adhesive lines, while LED curing systems represent the fastest-growing segment as mercury lamp phase-outs accelerate under EU RoHS amendments and EPA toxic substance evaluations.
FDA 21 CFR Part 175 indirect food contact regulations and EPA TSCA Section 5 pre-manufacture notification requirements shape monomer selection and new product introduction timelines in the United States, while REACH Annex XVII restrictions on acrylate skin sensitizers constrain formulation flexibility across European supply chains. China's GB standards for photocurable coatings and Japan's METI chemical substance classification system add compliance layers for regional market access. Stakeholders must monitor photoinitiator substitution dynamics as BAPO-type initiators face regulatory pressure and determine whether bio-based acrylate development warrants dedicated R&D allocation versus licensing strategies.
Market Dynamics
UV-LED curing hardware is collapsing photopolymer processing economics across coating and adhesive lines, compressing mercury lamp replacement cycles from ten-year intervals to three-year refresh mandates under EU RoHS amendments and EPA toxic substance evaluations.
Growth Catalysts
- Dental Aligner Manufacturing:Medical device producers in Germany and Japan are displacing thermoset systems with UV-curing formulations for clear orthodontic devices, driving resin formulation specialization.
- REACH Annex XVII:European restrictions on acrylate skin sensitizers are accelerating photoinitiator substitution toward BAPO alternatives, opening formulation service contracts.
- Printed Circuit Board Fabrication:Japan's Kansai corridor and Taiwan's semiconductor packaging hubs sustain dry film photopolymer consumption for high-density interconnect substrates.
Market Restraints
- Photoinitiator Supply Concentration:Three Chinese producers control 70% of TPO and BAPO raw material output, creating single-source vulnerability for European formulators.
- Acrylic Acid Price Volatility:Crude propylene feedstock fluctuations transmit directly to oligomer cost structures, compressing toll manufacturer margins.
- Thermoset Substitution in Thick Sections:Epoxy and polyurethane systems retain cost advantage in parts exceeding 50mm cure depth, limiting photopolymer addressable market.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Domestic manufacturing incentives are attracting photopolymer distributors to establish formulation facilities near Ahmedabad and Hyderabad dental clusters.
- Bio-Based Acrylate Development:Lignin-derived oligomers from Finnish pulp mills offer regulatory positioning under EU Green Deal procurement criteria.
- Programmable Liquid Crystal Elastomers:Convergence of DLP hardware with mesogenic monomer chemistry enables lattice structures for soft robotics prototyping.
Industry Challenges
- Photochemistry Talent Scarcity:Formulation laboratories face recruitment gaps for radical polymerization kinetics specialists capable of tuning gel point conversion rates.
- Multi-Jurisdictional Notification Timelines:EPA TSCA Section 5 pre-manufacture reviews and China's SAMR registration requirements extend new product introduction cycles by 14-18 months.
- Legacy Vat Polymerization Hardware Lock-In:Stratasys cartridge architectures and Carbon's proprietary resin channels limit third-party material substitution for installed base customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photopolymers Market |
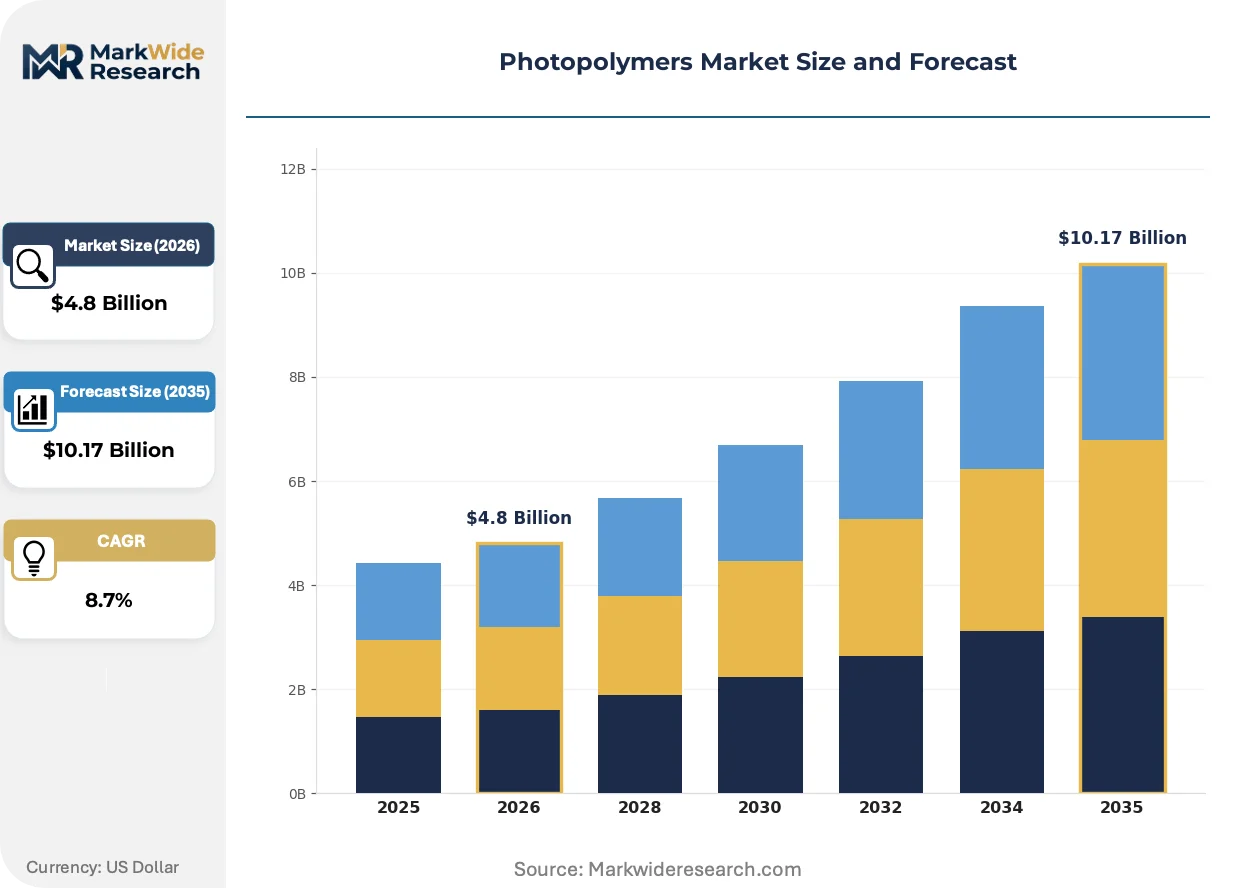
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Photopolymers, Dry Photopolymers, Powder Photopolymers, Hybrid Photopolymers Application: 3D Printing, Coatings, Adhesives, Electronics End User: Consumer Goods, Automotive Parts, Medical Devices, Aerospace Components Technology: UV Curing, LED Curing, Thermal Curing, Electron Beam Curing |
| Companies Covered | BASF SE, Stratasys Ltd., 3D Systems Corporation, Carbon, Inc., Henkel AG & Co. KGaA, DuPont de Nemours, Inc., Evonik Industries AG, Arkema, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photopolymers Market Evolving Landscape
Photopolymer chemistry is fragmenting into application-specific formulations as hardware OEMs tighten material ecosystems and regulatory pressure accelerates photoinitiator substitution timelines.
LED-curable cationic epoxy formulations are miniaturizing semiconductor encapsulation processes. Advanced packaging houses in South Korea and Taiwan are adopting these systems for wafer-level chip-scale packages, replacing thermal cure cycles that previously required 90-minute oven dwells. The technology is miniaturizing process footprints from batch ovens to inline conveyor systems, compressing cleanroom capital requirements by 40%.
ECHA's 2023 restriction proposal on TPO photoinitiator is forcing formulation reformulation across European coating lines. Industrial finishers in Germany's automotive supplier corridor are accelerating BAPO and oxime ester alternatives qualification, with compliance deadlines compressing supplier development cycles. Decorative wood coating segments face the steepest cost pass-through as TPO alternatives carry 15-20% raw material premiums.
Direct resin purchasing from chemical producers is displacing distributor intermediaries among high-volume dental aligner manufacturers. Align Technology and regional competitors in China's Hangzhou cluster are establishing annual volume contracts with BASF and Allnex, bypassing traditional dental supply houses. This channel compression is most visible in North America and Western Europe where aligner production concentrates in single-facility operations exceeding 100,000 units annually.
Photopolymers Market Segmentation
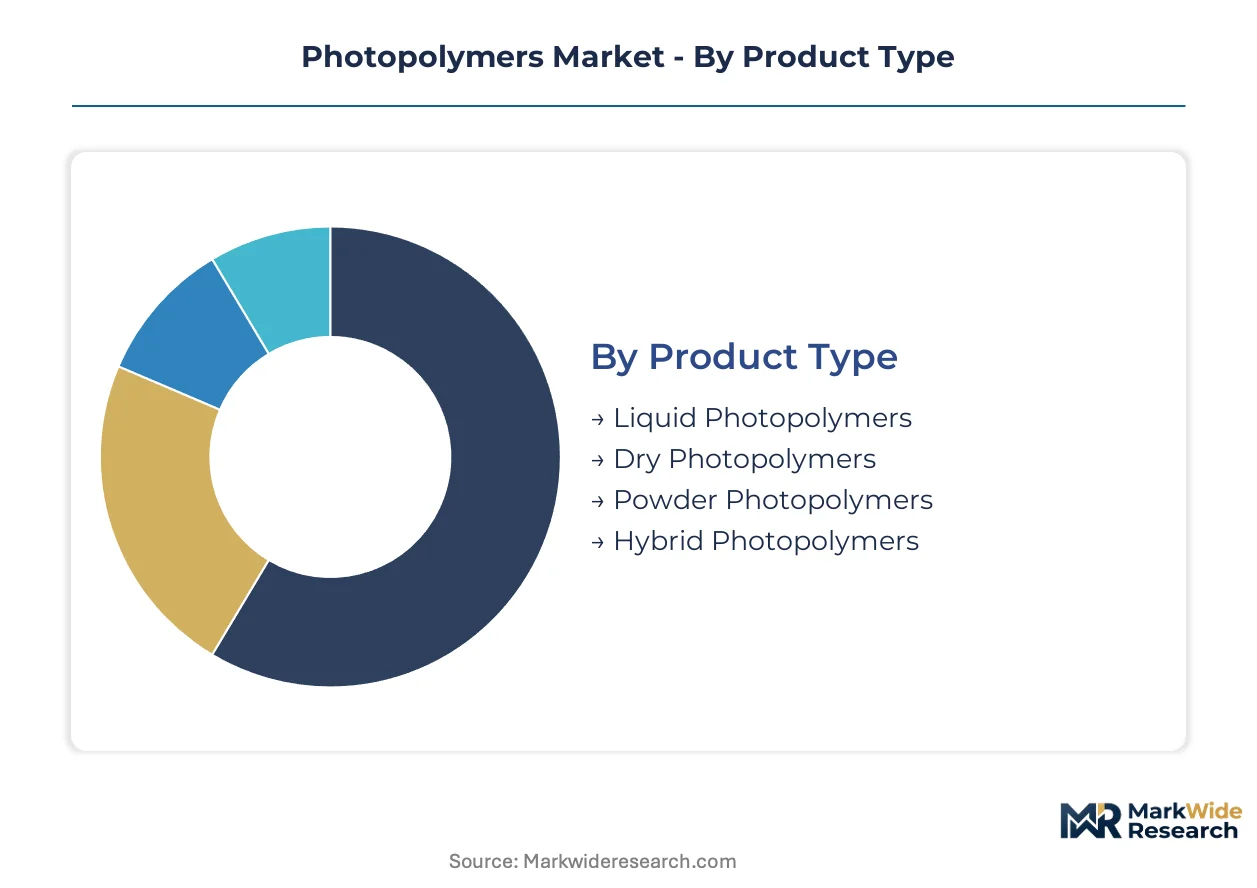
Photopolymer market segmentation reveals how margin pools migrate between formulation chemistry, hardware compatibility, and regulatory positioning. Understanding these divisions exposes where integrated producers capture value versus where toll manufacturers face compression.
Product Type:
Margin concentration sits with formulations that solve specific processing constraints rather than commodity resin supply.
- Liquid Photopolymers:Low-viscosity oligomer-monomer blends dominate vat-polymerization 3D printing platforms. Demand concentrates in Germany's dental aligner manufacturing corridor where UV-curing formulations displace thermoset systems for clear orthodontic devices.
- Dry Photopolymers:Solvent-free film formulations laminate flexible circuits and semiconductor substrates. Japan's Kansai corridor and Taiwan's packaging hubs sustain premium positioning for high-density interconnect applications.
- Powder Photopolymers:Solid resin particles enable selective laser sintering workflows. Automotive prototyping studios in Stuttgart and Detroit represent primary offtake.
- Hybrid Photopolymers:Dual-cure systems combine photoinitiated and thermal polymerization mechanisms. Aerospace composite tooling in Toulouse and Hamburg drives qualification timelines.
Liquid photopolymers hold installed capacity. Dry photopolymers are rotating up the share rankings.
Application:
Application segmentation tracks how curing hardware investments reshape addressable chemistry demand.
- 3D Printing:Layer-wise photopolymerization builds dimensionally accurate parts through stereolithography and digital light processing. Stratasys and Carbon hardware ecosystems in North America and Western Europe lock resin formulation specifications.
- Coatings:UV-curable surface finishes protect automotive interior components and decorative wood products. ECHA restrictions on acrylate skin sensitizers accelerate photoinitiator substitution toward BAPO alternatives.
- Adhesives:Rapid-setting bonds assemble electronics and medical device subcomponents. LED curing systems displace mercury lamp lines under EU RoHS amendments.
- Electronics:Photoresists and solder masks pattern printed circuit boards. Taiwan's semiconductor packaging cluster maintains dry film consumption for wafer-level chip-scale packages.
Coatings command the broadest installed base. 3D printing applications are climbing the fastest.
End User:
End user segmentation exposes how regulatory pathways and certification requirements fragment formulation specifications.
- Medical Devices:FDA 21 CFR Part 175 indirect food contact regulations and biocompatibility ISO 10993 testing shape monomer selection. Clear aligner producers in Germany and Japan establish direct resin contracts with BASF and Allnex.
- Automotive Parts:Interior trim coatings and headlamp lens assemblies require weathering resistance and optical clarity. Suppliers to BMW and Mercedes-Benz specify acrylated urethane oligomers.
- Consumer Goods:Packaging coatings and novelty 3D-printed products tolerate lower performance thresholds. Price sensitivity drives distributor purchasing through traditional channels.
- Aerospace Components:Flame-retardant specifications and outgassing controls constrain formulation flexibility. Airbus and Boeing tier-one suppliers qualify resins through 18-month validation cycles.
Medical devices concentrate margin extraction. Automotive parts are gaining share fastest.
Technology:
Technology segmentation captures how curing hardware replacement cycles compress or extend resin demand visibility.
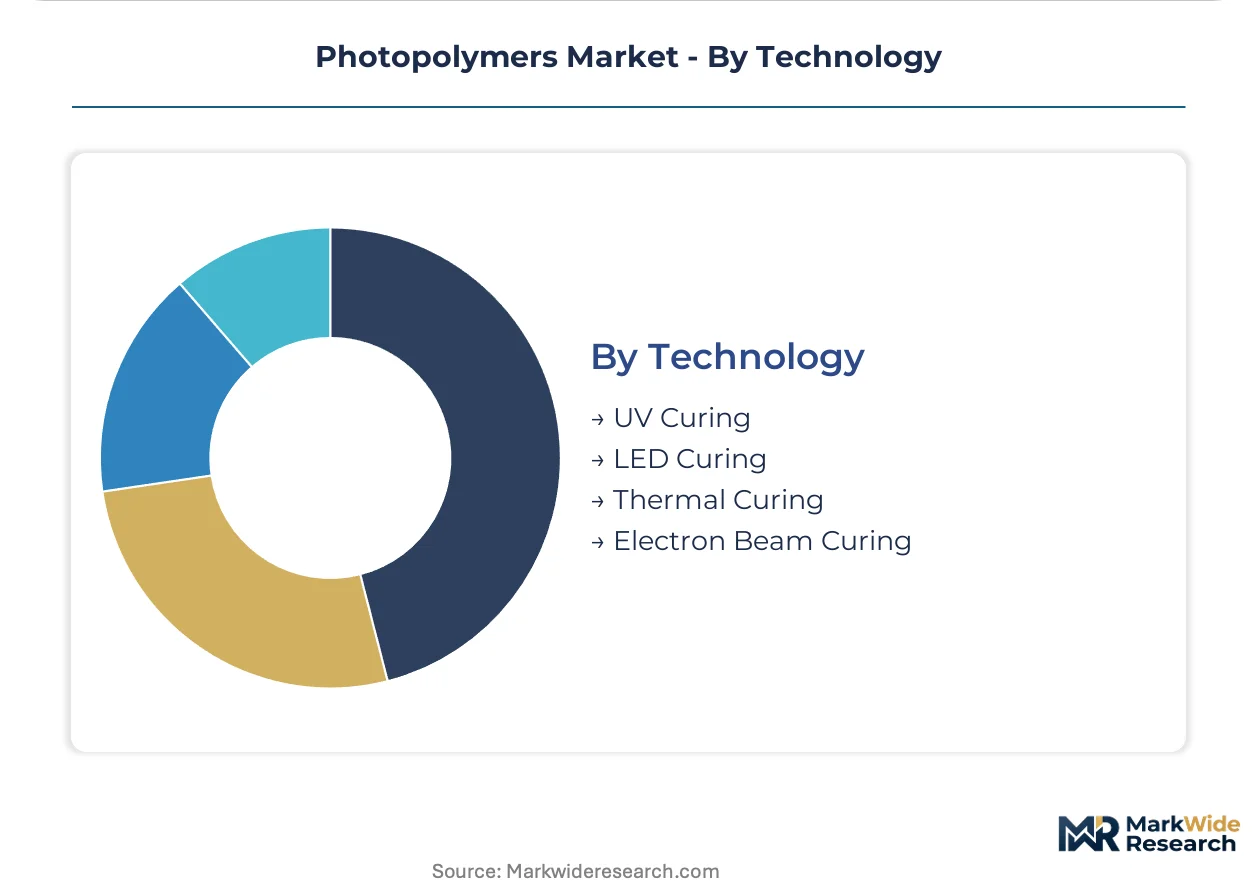
- UV Curing:Mercury vapor lamp systems occupy the largest installed base across coating and adhesive production lines. EPA toxic substance evaluations and EU RoHS amendments accelerate phase-out timelines.
- LED Curing:Solid-state UV sources reduce energy consumption and eliminate mercury handling. South Korean and Taiwanese advanced packaging houses adopt these systems for semiconductor encapsulation.
- Thermal Curing:Oven-based polymerization persists where photoinitiation cannot penetrate thick sections. Epoxy and polyurethane systems retain cost advantage in parts exceeding 50mm cure depth.
- Electron Beam Curing:High-energy radiation polymerizes resins without photoinitiator requirements. Food packaging sterilization applications in Switzerland and the Netherlands drive niche adoption.
UV curing maintains the deepest installed base. LED curing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's dental clusters demonstrate acute price sensitivity, while German precision optics manufacturers absorb raw material premiums without volume elasticity. This demand-elasticity contrast shapes regional formulation strategies and distribution economics.
United States
FDA 21 CFR Part 175 indirect food contact regulations constrain monomer selection for medical device applications. EPA TSCA Section 5 pre-manufacture notification timelines extend new product introduction cycles by 14-18 months. Dental aligner production concentrates in Texas and California single-facility operations exceeding 100,000 units annually, driving direct resin contracts with integrated chemical producers.
Germany
REACH Annex XVII restrictions on acrylate skin sensitizers accelerate photoinitiator substitution toward BAPO alternatives. ECHA's 2023 TPO restriction proposal compresses supplier development cycles for industrial finishers. The precision optics cluster around Jena and Stuttgart sustains premium positioning for UV-curing formulations in automotive interior coatings.
China
SAMR accelerates domestic standardization for photocurable coatings through GB standards implementation. Three Chinese producers control 70% of TPO and BAPO raw material output, creating single-source vulnerability for European formulators. The Hangzhou dental cluster attracts annual volume contracts from aligner manufacturers bypassing traditional supply houses.
Japan
METI chemical substance classification system adds compliance layers for regional market access. The Kansai corridor sustains dry film photopolymer consumption for high-density interconnect substrates in semiconductor packaging. LED curing systems displace mercury lamp lines under accelerating phase-out mandates.
India
PLI scheme incentives for medical devices attract photopolymer distributors to establish formulation facilities near Ahmedabad and Hyderabad dental clusters. BIS standards for photocurable materials remain under development, creating regulatory uncertainty for imported formulations. Price-sensitive procurement patterns favor distributor intermediaries over direct chemical producer relationships.
Photopolymers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical producers dominating feedstock economics while hardware-locked specialists capture premium formulation margins. The market structure concentrates around captive supply chains and proprietary cartridge architectures that limit third-party material substitution. Three strategic archetypes define competitive positioning: backward-integrated resin producers, hardware-tied formulation specialists, and toll manufacturers serving regional dental clusters. Dominant competitive moves include strategic partnerships between chemical producers and aligner manufacturers, plus capacity expansion in bio-based acrylate development.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify producers leveraging captive acrylic acid supply to dominate liquid photopolymer feedstock economics. Among hardware-locked specialists, Stratasys Ltd. occupies a position representing proprietary cartridge architectures that constrain material substitution for installed base customers. These company patterns illustrate how margin pools migrate between resin synthesis and downstream formulation as supply chain control reshapes competitive boundaries.
| Leading Market Players |
|---|
| BASF SE |
| Stratasys Ltd. |
| 3D Systems Corporation |
| Carbon, Inc. |
| Henkel AG & Co. KGaA |
| DuPont de Nemours, Inc. |
| Evonik Industries AG |
| Arkema |
| Covestro AG |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 175 indirect food contact regulations and EPA TSCA Section 5 pre-manufacture notification requirements gate both supply qualification timelines and price differentiation between medical-grade and industrial-grade photopolymer formulations. These certification layers create tiered entry barriers where biocompatible resins command sustained premiums over commodity coating grades.
Pricing Analysis
After-sales service contracts and technical formulation support drive lifetime value capture beyond initial resin sales. The dominant pricing structure combines per-unit transactional pricing for standard grades with project-based contracting for customized dental and aerospace formulations. Price differentiation rests on ISO 10993 biocompatibility certification tier and vertical integration depth of the supplier. Cost compression in decorative wood coating segments is intensifying because ECHA's TPO restriction forces 15-20% raw material premiums onto formulators. Dental aligner manufacturers in Germany and Japan show the lowest price sensitivity, while India's Ahmedabad cluster buyers negotiate aggressively on spot purchases.
Supply Chain Analysis
Strategic stockpiling of photoinitiator inventories dominates over just-in-time preferences given the 70% supply concentration of TPO and BAPO raw materials among three Chinese producers. Manufacturing capacity concentrates in Germany, China, and Japan for oligomer synthesis and downstream formulation. The supply chain draws from crude propylene feedstocks, specialty photoinitiator chemicals, and functional additive packages. Single-source vulnerability for European formulators creates structural risk exposure to export restriction scenarios. Distribution runs through direct annual volume contracts for high-volume dental manufacturers and distributor intermediaries for regional coating applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The photopolymers market operates as a substitution defense against thermoset epoxy and polyurethane systems that retain cost advantages in thick-section curing applications above 50mm depth.
For Market Incumbents: Consolidate formulation service capabilities around REACH Annex XVII compliance support to capture reformulation contracts as TPO restrictions tighten. Deepen backward integration into captive acrylic acid supply to defend margin position against propylene feedstock volatility. Lock in direct resin contracts with aligner manufacturers exceeding 100,000 annual units to bypass distributor compression. For New Entrants and Emerging Players: Photoinitiator substitution technical services represent a service-layer gap where incumbents under-serve mid-tier European coating finishers facing compressed compliance deadlines. India's PLI scheme medical device clusters offer the most penetrable geography for formulation facility establishment near Ahmedabad and Hyderabad dental manufacturing. A qualification-as-a-service go-to-market angle accelerates customer acquisition among formulators lacking in-house photochemistry expertise. For Investors and Strategic Acquirers: ECHA's 2023 TPO restriction proposal reshapes the acquisition landscape toward formulators with qualified BAPO and oxime ester alternative portfolios. Long-term viability favors targets with demonstrated regulatory navigation capabilities across FDA, REACH, and SAMR jurisdictions. The signal to watch is photoinitiator substitution timeline acceleration as additional European restriction proposals emerge.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | BASF's captive supply dominance demonstrates feedstock cost control that toll manufacturers cannot replicate. |
| Photoinitiator Substitution R&D Investment | Qualification of BAPO alternatives ahead of ECHA compliance deadlines captures stranded European coating demand. |
| Direct Aligner Manufacturer Contracts | Channel compression in North America and Western Europe rewards bypass of traditional dental supply houses. |
| India Formulation Facility Establishment | PLI scheme incentives near Ahmedabad and Hyderabad clusters align with price-sensitive procurement patterns. |
| LED Curing Hardware Partnership | South Korean and Taiwanese advanced packaging adoption accelerates resin demand visibility for semiconductor encapsulation grades. |
Research Methodology
Cross-validation between primary interviews with resin synthesis plant managers, dental device procurement leads, coating applicator technical directors, and photoinitiator distribution channel partners anchors the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of integrated chemical producers, ECHA restriction proposal documentation, and SAMR GB standards publications. Bottom-up demand modeling from individual application segments triangulates against top-down supply-side capacity assessments across the analysis window.
Sensitivity analysis across oligomer grade tier, end-use industry concentration, curing technology platform, and regional regulatory cluster dimensions shapes the analytical framework. CAGRs derive from segment-level demand elasticity coefficients applied to installed base replacement cycles and new capacity absorption rates. Forecast inputs incorporate UV-LED curing hardware penetration curves and REACH Annex XVII compliance timeline assumptions.
Forecasts assume regulatory continuity in FDA 21 CFR Part 175, REACH Annex XVII, and SAMR GB standard regimes; material policy shifts would require re-modeling. Specific risk factors include photoinitiator export restrictions from Chinese suppliers and accelerated mercury lamp phase-outs under EPA toxic substance evaluations. Revision becomes warranted when LED curing system adoption in semiconductor packaging crosses threshold penetration rates that structurally displace incumbent UV lamp resin formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Microcellular Plastics Market