
 Polyurethanes (PU) Market | 2026-2036
Polyurethanes (PU) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethanes (PU) Market Analytics
Bio-based polyol chemistry is rewriting material selection protocols across PU value chains. BASF SE leverages its vertical integration into renewable feedstocks to anchor European supply positions. Covestro AG competes through specialty isocyanate capacity tailored to automotive lightweighting programs. Dow Inc. dominates North American spray foam distribution through contractor channel control and technical service density.
Polyurethanes comprise a class of polymers formed by reacting a diisocyanate with a polyol, yielding carbamate linkages that enable tunable density, elasticity, and thermal resistance from rigid to flexible systems. Flexible foam commands mature volume positions in furniture and bedding, while rigid foam captures expanding margin pools tied to construction insulation mandates. Coatings and adhesives segments sustain above-average growth as manufacturers substitute solvent-based alternatives with low-VOC polyurethane formulations in automotive and industrial maintenance applications.
EPA regulations under SNAP and Significant New Alternatives Policy constrain blowing agent chemistries, redirecting formulation investment toward low-GWP options. REACH and the EU F-Gas Regulation impose parallel substance restrictions and thermal performance standards that reshape product certification requirements across European construction markets. OSHA workplace exposure limits for isocyanates drive capital allocation toward enclosed processing equipment and automated metering systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation assets and secure cross-border market access.
Market Dynamics
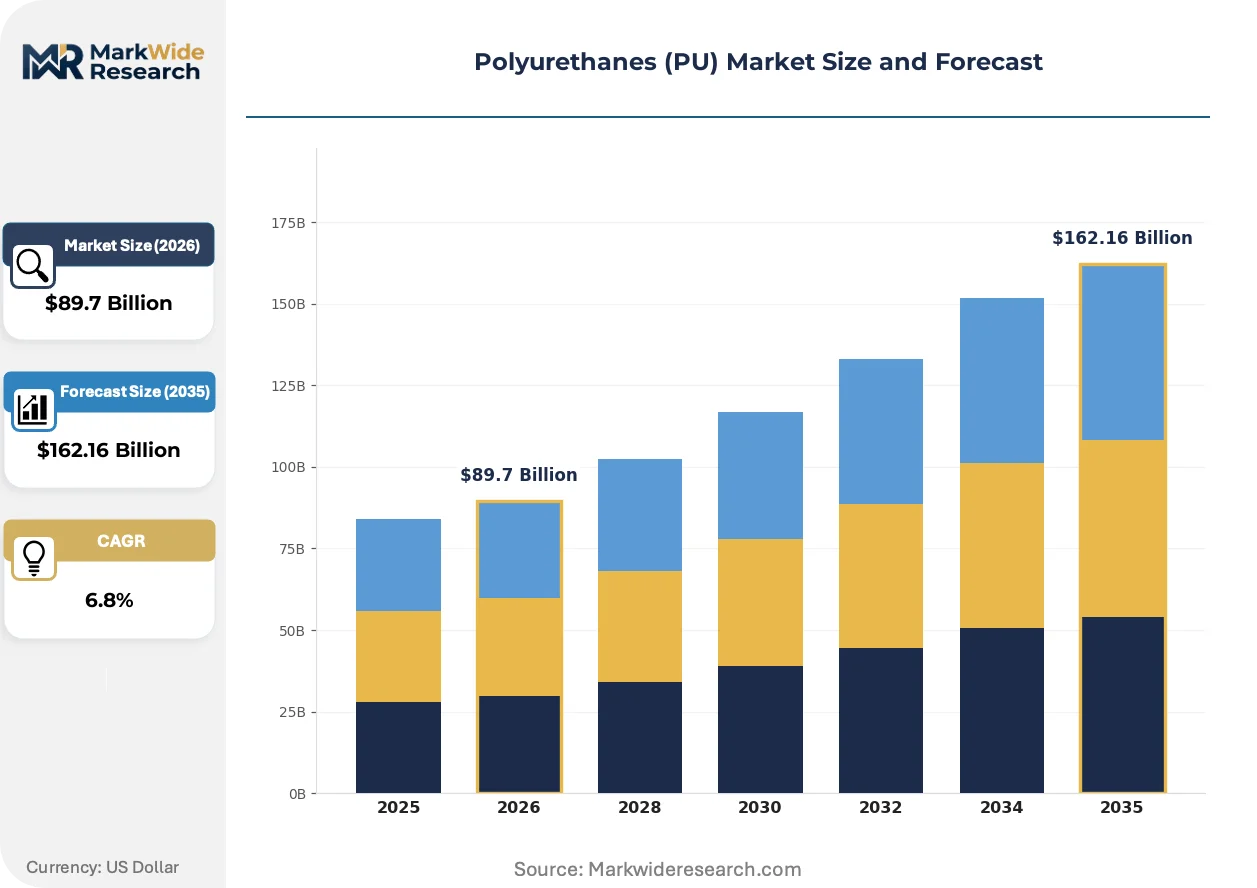
Construction insulation mandates are compressing formulation cycles as rigid foam producers race to certify low-GWP blowing agents ahead of enforcement deadlines. The EU F-Gas Regulation and parallel US EPA SNAP restrictions have triggered simultaneous R&D sprints across multiple supply chains.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Tightening HFC quotas force building envelope retrofits, expanding rigid foam specification in commercial and residential construction across Germany, France, and Poland.
- Automotive Lightweighting Programs:Structural PU composites displace metal stampings in electric vehicle battery housings and seat structures, with OEMs specifying high-performance isocyanate systems.
- China Infrastructure Investment:State-backed cold chain expansion and energy-efficient building codes concentrate flexible and rigid foam offtake in tier-one and tier-two cities.
Market Restraints
- MDI Supply Concentration:Asian producers control over two-thirds of global methylene diphenyl diisocyanate capacity, exposing formulators in Europe and North America to freight cost volatility and allocation risk.
- Propylene Oxide Price Volatility:Polyol feedstock costs swing with refinery utilization and propylene derivative demand, compressing margin predictability for flexible foam manufacturers.
- REACH Substance Authorization:ECHA scrutiny of aromatic amines and residual isocyanates extends registration timelines and restricts certain catalyst chemistries in EU-sold formulations.
Strategic Opportunities
- India Cold Chain Buildout:FSSAI mandates for temperature-controlled food distribution create specification windows for rigid PU insulation in refrigerated transport and warehouse construction.
- Bio-Based Polyol Certification:USDA BioPreferred and EU Ecolabel procurement preferences open public-sector tender access for formulations with 20-30% renewable content.
- Spray Foam Contractor Networks:Technical service density and applicator certification programs create captive distribution channels in residential retrofit markets.
Industry Challenges
- Isocyanate Handling Certification:OSHA respiratory protection and process safety requirements constrain workforce scalability, forcing capital allocation toward enclosed metering systems.
- Multi-Jurisdictional Formulation Registration:Divergent substance restrictions between EPA SNAP, REACH, and China's GB standards fragment product portfolios and extend commercialization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethanes (PU) Market |
| Market Size in 2026 | $89.7 Billion |
| Market Size in 2035 | $162.16 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives End Use Industry: Construction, Automotive, Furniture, Footwear Technology: Reaction Injection Molding, Spray Polyurethane Foam, Thermoplastic, Casting Application: Insulation, Upholstery, Sealants, Automotive Interiors |
| Companies Covered | BASF SE, Covestro AG, Dow Inc., Huntsman Corporation, Wanhua Chemical Group Co., Ltd., Mitsui Chemicals, Inc., Lubrizol Corporation, Recticel S.A., Tosoh Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethanes (PU) Market Evolving Landscape
Hydrofluoroolefin blowing agent adoption is fragmenting competitive positions as early movers capture specification lock-in. Formulation chemistry, regulatory certification velocity, and contractor training infrastructure now determine market access more than commodity scale.
Next-generation HFO-1233zd and HFO-1336mzz-Z blowing agents deliver sub-10 GWP thermal performance while maintaining lambda values comparable to legacy HFC-245fa systems. Spray foam contractors in the US Northeast and Pacific Northwest are specifying these formulations for passive house and net-zero certifications. Closed-cell rigid foam producers without HFO-capable blend equipment are rendering obsolete their own product lines as building codes tighten.
EPA SNAP Rule 23 and subsequent rulemakings prohibit HFC-245fa and HFC-365mfc in most insulation applications, with full phase-out timelines accelerating in California through CARB amendments. Formulators must recertify entire product families under ASTM C1029 and ICC-ES evaluation reports, compressing R&D budgets toward compliance rather than performance differentiation. The commercial roofing segment faces the steepest transition costs due to bonded membrane compatibility testing requirements.
Building owners now specify whole-wall U-value guarantees rather than material R-value alone, shifting risk to insulation contractors and foam suppliers. Performance contracting and installation-warranty bundling displace traditional material-plus-labor procurement in multi-family and healthcare construction. This shift concentrates specification authority with national installers in Germany, the Netherlands, and the US Pacific Coast who carry EPD-verified environmental claims and long-term thermal performance insurance.
Polyurethanes (PU) Market Segmentation
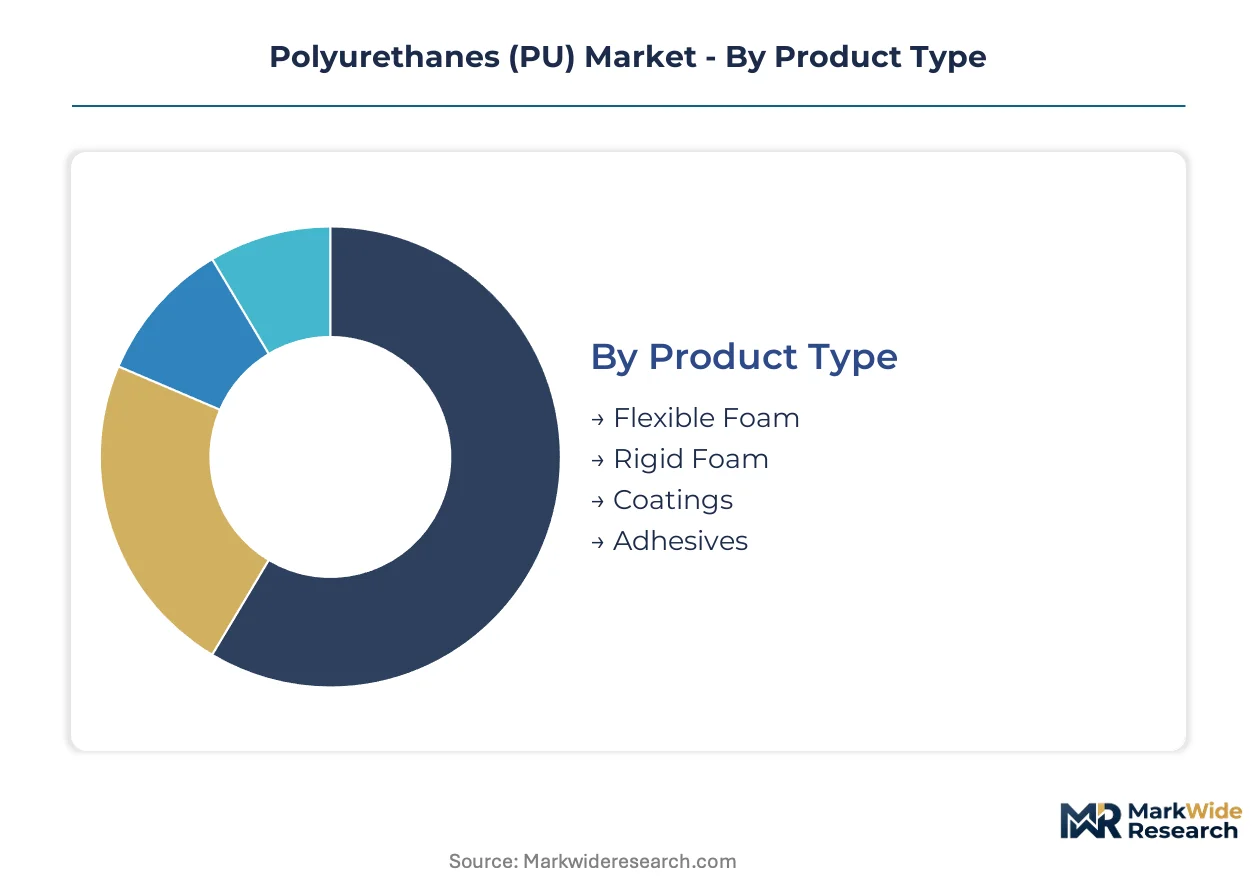
Polyurethane market segmentation reveals divergent margin profiles across product chemistry and application intensity. Technical service requirements and formulation complexity vary dramatically between commodity flexible foam and specialized rigid foam systems.
Product Type:
After-sales service intensity distinguishes polyurethane product categories, with rigid foam demanding continuous contractor support and flexible foam operating on volume replenishment models.
- Flexible Foam:Open-cell polyether and polyester formulations dominate furniture cushioning and bedding applications. Demand concentrates in China and Vietnam where vertically integrated furniture manufacturers source directly from polyol blenders. Margin compression from propylene oxide volatility forces producers toward just-in-time delivery contracts.
- Rigid Foam:Closed-cell systems incorporating HFO blowing agents command specification authority in passive house construction across Germany, Austria, and the US Pacific Northwest. Regulatory deadlines under EU F-Gas Regulation and EPA SNAP Rule 23 accelerate formulation turnover and recertification costs.
- Coatings:Two-component aliphatic and aromatic systems serve industrial maintenance and automotive refinish markets requiring applicator training programs.
- Adhesives:Reactive hot-melt and moisture-cure formulations bond composite panels in transportation and construction assembly.
Flexible foam holds the largest share; momentum sits with rigid foam as building envelope retrofits accelerate.
End Use Industry:
Cost tier differentiation separates specification-driven construction applications from price-sensitive furniture procurement.
- Construction:Thermal insulation mandates under REACH and EU F-Gas Regulation drive rigid foam specification for wall assemblies and commercial roofing. German and Polish building codes now require whole-wall U-value guarantees that shift liability to insulation contractors.
- Automotive:Structural composites displace metal in electric vehicle battery housings and seat structures. OEMs specify high-performance isocyanate systems from Covestro and BASF with crash-performance certification.
- Furniture:Mattress and upholstery manufacturers in China and Vietnam source commodity polyol blends on quarterly price negotiations.
- Footwear:Thermoplastic polyurethane midsoles and outsoles serve athletic and safety boot segments with shorter design cycles.
Construction holds the largest share; automotive applications are climbing the fastest on lightweighting programs.
Technology:
Volume concentration favors spray polyurethane foam in residential retrofit markets where contractor certification creates captive distribution.
- Reaction Injection Molding:High-pressure mixing of isocyanate and polyol enables complex automotive fascia and structural parts with Class A surfaces. Tooling costs limit adoption to programs above 50,000 units annually.
- Spray Polyurethane Foam:On-site application of rigid foam insulation requires OSHA-compliant respiratory protection and enclosed metering equipment. US Northeast and Pacific Northwest contractors build specification lock-in through applicator training density.
- Thermoplastic:Injection-moldable TPU pellets serve footwear and industrial hose applications with recyclable processing advantages.
- Casting:Open-pour and machine-cast elastomers produce industrial wheels, rollers, and mining screens with abrasion resistance requirements.
Spray polyurethane foam holds the largest share; reaction injection molding is gaining share fastest on automotive composite substitution.
Application:
Margin structure varies by performance guarantee requirements, with insulation contractors now carrying long-term thermal performance risk.
- Insulation:Rigid foam boards and spray-applied systems deliver lambda values below 0.022 W/mK using HFO-1233zd blowing agents. German and Dutch installers bundle EPD-verified environmental claims with installation warranties.
- Upholstery:Flexible foam cushioning serves furniture and automotive seating with density specifications from 18 to 55 kg/m³.
- Sealants:One-component moisture-cure and two-component systems fill construction joints and expansion gaps.
- Automotive Interiors:Dashboard skins, door panels, and headliners combine soft-touch aesthetics with VOC compliance under EPA and CARB limits.
Insulation holds the largest share; automotive interiors are expanding most quickly on cabin refinement priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors and automotive OEMs concentrate procurement authority in distinct national clusters. Regulatory divergence across jurisdictions fragments formulation portfolios and extends commercialization timelines for multinational suppliers.
China
Wanhua Chemical anchors domestic isocyanate supply while state-backed cold chain expansion drives rigid foam specification in Shanghai and Guangzhou. MIIT enforces GB standards for building energy efficiency that accelerate HFO blowing agent adoption. The Yangtze River Delta cluster concentrates flexible foam production for furniture export manufacturers.
Germany
Passive house construction standards in Bavaria and North Rhine-Westphalia command premium rigid foam systems with whole-wall U-value guarantees. The EU F-Gas Regulation Phase-Down forces HFC quota compliance across commercial envelope retrofits. BASF SE leverages backward integration into renewable feedstocks to anchor European bio-based polyol positions.
United States
Spray foam contractors in the Pacific Northwest and Northeast build specification lock-in through applicator certification density. EPA SNAP Rule 23 prohibits HFC-245fa in most insulation applications, compressing recertification timelines. Dow Inc. dominates residential retrofit distribution through technical service infrastructure.
India
FSSAI mandates for temperature-controlled food distribution create specification windows in Maharashtra and Gujarat. The national building code tightens thermal performance standards for commercial construction in Delhi-NCR. Cold chain warehouse construction concentrates rigid foam demand in Mumbai-Pune and Ahmedabad industrial corridors.
Japan
Automotive lightweighting programs in Toyota City and Yokohama specify high-performance isocyanate systems for electric vehicle battery housings. METI promotes carbon-neutral material procurement preferences in public infrastructure tenders. Mitsui Chemicals anchors domestic specialty polyol supply for industrial elastomer applications.
Polyurethanes (PU) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation complexity tiers. The market structure concentrates around three strategic archetypes: integrated chemical conglomerates with captive feedstock positions, specialty isocyanate producers serving automotive specification chains, and regional foam fabricators with contractor network density. Capacity expansion and regulatory certification velocity constitute the dominant competitive moves as HFO transition deadlines compress R&D allocation.
Among integrated chemical conglomerates, BASF SE and Covestro AG exemplify the feedstock-integrated archetype with European supply positions. Dow Inc. occupies the North American channel-control position through spray foam distribution infrastructure. Wanhua Chemical represents the scale-driven Asian producer archetype with concentrated isocyanate capacity.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Dow Inc. |
| Huntsman Corporation |
| Wanhua Chemical Group Co., Ltd. |
| Mitsui Chemicals, Inc. |
| Lubrizol Corporation |
| Recticel S.A. |
| Tosoh Corporation |
| Others |
Value Network & Pricing Analysis
Asian isocyanate concentration, particularly Chinese MDI capacity dominance, anchors margin capture upstream while forcing European and North American formulators into long-term offtake contracts to secure allocation certainty. This feedstock asymmetry compresses downstream pricing power and redirects formulation investment toward blowing agent transitions that preserve specification access.
Pricing Analysis
Cost-plus contracts with propylene oxide indexation dominate flexible foam procurement, tying margin predictability to refinery utilization cycles. Price differentiation rests on HFO blowing agent certification status and whole-wall U-value guarantee bundling. Cost compression in commodity flexible foam intensifies because Vietnamese furniture manufacturers negotiate quarterly volume rebates. Mattress producers in China exhibit the highest price sensitivity, while German passive house contractors accept premium rigid foam systems with installation-warranty bundling.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for isocyanate importers. Manufacturing concentrates in China, Germany, and the United States for distinct chemistries. Feedstock dependencies center on propylene oxide, aniline, and formaldehyde derivatives. Single-source vulnerability persists in MDI supply where Asian producers control two-thirds of global capacity. Distribution runs through certified spray foam contractor networks in residential retrofit markets and direct polyol blending relationships with furniture OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyurethane formulation chemistry is approaching a platform-economics inflection where HFO blowing agent certification creates interoperability lock-in across building code jurisdictions. Contractors specifying certified systems gain specification authority that transcends commodity pricing.
For Market Incumbents: Entrench specification authority by accelerating HFO-1233zd blend capacity ahead of EPA SNAP enforcement deadlines. Backward integration into renewable feedstock supply secures EU Ecolabel procurement access against bio-based polyol entrants. Channel control through applicator certification density remains the priority defensive lever against regional foam fabricators.
For New Entrants and Emerging Players: Build out cold chain insulation specification in India where FSSAI mandates create tender windows without entrenched contractor networks. The most penetrable segment is refrigerated transport and warehouse construction in Maharashtra and Gujarat. A go-to-market angle through EPD-verified environmental claims with installation-warranty bundling bypasses commodity pricing pressure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional spray foam distributors lacking HFO-capable blend equipment. Long-term viability over the projection horizon favors targets with contractor certification infrastructure and cross-jurisdictional formulation registration capabilities. The signal to watch is CARB amendment acceleration that compresses recertification timelines and strands non-compliant product portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| HFO Blowing Agent Capacity Expansion | Captures specification lock-in ahead of EPA SNAP Rule 23 enforcement deadlines. |
| Backward Integration into Renewable Feedstocks | Secures EU Ecolabel access and USDA BioPreferred procurement preference. |
| Contractor Certification Program Buildout | Creates captive distribution channels in residential retrofit markets. |
| Cross-Jurisdictional Formulation Registration | Prevents stranded assets from divergence between EPA SNAP, REACH, and GB standards. |
| Whole-Wall U-Value Guarantee Bundling | Shifts liability to insulation contractors and commands premium pricing. |
Research Methodology
A standing panel of rigid foam plant managers, spray foam contractor network heads, automotive OEM procurement leads, and polyol blend R&D directors provided ongoing calibration against operating reality. This primary fieldwork combined with customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and building code enforcement databases. Bottom-up volume builds across product types and end-use industries triangulated against top-down macroeconomic demand indicators.
Scenario-bracketing anchored the analytical framework, with low, base, and high cases reflecting divergent HFO adoption velocities and building code enforcement intensities across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry, blowing agent technology, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating propylene oxide price volatility and isocyanate capacity expansion schedules.
Practitioners should monitor EPA SNAP rulemaking acceleration, EU F-Gas quota tightening schedules, and Chinese GB standard revision timelines for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market