
 Oman Dairy Products and Juice Market | 2026-2036
Oman Dairy Products and Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Dairy Products and Juice Market Intelligence
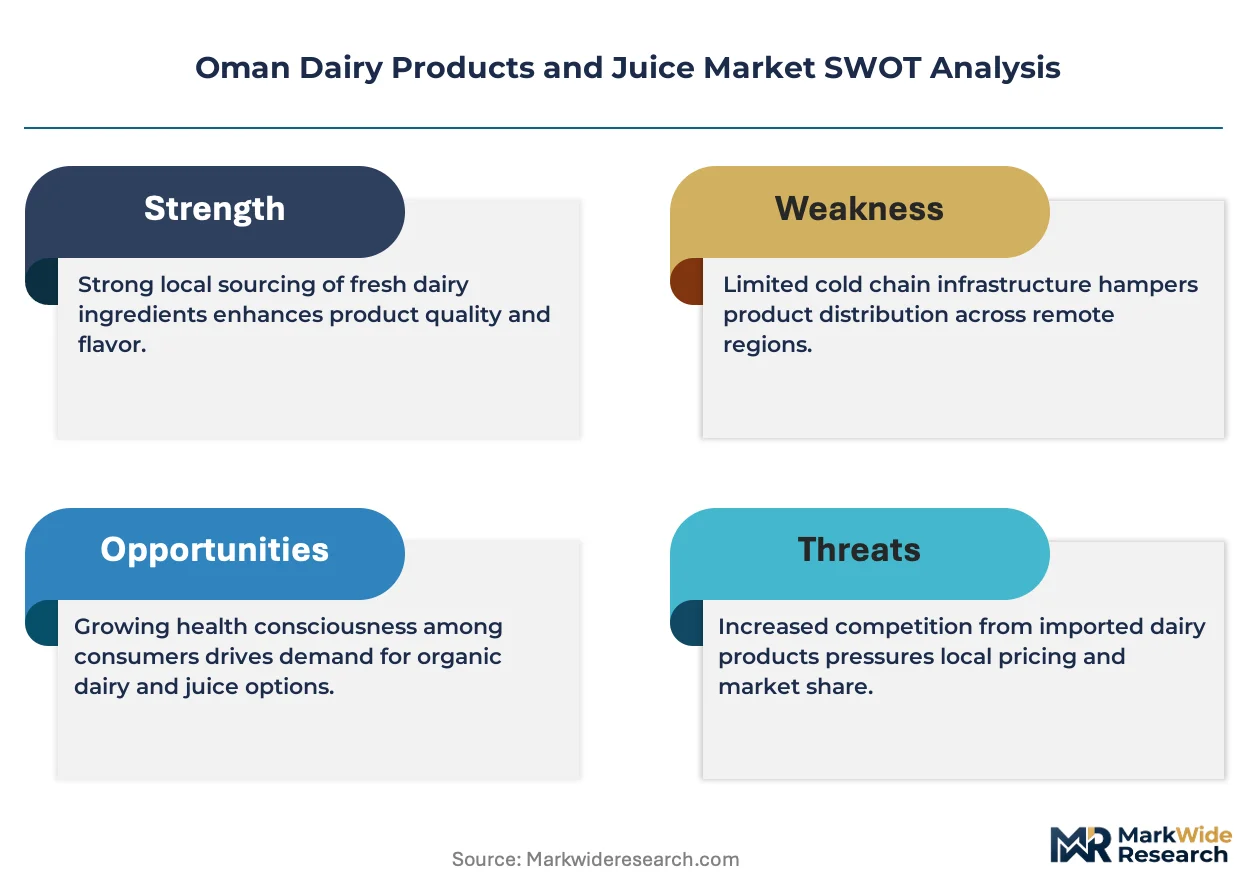
Modern retail distribution in Oman is fragmenting as hypermarket chains lose exclusive control over chilled dairy and juice categories. Mazoon Dairy leverages its integrated farm-to-plant operations near Al Buraimi to sustain consistent fresh milk supply across northern governates. Gulf Dairy Company competes through specialized labneh and strained yogurt formats that anchor premium shelf positioning in Carrefour and Lulu outlets. Oman Juice Industries controls the food service channel, supplying hotels and airline catering with bulk-format concentrates.
Oman dairy products and juice encompass pasteurized fluid milk, fermented cultured products, processed cheese, and fruit-based beverages manufactured under cold-chain protocols with standardized fat content, pH levels, and shelf-life parameters designed for consumer nutrition and food service procurement. Milk and yogurt categories dominate volume throughput due to daily consumption rituals embedded in Omani household purchasing, while juice segments concentrate margin pools in premium not-from-concentrate offerings targeting health-positioned buyers. Tetra Pak packaging extends ambient distribution reach into rural interior regions where refrigerated logistics remain sparse, though pouch formats gain traction among price-sensitive households in South Batinah and Dhofar.
Oman's Ministry of Regional Municipalities and Water Resources enforces hygienic standards for dairy processing facilities, while the GCC Standardization Organization (GSO) technical regulations mandate nutritional labeling and additive limits across cross-border trade. The Food Safety and Quality Centre within the Ministry of Agriculture and Fisheries conducts routine sampling that shapes product reformulation timelines and import substitution incentives for local manufacturers. Stakeholders must monitor evolving shelf-life extension technologies and cold-storage infrastructure investments that will determine which product formats penetrate underserved governorates.
Market Dynamics
The Omani Ministry of Commerce, Industry and Investment Promotion's tightened labeling requirements for processed foods are compressing formulation cycles and forcing manufacturers toward transparent ingredient declarations that expose legacy additive dependencies.
Growth Catalysts
- Domestic Tourism Capacity Expansion:Hotels and hospitality venues across Muscat Governorate are scaling chilled dairy and juice procurement volumes as visitor accommodation capacity rises.
- Port Sohar Export Logistics Proximity:Dairy farming clusters and juice processing plants concentrated in the Batinah coastal corridor benefit from streamlined cold-chain access to international shipping infrastructure.
- Extended Shelf-Life Packaging:Tetra Pak ambient distribution technology is penetrating rural interior governorates where refrigerated logistics infrastructure remains sparse.
Market Restraints
- Raw Milk Input Volatility:Local dairy farming output fluctuates with seasonal feed costs and water scarcity pressures concentrated in Al Buraimi and Batinah production zones.
- Refrigerated Distribution Gaps:Cold-chain infrastructure deficits in South Batinah and Dhofar governorates limit fresh product penetration and compress margin realization on chilled formats.
- Import Substitution Incentives:The Food Safety and Quality Centre within the Ministry of Agriculture and Fisheries shapes reformulation timelines that disadvantage foreign suppliers lacking local manufacturing presence.
Strategic Opportunities
- Underpenetrated Interior Governorates:Dhofar and Al Wusta regions present white-space demand for ambient-stable dairy and juice formats that bypass refrigerated logistics constraints.
- Food Service Channel Specialization:Bulk-format concentrate supply to airline catering and hotel chains offers margin expansion beyond retail price compression.
- Clean Label Reformulation:The Ministry's labeling mandate creates first-mover advantage for manufacturers achieving additive-free certification ahead of compliance deadlines.
Industry Challenges
- Refrigerated Logistics Capex Intensity:Cold-storage infrastructure investments required for fresh product distribution into underserved governorates demand capital deployment that strains mid-scale processors.
- Multi-Agency Compliance Coordination:Alignment between the Ministry of Regional Municipalities and Water Resources facility standards and GCC Standardization Organization cross-border regulations creates certification timeline friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Dairy Products and Juice Market |
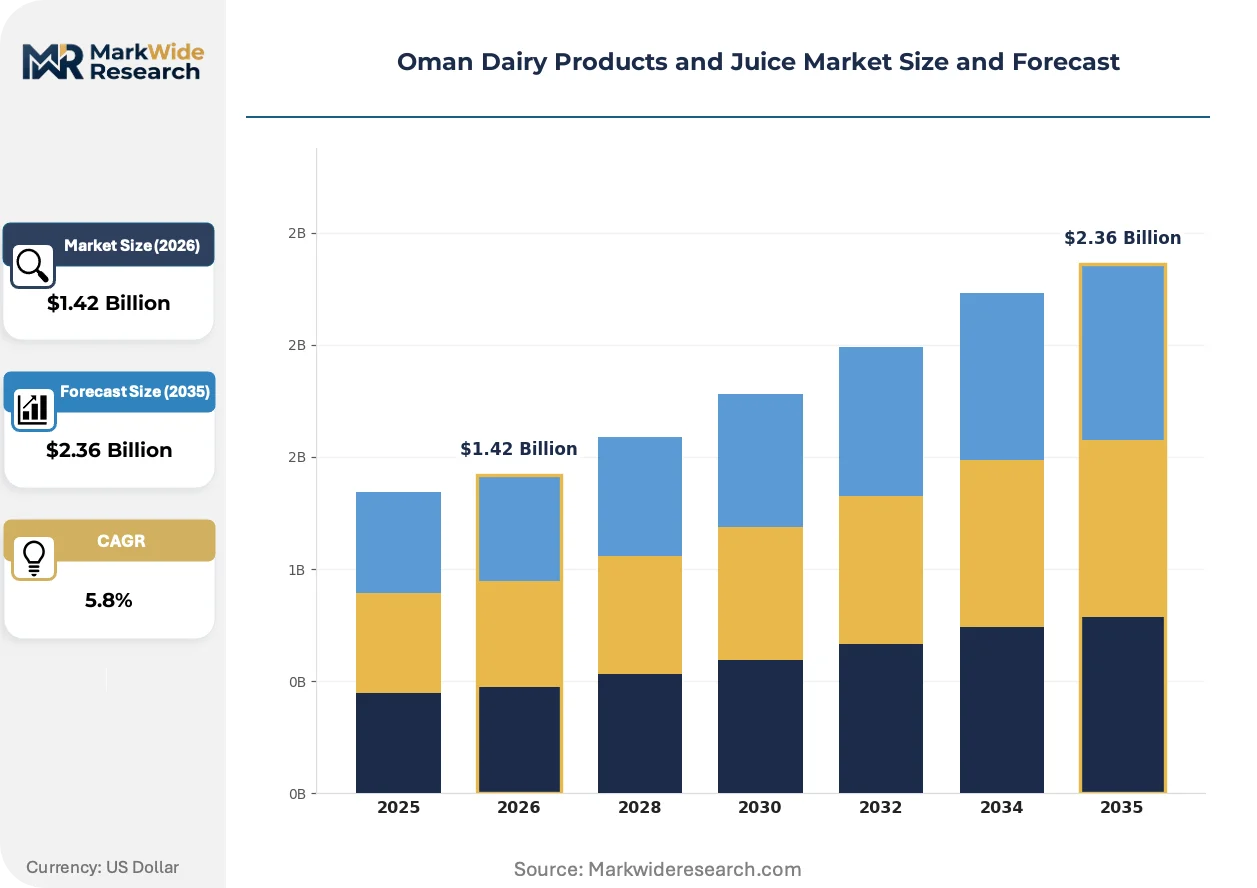
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Juice Packaging Type: Bottle, Carton, Tetra Pak, Pouch Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Customer Type: Households, Restaurants, Cafes, Schools |
| Companies Covered | Al Bashayer Meat Company, Oman Air (Dairy Partnership), Mazoon Dairy, Gulf Dairy Company, Al Reef Dairy, A'Safwah Milk and Dairy, Hatsun Agro, Oman Juice Industries, Al Jazeera Cattle Farm, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Dairy Products and Juice Market Strategic Shifts & Innovations
Three intersecting forces are restructuring competitive positioning in Oman's dairy and juice segments: shelf-life extension technologies expanding addressable geography, regulatory transparency mandates compressing formulation freedom, and channel fragmentation eroding hypermarket gatekeeper status.
Aseptic filling and ESL (extended shelf-life) processing technology is rendering obsolete the traditional trade-off between ambient distribution reach and fresh taste positioning. Dairy processors serving rural Al Dakhiliyah and Al Sharqiyah governorates are adopting these systems to bypass refrigerated logistics bottlenecks. The structural consequence is market share compression for legacy pasteurized-only operators locked into cold-chain dependency.
The GCC Standardization Organization's technical regulations on nutritional labeling and additive limits are forcing cross-border trade compliance investments that reshape product portfolios. Manufacturers reformulating for Omani market access must simultaneously satisfy GSO mandates and domestic Ministry of Agriculture and Fisheries sampling protocols. Fermented cultured products and premium not-from-concentrate juices face the steepest adaptation curves due to complex ingredient declarations.
Modern retail distribution fragmentation is eroding hypermarket exclusive control over chilled dairy and juice categories. Independent convenience formats and direct food service supply relationships are capturing volume from Carrefour and Lulu traditional dominance. This channel disintermediation is most visible in Muscat Governorate where hospitality procurement teams increasingly source through specialized distributors rather than retail intermediaries.
Oman Dairy Products and Juice Market Segmentation
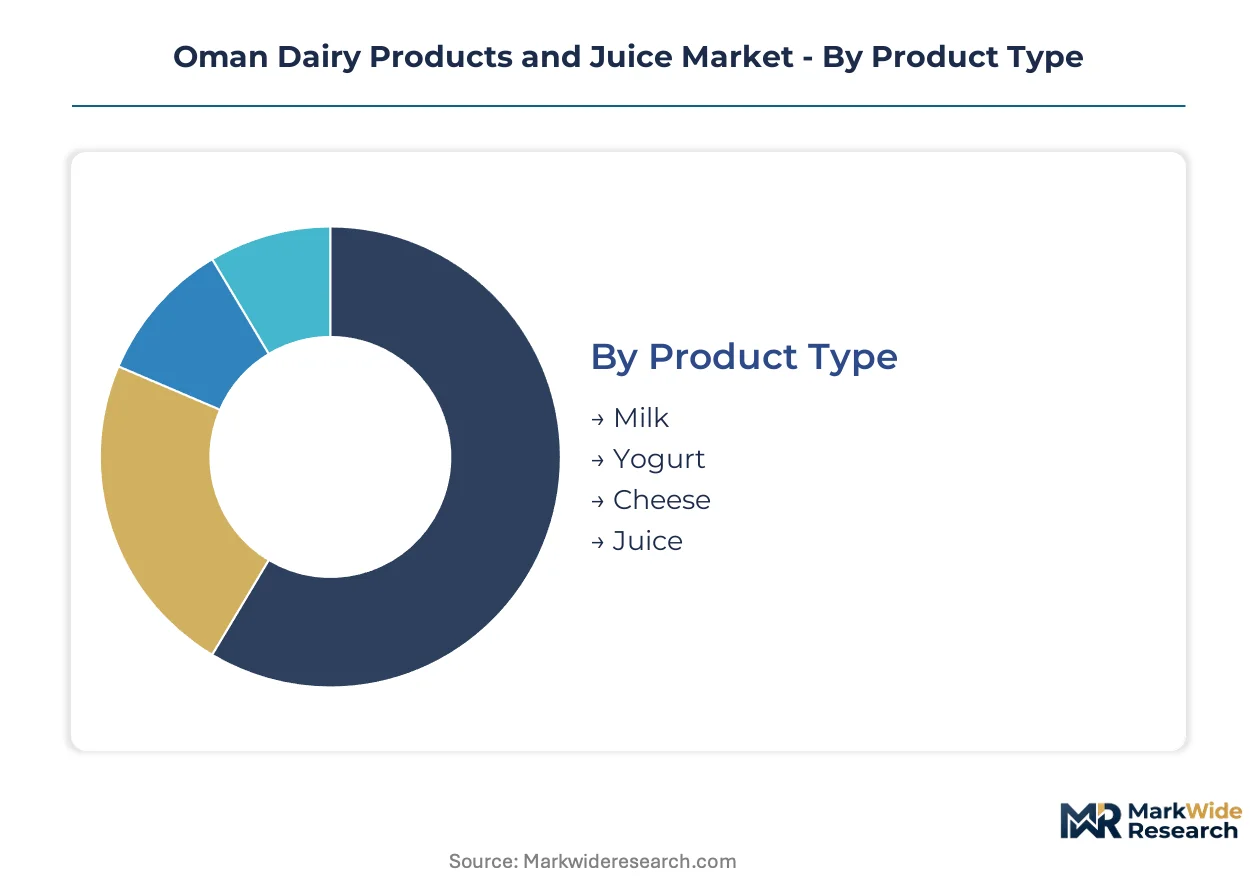
Segmentation in Oman's dairy and juice market reveals how product format, packaging technology, and channel access determine which consumer clusters manufacturers can profitably serve. The intersection of cold-chain infrastructure gaps and regulatory transparency mandates creates divergent growth trajectories across segment boundaries.
Product Type:
Mature categories anchor daily consumption rituals while emerging formats capture health-positioned premiumization.
- Milk:Pasteurized fluid milk with standardized fat content (full-fat, low-fat, skim) dominates household procurement frequency. Daily consumption rituals in Muscat and Batinah households sustain volume throughput, though raw milk input volatility from Al Buraimi farming clusters compresses margin stability.
- Yogurt:Fermented cultured products span drinking yogurt, set yogurt, and labneh formats with defined pH and live culture specifications. Strained yogurt and labneh variants anchor premium shelf positioning in Carrefour and Lulu outlets, with specialized formats gaining traction among health-conscious buyers seeking protein-rich alternatives.
- Cheese:Processed cheese and fresh white cheese categories serve sandwich preparation and traditional Omani cuisine applications.
- Juice:Fruit-based beverages span from-concentrate, not-from-concentrate, and fresh-chilled formats with mandated shelf-life parameters.
Milk retains volume leadership; juice holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates ambient-stable mass market penetration from cold-chain dependent premium positioning.
- Tetra Pak:Aseptic carton systems with aluminum barrier layers enable ambient distribution reach into rural interior regions where refrigerated logistics remain sparse. Extended shelf-life parameters bypass cold-storage bottlenecks in Al Dakhiliyah and Al Sharqiyah governorates.
- Bottle:PET and HDPE bottle formats serve fresh chilled milk and juice segments requiring transparent ingredient visibility. Hotels and hospitality venues across Muscat Governorate specify bottle formats for front-of-house presentation, with procurement volumes scaling alongside tourism capacity expansion.
- Carton:Gable-top cartons occupy mid-tier positioning for fresh pasteurized products with shorter shelf-life windows.
- Pouch:Flexible film pouches gain traction among price-sensitive households in South Batinah and Dhofar through lower unit economics and reduced material costs.
Tetra Pak captures the widest geographic penetration; pouch formats are expanding most quickly in price-sensitive segments.
Distribution Channel:
Customer type concentration determines whether procurement flows through retail intermediaries or direct food service relationships.
- Supermarkets:Hypermarket chains including Carrefour and Lulu maintain category captain status for chilled dairy and juice, though exclusive control is fragmenting. Carrefour and Lulu outlets in Muscat Governorate still process the highest transaction volumes for family-sized formats.
- Food Service:Direct supply relationships with hotels, airline catering, and institutional kitchens bypass retail markups. Oman Juice Industries controls this channel through bulk-format concentrate supply, with margin expansion potential exceeding retail price compression pressures.
- Convenience Stores:Independent neighborhood formats capture impulse and top-up purchasing for single-serve products.
- Online Retail:E-commerce platforms aggregate subscription-based milk delivery and premium juice assortment for time-constrained urban households.
Supermarkets retain transaction volume leadership; food service channels are gaining share fastest through direct procurement relationships.
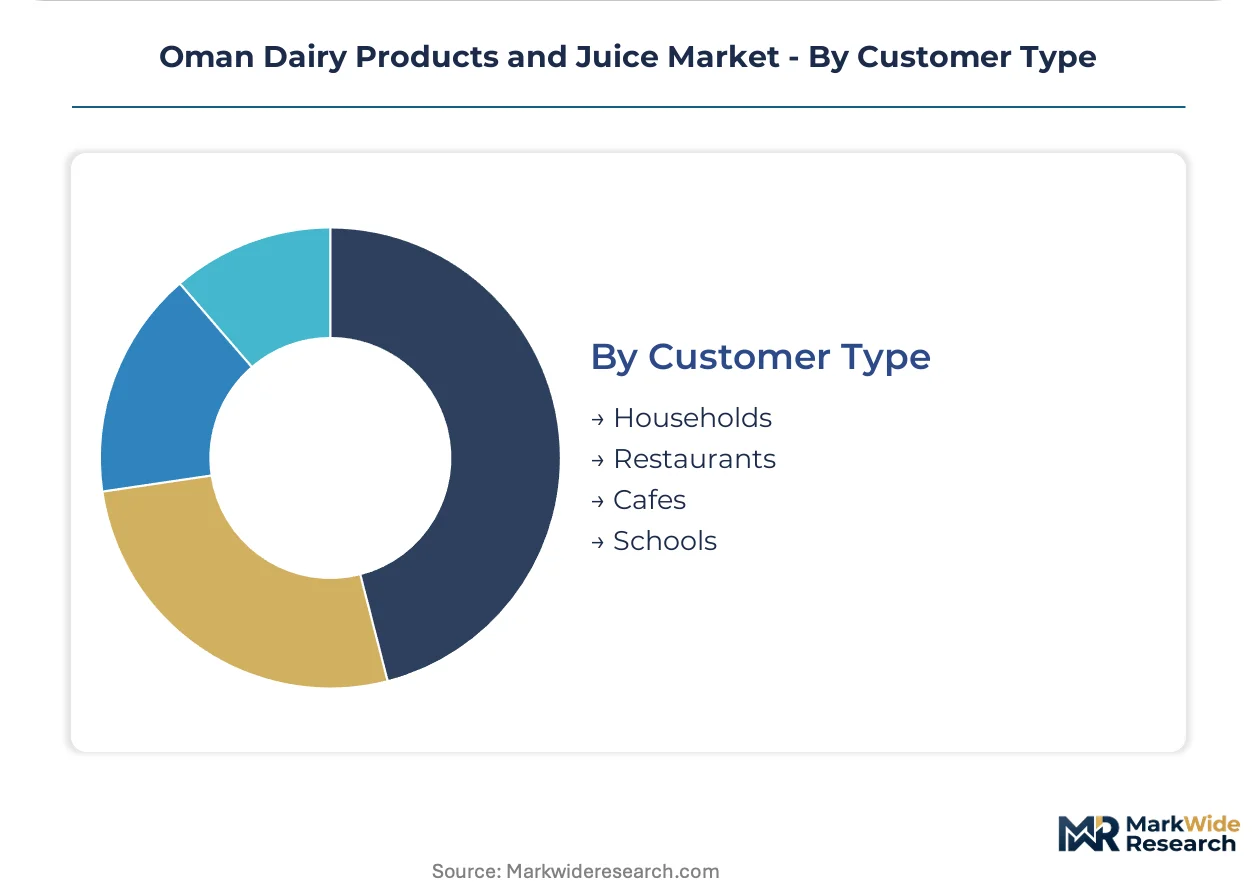
Customer Type:
Application context shapes product specification requirements from institutional nutrition standards to hospitality presentation standards.
- Households:Family units drive recurring purchase frequency for daily consumption staples, with purchasing decisions influenced by children's nutritional preferences and elder dietary requirements. Batinah coastal corridor households benefit from proximity to Mazoon Dairy's integrated farm-to-plant operations.
- Restaurants:Food service operators specify bulk formats and consistent supply reliability for menu integration. Hotel procurement teams in Muscat Governorate increasingly source through specialized distributors rather than retail intermediaries.
- Cafes:Coffee shop chains demand barista-grade milk with specific foaming properties and fat content parameters.
- Schools:Institutional feeding programs mandate fortified milk and controlled-sugar juice formats meeting Ministry of Agriculture and Fisheries sampling protocols.
Households retain volume leadership; restaurants hold the steepest expansion curve as tourism capacity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port Sohar anchors the Batinah coastal corridor's export logistics, underwriting cold-chain access to international shipping lanes while dairy farming clusters and juice processing plants concentrate nearby to exploit this infrastructure advantage.
Muscat Governorate
Hotels and hospitality venues across Muscat are scaling chilled dairy and juice procurement volumes as visitor accommodation capacity rises. The Ministry of Commerce, Industry and Investment Promotion enforces tightened labeling requirements for processed foods distributed through hospitality channels. Urban retail clusters in Muscat city center fragment hypermarket control as independent convenience formats capture impulse purchasing.
Batinah North and South
Dairy farming clusters concentrated along the coastal plain supply raw milk to integrated processing plants benefiting from proximity to Port Sohar export infrastructure. The Food Safety and Quality Centre within the Ministry of Agriculture and Fisheries conducts routine sampling that shapes local reformulation timelines. Mazoon Dairy's farm-to-plant operations near Al Buraimi extend distribution reach across northern governorates through captive supply chain control.
Dhofar Governorate
Pouch format dairy and juice products gain traction among price-sensitive households where refrigerated logistics infrastructure remains sparse. Tetra Pak ambient distribution technology penetrates this underserved region, bypassing cold-storage bottlenecks that constrain fresh product margins. Salalah's emerging retail corridors present white-space demand for shelf-stable formats that circumvent refrigerated distribution gaps.
Al Dakhiliyah Governorate
Rural interior households drive demand for extended shelf-life dairy products distributed through ambient-stable packaging formats. Aseptic filling and ESL processing technology adoption accelerates as processors seek to bypass refrigerated logistics constraints. Nizwa and surrounding population centers represent penetration targets for Tetra Pak-enabled distribution networks.
Al Sharqiyah Governorate
E-commerce platforms aggregate subscription-based milk delivery for time-constrained urban households in Sur and coastal towns. The GCC Standardization Organization's technical regulations on nutritional labeling apply to cross-border trade flows through this eastern corridor. Local dairy processors adopting shelf-life extension systems compete against imports lacking localized manufacturing presence.
Oman Dairy Products and Juice Market Key Industry Players
On the supply side, the industry is consolidating around integrated farm-to-plant operators and specialized format specialists rather than fragmented trading intermediaries. Three strategic archetypes dominate: vertically integrated dairy producers with captive raw milk supply, juice processors controlling food service channel relationships, and regional specialists in fermented cultured products. Competitive moves concentrate on backward integration into farming assets and direct procurement relationships with hospitality buyers that bypass retail markups.
Among Omani integrated producers, Mazoon Dairy, Gulf Dairy Company, and Oman Juice Industries exemplify divergent positioning archetypes. Mazoon Dairy represents the vertically integrated model with farm-to-plant operations anchoring northern governorate supply security. Gulf Dairy Company occupies the premium fermented products tier through specialized labneh and strained yogurt formats. Oman Juice Industries sits within the food service channel specialization archetype, supplying bulk-format concentrates to hospitality and airline catering procurement teams.
| Leading Market Players |
|---|
| Al Bashayer Meat Company |
| Oman Air (Dairy Partnership) |
| Mazoon Dairy |
| Gulf Dairy Company |
| Al Reef Dairy |
| A'Safwah Milk and Dairy |
| Hatsun Agro |
| Oman Juice Industries |
| Al Jazeera Cattle Farm |
| Others |
Cost & Logistics Intelligence
Raw milk input volatility from Al Buraimi and Batinah farming clusters compresses margin stability while simultaneously forcing three-tier pricing stratification across premium, standard, and economy levels. This commodity exposure determines both the spread between Tetra Pak ambient formats and fresh chilled bottle products and the geographic reach of cold-chain dependent distribution networks.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships between dairy processors and Muscat Governorate hospitality buyers. Three-tier pricing stratifies across premium not-from-concentrate juices, standard pasteurized milk, and economy pouch formats for price-sensitive South Batinah households. Pricing pressure stems from feed cost fluctuations that compress processor margins without commensurate retail pass-through. Food service channels exhibit lowest price sensitivity due to menu cost absorption; rural interior households face highest sensitivity due to disposable income constraints.
Supply Chain Analysis
Supplier-financing facilities extended by Mazoon Dairy and Gulf Dairy Company lock in exclusive procurement relationships with independent convenience retailers across northern governorates. Geographic supply concentrates in Oman with raw milk drawn from Al Buraimi farming clusters and packaging materials sourced from UAE and Saudi manufacturing hubs. Single-source vulnerability attaches to Port Sohar cold-chain export infrastructure. Distribution runs through hypermarket chains for retail volume and direct specialized distributors for hospitality procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's dairy and juice market sits within a cyclical recovery phase driven by tourism capacity expansion across Muscat Governorate accommodation and food service venues.
For Market Incumbents: Entrench backward integration into captive raw milk supply through Al Buraimi farming asset expansion to defend against import substitution incentives disadvantaging foreign suppliers. Deepen channel control by establishing direct procurement relationships with hotel chains that bypass retail markups and hypermarket gatekeepers. For New Entrants and Emerging Players: Establish a beachhead in ambient-stable Tetra Pak formats for Dhofar and Al Wusta interior governorates where refrigerated logistics gaps constrain incumbent penetration. Target price-sensitive household segments through pouch format distribution partnerships with independent convenience retailers in South Batinah. For Investors and Strategic Acquirers: The Ministry of Commerce, Industry and Investment Promotion's labeling mandate reshapes the acquisition landscape toward additive-free certified manufacturers ahead of compliance deadlines. Long-term viability favors vertically integrated operators with captive farm supply and Port Sohar export logistics access. Watch for shelf-life extension technology adoption rates as the signal indicating which processors can penetrate underserved interior governorates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farming Assets | Captive raw milk supply from Al Buraimi clusters insulates processors from seasonal feed cost volatility. |
| Clean Label Reformulation Investment | Additive-free certification ahead of Ministry compliance deadlines secures first-mover retail shelf positioning. |
| Shelf-Life Extension Technology Adoption | ESL processing and aseptic filling unlock ambient distribution into Al Dakhiliyah and Dhofar cold-chain gaps. |
| Food Service Channel Direct Supply | Bulk-format concentrate relationships with airline catering bypass hypermarket margin compression. |
| Port Sohar Export Logistics Expansion | Streamlined cold-chain access to international shipping lanes anchors Batinah coastal corridor processing concentration. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy processing plant managers, hospitality procurement directors at Muscat hotels, retail category buyers at Carrefour and Lulu, and Ministry of Agriculture and Fisheries sampling protocol administrators. Secondary validation drew from GCC Standardization Organization technical regulations, Omani Ministry of Commerce labeling directives, customs trade data for dairy and juice imports, and food service distribution channel records. Bottom-up volume estimates from processor capacity utilization were triangulated against top-down expenditure flows from hospitality and retail audit data.
Calibration against historical production volumes and tourism capacity expansion trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, packaging technology, distribution channel, and customer application context. CAGRs were derived from elasticity-adjusted demand projections incorporating raw milk supply constraints and cold-chain infrastructure investment schedules. Forecast inputs included Ministry of Regional Municipalities facility compliance timelines and Port Sohar throughput capacity expansion.
Stress conditions across feed cost volatility, water scarcity pressures, and refrigerated logistics investment delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and tourism recovery trajectory. Macroeconomic contraction, accelerated import substitution policy shifts, or breakthrough ambient stabilization technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cream Powder Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Filled Cheese Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
India Dairy Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Low Fat Butter Market
Dairy Products
China Lactose-Free Dairy Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
White Cheese Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Goat Milk Products Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
North America Casein Market