
 Low Fat Butter Market | 2026-2036
Low Fat Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Butter Market Foresight
Dairy technologist talent scarcity is bifurcating the competitive landscape into R&D-heavy multinationals and regional processors. Land O'Lakes, Inc. leverages its captive dairy cooperative structure to secure fluid milk supply for low-fat formulation. Arla Foods anchors European production through centralized emulsion-processing facilities in Denmark and Sweden. Upfield competes on plant-blend expertise, extending its spreadable portfolio into hybrid dairy-alternative territories.
Low fat butter denotes a water-in-oil emulsion containing reduced milk fat content, typically achieved through churning cream with added water, stabilizers, and emulsifiers to maintain spreadability and mouthfeel. The product serves commercial and retail buyers seeking sensory parity with standard butter at lower caloric density. Spreadable formats dominate household penetration in temperate climates where cold-chain storage complicates block butter usability. Block formats sustain bakery and foodservice procurement where portion control and recipe standardization matter. Online retail channels represent the fastest-growing distribution vector as direct-to-consumer subscription models bypass traditional supermarket slotting fees.
EFSA nutrition and health claims regulation governs permissible fat-content descriptors across EU member states, while FDA standards of identity in the United States restrict butter labeling to minimum milk-fat thresholds that low-fat variants must circumvent through alternative product classifications. BIS food safety standards in India impose microbial limits that shape export eligibility for AMUL Dairy and other subcontinent suppliers. Stakeholders must monitor evolving front-of-pack labeling mandates in multiple jurisdictions, as these rules increasingly determine shelf placement and consumer trial rates.

Market Dynamics
Emulsifier technology convergence is restructuring competitive advantage around water-in-oil formulation mastery, concentrating margin capture among processors with captive dairy supply and in-house stabilization expertise.
Growth Catalysts
- EFSA Labeling Mandates:Tightened EU nutrition claims under EFSA Regulation 1924/2006 are compelling household purchasers toward verified low-fat spreads, tightening compositional standards that favor R&D-capable processors.
- Spreadable Format Preference:Temperate-climate retail channels in Germany, France, and the United Kingdom are expanding refrigerated spreadable purchases as cold-chain infrastructure penetrates secondary urban markets.
- Direct-to-Consumer Subscription Models:Online retail channels are bypassing traditional supermarket slotting fees, enabling challenger brands to capture household trial through recurring delivery logistics.
Market Restraints
- Fluid Milk Supply Concentration:Dairy cooperative structures in Northern Europe and the Upper Midwest United States control cream supply access, elevating input cost volatility for independent processors lacking backward integration.
- FDA Standards of Identity:United States labeling restrictions on minimum milk-fat thresholds force low-fat variants into alternative product classifications, fragmenting retail shelf positioning and consumer recognition.
- Plant-Blend Substitution:Hybrid dairy-alternative spreads from specialized emulsion processors are capturing price-sensitive household segments through cholesterol-free positioning and comparable spreadability.
Strategic Opportunities
- BIS Export Eligibility in India:Microbial compliance pathways under BIS food safety standards are opening procurement contracts for processors meeting subcontinent export thresholds, with AMUL Dairy anchoring quality benchmarks.
- Emulsifier-Convergence Innovation:Polyglycerol polyricinoleate and lecithin hybrid stabilization systems are enabling fat reduction below 40% without texture degradation, creating premium positioning for bakery and foodservice verticals.
- Front-of-Pack Labeling Tailwinds:Evolving Nutri-Score and traffic-light mandate expansions across EU member states are rewarding reformulated products with favorable shelf placement in Carrefour, Tesco, and REWE networks.
Industry Challenges
- Dairy Technologist Scarcity:Water-in-oil emulsion expertise and churning-process optimization skills are concentrating within R&D-heavy multinationals, constraining regional processor innovation velocity.
- Emulsion-Processing Capex Intensity:Centralized high-shear mixing and continuous churning infrastructure require substantial capital deployment, disadvantaging smaller processors in facility upgrade cycles.
- Cross-Jurisdictional Certification Complexity:Divergent microbial limits, additive approvals, and health claim substantiation requirements across EFSA, FDA, and BIS regimes extend product launch timelines and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Butter Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spreadable, Block, Whipped, Liquid Packaging Type: Tubs, Sticks, Pouches, Jars Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Customer Type: Households, Restaurants, Cafes, Catering Services |
| Companies Covered | Land O'Lakes, Inc., Ornua Co-operative Limited, AMUL Dairy, Palsgaard, Agral S.A., Finlandia Cheese, Inc., Saputo Dairy Australia Pty Ltd, Arla Foods, Upfield, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Butter Market Shifts & Advancements
Reformulation science is compressing the sensory-performance gap between reduced-fat and conventional butter, while regulatory labeling convergence and channel disintermediation are rewriting how household purchasers discover and repurchase spreadable formats.
Advanced emulsifier systems incorporating polyglycerol esters and modified lecithin are decomposing the traditional trade-off between fat reduction and mouthfeel retention. Bakery and foodservice procurement teams are accelerating adoption of sub-40% fat variants for recipe standardization. This technological shift is decomposing the premium pricing power historically commanded by full-fat butter in commercial applications.
EFSA's evolving enforcement of nutrient profiling criteria for health claims is compressing permissible marketing language across EU member states. Processors must now substantiate compositional claims through standardized testing protocols or face delisting from retailer-approved supplier programs. Spreadable formats bearing validated fat-content descriptors are securing preferential placement in German and French supermarket chains.
Subscription-based replenishment models are displacing intermittent supermarket purchasing among health-conscious households in the United Kingdom and Scandinavia. Direct-to-consumer platforms are capturing recurring revenue through personalized portion sizing and flavor rotation, bypassing traditional retail margin stacking. This behavioral pivot is most visible in urban centers with mature cold-chain last-mile infrastructure.
Low Fat Butter Market Segmentation

Segmentation in low fat butter reveals how formulation, packaging, and channel choices map to distinct supply chain configurations. Each dimension carries regulatory and logistical implications that reshape processor investment priorities.
Product Type:
Spreadable formats dominate domestic retail channels across Germany, France, and the United Kingdom, while block and liquid variants serve export-oriented foodservice procurement.
- Spreadable:Water-in-oil emulsion with added stabilizers maintains spreadability at refrigeration temperatures. Household penetration concentrates in temperate European climates where cold-chain storage complicates block butter usability, with EFSA labeling mandates tightening compositional standards.
- Block:Traditional churned format with reduced fat content achieved through modified cream processing. Bakery and foodservice procurement in Northern Europe favors this format for recipe standardization and portion control, though emulsion stability challenges limit fat reduction below 40%.
- Whipped:Aerated emulsion with nitrogen injection creating volume expansion. Premium positioning in Scandinavian retail channels leverages mouthfeel differentiation.
- Liquid:Homogenized low-fat emulsion for industrial sauce and ready-meal manufacturing. Concentrated demand from centralized food production facilities in the Netherlands and Belgium.
Spreadable commands the established base. The steepest expansion runs through liquid formats for industrial applications.
Packaging Type:
Packaging economics bifurcate between high-volume retail tubs and portion-controlled foodservice formats, with sustainability mandates reshaping material specifications.
- Tubs:Polypropylene or bio-based containers dominate spreadable retail in German and French supermarkets. Recyclability requirements under EU Single-Use Plastics Directive are elevating rPET content minimums.
- Sticks:Individual portion wrappers serve airline, hospitality, and institutional catering procurement. Wax-paper and foil laminates balance shelf stability against disposal regulations.
- Pouches:Flexible stand-up formats for subscription-based direct-to-consumer channels in the United Kingdom. Lightweight logistics reduce last-mile carbon intensity.
- Jars:Glass containers sustain premium positioning in specialty retail and gift segments. Higher unit economics constrain mass-market penetration.
Tubs anchor volume throughput. Pouches are gaining share fastest among challenger brands bypassing traditional retail slotting.
Distribution Channel:
Channel structure determines margin stacking and regulatory exposure, with online formats fragmenting traditional supermarket dominance.
- Supermarkets:Carrefour, Tesco, and REWE networks control household trial through front-of-pack placement. Nutri-Score labeling mandates in France and Germany are reshaping shelf-set composition.
- Convenience Stores:Urban grab-and-go formats in London, Paris, and Berlin prioritize single-serve and small-format SKUs. Cold-chain limitations constrain assortment depth.
- Online Retail:Direct-to-consumer subscription models bypass slotting fees and capture recurring revenue. Mature last-mile infrastructure in Scandinavian urban centers enables personalized portion sizing.
- Specialty Shops:Organic and farm-direct channels in rural France and Italy emphasize provenance and artisan credentials. Limited scale elevates unit premiums.
Supermarkets retain the volume base. Online retail shows the steepest expansion trajectory as subscription penetration deepens.
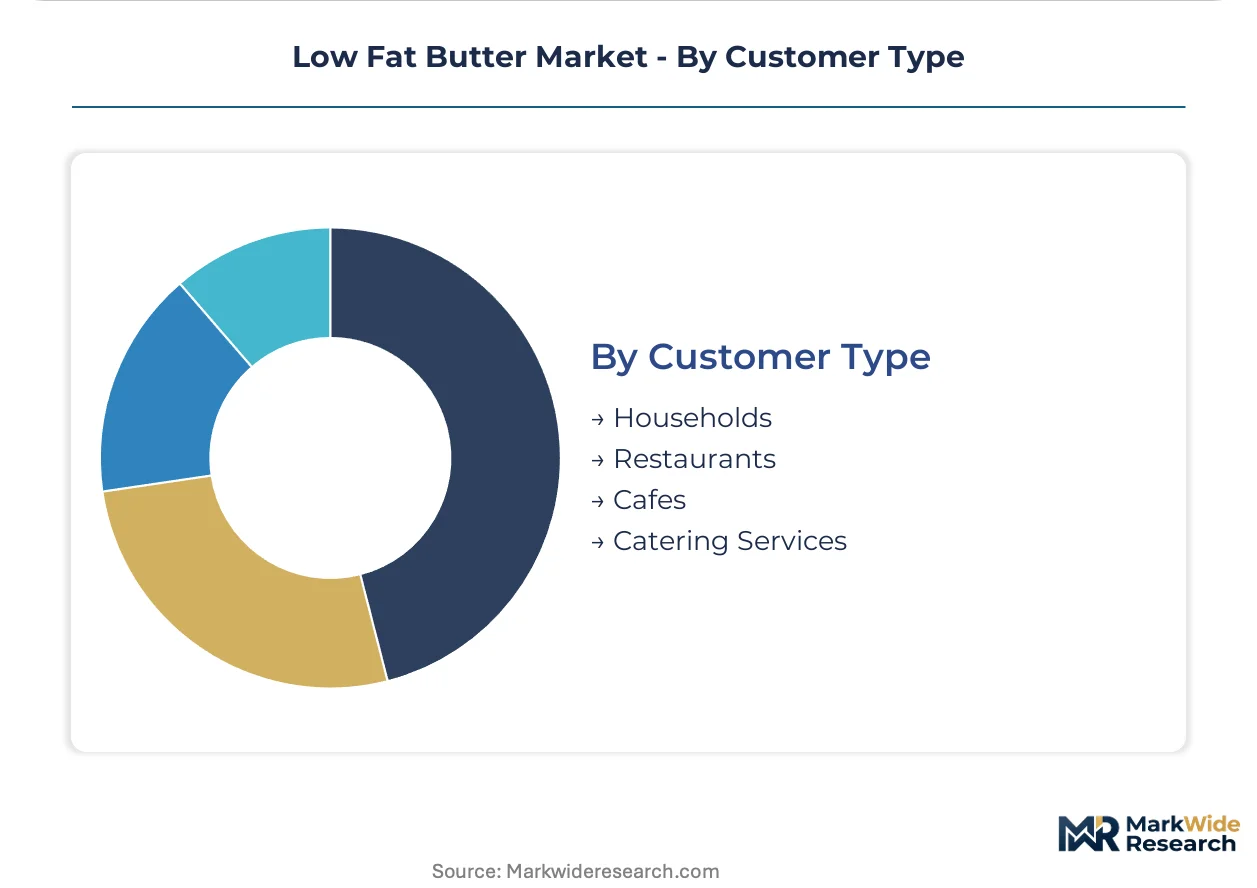
Customer Type:
End-user concentration varies by procurement scale, with institutional buyers demanding specification compliance that household segments ignore.
- Households:Health-conscious purchasers in the United Kingdom and Germany drive spreadable format trial through validated fat-content claims. EFSA substantiation requirements filter marketing language.
- Restaurants:Full-service dining procurement in France and Italy prioritizes sensory parity with traditional butter for sauce and finishing applications. Recipe reformulation costs slow adoption.
- Cafes:Coffee-shop chains in urban German centers specify portion-controlled spreads for pastry and breakfast service. Consistency requirements favor centralized supplier relationships.
- Catering Services:Institutional and event catering in the Netherlands demands bulk formats with extended shelf stability. HACCP compliance and batch traceability dominate vendor selection.
Households anchor the revenue base. Catering services are climbing the fastest as centralized procurement consolidates volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German households favor spreadable formats for daily bread consumption, whereas Indian procurement concentrates in liquid variants for industrial sauce manufacturing. This consumption-mix differential shapes divergent supply chain investments across temperate European retail and tropical Asian foodservice channels.
Germany
Health-conscious households in Berlin and Munich drive refrigerated spreadable purchases through REWE and Aldi Süd networks. EFSA Regulation 1924/2006 substantiation requirements filter permissible fat-content marketing claims. The North Rhine-Westphalia dairy processing corridor concentrates emulsion-technology R&D facilities serving pan-European export demand.
France
Bakery and foodservice procurement in Paris and Lyon sustains block-format demand for recipe standardization in croissant and pastry production. Nutri-Score front-of-pack labeling mandates reshape shelf-set composition across Carrefour hypermarkets. The Brittany dairy cooperative belt anchors fluid milk supply for low-fat churning operations.
United Kingdom
Subscription-based direct-to-consumer models in London and Manchester capture recurring household revenue through personalized portion sizing. Traffic-light labeling regulations govern permissible health claims on Tesco and Sainsbury's shelves. The East Midlands logistics cluster enables cold-chain last-mile delivery for challenger brands bypassing traditional retail slotting.
India
Centralized food production facilities in Gujarat and Maharashtra drive liquid-format procurement for ready-meal and sauce manufacturing. BIS food safety standards impose microbial limits shaping export eligibility for AMUL Dairy and other subcontinent suppliers. The Anand dairy cooperative complex in Gujarat anchors quality benchmarks for international procurement contracts.
United States
Dairy cooperative structures in Wisconsin and Minnesota control cream supply access for low-fat formulation. FDA standards of identity restrict butter labeling to minimum milk-fat thresholds, forcing reduced-fat variants into alternative product classifications. The Upper Midwest processing corridor concentrates churning infrastructure serving domestic retail and Canadian export channels.
Low Fat Butter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cooperative structures and emulsion-technology suppliers occupying distinct competitive positions. R&D-heavy multinationals with captive dairy supply capture margin through formulation mastery, while regional processors compete on localized distribution relationships. Two strategic archetypes dominate: backward-integrated dairy cooperatives with fluid milk security, and specialized emulsion-technology licensors enabling fat reduction without texture degradation. Competitive moves concentrate on geographic licensing partnerships and portfolio diversification into hybrid dairy-alternative territories.
Within the cooperative archetype, Land O'Lakes, Inc. and Arla Foods exemplify structures combining captive milk supply with centralized processing infrastructure. Upfield occupies a position representing plant-blend expertise extension into hybrid spreadable formats. These three entities anchor distinct strategic vectors—dairy cooperative integration, European centralized emulsion processing, and plant-based formulation diversification—each capturing household trial through differentiated sensory positioning and channel access.
| Leading Market Players |
|---|
| Land O'Lakes, Inc. |
| Ornua Co-operative Limited |
| AMUL Dairy |
| Palsgaard |
| Agral S.A. |
| Finlandia Cheese, Inc. |
| Saputo Dairy Australia Pty Ltd |
| Arla Foods |
| Upfield |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between Northern European dairy cooperatives and industrial buyers lock in fluid milk supply visibility while stabilizing input cost baselines for low-fat butter processors navigating EFSA labeling compliance cycles.
Pricing Analysis
Contract-based long-term offtake dominates procurement between dairy cooperatives and foodservice distributors, with spot markets serving residual retail demand fluctuations. Price differentiation rests on emulsion-technology certification tiers and volume scale commitments from bakery chains. Cost compression in standard-grade spreadable formats is intensifying because plant-blend substitutes erode dairy-origin premiums. Quick-service restaurant procurement teams exhibit highest price sensitivity, while premium retail channels absorb formulation premiums for validated fat-content claims.
Supply Chain Analysis
Strait of Malacca transit lanes underpin lecithin and palm-derived emulsifier flows from Southeast Asian processing hubs to European churning facilities. Raw material sourcing draws from Denmark, Germany, and the Netherlands for fluid milk, with stabilizer inputs anchored in Malaysia and Indonesia. Single-source vulnerability concentrates in polyglycerol ester supply from specialized chemical processors. Distribution runs through temperature-controlled consolidation centers in the East Midlands logistics cluster before final-mile deployment to retail and foodservice endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low fat butter sits in early-cycle expansion as EFSA front-of-pack labeling mandates accelerate household trial rates across temperate European markets.
For Market Incumbents: Consolidate emulsion-technology R&D capabilities through selective acquisition of regional stabilization specialists threatened by dairy technologist scarcity. Deepen backward integration into captive dairy supply in the Upper Midwest and Brittany cooperative belts to defend margin position against input cost volatility. For New Entrants and Emerging Players: Subscription-based replenishment service gaps in Scandinavian urban centers offer white-space entry points where incumbents under-serve health-conscious households seeking personalized portion sizing. Direct-to-consumer platforms bypassing supermarket slotting fees represent the most penetrable channel architecture for challenger brands with limited balance sheet capacity. For Investors and Strategic Acquirers: Capital is best deployed toward R&D-heavy mid-cap processors possessing in-house emulsion stabilization expertise and established EFSA substantiation track records. Long-term viability over the coming decade hinges on formulation agility as plant-blend substitution pressures intensify. Watch for inflection signals in BIS microbial compliance certification rates among Indian export-oriented suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Emulsifier-Convergence R&D Partnership | Polyglycerol-lecithin hybrid systems enable sub-40% fat variants without texture degradation for bakery verticals. |
| Direct-to-Consumer Channel Launch | Subscription models bypass Carrefour and Tesco slotting fees while capturing recurring household revenue in UK urban centers. |
| Backward Integration into Dairy Supply | Captive fluid milk access in Wisconsin and Minnesota insulates processors from cooperative pricing power concentration. |
| BIS Export Certification Investment | Microbial compliance pathways unlock procurement contracts with AMUL Dairy-anchored Indian food production facilities. |
| Hybrid Dairy-Alternative Portfolio Extension | Plant-blend expertise acquisition defends against cholesterol-free positioning from specialized emulsion processors. |
Research Methodology
Operator-level perspectives from dairy processing plant managers, emulsion-technology R&D directors, retail category buyers at REWE and Tesco, and foodservice procurement leads anchored the qualitative base. Secondary validation drew from EFSA regulatory filings, BIS food safety standard documentation, EU Single-Use Plastics Directive implementation records, and customs trade data tracking emulsifier ingredient flows. Bottom-up volume estimates triangulated against top-down category spending analyses across the analysis window.
Sensitivity analysis tested forecast outputs against varying adoption rates for subscription-based distribution and divergent EFSA enforcement intensities. Segmentation dimensions modeled include product format, packaging type, distribution channel, and customer procurement scale throughout the forecast period. CAGRs derived from historical trajectory analysis adjusted for technology diffusion curves in emulsifier stabilization systems and cold-chain infrastructure penetration patterns.
Forecasts assume regulatory continuity in EFSA nutrition claims enforcement and BIS microbial limit regimes; material policy shifts in front-of-pack labeling mandates or export certification pathways would require re-modeling. Practitioners should keep alternative scenarios live as plant-blend substitution rates and direct-to-consumer channel penetration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
North America Fluid Milk Market
Dairy Products
United States Casein Market
Dairy Products
Dairy Products Market
Dairy Products
Non-GMO Yogurt Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Milk Retentate Market
Dairy Products
North America A2 Milk Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Spoonable Yogurt Market
Dairy Products
Ricotta Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Evaporated Milk Market
Dairy Products
Butter and Margarine Market