
 Europe Flavored Milk Market | 2026-2036
Europe Flavored Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flavored Milk Market Foresight
On-premise consumption in cafés and quick-service restaurants is rebalancing toward grab-and-go chilled formats as post-pandemic commuter patterns normalize across metropolitan France and the United Kingdom. Arla Foods amba leverages its cooperative dairy sourcing network to secure consistent milk supply for flavored production lines. Lactalis Group anchors its position through deep retail penetration in Southern European markets. Nestlé S.A. competes on formulation science, maintaining R&D facilities in Switzerland that develop reduced-sugar flavor systems.
Europe flavored milk denotes pasteurized or UHT-treated dairy beverages infused with cocoa, fruit extracts, coffee solids, or vanilla compounds, typically containing 80-90% milk content with stabilizers and sweeteners, processed through homogenization and thermal treatment to achieve shelf stability or refrigerated distribution. Chocolate milk occupies the dominant volume position due to entrenched child-consumer loyalty and sports-recovery positioning, while coffee milk captures faster growth as adult breakfast routines shift toward caffeinated convenience formats. Tetra Pak cartons lead package-type share for ambient distribution, though bottle formats gain traction in premium chilled segments where visual branding and resealability drive purchase decisions.
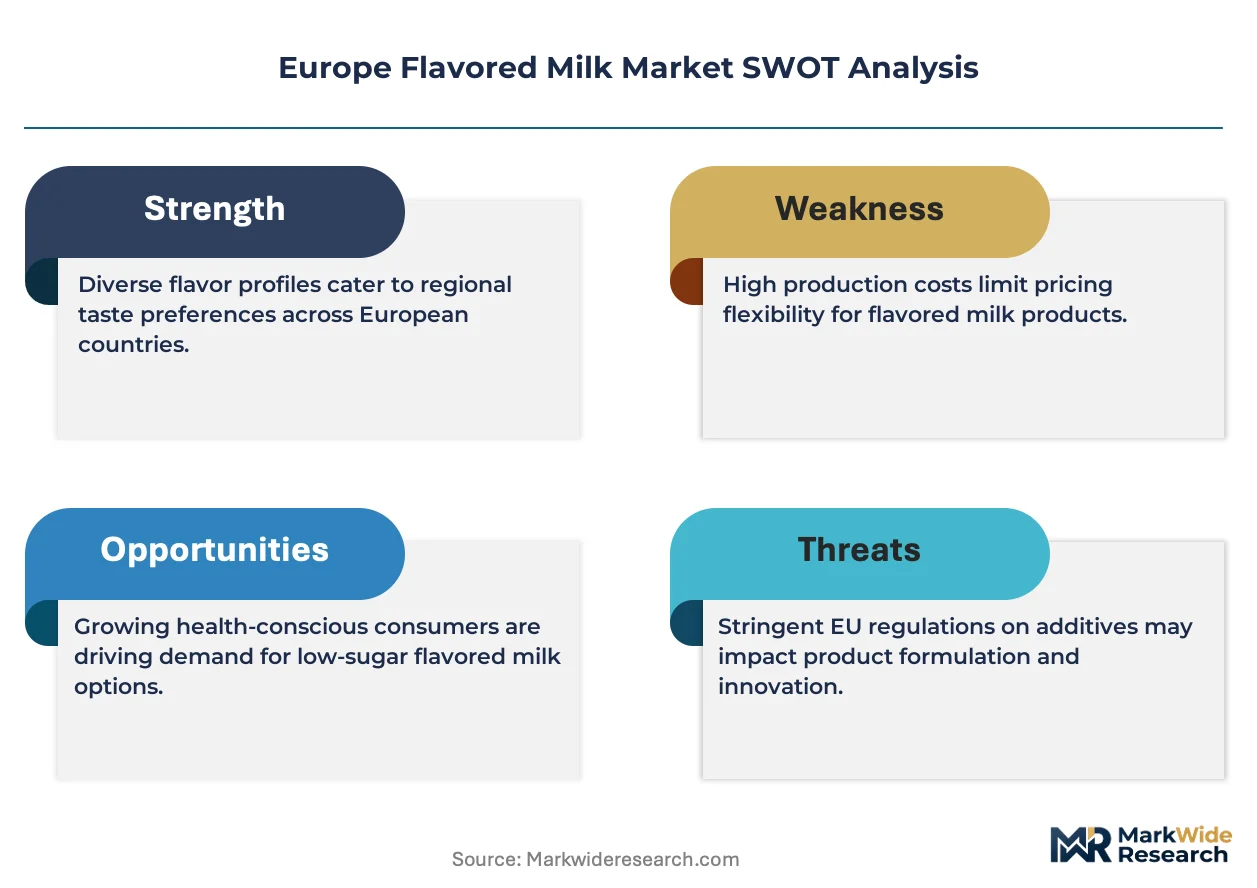
EFSA nutrition and health claims regulation shapes product labeling and fortification strategies, while the EU Farm to Fork Strategy mandates progressive sugar reduction that reformulation teams must address. ECHA oversight of food-contact materials influences packaging migration limits and barrier-layer specifications for multilayer cartons. Stakeholders must monitor evolving EU-wide front-of-pack nutritional scoring systems and national sugar-tax implementations that could reshape margin structures across member states.
Market Dynamics
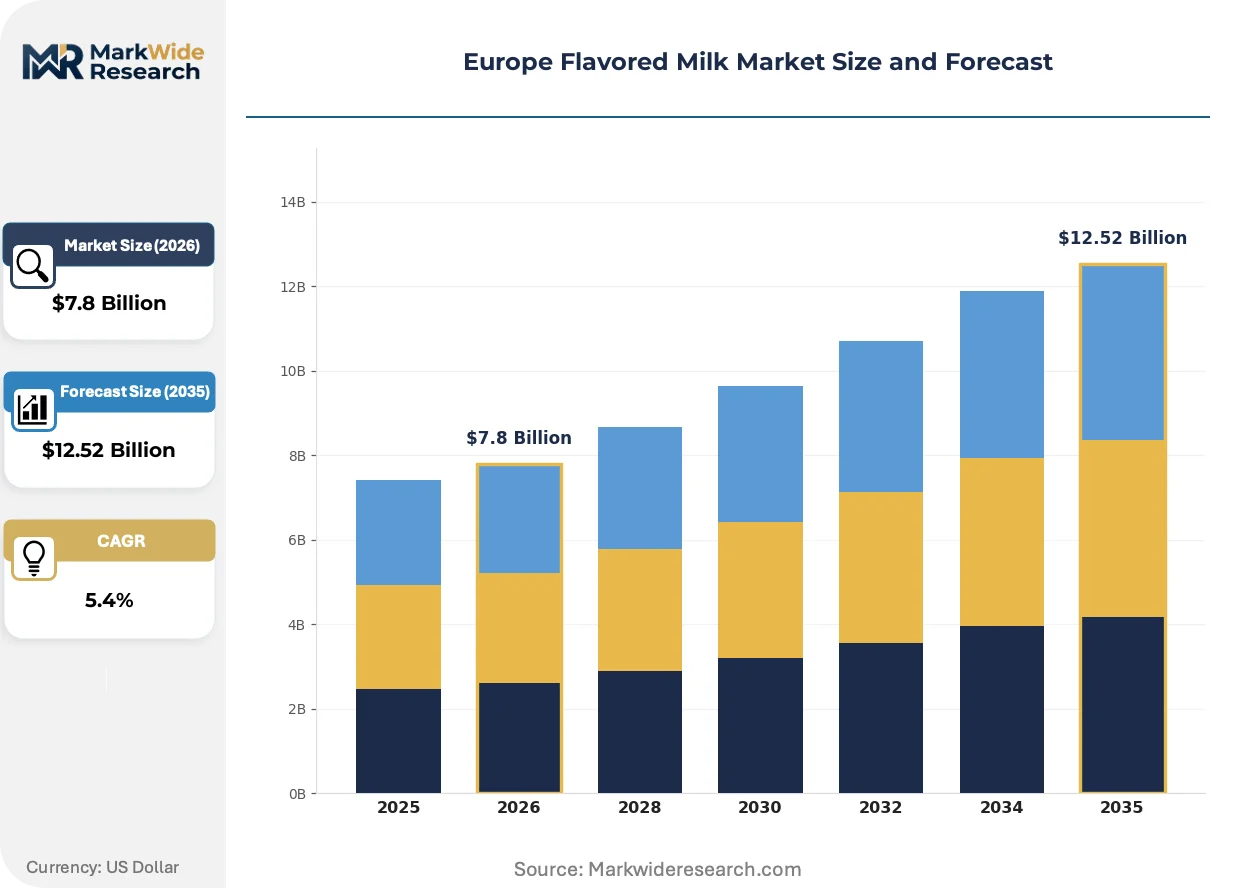
The EU Farm to Fork Strategy's sugar-reduction mandates are forcing accelerated reformulation across European flavored milk portfolios, compressing formulation timelines while opening premium positioning for clean-label alternatives.
Growth Catalysts
- Fortified nutrition positioning:School nutrition programs in Germany and France are expanding procurement volumes for calcium and vitamin D enriched variants targeting adolescent bone health.
- ESPR packaging rules:The EU's Ecodesign for Sustainable Products Regulation is accelerating fiber-based barrier material adoption, creating first-mover advantages for compliant suppliers.
- Chilled distribution infrastructure:Cold chain expansion in metropolitan France and the United Kingdom is enabling extended shelf-life premium products with higher margin capture.
Market Restraints
- Raw milk price volatility:Dairy commodity fluctuations in the Netherlands and Denmark directly compress processor margins, particularly for standard-tier products with limited pricing power.
- Sweetener reformulation costs:Stevia and monk fruit extract procurement carries 40-60% cost premiums versus sucrose, straining R&D budgets across mid-sized producers.
- Retailer consolidation:Aldi and Lidl's combined 35%+ grocery share in Germany and Austria concentrates buyer power, squeezing supplier terms and promotional flexibility.
Strategic Opportunities
- Polish and Romanian market penetration:Per capita flavored milk consumption in these markets sits below 30% of Western European levels, offering volume expansion potential for chilled premium formats.
- Coffee-milk hybrid acceleration:Workplace breakfast routines favoring caffeinated convenience are driving double-digit growth in barista-inspired ready-to-drink variants across the United Kingdom.
- Deposit return scheme alignment:Germany's DRS expansion and impending French consigne regulations favor rPET bottle formats over multilayer cartons in premium segments.
Industry Challenges
- Clean-label stabilization:Removing carrageenan and artificial emulsifiers while maintaining mouthfeel requires novel protein-hydrocolloid systems that extend development cycles by 12-18 months.
- Cross-border formulation compliance:Divergent national implementations of EU health claims create labeling fragmentation, forcing country-specific production runs that erode scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flavored Milk Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Milk, Strawberry Milk, Vanilla Milk, Coffee Milk Package Type: Bottle, Carton, Tetra Pack, Sachet Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops Consumer Age Group: Children, Teenagers, Adults, Seniors |
| Companies Covered | Arla Foods amba, Lactalis Group, Nestlé S.A., Dr. Oetker, Parmalat S.p.A., Danone S.A., Müller Group, Fonterra Co-operative Group, Royal FrieslandCampina N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flavored Milk Market Shifts & Advancements
Reformulation science and packaging material innovation are converging to reshape competitive positioning in European flavored milk, with sustainability credentials and functional benefits displacing traditional sweetness-based differentiation.
Aseptic cold-brew coffee infusion technology is electrifying production efficiency for adult-oriented variants. Mid-sized processors in Italy and Spain are adopting modular in-line extraction systems that reduce thermal degradation of aromatic compounds. This capability compression is enabling regional brands to challenge multinational shelf presence in convenience channels.
EFSA's updated nutrition and health claims guidance is tightening substantiation requirements for probiotic and immune-support positioning. Manufacturers must now generate human intervention studies for strain-specific claims, elevating R&D investment thresholds. The French and German markets show fastest response, with reformulated portfolios dropping unverified claims ahead of enforcement deadlines.
Direct-to-subscription models are fragmenting traditional grocery dependence in the United Kingdom and Netherlands. Urban professionals are adopting weekly chilled delivery services for premium variants, bypassing supermarket shelf competition. This channel rotation is most pronounced in London and Amsterdam metropolitan zones, where refrigerated last-mile logistics have achieved cost parity with retail distribution.
Europe Flavored Milk Market Segmentation
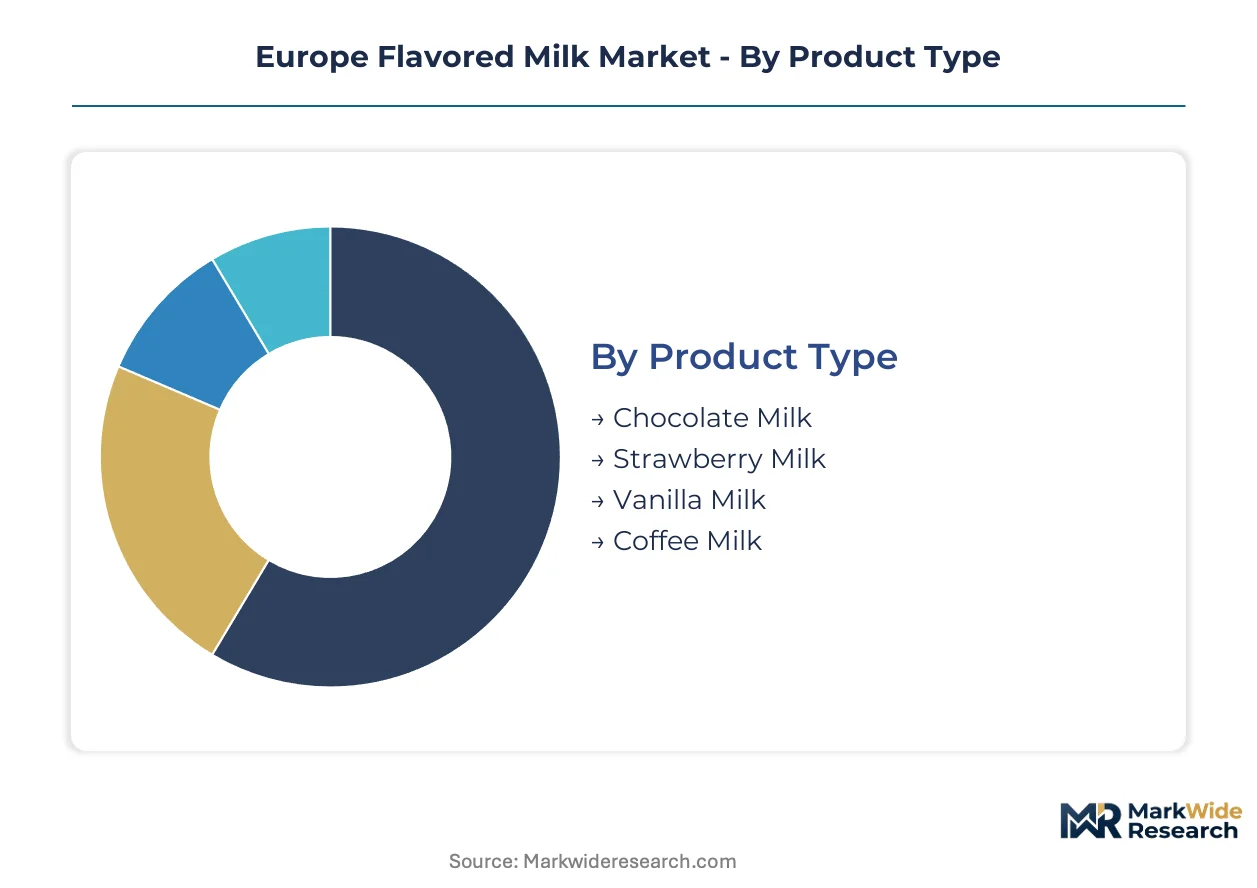
Segmentation in the Europe flavored milk market reveals distinct performance profiles across product formulations, packaging formats, and channel strategies. Each dimension carries unique margin structures and regulatory exposure that shape portfolio prioritization for processors operating under EU Farm to Fork compliance timelines.
Product Type:
Chocolate milk anchors standalone consumption occasions with entrenched brand loyalty, while coffee milk embeds within broader adult beverage routines as a hybrid convenience format.
- Chocolate Milk:Formulations contain 80-90% dairy base with cocoa solids and stabilizer systems, typically UHT-treated for ambient distribution. German and French school nutrition programs concentrate procurement for this variant, though EFSA sugar-reduction mandates are compressing formulation flexibility.
- Coffee Milk:Cold-brew coffee infusion technology enables barista-inspired flavor profiles with reduced thermal degradation. United Kingdom metropolitan demand is climbing fastest as workplace breakfast routines favor caffeinated convenience over traditional hot preparation.
- Strawberry Milk:Fruit-extract formulations targeting child consumers with pink-color positioning and vitamin fortification claims.
- Vanilla Milk:Classic flavor profile serving as a gateway variant for flavor-adverse consumers and senior nutritional supplementation programs.
Chocolate milk leads volumes today; coffee milk is gaining share fastest.
Package Type:
Packaging selection stratifies across ambient distribution economics, chilled premium positioning, and emerging deposit-return compliance requirements.
- Tetra Pack:Multilayer carton construction with aluminum barrier layers dominates ambient shelf-stable distribution. ECHA food-contact material oversight on migration limits is forcing barrier-layer redesigns that extend qualification timelines for compliant suppliers.
- Bottle:rPET and HDPE formats enable resealability and visual branding for chilled premium segments. Germany's DRS expansion and impending French consigne regulations favor bottle adoption over cartons in metropolitan convenience channels.
- Carton:Fiber-based gable-top constructions for short-shelf-life chilled distribution with reduced material complexity.
- Sachet:Single-serve powder or liquid concentrate formats targeting price-sensitive Eastern European markets and foodservice portion control.
Tetra Pack commands the largest installed base; bottle formats are expanding most quickly in premium chilled segments.
Distribution Channel:
Channel mix reflects divergent shopper missions from stock-up grocery trips to immediate consumption and subscription-based household replenishment.
- Supermarkets:Multi-format shelf presence with promotional intensity concentrated in family-pack chocolate milk. Aldi and Lidl's combined 35%+ share in Germany and Austria compresses supplier terms and limits promotional autonomy for branded portfolios.
- Online Retail:Direct-to-subscription models fragment traditional grocery dependence in London and Amsterdam metropolitan zones. Refrigerated last-mile logistics have achieved cost parity with retail distribution for weekly chilled delivery services.
- Convenience Stores:Grab-and-go chilled formats aligned with post-pandemic commuter normalization across metropolitan France.
- Specialty Shops:Premium and organic-positioned variants with extended ingredient transparency and local sourcing credentials.
Supermarkets retain volume leadership; online retail is climbing the fastest as subscription penetration deepens in Northern European urban markets.
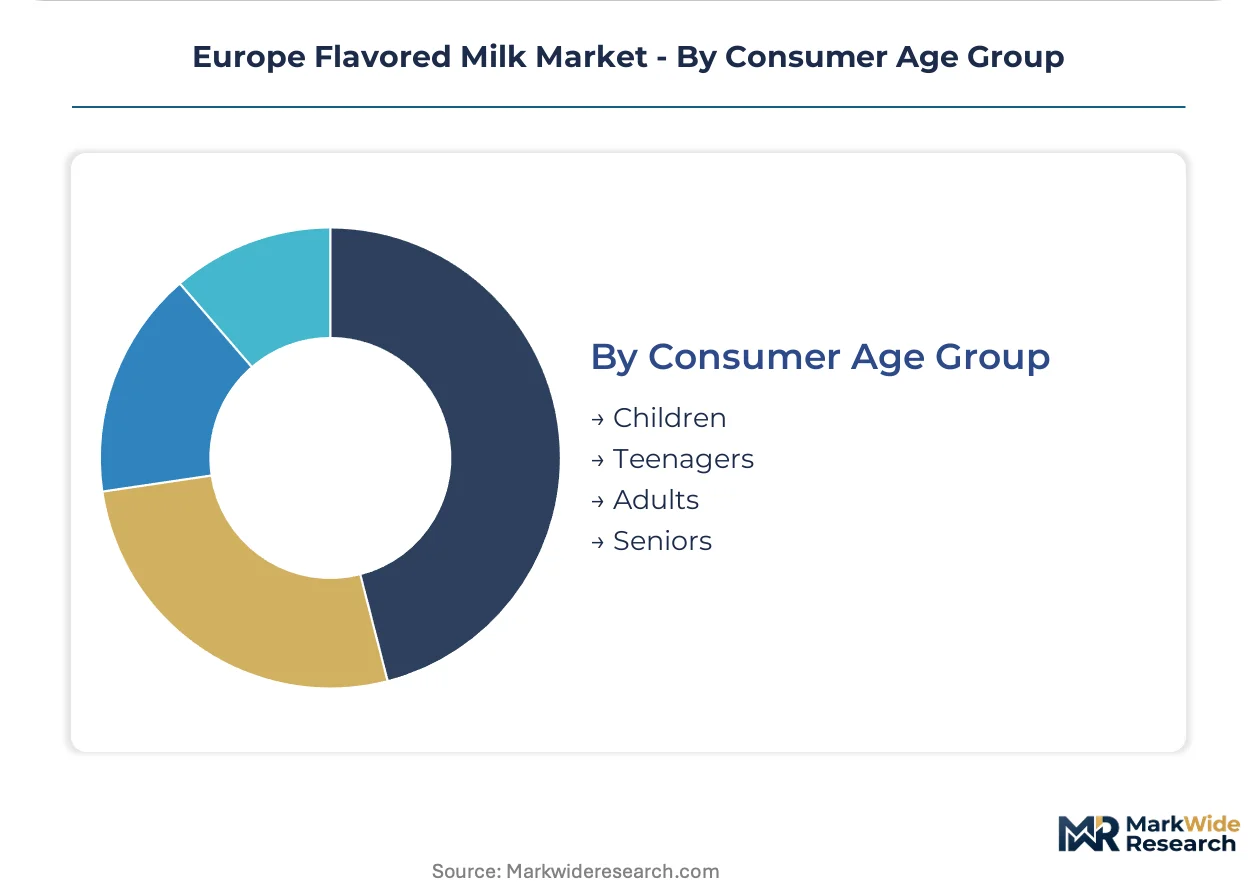
Consumer Age Group:
Age-based targeting determines fortification strategy, flavor profile intensity, and health claim substantiation requirements under EFSA guidance.
- Children:Calcium and vitamin D enrichment with reduced-sugar formulations responding to parental scrutiny. School procurement programs in Germany and France validate this segment's institutional volume concentration.
- Adults:Coffee milk and protein-fortified variants align with workplace convenience and sports-recovery positioning. United Kingdom demand for caffeinated breakfast alternatives is steepening growth curves for this cohort.
- Teenagers:Social consumption occasions with brand-conscious flavor experimentation and on-the-go portability requirements.
- Seniors:Nutritional supplementation focus with texture-modified formulations and medical-channel distribution in select markets.
Children anchor current volume; adults represent the steepest expansion trajectory as coffee milk penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling flavored milk production toward jurisdictions with more flexible sugar-reduction timelines, as EFSA compliance costs compress margins in early-adopter markets. Processors are relocating formulation centers to exploit staggered national implementation of EU Farm to Fork mandates.
Germany
School nutrition procurement in Bavaria and North Rhine-Westphalia drives institutional volume for calcium-fortified chocolate milk. The country's deposit return scheme expansion favors rPET bottle formats over multilayer cartons in convenience channels. Berlin-based dairy cooperatives are consolidating chilled distribution networks to serve metropolitan commuter corridors.
France
Pending consigne regulations are accelerating packaging format shifts in Île-de-France retail channels. ANSM oversight of nutritional claims is tightening substantiation requirements for probiotic-positioned variants. Lyon and Marseille processors are piloting fiber-based barrier materials to preempt ESPR compliance deadlines.
United Kingdom
London and Amsterdam-style subscription delivery models are achieving cost parity with traditional retail in Greater London and the Southeast. Workplace breakfast routines favoring caffeinated convenience are steepening coffee milk growth curves. Birmingham distribution hubs are expanding cold chain capacity for premium chilled formats.
Italy
Lombardy and Emilia-Romagna processors are adopting modular cold-brew infusion systems to challenge multinational shelf presence. ECHA migration limits on food-contact materials are forcing barrier-layer redesigns for Tetra Pak-dependent ambient portfolios. Milan-based mid-sized brands are fragmenting grocery dependence through direct-to-subscription channels.
Poland
Per capita consumption sitting below 30% of Western European levels offers volume expansion potential for chilled premium entrants. Warsaw and Krakow retail consolidation is concentrating buyer power among domestic grocery chains. Local processors are leveraging flexible formulation timelines to capture reformulation-driven supplier switches from German and French markets.
Europe Flavored Milk Market Competitive Landscape
Portfolio diversification dominates the current landscape as processors hedge against sugar-tax exposure and raw milk volatility. The vendor base stratifies across three tiers: multinational dairy conglomerates with integrated supply chains, regional cooperatives leveraging local sourcing credentials, and mid-sized specialists exploiting modular production flexibility. Two competitive vectors define current positioning: accelerated reformulation partnerships with flavor houses to compress clean-label development cycles, and backward integration into captive dairy supply to insulate margin structures from commodity swings.
Within the cooperative tier, Arla Foods amba and Fonterra Co-operative Group exemplify member-owned structures that secure consistent milk supply for flavored production lines. Among diversified dairy conglomerates, Nestlé S.A. occupies a position emphasizing formulation science capabilities. Lactalis Group and Danone S.A. sit within the scale-driven segment, leveraging deep retail penetration across multiple European jurisdictions. These archetypes represent distinct responses to EFSA sugar-reduction mandates and ESPR packaging compliance timelines.
| Leading Market Players |
|---|
| Arla Foods amba |
| Lactalis Group |
| Nestlé S.A. |
| Dr. Oetker |
| Parmalat S.p.A. |
| Danone S.A. |
| Müller Group |
| Fonterra Co-operative Group |
| Royal FrieslandCampina N.V. |
| Others |
Supply & Pricing Matrix
EU Farm to Fork Strategy sugar-reduction mandates gate qualified supply access for premium-tier flavored milk positioning, as compliant reformulation capabilities concentrate among processors with captive R&D infrastructure and backward-integrated dairy supply. Retailer consolidation across German and Austrian markets compresses channel margins, forcing suppliers to absorb sweetener cost premiums or sacrifice shelf placement.
Pricing Analysis
Retailer markup layers in German and French grocery channels absorb 25-35 points of final shelf price, compressing processor margins on standard-tier chocolate milk while subscription direct-to-consumer models bypass this extraction. Three-tier pricing structure across premium chilled, standard UHT, and economy private-label levels reflects fortification intensity and packaging format costs. Pricing pressure stems from stevia and monk fruit extract procurement carrying 40-60% premiums over sucrose, squeezing mid-sized producers with limited reformulation scale. Aldi and Lidl shoppers exhibit highest price sensitivity, while London and Amsterdam subscription adopters accept 20-30% premiums for chilled delivery convenience.
Supply Chain Analysis
Workforce availability constraints in Netherlands and Denmark dairy processing regions are tightening operational flexibility for UHT line expansion. Raw milk supply concentrates in Germany, France, and the Netherlands, with seasonal volatility in Dutch dairy commodity markets feeding directly into processor margin compression. Cold-brew coffee extract, cocoa solids, and novel protein-hydrocolloid stabilizers constitute critical input dependencies with concentrated supplier bases. Single-source vulnerability in carrageenan replacement ingredients extends clean-label development cycles by 12-18 months. Distribution runs through refrigerated hub-and-spoke networks in metropolitan France and the United Kingdom, with ambient Tetra Pak volumes flowing through centralized dairy cooperative logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe flavored milk functions as a stable compounder anchored by institutional school nutrition procurement in Germany and France, where adolescent bone-health fortification mandates generate recurring volume commitments with limited substitution risk.
For Market Incumbents: Cement supply security through cooperative dairy membership consolidation in Denmark and the Netherlands, insulating margin structures from raw milk spot volatility. Deepen captive R&D partnerships with Swiss flavor houses to compress clean-label reformulation timelines ahead of EFSA enforcement deadlines. Prioritize ESPR-compliant fiber-based barrier material qualification to capture first-mover shelf access in French consigne-regulated channels.
For New Entrants and Emerging Players: Launch via direct-to-subscription refrigerated delivery in Greater London and Amsterdam metropolitan zones, where cost parity with retail distribution eliminates slotting fee barriers. Target Polish and Romanian chilled premium white space, where per capita consumption sits below 30% of Western European levels and domestic grocery chains lack exclusive supplier lock-ins. Exploit modular cold-brew infusion technology to challenge multinational coffee milk shelf presence without capital-intensive UHT line investment.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized Italian and Spanish processors with modular production flexibility because EFSA compliance costs are forcing portfolio divestitures from conglomerates seeking clean-label speed. Five-to-ten-year viability hinges on reformulation capability depth and captive dairy supply ratios. Monitor German and French sugar-tax implementation announcements as inflection indicators for accelerated supplier switching toward compliant portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Partnership | Swiss flavor house collaborations compress carrageenan-free development cycles ahead of EFSA deadlines. |
| Refrigerated Subscription Channel Launch | London and Amsterdam direct-to-consumer models bypass Aldi and Lidl buyer power concentration. |
| ESPR-Compliant Packaging Transition | Fiber-based barrier qualification secures French consigne-regulated shelf access before enforcement. |
| Cooperative Dairy Supply Consolidation | Netherlands and Denmark member-owned structures insulate processor margins from commodity swings. |
| Polish and Romanian Market Entry | Chilled premium penetration captures volume expansion in underpenetrated Eastern European markets. |
Research Methodology
Multiple input streams — executive interviews with dairy cooperative procurement directors, flavor house R&D leads, and German retail category buyers; secondary validation against EFSA guidance documents, EU Farm to Fork Strategy implementation timelines, and Nielsen retail audit data; plus customs records for cocoa and coffee extract trade flows — were reconciled through bottom-up volume modeling and top-down value triangulation.
Data-stream reconciliation anchored forecast outputs to segmentation dimensions spanning product formulation intensity, packaging format compliance tiers, and channel mix evolution across the projection horizon. CAGRs were derived from trend-line extrapolation of historical procurement volumes adjusted for regulatory phase-in schedules. School nutrition program expansion rates and cold chain infrastructure investment pipelines in metropolitan France and the United Kingdom served as demand-side calibration inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU-wide sugar-tax implementation or raw milk price spike scenarios beyond historical volatility bands. Practitioners should monitor EFSA enforcement deadline announcements and German DRS expansion timelines for early signals of supplier switching velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Ricotta Market
Dairy Products
Germany Dairy Market
Dairy Products
Dairy Protein Market
Dairy Products
Dairy Carton Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Parmesan Cheese Market
Dairy Products
North America Flavored Milk Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Organic Milk Protein Market
Dairy Products
India Milk Protein Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Mascarpone Cheese Market
Dairy Products
GCC UHT Milk Market