
 Low-Fat Cocoa Powder Market | 2026-2036
Low-Fat Cocoa Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Cocoa Powder Market Analytics
West African grinding capacity is decoupling from traditional fat-content specifications as processors retool for health-positioned outputs. Cargill leverages its integrated bean-to-powder infrastructure across Ivory Coast and Ghana to secure low-fat stream consistency. Barry Callebaut sustains R&D intensity in cocoa butter reduction technologies without sacrificing flavor delivery. ADM anchors North American supply through its Decatur, Illinois processing complex, where it controls alkalization and pressing parameters for fat-standardized output.
Low-fat cocoa powder contains typically 10-12% residual cocoa butter, achieved through hydraulic pressing of cocoa liquor to separate fat prior to pulverization, and serves primarily as a color and flavor vehicle in calorie-reduced confectionery and baked goods. Dutch-processed cocoa dominates industrial procurement because alkalization improves dispersibility in beverage applications and extends pH-adjusted stability in baked matrices. Organic cocoa commands premium positioning within specialty stores and online retail channels, where home cooks and artisan bakeries drive smaller-volume, higher-margin purchases.
FDA standards of identity for cocoa products govern fat-content labeling in the United States, while the EU Green Deal and EUDR deforestation regulations reshape import documentation and traceability requirements for European processors. BIS quality specifications in India and FSSAI food safety mandates further segment market access by certifying heavy-metal limits and microbiological thresholds. Stakeholders must monitor how evolving trans-fat disclosure rules and clean-label procurement policies redirect formulation choices across confectionery and beverage channels.
Market Dynamics
The EUDR deforestation-free mandate is compressing supply chain timelines for European processors while simultaneously elevating traceability costs across West African sourcing corridors. This regulatory pressure is redrawing procurement geography and forcing rapid infrastructure upgrades at origin.
Growth Catalysts
- EU Green Deal traceability mandates:Importers must document deforestation-free origins through satellite-verified supply chains, accelerating certified low-fat grade premiums.
- Confectionery calorie-reduction targets:Industrial chocolate formulators in Germany and Belgium are specifying 10-12% fat cocoa powders for mass-market product lines.
- Alkalization process refinements:Enhanced dispersibility in beverage matrices is opening institutional foodservice channels previously dominated by full-fat alternatives.
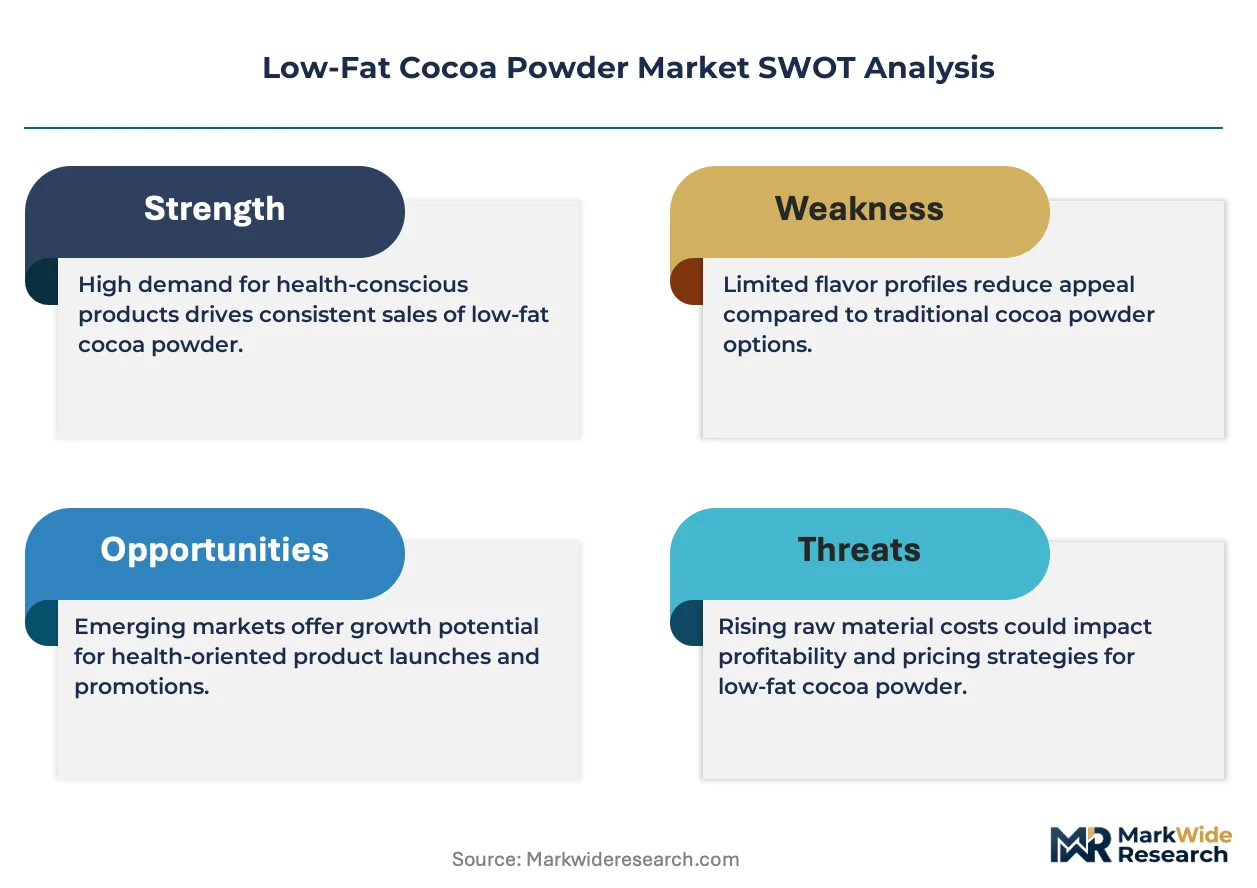
Market Restraints
- Cocoa butter price volatility:Hydraulic pressing economics fluctuate with cocoa butter futures, squeezing processor margins when fat values drop.
- West African supply concentration:Ivory Coast and Ghana origin dependency creates weather and political risk exposure for standardized low-fat streams.
- Flavor-fat tradeoff ceiling:Residual butter reduction below 10% degrades mouthfeel in premium chocolate applications, limiting health-positioning penetration.
Strategic Opportunities
- Indian FSSAI-compliant manufacturing:Domestic alkalization capacity expansion can capture import-substitution demand from Mumbai and Bangalore chocolate processors.
- E-commerce artisan baking channels:Organic low-fat SKUs command premium positioning through direct-to-consumer platforms targeting home bakers.
- Clean-label beverage convergence:Natural alkalization methods paired with stevia-sweetened formulations align with retailer procurement policies.
Industry Challenges
- Heavy-metal testing compliance:Cadmium and lead threshold verification under EU and BIS specifications extends batch release timelines.
- Legacy ERP traceability gaps:Origin documentation systems struggle to integrate satellite mapping data with existing inventory management platforms.
- Press operator skill scarcity:Hydraulic liquor pressing requires calibrated fat-standardization expertise that training programs have not scaled.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Cocoa Powder Market |
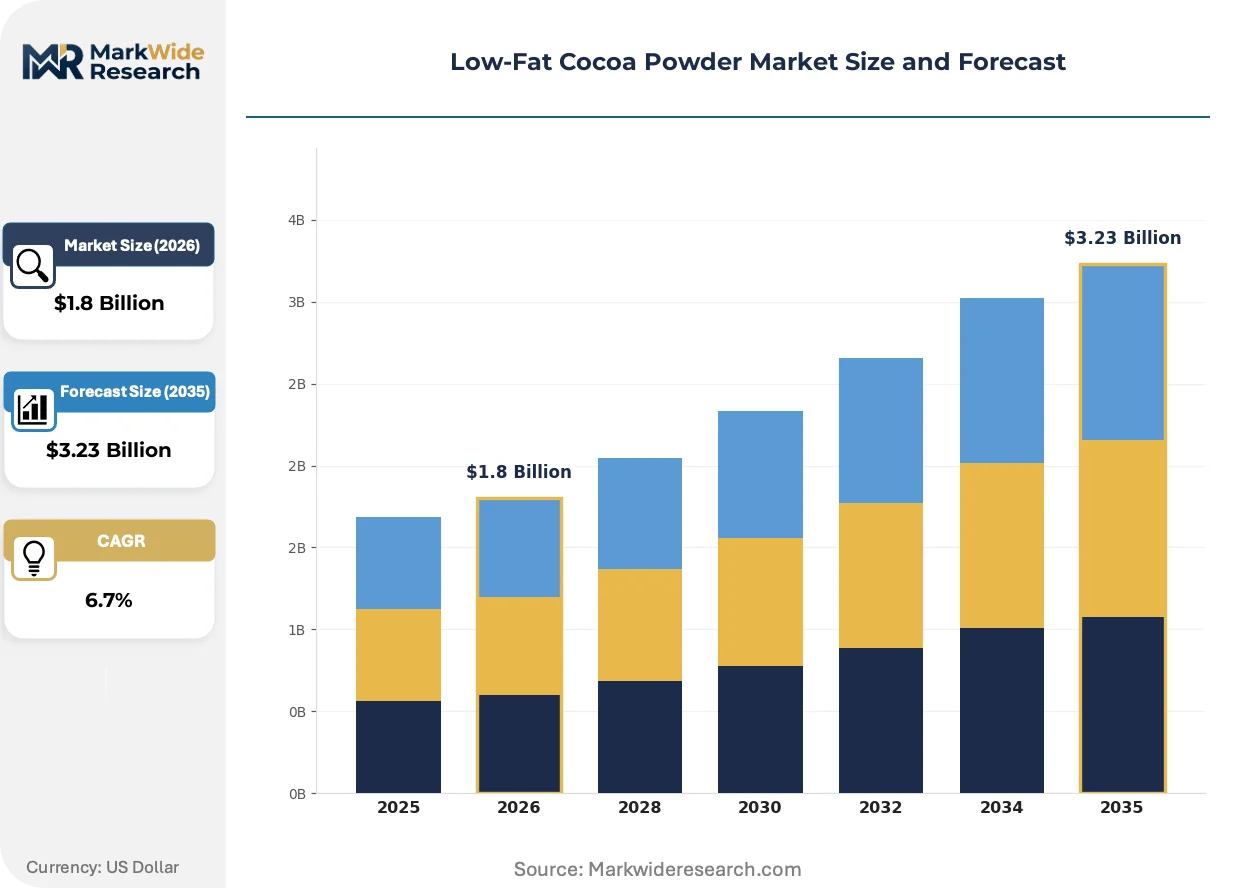
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Cocoa, Dutch-Processed Cocoa, Organic Cocoa, Instant Cocoa End User: Bakeries, Confectionery Manufacturers, Beverage Producers, Home Cooks Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors Application: Baking, Beverages, Desserts, Snack Foods |
| Companies Covered | Cargill, ADM, Barry Callebaut, Dr. Oetker, ICAM, Nestle, Moner Cocoa, Chocolates Valor, JS Cocoa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Cocoa Powder Market Evolving Landscape
Processing technology and procurement protocols are converging to reshape how low-fat cocoa powder moves from bean to formulated end-product. Three distinct vectors are compressing traditional supply timelines and opening new specification tiers.
Supercritical CO2 fat extraction is expanding into commercial-scale cocoa processing, replacing hydraulic pressing in premium-grade lines. Swiss and Belgian confectionery houses are piloting this technology for sub-8% residual fat powders. The process is expanding into mid-tier supply as equipment costs decline and flavor retention improves.
REACH chemical safety registrations and EUDR due diligence obligations are forcing European importers to consolidate supplier panels. Documentation burdens favor vertically integrated processors with captive West African grinding assets. German industrial chocolate clusters are responding by locking multi-year offtake agreements with traceability-guaranteed origins.
Artisan bakery procurement through specialty distributors is fragmenting volume concentration historically held by industrial confectionery. Small-batch alkalized powders in retail packaging are displacing bulk foodservice formats in urban centers. This channel rotation is most visible in Paris, London, and New York specialty ingredient retail.
Low-Fat Cocoa Powder Market Segmentation
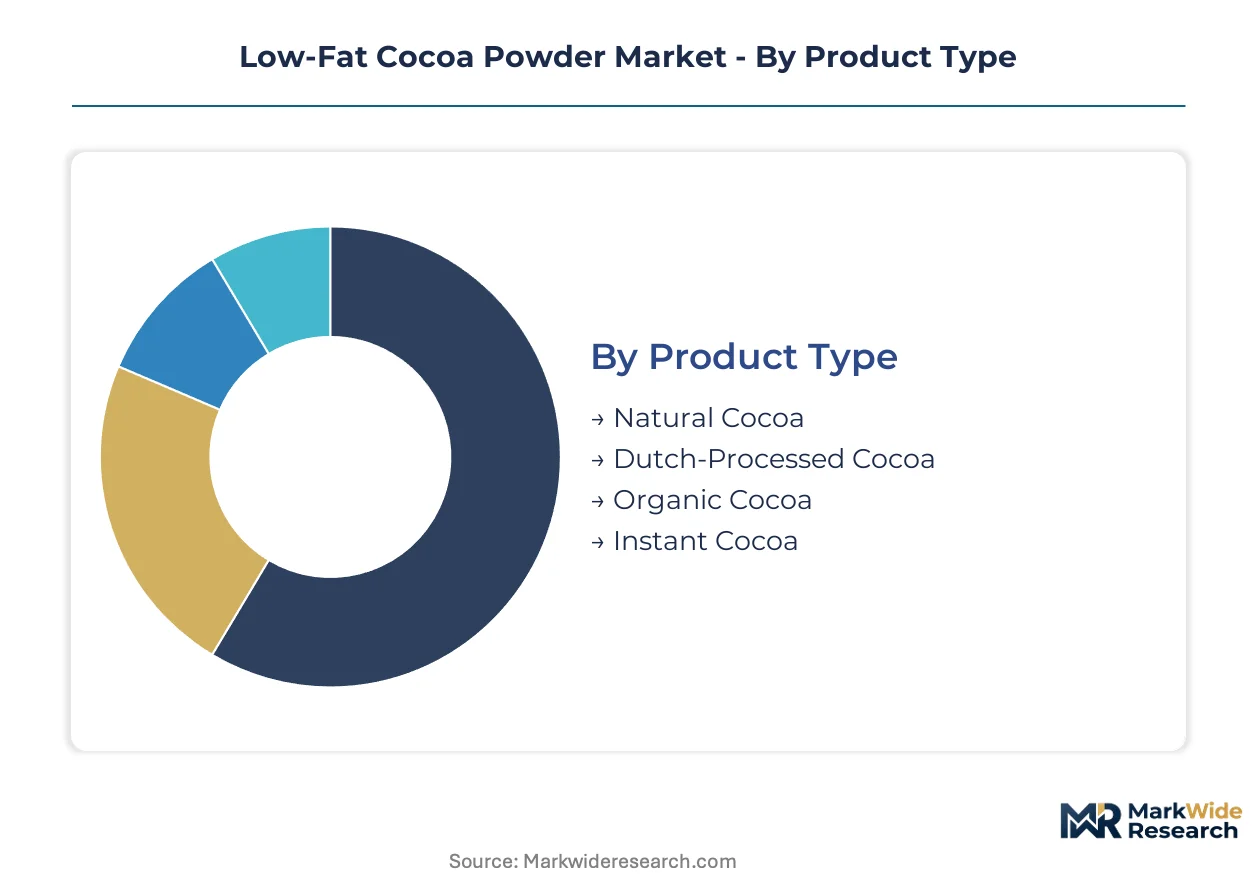
Low-fat cocoa powder specifications diverge sharply across processing methods and end-use requirements. Procurement patterns fragment by alkalization chemistry, residual fat tolerance, and traceability certification tiers.
Product Type:
Alkalization chemistry defines functional performance in beverage and baked matrices.
- Dutch-Processed Cocoa:Alkalization raises pH to neutral or mildly alkaline, improving dispersibility in milk-based beverages and extending shelf stability in high-moisture applications. German and Belgian industrial chocolate clusters specify Dutch-processed grades for mass-market calorie-reduced formulations.
- Organic Cocoa:Certified deforestation-free origin documentation commands premium positioning through specialty retail and direct-to-consumer channels. Artisan bakeries in Paris, London, and New York drive smaller-volume, higher-margin procurement of low-fat organic powders.
- Natural Cocoa:Unalkalized powder retains acidic pH and sharper chocolate flavor, serving traditional baking applications where chemical leavening reactions matter.
- Instant Cocoa:Agglomerated particles engineered for cold-water solubility target convenience beverage segments and foodservice powder dispensers.
Dutch-Processed Cocoa leads on scale; Organic Cocoa leads on momentum.
End User:
Volume concentration and specification tolerance split across industrial and consumer-facing channels.
- Confectionery Manufacturers:Mass-market chocolate processors in Germany specify 10-12% residual fat powders for calorie-reduced product lines, locking multi-year offtake agreements with traceability-guaranteed West African origins.
- Beverage Producers:Alkalized low-fat grades with enhanced dispersibility displace full-fat alternatives in institutional foodservice and ready-to-drink manufacturing.
- Bakeries:Industrial and artisan baking operations source natural or lightly alkalized powders for chemical leavening compatibility and color control in cake and pastry applications.
- Home Cooks:Retail-packaged SKUs through specialty stores and e-commerce platforms drive premium pricing for organic and single-origin certified grades.
Confectionery Manufacturers anchor volume procurement; Beverage Producers are expanding most quickly.
Distribution Channel:
Channel selection determines margin capture and certification documentation depth.
- Wholesale Distributors:Bulk alkalized powders move through foodservice and industrial procurement networks serving chocolate processors and large-scale bakeries.
- Specialty Stores:Urban ingredient retailers in Paris, London, and New York fragment volume concentration with small-batch, retail-packaged organic and single-origin SKUs.
- Online Retail:Direct-to-consumer platforms enable premium positioning for certified low-fat grades targeting home bakers and artisan producers.
- Supermarkets:Mass-market retail chains stock conventional instant and natural cocoa powders for household beverage and baking use.
Wholesale Distributors concentrate industrial volume; Specialty Stores are gaining share fastest.
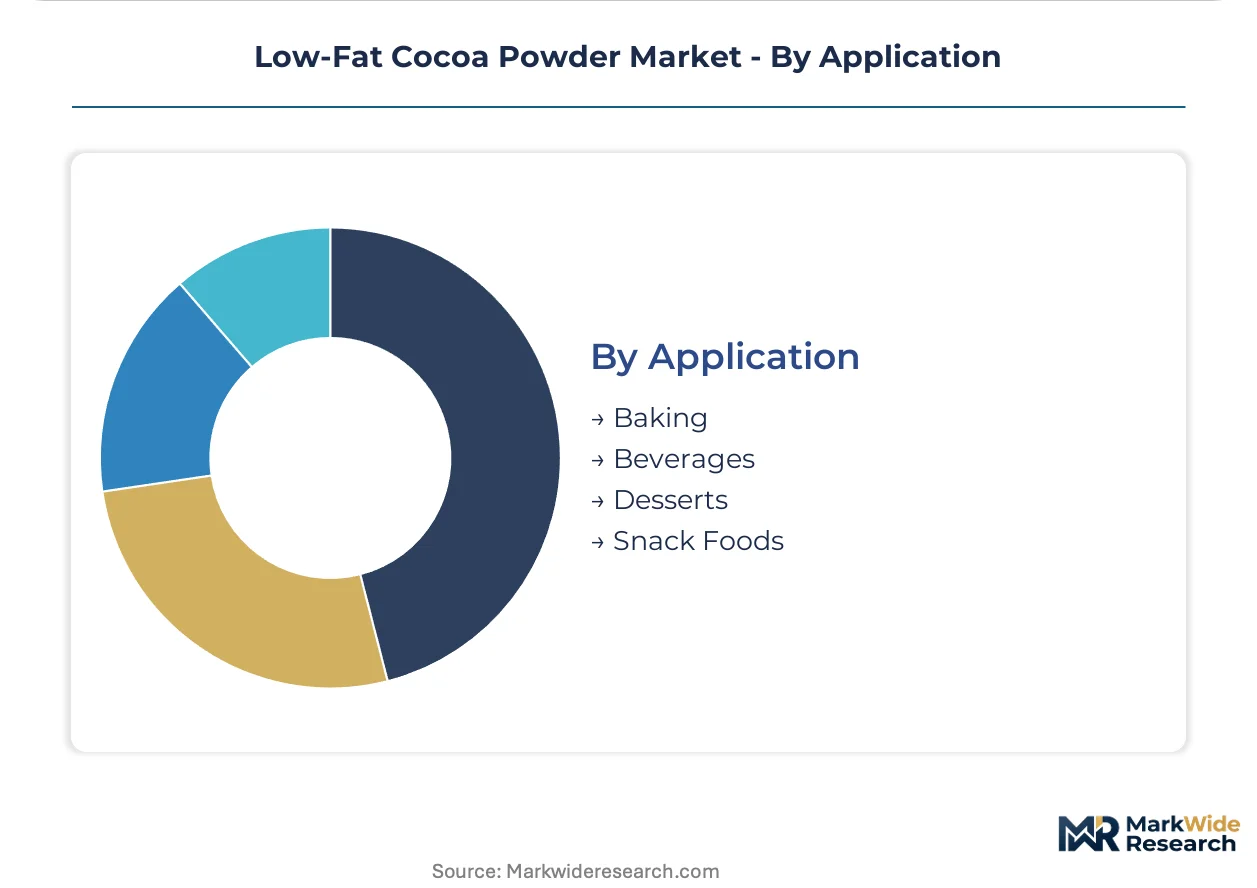
Application:
Functional requirements for fat content, dispersibility, and flavor intensity vary by finished product category.
- Beverages:Alkalized low-fat powders with optimized particle size and lecithin treatment dominate milk-based and ready-to-drink applications.
- Baking:Natural cocoa maintains acidic pH for chemical leavening reactions in cakes and pastries; Dutch-processed grades serve color-critical applications.
- Desserts:Mousse, pudding, and ice cream formulations balance residual cocoa butter for mouthfeel against calorie-positioning requirements.
- Snack Foods:Coating applications for cereals, granola, and protein bars specify low-fat powders for adhesion and flavor without excessive fat contribution.
Beverages concentrate specification innovation; Snack Foods are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial chocolate clusters import bulk low-fat grades at volumes exceeding France's artisan-oriented procurement by a factor of three, while India domestic grinding capacity races to capture import-substitution demand from Mumbai processors.
Germany
Cologne and Hamburg harbor Europe's densest chocolate processing infrastructure, with industrial formulators locking multi-year offtake agreements for 10-12% fat alkalized powders. EU Green Deal traceability mandates force satellite-verified documentation through EUDR compliance platforms. The Cologne-Chocolate-Cluster now mandates deforestation-free certificates for all West African origin shipments.
United States
Decatur, Illinois anchors North American supply through integrated bean-to-powder processing, with beverage manufacturers driving dispersibility-optimized grade procurement. FDA standards of identity govern fat-content labeling thresholds for interstate commerce. Chicago-area confectionery headquarters specify low-fat powders for calorie-reduced mass-market lines.
India
Mumbai and Bangalore chocolate processors source FSSAI-compliant alkalized powders for domestic confectionery expansion, with heavy-metal testing protocols extending batch release timelines. BIS quality specifications certify cadmium and lead limits for import substitution. Gujarat-based grinding capacity expansion targets western India industrial demand.
Belgium
Antwerp grinding facilities retool hydraulic pressing lines for health-positioned outputs, with R&D intensity concentrated in cocoa butter reduction technologies. REACH chemical safety registrations constrain supplier panel consolidation among European importers. The Brussels-Wavre corridor pilots supercritical CO2 extraction for sub-8% residual fat premium grades.
Brazil
São Paulo confectionery manufacturers source natural cocoa powders for traditional baking applications, with ANVISA food safety mandates governing microbiological thresholds. Domestic alkalization capacity remains limited, forcing reliance on imported Dutch-processed grades. The Campinas industrial belt experiments with regional origin certification for specialty cocoa streams.
Low-Fat Cocoa Powder Market Competitive Landscape
West African integrated processors anchor one tier; European specialty houses and North American agribusiness conglomerates hold differentiated positions through technology and scale. The vendor base concentrates around three strategic archetypes: vertically integrated origin processors with captive grinding assets, European R&D-intensive specialists, and North American distribution-heavy conglomerates. Capacity expansion and traceability-guaranteed supply contracts constitute the dominant competitive moves.
Within the integrated-processor tier, Cargill and Barry Callebaut exemplify archetypes of West African infrastructure control and European R&D specialization respectively. ADM occupies a position among North American agribusiness conglomerates with Midwest processing concentration. These three entities represent the spectrum from origin-integrated supply to downstream formulation partnership.
| Leading Market Players |
|---|
| Cargill |
| ADM |
| Barry Callebaut |
| Dr. Oetker |
| ICAM |
| Nestle |
| Moner Cocoa |
| Chocolates Valor |
| JS Cocoa |
| Others |
Value Network & Pricing Analysis
EUDR deforestation-free mandates gate qualified supply and premium-tier pricing access by forcing satellite-verified documentation costs onto European importers. Buyers without traceability-guaranteed West African origins face exclusion from German industrial chocolate clusters, compressing eligible supplier pools and elevating certified low-fat grade premiums.
Pricing Analysis
Capacity additions in India are reshaping price floors for FSSAI-compliant alkalized powders as domestic grinding expands to serve Mumbai and Bangalore processors. Three-tier pricing structure across premium, standard, and economy levels separates EUDR-certified traceability-guaranteed grades from conventional bulk alkalized powders and commodity natural cocoa. Pricing pressure stems from cocoa butter futures volatility squeezing hydraulic pressing margins when fat values drop. Industrial confectionery manufacturers in Germany exhibit lowest price sensitivity due to locked multi-year offtake agreements, while artisan bakeries through specialty stores show highest sensitivity to per-kilogram premiums.
Supply Chain Analysis
Press operator skill scarcity in Ivory Coast, Ghana, and India constrains calibrated fat-standardization throughput at hydraulic liquor pressing facilities. Supply draws from West African bean origins, European alkalization infrastructure, and North American integrated processing complexes at Decatur, Illinois. Raw material dependencies center on cocoa bean supply, cocoa butter futures hedging, and alkalizing agent chemicals. Single-source vulnerability concentrates in Ivory Coast and Ghana origin dependency creating weather and political risk exposure. Distribution runs through wholesale industrial networks serving chocolate processors, specialty ingredient retailers in Paris, London, and New York, and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-fat cocoa powder market functions as a stable compounder anchored by health-positioned confectionery reformulation mandates that sustain procurement intensity across economic cycles.
For Market Incumbents: Acquire satellite-verified traceability infrastructure to lock EUDR-compliant supply corridors against emerging European specialty houses with captive West African assets. Consolidate alkalization capacity in Gujarat to capture Indian import-substitution demand before domestic grinding expansion saturates price premiums. Certification investment in heavy-metal testing protocols defends position against FSSAI compliance delays that extend rival batch release timelines. For New Entrants and Emerging Players: Supercritical CO2 extraction technology offers a technology-first wedge to bypass hydraulic pressing skill scarcity and serve Belgian and Swiss premium-grade lines seeking sub-8% residual fat powders. Target artisan bakery procurement through Paris, London, and New York specialty ingredient retail where small-batch retail-packaged SKUs displace bulk formats. Direct-to-consumer e-commerce platforms provide the most penetrable go-to-market angle for organic certified grades commanding premium positioning from home bakers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European alkalization specialists because EUDR documentation burdens favor consolidated supplier panels with integrated origin assets. Five-to-ten year viability hinges on traceability-guaranteed supply contract duration rather than spot market exposure. Watch for inflection in German industrial chocolate cluster procurement shifts toward supercritical CO2 extracted premium grades as equipment costs decline.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into West African Grinding Assets | Captive supply of traceability-guaranteed beans secures EUDR-compliant documentation for European industrial buyers. |
| Supercritical CO2 Extraction Scale-Up | Sub-8% residual fat premium grades open Belgian and Swiss confectionery house procurement previously closed to hydraulic pressing. |
| FSSAI-Compliant Alkalization Capacity Expansion | Gujarat-based processing captures Mumbai and Bangalore chocolate processor demand under import-substitution pressure. |
| Direct-to-Consumer E-Commerce Platform Launch | Organic low-fat SKUs bypass wholesale distributor margin capture to serve Paris, London, and New York artisan bakers. |
| Heavy-Metal Testing Protocol Investment | Cadmium and lead threshold verification accelerates batch release timelines against BIS and EU specification delays. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cocoa processing plant managers, procurement leads at German industrial chocolate manufacturers, alkalization R&D directors, and specialty ingredient retail buyers with secondary validation. Secondary sources included EU customs and trade data, FDA standards of identity filings, FSSAI food safety mandate documentation, and SEC 10-K disclosures from agribusiness conglomerates. Bottom-up bean-to-powder volume modeling and top-down confectionery end-use demand estimation provided triangulation.
Historical reference periods anchored the forecast window through verified grinding capacity utilization rates and alkalized powder shipment volumes across the projection horizon. Segmentation dimensions modeled include alkalization chemistry, residual fat tolerance tiers, end-use application, and traceability certification status. CAGRs derived from regression against cocoa butter futures correlation, health-positioned confectionery launch pipelines, and regulatory compliance cost trajectories. Industry-specific inputs incorporated EUDR implementation timelines and supercritical CO2 extraction equipment cost decline curves.
The model holds under stable EU Green Deal enforcement intensity and cocoa butter futures within historical volatility bands; deviation in West African political stability or abrupt EUDR scope expansion would shift volume and value trajectories. Forecasts reflect assumptions about hydraulic pressing skill training program scaling and satellite mapping data integration rates with legacy ERP platforms. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydroxytyrosol Market
Ingredients
Vegan Ingredients Market
Ingredients
Germany Gelatin Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Pine Needle Oil Market
Ingredients
Bulk Food Ingredients Market
Ingredients
Coconut Cream Powder Market
Ingredients
Orange Powder Market
Ingredients
China Gelatin Market
Ingredients
Botanical Ingredients Market
Ingredients
Savory Ingredients Market
Ingredients
Cholesterol API Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Global Edible Oil Market
Ingredients
Whipped Topping Concentrate Market
Ingredients
Icing Shortening Market