
 White Cheese Market | 2026-2036
White Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
White Cheese Market Analytics
Food service buyer concentration is expanding as restaurant chains and institutional caterers consolidate procurement under fewer national distributors. FrieslandCampina leverages its European whey processing network to secure long-term supply contracts with these consolidated buyers. Lactalis Ingredients anchors its position through backward integration into regional milk collection cooperatives. Saputo Inc. competes by specializing in crumbled and shredded formats tailored to quick-service kitchen workflows.
White cheese encompasses fresh, unripened dairy products with high moisture content, typically manufactured through direct acidification or minimal rennet coagulation at temperatures below 40°C, yielding soft, sliceable textures for immediate consumption or further processing. Feta and ricotta lead product-type revenue pools due to established Mediterranean diet associations and bakery application versatility, while queso blanco posts the fastest trajectory among food manufacturers seeking clean-label melting agents. Cottage cheese occupies a mature, volume-driven niche concentrated in North American retail channels with thinner margin profiles.
EU EFSA standards govern pathogen limits and labeling claims across member-state production, while FDA pasteurization requirements shape US import eligibility and domestic plant certification burdens. The EU F-Gas Regulation and US EPA energy-efficiency mandates are accelerating cold-chain capital investment, indirectly tightening supply economics for temperature-sensitive fresh cheese categories. Stakeholders must monitor regulatory divergence between transatlantic jurisdictions when configuring multi-origin sourcing strategies and plant certification timelines.
Market Dynamics
Consolidation among food service distributors is compressing supplier margins while simultaneously demanding extended shelf-life guarantees that strain fresh cheese production economics.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain retrofit mandates are accelerating investment in energy-efficient dairy storage infrastructure across member states, indirectly expanding capacity for temperature-sensitive white cheese categories.
- Quick-service restaurant chains:These buyers are standardizing crumbled and shredded formats for kitchen workflow efficiency, creating pull-through demand for processed white cheese variants.
- Mediterranean diet associations:Established health positioning of feta and ricotta in bakery and prepared meal applications sustains baseline consumption in European and North American retail channels.
Market Restraints
- Milk price volatility:Input cost swings in regional dairy markets compress margin predictability for processors lacking cooperative-backed supply agreements.
- Supply concentration in Mediterranean basins:Feta production gravity in Greece and Bulgaria creates geographic vulnerability to climate-driven milk yield fluctuations.
- Rennet and starter culture dependencies:Technical limitations in non-animal coagulant performance for traditional texture profiles constrain clean-label reformulation timelines.
Strategic Opportunities
- German food manufacturing corridor:Industrial cheese demand from prepared meal and sauce processors in Bavaria and Baden-Württemberg offers volume expansion potential for queso blanco suppliers.
- Plant-based hybrid positioning:Technology convergence between precision fermentation and conventional dairy processing enables novel white cheese analogues targeting flexitarian consumers.
- E-commerce cold-chain expansion:Direct-to-consumer refrigerated logistics platforms are opening bypass channels around consolidated food service distribution.
Industry Challenges
- HACCP certification timelines:Extended approval cycles for EU EFSA pathogen compliance delay new product introductions and plant expansions.
- Refrigerated fleet reconfiguration:Capex intensity for EU F-Gas-compliant transport equipment strains mid-scale distributors' balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Cheese Market |
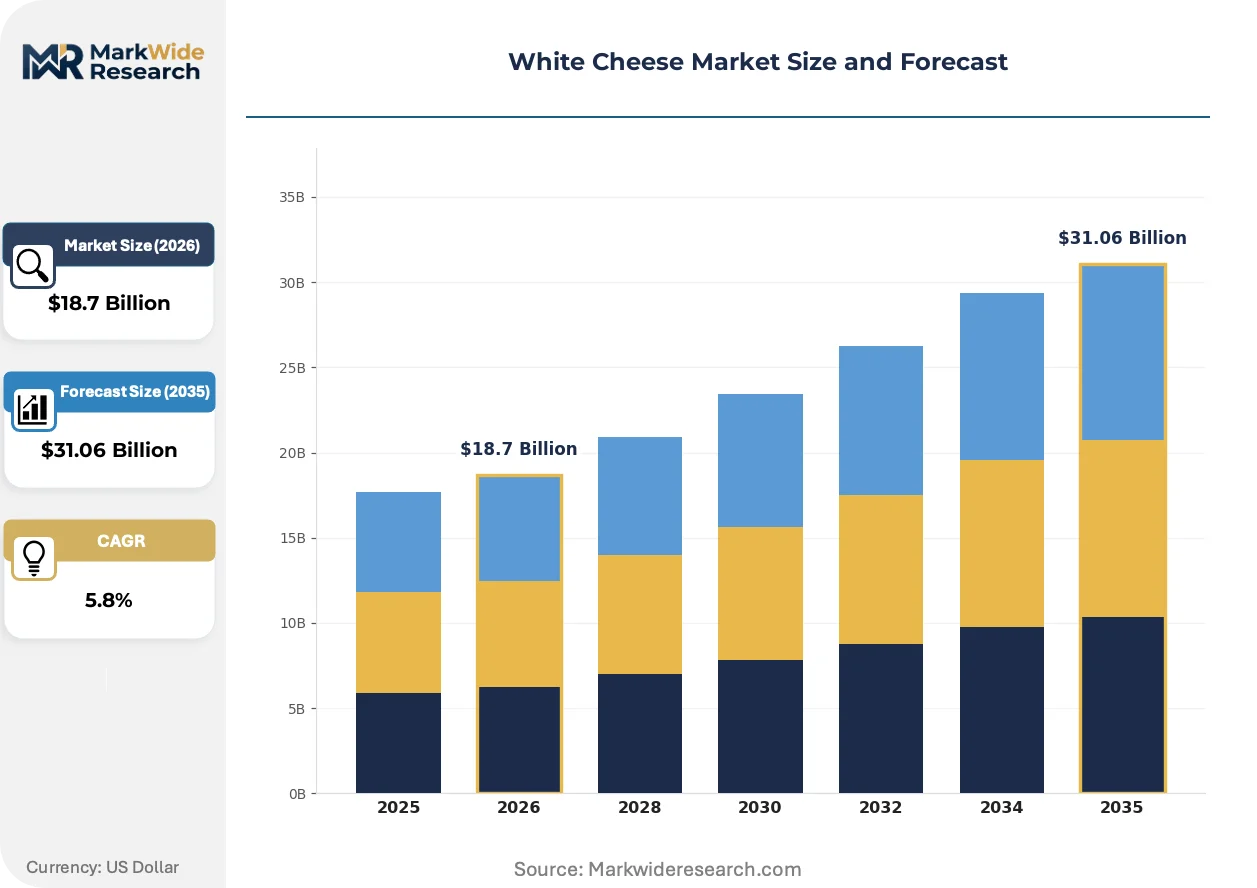
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Feta, Cottage Cheese, Queso Blanco, Ricotta End User: Household, Food Service, Retailers, Food Manufacturers Packaging Type: Blocks, Slices, Shredded, Crumbled Distribution Channel: Supermarkets, Online Retail, Wholesalers, Specialty Stores |
| Companies Covered | FrieslandCampina, Lactalis Ingredients, The Kraft Heinz Company, SAVENCIA SA, Dairy Farmers of America, Inc., Fonterra Co-operative Group Limited, Saputo Inc., Leprino Foods Company, Arla Foods amba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Cheese Market Evolving Landscape
Active culture stabilization technologies and alternative protein integration are reshaping formulation strategies across fresh cheese categories. Processors are racing to align product development with tightening cold-chain energy standards and evolving food service operational requirements.
Membrane filtration for whey protein concentration is expanding into standard white cheese production workflows. Mid-scale processors in the Netherlands and Denmark are adopting these systems to recover value-added ingredients from acid whey streams. This technology is expanding into cost structures previously reserved for commodity mozzarella operations, compressing the equipment payback period for fresh cheese specialists.
The EU F-Gas Regulation is mandating phasedown of hydrofluorocarbon refrigerants in dairy cold storage facilities. Industrial operators face retrofit deadlines that accelerate capital replacement cycles for aging compression equipment. German and French processors are most exposed given their concentration of temperature-controlled fresh cheese maturation and distribution infrastructure.
Food service buyers are consolidating procurement under fewer national distributors with dedicated dairy logistics capabilities. Independent restaurant operators and regional chains are losing direct supplier relationships as volume thresholds rise. This concentration is most visible in the United Kingdom and Spain, where distributor mergers have reduced viable supply channels by half within five years.
White Cheese Market Segmentation
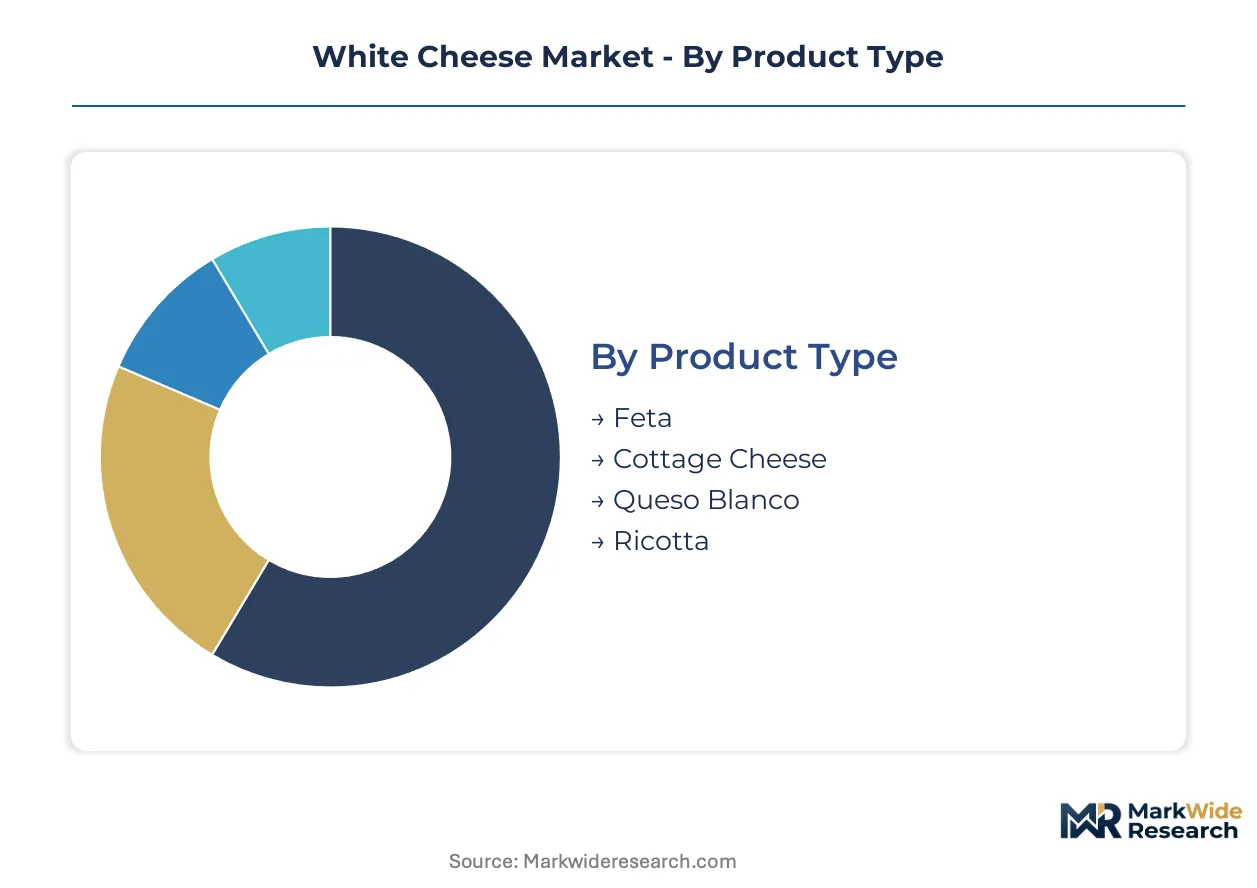
White cheese segmentation reveals divergent margin structures across freshness-dependent categories. Product format and channel configuration determine cold-chain investment intensity and shelf-life economics for processors.
Product Type:
Customization spans from protected-origin specifications to industrial melting-grade formulations across this category.
- Feta:Brined curd cheese with minimum 70% moisture content and protected designation of origin requirements in Greece and Bulgaria. Demand concentrates in German and French retail channels where Mediterranean diet positioning commands shelf-space premiums. PDO compliance burdens constrain new entrant expansion timelines.
- Cottage Cheese:Direct-acidified fresh curd with granular texture and high protein retention. North American retail dominates volume consumption, though thinner margins limit processor investment in flavor innovation. Clean-label reformulation pressures strain starter culture sourcing.
- Queso Blanco:Heat-resistant melting cheese with acid coagulation preventing string formation. Mexican and Tex-Mex restaurant chains standardize this format for kitchen consistency. Clean-label positioning drives fastest expansion among food manufacturers.
- Ricotta:Whey-recovery cheese with delicate curd structure from secondary heat precipitation. Italian bakery applications and prepared meal processors sustain baseline demand. Artisan positioning in specialty retail competes with industrial whey concentration economics.
Leading the category by volume: Feta. Growing fastest: Queso Blanco.
End User:
Volume concentration versus margin capture varies sharply across buyer types in this category.
- Household:Supermarket retail purchasers seeking convenience formats and extended shelf-life claims. Private-label penetration compresses branded premium realization in European markets.
- Food Service:Restaurant chains and institutional caterers consolidating procurement under national distributors with dedicated dairy logistics. Workflow-optimized formats command specification premiums.
- Retailers:Supermarket and hypermarket operators controlling shelf-space allocation and promotional calendars. Direct supplier relationships fragment as volume thresholds rise.
- Food Manufacturers:Prepared meal, sauce, and bakery ingredient processors in Germany's Bavaria and Baden-Württemberg corridor driving industrial queso blanco demand. Clean-label melting requirements reshape formulation specifications.
Food service buyers capture fastest volume growth. Household retail maintains largest absolute consumption base.
Packaging Type:
Processing intensity and cold-chain requirements differentiate format economics in this category.
- Blocks:Traditional bulk format for food service portioning and retail deli counters. Greek feta exports dominate this configuration with brine-filled modified atmosphere packaging.
- Slices:Portion-controlled formats for sandwich preparation and institutional meal service. Higher packaging material costs offset labor savings in quick-service applications.
- Shredded:Pre-processed formats tailored to pizza and prepared meal manufacturing workflows. Anti-caking agent regulations constrain clean-label positioning.
- Crumbled:Salad and topping applications driving premium realization in North American retail. Saputo specializes in this format for quick-service kitchen efficiency.
Blocks lead by tonnage. Crumbled formats expand most quickly in premium retail.
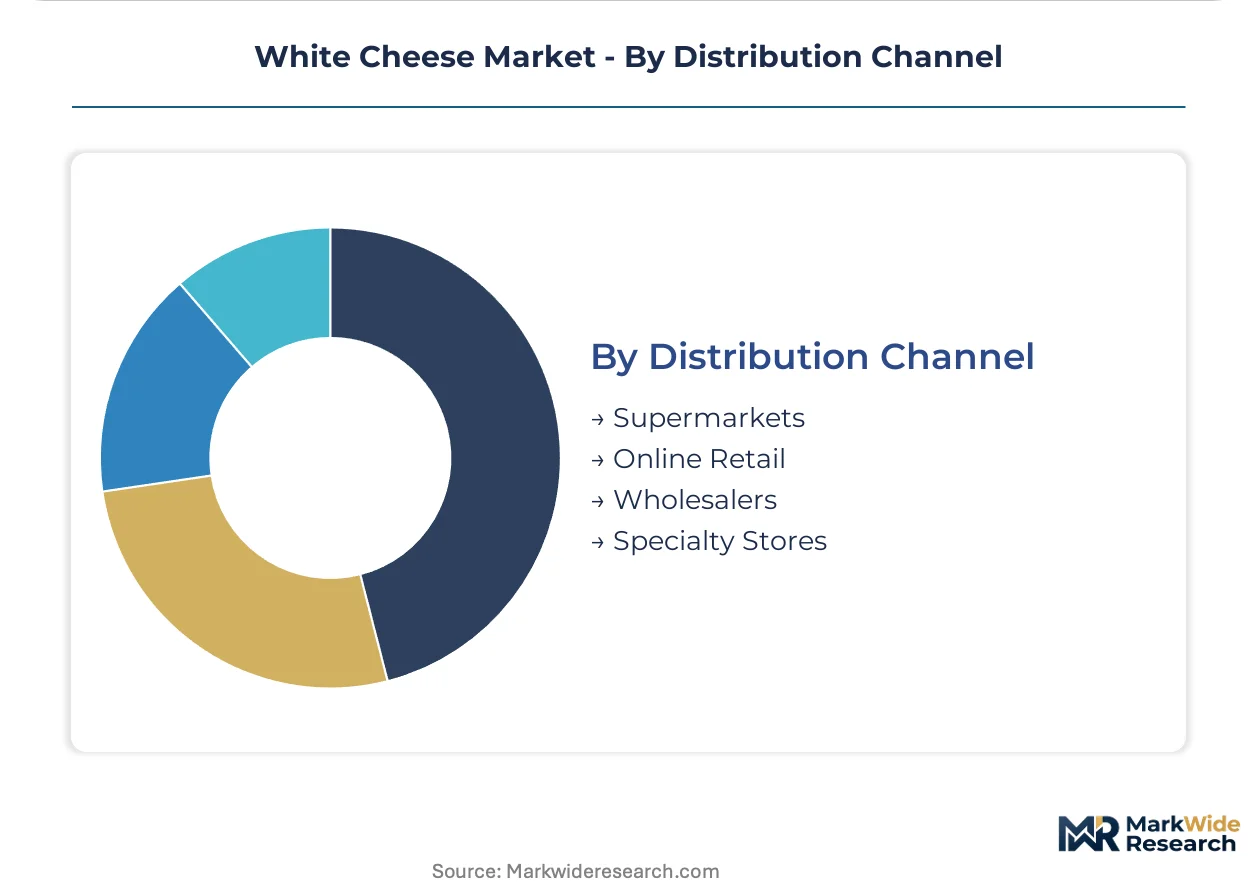
Distribution Channel:
Cold-chain reliability and buyer consolidation patterns reshape channel viability in this category.
- Supermarkets:Temperature-controlled dairy cases with high-frequency replenishment requirements. UK and Spanish market concentration among fewer national distributors halves viable supply channels.
- Online Retail:Direct-to-consumer refrigerated logistics platforms bypassing consolidated food service distribution. EU F-Gas Regulation compliance costs strain mid-scale operator balance sheets.
- Wholesalers:Food service and institutional volume aggregation with dedicated dairy logistics capabilities. Margin compression accompanies procurement consolidation.
- Specialty Stores:Artisan positioning and protected-origin authentication for Mediterranean import varieties. Limited scale constrains processor investment prioritization.
Supermarkets dominate volume throughput. Online retail channels gain share fastest in urban cold-chain expansion zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates industrial white cheese demand through its prepared meal manufacturing corridor, while procurement consolidation across Europe and North America reshapes supplier access patterns.
Germany
Food manufacturers in Bavaria and Baden-Württemberg drive queso blanco volume for sauce and ready-meal applications. EU F-Gas Regulation retrofit deadlines compress cold-chain investment timelines for temperature-sensitive fresh cheese storage. Stuttgart and Munich anchor the highest concentration of industrial dairy processing capacity in Central Europe.
United States
Quick-service restaurant chains standardize crumbled and shredded formats for kitchen workflow efficiency, pulling processed white cheese demand through national distributors. FDA pasteurization requirements shape import eligibility and domestic plant certification burdens. Wisconsin and California dairy cooperatives supply the bulk of domestic ricotta and cottage cheese volume.
Greece
Protected designation of origin feta production maintains premium positioning in German and French retail channels despite climate-driven milk yield volatility. EFSA pathogen limits and labeling claims enforcement constrains new entrant expansion timelines. Thessaly and Central Macedonia host the densest concentration of PDO-compliant brined curd operations.
United Kingdom
Food service distributor mergers have halved viable supply channels within five years, compressing supplier margins while demanding extended shelf-life guarantees. UK cold-chain operators face parallel EU F-Gas Regulation compliance costs for refrigerated fleet reconfiguration. London and the Southeast concentrate quick-service procurement consolidation.
Canada
Saputo anchors North American crumbled format specialization for quick-service kitchen efficiency, competing against US-based shredded and sliced product lines. Provincial dairy marketing boards regulate milk pricing and quota allocation for fresh cheese processors. Quebec and Ontario host the primary concentration of Canadian white cheese manufacturing infrastructure.
White Cheese Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue plant-based hybrid positioning and precision fermentation alternatives. The vendor base stratifies across cooperative-backed dairy processors, multinational ingredient specialists, and regional fresh cheese fabricators. Three archetypes dominate: backward-integrated cooperatives with captive milk supply, format-specialist processors targeting food service workflow optimization, and diversified dairy conglomerates leveraging whey recovery networks. Competitive moves concentrate on M&A for distributor relationships and cold-chain capacity expansion for temperature-sensitive categories.
Among cooperative-structured processors, FrieslandCampina and Fonterra exemplify the backward-integrated archetype leveraging member-farmer milk pools for supply security. Lactalis Ingredients occupies a position within the ingredient-specialist tier, representing multinational scale advantages in whey processing and long-term contract negotiation with consolidated buyers.
| Leading Market Players |
|---|
| FrieslandCampina |
| Lactalis Ingredients |
| The Kraft Heinz Company |
| SAVENCIA SA |
| Dairy Farmers of America, Inc. |
| Fonterra Co-operative Group Limited |
| Saputo Inc. |
| Leprino Foods Company |
| Arla Foods amba |
| Others |
Value Network & Pricing Analysis
PDO certification ladders bifurcate the white cheese category into premium protected-origin tiers and commodity industrial grades, with this divergence manifesting in both pricing power and supply chain configuration. Greek feta commands shelf-space premiums in German retail through EFSA-enforced origin guarantees, while queso blanco suppliers compete on volume scale for food manufacturing contracts in Bavaria.
Pricing Analysis
Volume-driven cottage cheese in North American retail trades on thin margins, while PDO feta and artisan ricotta capture premium realization through protected-origin scarcity. Pricing stratifies across protected-origin, standard-grade, and industrial-melting tiers with differentiation anchored in EFSA certification status and cooperative-backed milk supply security. Pricing pressure stems from food service distributor consolidation demanding extended shelf-life guarantees without price accommodation. Quick-service chains show lowest price sensitivity for workflow-optimized crumbled formats, while private-label household buyers drive hardest bargain.
Supply Chain Analysis
Reverse-logistics for brine recovery and whey concentration flows shapes cost structures for mid-scale processors adopting membrane filtration. Milk supply concentrates in Greece, Bulgaria, and Germany, with raw material dependencies centering on regional dairy cooperatives, animal rennet, and starter culture strains. Single-source vulnerability runs through Mediterranean basin feta production exposed to climate-driven milk yield fluctuations. Distribution runs through consolidated national food service wholesalers with dedicated cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The white cheese market sits in a technology-transition phase as precision fermentation and membrane filtration displace conventional whey recovery and animal-derived coagulant systems. Active culture stabilization and alternative protein integration are replacing legacy acidification methods.
For Market Incumbents: To counter precision fermentation entrants targeting flexitarian positioning, incumbents should deepen backward integration into regional milk collection cooperatives for supply security and accelerate EFSA certification investment to extend shelf-life guarantees for consolidated food service buyers. Cold-chain capacity expansion in Germany's manufacturing corridor offers defensive positioning against queso blanco commoditization.
For New Entrants and Emerging Players: Enter via plant-based hybrid positioning targeting German prepared meal manufacturers seeking clean-label melting agents, or through direct-to-consumer refrigerated logistics bypassing consolidated UK and Spanish distributor channels. E-commerce cold-chain expansion in urban European zones presents the most penetrable entry vector with workflow-optimized format specialization as the go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with format-specialist processors possessing captive dairy logistics given EU F-Gas Regulation retrofit catalysts accelerating industry consolidation. Long-term viability favors operators with cooperative-backed milk pools and membrane filtration capabilities. Monitor HACCP certification timeline compression and distributor merger completion rates as inflection indicators for valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milk Cooperatives | FrieslandCampina secures supply security through member-farmer pools against price volatility. |
| Membrane Filtration Adoption | Dutch and Danish processors recover value-added whey ingredients from acid streams. |
| Cold-Chain Retrofit Compliance | German and French operators face EU F-Gas Regulation deadlines for refrigeration equipment. |
| Format Specialization for Food Service | Saputo captures quick-service workflow efficiency through crumbled and shredded positioning. |
| Direct-to-Consumer Platform Launch | E-commerce refrigerated logistics bypasses consolidated UK and Spanish distributor channels. |
Research Methodology
Multi-period observation of milk price volatility, distributor consolidation rates, and EU F-Gas Regulation compliance timelines anchored the trend analysis, supplemented by interviews with dairy processing plant managers, food service procurement directors at national distributors, cooperative supply planners, and EFSA regulatory affairs specialists. Secondary validation drew from EU dairy trade statistics, EFSA pathogen limit enforcement records, SEC filings of listed processors, and cold-chain equipment manufacturer order backlogs. Bottom-up volume modeling triangulated against top-down category spend analysis.
Segment-weighting applied product type, end user channel, and packaging format dimensions across the projection horizon, with additional weighting for PDO certification status and cooperative supply structure. CAGRs derived from trend extrapolation of historical volume trajectories adjusted for regulatory compliance cost pass-through and food service buyer concentration effects. Forecast inputs incorporated membrane filtration adoption curves and precision fermentation technology readiness levels.
Revisions become necessary when EU F-Gas Regulation enforcement intensity shifts, Mediterranean climate patterns disrupt milk yields, or precision fermentation achieves cost parity with conventional dairy processing. Practitioners should monitor HACCP certification backlog lengths, distributor merger regulatory approvals, and alternative coagulant performance benchmarks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Solidified Yogurt Market
Dairy Products
Textured Butter Market
Dairy Products
Fermented Milk Products Market
Dairy Products
Dairy Products Market
Dairy Products
Europe Cheese Market
Dairy Products
Fluid Milk Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
United States Dairy Market
Dairy Products
Low Fat Butter Market
Dairy Products
Reduced Fat Cheeses Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
A2 Protein Milk Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Europe Yogurt Market
Dairy Products
A2 Milk Market