
 North America Casein Market | 2026-2036
North America Casein Market Size, Share, and Industry Trends Forecast 2026-2036
North America Casein Market Intelligence
Plant-based protein isolates is rebalancing conventional casein economics in select beverage applications, though dairy-derived proteins retain functional advantages in texture and amino acid completeness. Fonterra Co-operative Group Limited leverages its New Zealand-origin supply chain to anchor premium caseinate positioning across U.S. food manufacturing accounts. Glanbia plc sustains R&D intensity in micellar casein extraction, while Lactalis Ingredients competes through backward integration into fluid milk collection networks in Wisconsin and California.
Casein denotes the family of phosphoproteins comprising approximately 80 percent of bovine milk protein, precipitated through acidification or enzymatic rennet coagulation at pH 4.6, then washed and dried into industrial powders with gelation, emulsification, and water-binding functionalities that serve formulated foods, nutritional products, and adhesive binders. Acid casein dominates volume flows into processed cheese analogs and technical applications where emulsifying salts enable rehydration, while caseinate variants command margin pools in protein supplements and clinical nutrition where solubility and digestibility specifications tighten. Casein phosphopeptides occupy a nascent but expanding position in mineral delivery systems and functional food positioning.
The U.S. FDA oversees dairy protein GRAS determinations and labeling standards under the Federal Food, Drug, and Cosmetic Act, while USDA's Agricultural Marketing Service administers quality grading protocols that influence export eligibility and domestic procurement premiums. Health Canada's Food Directorate and CFIA establish parallel standards for cross-border trade, with California's state-level dairy quota system and Wisconsin's DATCP enforcement adding operational complexity for processors spanning multiple jurisdictions. Stakeholders must monitor how evolving clean-label thresholds and protein content verification methods reshape specification requirements across pharmaceutical and sports nutrition contracts.
Market Dynamics
Sports nutrition formulators are pulling casein procurement toward micellar variants with extended amino acid release profiles, compressing traditional acid casein margins in commodity cheese analog applications. This demand rotation is restructuring processor capital allocation across the U.S. Midwest dairy belt.
Growth Catalysts
- FDA GRAS pathway streamlining:The U.S. FDA's evolving notification procedures for dairy-derived ingredients are accelerating product clearance timelines for novel caseinate formulations entering sports nutrition and clinical segments.
- Fractionation capacity clustering:Whey and casein separation infrastructure concentrates near cheese production facilities in Wisconsin and California, reducing logistics costs for industrial buyers sourcing technical-grade acid casein.
- Casein phosphopeptide mineral delivery:Functional food developers are incorporating these bioactive peptides into fortified beverages and supplements targeting calcium and phosphorus bioavailability enhancement.
Market Restraints
- Fluid milk input cost volatility:California's state-level dairy quota system and federal milk marketing order pricing create margin unpredictability for casein processors dependent on domestic raw material flows.
- Plant protein substitution pressure:Pea and fava bean isolates are capturing share in ready-to-drink beverage applications where emulsification requirements are less stringent than in dairy-derived systems.
- Cross-border regulatory friction:Health Canada's Food Directorate and CFIA establish parallel standards that complicate specification alignment for U.S. processors exporting caseinates into Canadian nutritional markets.
Strategic Opportunities
- Underpenetrated Mexican nutritional market:Clinical nutrition and infant formula manufacturers in Mexico present procurement expansion potential for U.S. caseinate exporters with established cold-chain distribution.
- Clean-label threshold evolution:Processor investment in phosphopeptide extraction and native micellar casein isolation aligns with emerging buyer specifications for minimally modified protein ingredients.
- Direct-to-manufacturer channel development:Sports nutrition brands are bypassing traditional ingredient distributors to establish captive supply relationships with fractionation facilities in the Upper Midwest.
Industry Challenges
- Specialized extraction talent scarcity:Micellar casein isolation requires protein chemistry expertise that outpaces supply from U.S. food science and dairy technology programs.
- Multi-jurisdictional compliance complexity:Processors spanning Wisconsin DATCP enforcement, California quota administration, and Canadian import standards face specification reconciliation costs that strain quality assurance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Casein Market |
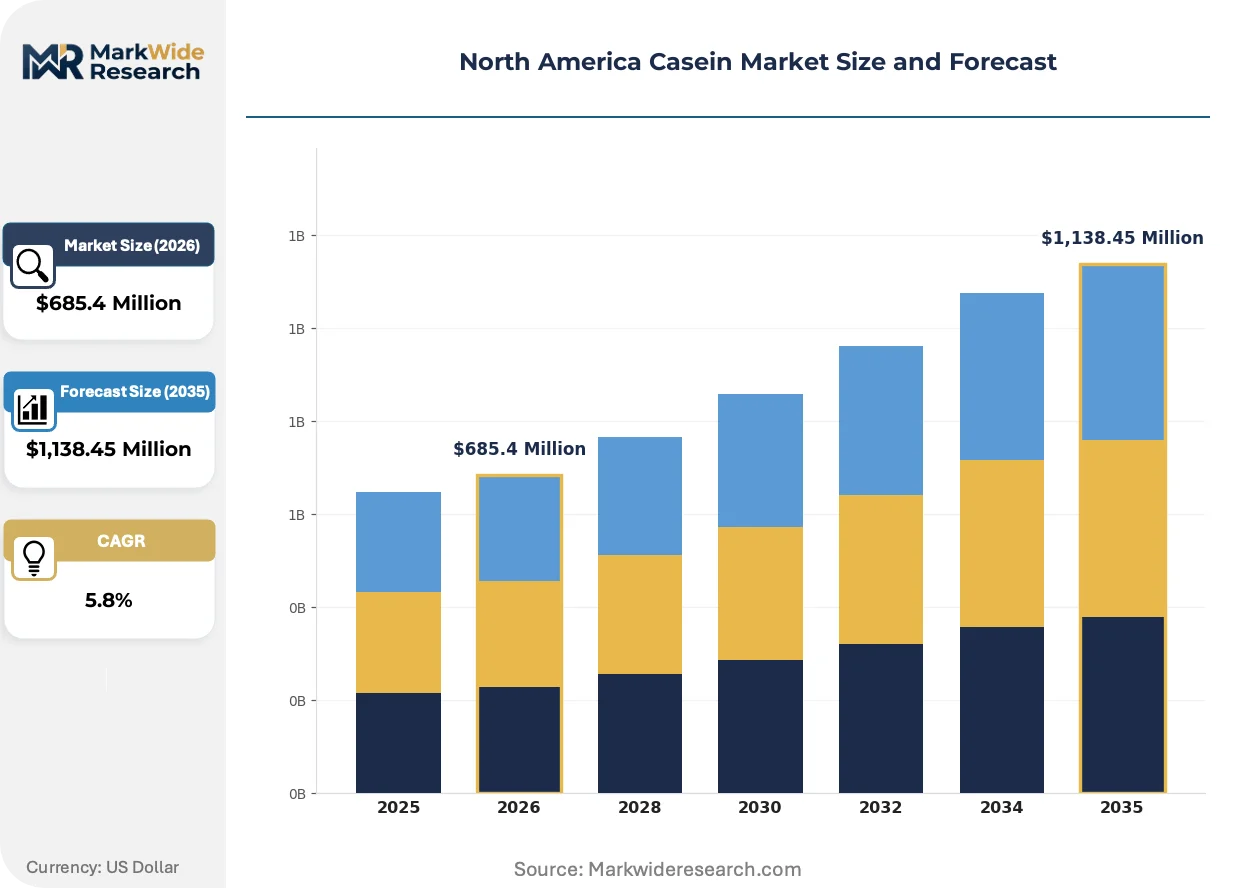
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulated Casein, Caseinate, Casein Phosphopeptides, Acid Casein Application: Dairy Products, Food & Beverages, Protein Supplements, Pharmaceutical End User: Retail Consumers, Manufacturers, Food Service, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | AMCO Proteins, Arla Foods Ingredients Group P/S, Erie Foods International Inc., Farbest-Tallman Foods Corporation, Fonterra Co-operative Group Limited, FrieslandCampina Ingredients, Glanbia plc, Idaho Milk Products, Lactalis Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Casein Market Strategic Shifts & Innovations
Membrane filtration advances and enzymatic processing refinements are fragmenting traditional casein product categories into application-specific variants. These technical developments are compressing the gap between commodity and specialty grades.
Cross-flow microfiltration technology is modularizing micellar casein production into scalable unit operations that processors can configure by protein concentration and fat retention specifications. Nutritional product manufacturers in the U.S. are adopting these modular systems to reduce minimum order quantities and accelerate formulation iteration cycles. This technical shift is modularizing supply relationships between fractionators and mid-sized sports nutrition brands that previously relied on standardized commodity grades.
The U.S. FDA's updated GRAS notification framework for dairy-derived proteins is compressing pre-market clearance timelines while tightening documentation requirements for novel extraction processes. Caseinate processors must now submit expanded safety and compositional data for modified phosphoprotein structures entering clinical nutrition applications. Sports nutrition and medical food segments are responding by front-loading regulatory consulting expenditure into product development budgets rather than post-formulation compliance phases.
Ingredient sourcing contracts are shortening from multi-year commitments to 12-18 month frameworks with price renegotiation clauses tied to Class III milk futures. Mid-sized sports nutrition brands in the U.S. are displacing traditional distributor relationships with direct procurement from Upper Midwest fractionators to capture transparency on extraction methods and origin documentation. This behavioral shift is most visible in the protein powder and ready-to-drink categories where clean-label positioning requires traceability to specific dairy cooperative sources.
North America Casein Market Segmentation
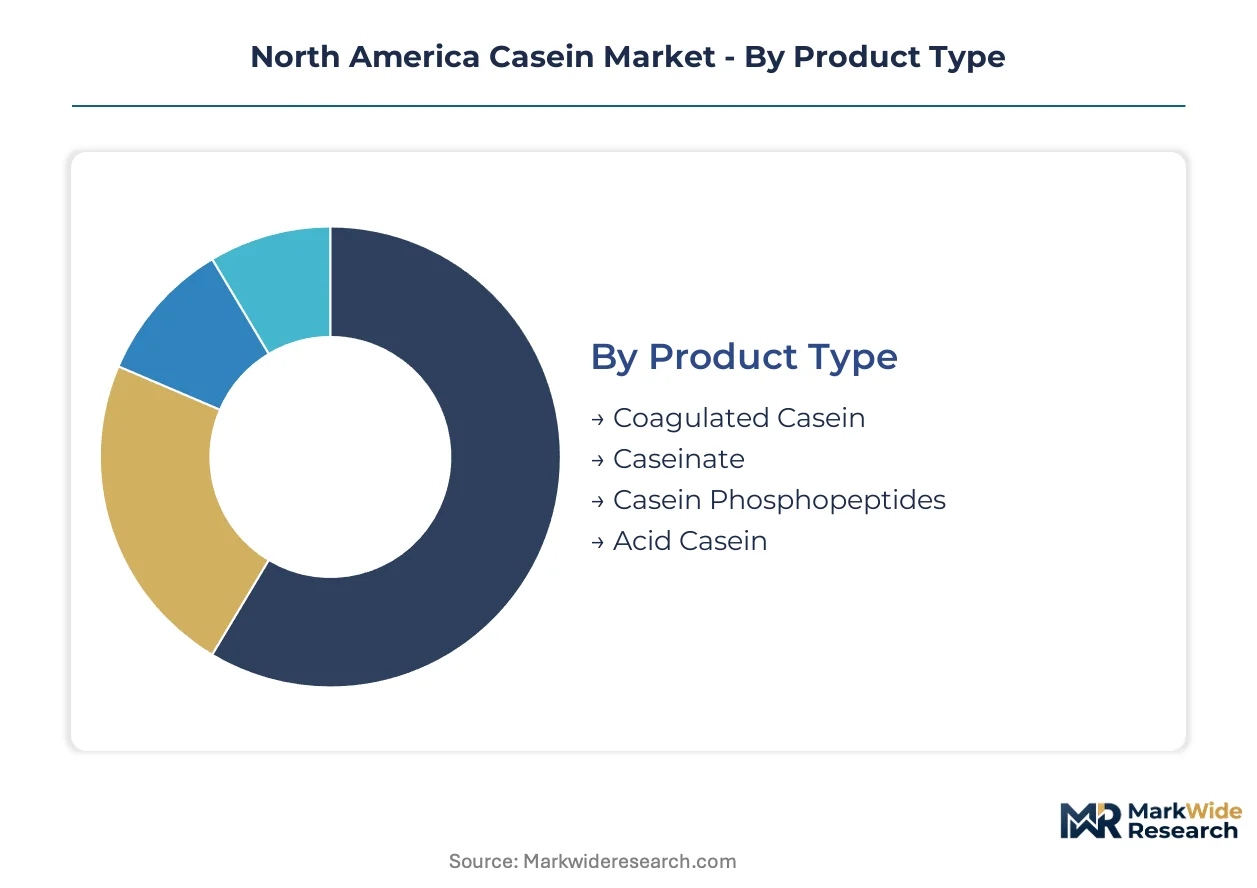
Casein procurement patterns diverge sharply across product specifications and end-use requirements. Sports nutrition formulators prioritize solubility and digestibility metrics that commodity cheese processors ignore. Understanding these segment boundaries clarifies why micellar casein commands premium positioning while acid casein flows through bulk industrial channels.
Product Type:
Fractionation technology and protein structural integrity define commercial value tiers across casein variants. Membrane filtration capabilities and enzymatic processing sophistication separate specialty grades from commodity powders.
- Coagulated Casein:Rennet-precipitated phosphoprotein with intact micellar structure retains superior gelation and water-binding functionality. Wisconsin cheese manufacturers source this grade for processed cheese analogs where texture consistency specifications tighten. Demand concentrates in the Upper Midwest dairy belt near fractionation facilities that minimize protein denaturation during transport.
- Caseinate:Alkali-treated derivatives achieve neutral pH solubility essential for protein fortification in beverages and clinical nutrition. Sports nutrition brands in the U.S. bypass distributors to establish direct procurement relationships with Upper Midwest fractionators for traceability documentation. This segment captures margin pools where amino acid completeness and sustained-release kinetics justify specification premiums.
- Casein Phosphopeptides:Bioactive mineral-carrying fragments from enzymatic hydrolysis.
- Acid Casein:Isoelectric precipitation at pH 4.6 yields technical-grade powders for adhesive and coating applications.
Mature deployment sits with acid casein in commodity industrial channels. Newer deployment is concentrated in caseinate variants for nutritional positioning.
Application:
Functional requirements and regulatory scrutiny intensity vary dramatically across downstream use cases. Pharmaceutical and clinical nutrition contracts impose documentation burdens that commodity food applications escape.
- Dairy Products:Processed cheese analogs and cultured dairy formulations leverage casein emulsification and melt characteristics. Midwest dairy processors integrate backward into fluid milk collection networks to secure input cost stability for this high-volume segment. Specification alignment with USDA quality grading protocols determines export eligibility into Canadian markets.
- Protein Supplements:Micellar casein isolation delivers extended amino acid release profiles that differentiate sports nutrition positioning. FDA GRAS notification pathway streamlining accelerates product clearance timelines for novel formulations targeting overnight recovery positioning. This application segment climbs the fastest as mid-sized brands displace standardized commodity grades with modular membrane filtration configurations.
- Food & Beverages:Fortification and texture modification in processed foods.
- Pharmaceutical:Excipient and active ingredient applications in drug delivery systems.
Established volume flows through dairy product channels. Steepest expansion trajectory appears in protein supplements as direct-to-manufacturer procurement displaces traditional distribution.
End User:
Procurement sophistication and specification granularity separate institutional buyers from consumer-facing channels. Healthcare and manufacturing accounts demand batch-level documentation that retail channels rarely require.
- Manufacturers:Formulated food and nutritional product companies specify protein concentration, fat retention, and mineral content with tight tolerances. Direct contracts with fractionators enable cold-chain transparency and origin verification for clean-label positioning. California and Wisconsin processors compete through backward integration into fluid milk collection networks.
- Healthcare:Clinical nutrition and medical food applications impose stringent microbiological and compositional standards. Health Canada's Food Directorate and CFIA parallel standards complicate specification alignment for U.S. processors exporting into Canadian institutional markets. This end user segment maintains the most rigorous documentation requirements.
- Retail Consumers:Individual purchasers through e-commerce and brick-and-mortar channels.
- Food Service:Restaurant and institutional catering operations sourcing ingredient inputs.
Volume concentration remains with manufacturers. Specification intensity peaks in healthcare procurement where regulatory compliance costs strain quality assurance teams.
Distribution Channel:
Channel selection reflects buyer scale, documentation requirements, and price transparency preferences. Large manufacturers bypass intermediaries while smaller accounts rely on distributor inventory buffers.
- Wholesale:Bulk procurement corridors serving industrial processors and large-scale food manufacturers. Wisconsin and California fractionation capacity clusters reduce logistics costs for technical-grade acid casein moving through this channel. Contract structures now incorporate 12-18 month frameworks with price renegotiation clauses tied to Class III milk futures.
- Online Retail:Direct-to-consumer protein powder and supplement sales enable brand-controlled positioning and origin storytelling. Sports nutrition brands leverage this channel to communicate specific dairy cooperative sourcing and extraction method transparency. E-commerce penetration is expanding most quickly in premium micellar casein variants.
- Supermarkets:Mass retail shelf placement for consumer packaged goods.
- Specialty Stores:Health food and fitness-focused retail environments.
Traditional volume flows through wholesale corridors. Channel innovation concentrates in online retail where direct relationships enable specification differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement intensity concentrates in the Upper Midwest dairy belt where fractionation infrastructure clusters near cheese production facilities. Wisconsin and California processors anchor supply capacity for acid casein and caseinate variants. Cross-border trade flows between the three North American countries shape specification alignment and regulatory compliance burdens.
United States
Sports nutrition manufacturers in the Upper Midwest drive micellar casein procurement for sustained-release protein formulations. The FDA's evolving GRAS notification pathways streamline product clearance timelines for novel caseinate formulations. Wisconsin's DATCP enforcement and California's state-level dairy quota system create multi-jurisdictional compliance complexity for processors operating across both states.
Canada
Health Canada's Food Directorate and CFIA establish parallel standards that complicate specification alignment for U.S. exporters entering Canadian nutritional markets. Clinical nutrition and medical food applications impose stringent microbiological documentation requirements. Ontario and Quebec dairy processors maintain quality grading protocols that influence cross-border procurement premiums.
Mexico
Clinical nutrition and infant formula manufacturers present procurement expansion potential for U.S. caseinate exporters with established cold-chain distribution. The underpenetrated nutritional market attracts direct-to-manufacturer channel development from fractionators seeking geographic diversification. Mexico City Metro and Nuevo León anchor demand concentration for protein fortification applications.
North America Casein Market Key Industry Players
Backward integration into fluid milk collection networks dominates the current landscape as processors seek input cost stability. The vendor base spans multinational dairy cooperatives, specialized fractionators, and regional ingredient suppliers. Three archetypes define competitive positioning: New Zealand-origin supply chain anchors, Midwest dairy belt integrated processors, and European dairy cooperative networks. M&A activity and direct-to-manufacturer channel development represent the dominant competitive moves reshaping procurement relationships.
Among the integrated processor tier, Fonterra Co-operative Group Limited and Glanbia plc exemplify supply chain anchoring strategies, while Lactalis Ingredients occupies a position representing European dairy cooperative penetration into North American accounts. These three entities illustrate how geographic origin and backward integration depth differentiate competitive positioning across sports nutrition and clinical nutrition procurement channels.
| Leading Market Players |
|---|
| AMCO Proteins |
| Arla Foods Ingredients Group P/S |
| Erie Foods International Inc. |
| Farbest-Tallman Foods Corporation |
| Fonterra Co-operative Group Limited |
| FrieslandCampina Ingredients |
| Glanbia plc |
| Idaho Milk Products |
| Lactalis Ingredients |
| Others |
Cost & Logistics Intelligence
California's state-level dairy quota system gates qualified supply for premium-tier caseinate procurement while compressing margin pools for processors unable to document origin traceability. Buyers demanding clean-label positioning now face tiered access where sustainability verification and cooperative sourcing credentials determine pricing power allocation across the U.S. Midwest dairy belt.
Pricing Analysis
Volume-margin splits separate commodity acid casein flows from micellar casein premiums, with contract-based long-term offtake dominating wholesale corridors and spot-market flexibility commanding standard-tier positioning. Price differentiation hinges on protein concentration certification and cold-chain documentation depth, with FDA GRAS notification status now a threshold qualifier for clinical nutrition premiums. Cost compression in acid casein intensifies because plant protein isolates capture ready-to-drink beverage share, while sports nutrition brands exhibit least price sensitivity where sustained-release kinetics justify specification premiums.
Supply Chain Analysis
Dual-sourcing mandates from major sports nutrition brands now require fractionator qualification across both Wisconsin and California processing networks, fragmenting single-state dependency. Raw material flows draw from fluid milk collection networks in the Upper Midwest, alkali reagent supply chains anchored in Gulf Coast chemical corridors, and membrane filtration equipment sourced from German and Japanese manufacturers. Single-source vulnerability concentrates in micellar casein isolation capacity where specialized protein chemistry expertise outpaces graduate program output. Distribution runs through direct-to-manufacturer channels displacing traditional ingredient distributors for traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The U.S. FDA's evolving GRAS notification framework constructs a cost-of-compliance moat where documentation-intensive clearance timelines favor incumbent processors with dedicated regulatory affairs infrastructure over undercapitalized entrants.
For Market Incumbents: Hedge against plant protein substitution by deepening backward integration into fluid milk collection networks in Wisconsin and California, securing input cost stability that commodity casein processors cannot match. Reinforce micellar casein extraction capacity through captive R&D investment in membrane filtration modularization, defending margin pools threatened by pea and fava bean isolate penetration in beverage applications. For New Entrants and Emerging Players: Launch via direct-to-manufacturer channel development targeting mid-sized sports nutrition brands in the Upper Midwest, bypassing distributor relationships that incumbent fractionators dominate. Mexico's clinical nutrition and infant formula manufacturing corridor presents the most penetrable white-space geography, with cold-chain distribution partnerships as the critical go-to-market angle for U.S. caseinate exporters. For Investors and Strategic Acquirers: FDA GRAS notification backlog clearance velocity is the leading indicator that regulatory consulting expenditure front-loading is separating viable acquisition targets from compliance-lagged processors. Long-term viability over the coming decade rests on fractionators with modular membrane filtration capabilities and established Mexican distribution networks. Watch for micellar casein isolation talent scarcity signals as the inflection point where specialized protein chemistry expertise premiums reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluid Milk Collection | Wisconsin and California captive supply networks reduce California quota system margin volatility for caseinate processors. |
| Modular Membrane Filtration Deployment | Scalable unit operations enable mid-sized sports nutrition brands to reduce minimum order quantities and accelerate formulation cycles. |
| Direct-to-Manufacturer Channel Development | Bypassing traditional distributors captures transparency on extraction methods and origin documentation for clean-label positioning. |
| Casein Phosphopeptide Extraction Investment | Functional food fortification applications targeting calcium bioavailability expand addressable market beyond commodity protein powders. |
| Mexican Cold-Chain Distribution Partnership | Clinical nutrition and infant formula manufacturers in Mexico City Metro and Nuevo León anchor geographic diversification for U.S. exporters. |
Research Approach
Multi-period observation of FDA GRAS notification clearance timelines, Class III milk futures volatility patterns, and micellar casein procurement contract structures anchored the trend analysis, supplemented by interviews with dairy cooperative procurement directors, sports nutrition formulators, membrane filtration equipment specialists, and clinical nutrition regulatory consultants. Secondary validation drew from USDA Agricultural Marketing Service quality grading protocols, Health Canada Food Directorate guidance documents, Wisconsin DATCP enforcement records, and SEC filings from publicly traded dairy processors. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the North American dairy protein complex.
Input-output matrix framing connected fluid milk supply volumes through fractionation capacity utilization rates to caseinate and acid casein price formation mechanisms across the projection horizon. Segmentation dimensions modeled encompassed product type variants, application intensity tiers, end-user procurement sophistication levels, and distribution channel transparency requirements. CAGRs were derived from regression analysis against historical dairy protein demand elasticity and forward-looking sports nutrition formulation trends. Industry-specific forecast inputs included California dairy quota administration changes and cross-border regulatory friction indices between U.S. and Canadian nutritional markets.
The model assumes a particular technology adoption path for cross-flow microfiltration modularization; alternative pathways for enzymatic processing refinements would alter the outlook for micellar casein production economics. Forecasts reflect assumptions regarding sustained FDA GRAS pathway streamlining and stable federal milk marketing order pricing structures. Deviation in plant protein isolate functionality improvements or Mexican peso-denominated procurement contract adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Camel Dairy Market
Dairy Products
Citrus Yogurt Market
Dairy Products
Global Fresh Milk Market
Dairy Products
Probiotic Cheese Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Natural Cheese Market
Dairy Products
Dairy Products Market
Dairy Products
Butter and Margarine Market
Dairy Products
North America Cheese Market
Dairy Products
China Milk Protein Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Ready-To-Use Cheese Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Germany Casein and Caseinates Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Evaporated Milk Market