
 Cream Powder Market | 2026-2036
Cream Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Cream Powder Market Outlook
Market Context
Dairy processing labor shortages across Europe and Oceania are unwinding as automated spray-drying facilities reduce operator dependence. Fonterra Co-operative Group Limited leverages its New Zealand milk pool to sustain bulk powder exports into Asian bakery chains. Nestlé anchors retail shelf presence through instant cream formulations in Latin American markets. Danone competes on clean-label positioning in European food service channels.
Technical Definition and Segment Structure
Cream powder consists of spray-dried dairy fat emulsions containing 35-70% milk fat, reconstitutable with water for whipping, cooking, or direct incorporation into processed foods. Manufacturers concentrate liquid cream through vacuum evaporation before atomization in heated drying towers, yielding shelf-stable particles with 12-24 month stability. Cooking cream and heavy cream segments dominate industrial procurement volumes due to their fat stability under thermal stress in sauce and soup applications. The instant form category leads growth trajectory as Southeast Asian food service operators prioritize one-step rehydration over traditional non-instant powders requiring controlled temperature blending.
Regulatory Framework
The EU's EFSA dairy fat labeling requirements and the FDA's Grade A Pasteurized Milk Ordinance shape cross-border powder trade through divergent moisture-content and bacterial-count thresholds. India's FSSAI enforces compositional standards on imported cream powders that constrain non-dairy fat adulteration in South Asian markets. Stakeholders must monitor evolving Codex Alimentarius draft standards on dairy fat identity preservation, as these rules will determine which spray-drying facilities qualify for premium export certification.
Market Dynamics
Spray-drying automation is concentrating production among capital-rich operators while Southeast Asian bakery chains expand procurement of shelf-stable instant formulations, creating bifurcation between industrial-scale suppliers and regional blenders.
Growth Catalysts
- EU Farm to Fork Strategy:Tightened dairy processing standards are accelerating facility upgrades among European processors, filtering subscale operators and consolidating export-grade capacity among compliant spray-drying plants.
- Instant whipping formulations:Southeast Asian food service channels in Indonesia, Vietnam, and the Philippines are standardizing one-step rehydration protocols, displacing traditional temperature-controlled blending equipment.
- Shelf-stable bakery inputs:Extended supply chains across island economies are prioritizing 12-24 month stability windows in procurement specifications, favoring low-moisture cream powders over liquid alternatives.
Market Restraints
- Butterfat price volatility:New Zealand and EU dairy auction cycles transmit directly into cream powder input costs, compressing margin predictability for toll processors without forward-contracted milk pools.
- Spray-drying equipment concentration:German and Danish engineering firms dominate turnkey drying tower supply, creating capex bottlenecks for new entrants in South Asian and African markets.
- Plant-based emulsion substitution:Coconut and oat fat whipping agents are capturing clean-label positioning in European retail, constraining premium pricing power for dairy-derived powders.
Strategic Opportunities
- Clean-label positioning:EFSA dairy fat identity preservation rules create certification premiums for processors documenting single-origin milk sourcing through blockchain traceability systems.
- African food service penetration:Underdeveloped cold-chain infrastructure across Nigeria, Kenya, and Egypt favors ambient-stable cream powders for hotel and catering procurement.
- Direct-to-bakery e-procurement:B2B platform integration is disintermediating traditional ingredient distributors in Indonesian and Vietnamese urban centers, enabling margin capture by primary manufacturers.
Industry Challenges
- Spray-drying operator certification:Advanced thermal process control and atomization parameter management require specialized training pipelines that remain underdeveloped in emerging production geographies.
- Codex Alimentarius alignment:Draft dairy fat identity standards are creating compliance uncertainty for multi-destination exporters awaiting finalized moisture-content and bacterial-count thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cream Powder Market |
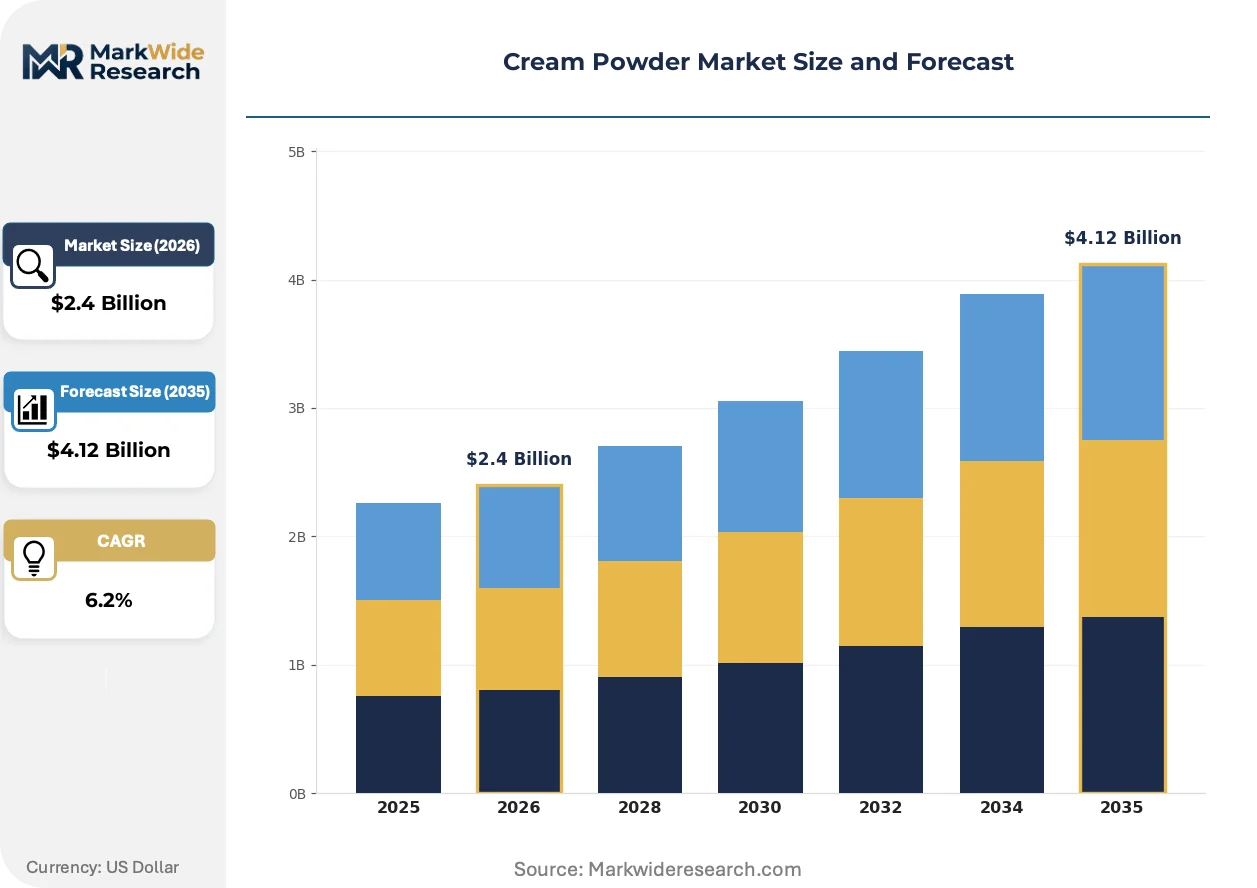
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whipping Cream, Cooking Cream, Sour Cream, Heavy Cream End Use Industry: Dairy Products, Bakery, Confectionery, Food Service Packaging Type: Bulk Bags, Pouches, Cans, Cartons Form: Powdered, Granulated, Instant, Non-Instant |
| Companies Covered | Fonterra Co-operative Group Limited, Kraft Heinz, Nestlé, Danone, Mondelez International, The Food Source International, Inc., Bluegrass Ingredients, Inc., Commercial Creamery Company, Arion Dairy Products B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cream Powder Market Strategic Shifts
Reformulation science and processing hardware are converging to compress rehydration steps while regulatory identity preservation tightens provenance documentation requirements across export corridors.
Encapsulated fat microsphere technology is miniaturizing cream powder particle architecture to sub-100-micron diameters, enabling cold-water dispersibility without mechanical shear. Indonesian cloud-kitchen operators are adopting these formulations for equipment-minimal workflows. The technology is miniaturizing the functional boundary between instant and traditional non-instant categories, collapsing premium pricing tiers.
EFSA dairy fat labeling requirements are mandating geographic origin disclosure and processing method transparency for retail-facing products. European food service distributors are now demanding batch-level documentation from Asian suppliers. Industrial procurement segments in Germany and France are restructuring supplier qualification protocols to preempt enforcement actions.
Bakery chain procurement departments are consolidating vendor panels and negotiating multi-year supply agreements with fixed-volume escalators. Direct manufacturer relationships are replacing regional ingredient distributors in Philippines and Vietnam food service channels. This concentration is most visible in Metro Manila and Ho Chi Minh City, where national bakery franchises are standardizing single-source cream powder specifications across outlet networks.
Cream Powder Market Segmentation
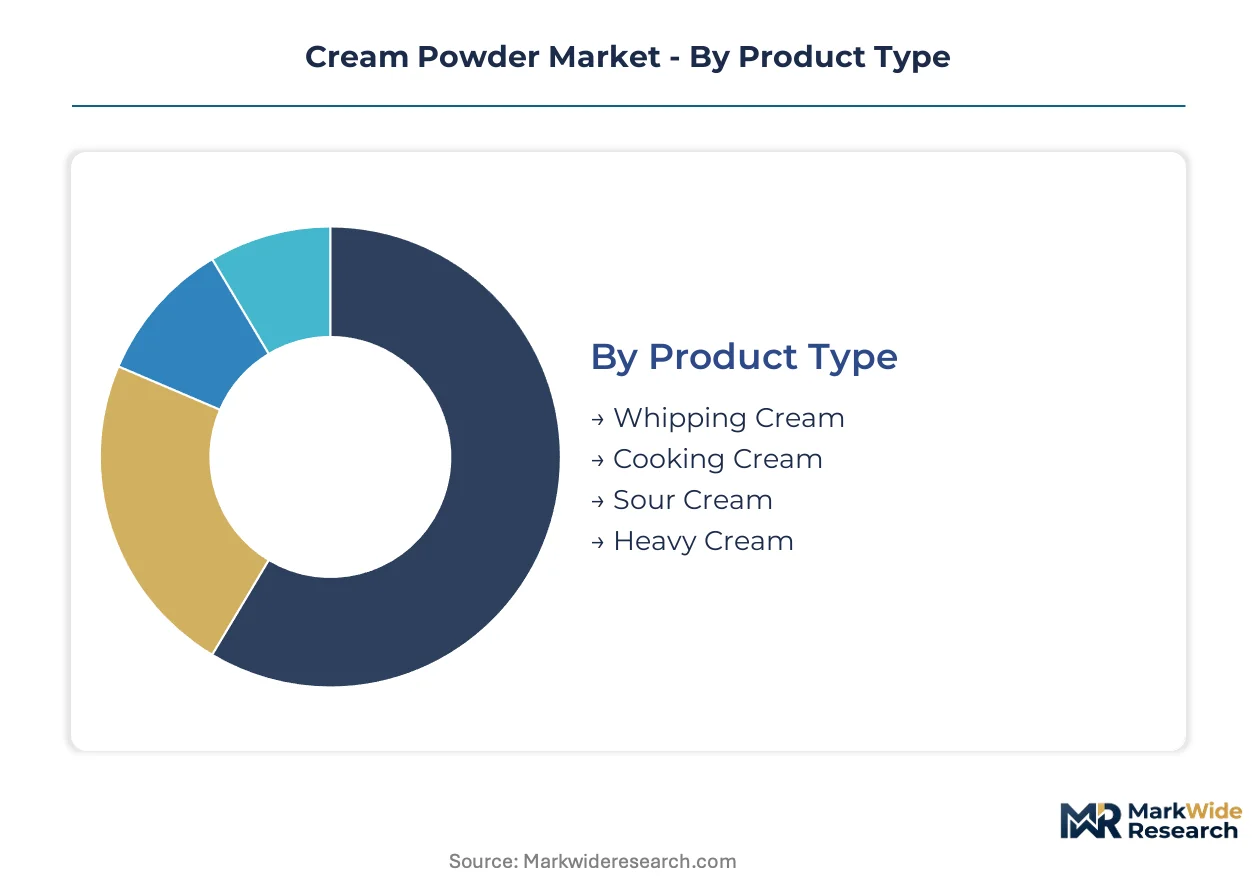
Cream powder segmentation reveals how fat content, rehydration speed, and packaging format determine channel access and margin capture. Manufacturers configure production lines around specific segment bundles to lock in bakery chain contracts or food service distribution slots.
Product Type:
Whipping cream and cooking cream move through distinct channel ecosystems, with bakery procurement favoring high-fat stability while food service operators prioritize reconstitution speed.
- Cooking Cream:Spray-dried emulsions with 35-50% milk fat content withstand thermal stress in sauce and soup manufacturing. Southeast Asian industrial kitchens in Indonesia and Vietnam are standardizing this grade for ambient-stable roux bases, displacing liquid cream in extended supply chains.
- Heavy Cream:Contains 50-70% milk fat, delivering viscosity without stabilizer additives for premium bakery applications. Philippines-based bakery chains are consolidating procurement specifications around heavy cream powders for consistent ganache and mousse production across franchise networks.
- Whipping Cream:Optimized for aeration with standardized fat globule distribution, serving European retail and Latin American instant dessert markets.
- Sour Cream:Acidified pre-drying for tangy flavor profiles, penetrating snack seasoning and dip powder formulations in North American food processing.
Cooking cream dominates installed base. Heavy cream is where expansion concentrates.
End Use Industry:
Volume concentration varies sharply by customer technical requirements, with industrial processors demanding batch consistency while food service prioritizes shelf stability.
- Food Service:Cloud kitchens and hotel catering operations in Metro Manila and Ho Chi Minh City are driving instant formulation adoption. One-step rehydration protocols eliminate temperature-controlled blending equipment, reducing capital deployment for small-format operators.
- Bakery:Regional chains across Indonesia standardize cream powder specifications for cross-outlet consistency in laminated dough and filling applications. Procurement departments negotiate multi-year supply agreements with fixed-volume escalators, bypassing traditional ingredient distributors.
- Confectionery:Chocolate and praline manufacturers in Western Europe source identity-preserved dairy fat for clean-label positioning under EFSA traceability requirements.
- Dairy Products:Recombined milk and yogurt processors in African markets leverage cream powders where fresh milk supply remains intermittent.
Bakery commands the largest volume share. Food service is gaining share fastest.
Packaging Type:
Packaging economics align with customer scale and handling infrastructure, with bulk formats capturing industrial volume and retail-ready units penetrating fragmented distribution.
- Bulk Bags:25kg multi-wall paper sacks with moisture barriers serve industrial bakeries and dairy recombination plants. Nigerian and Kenyan hotel procurement favors bulk formats where cold-chain infrastructure remains underdeveloped.
- Pouches:Flexible laminate sachets target small-format food service operators in Indonesian urban centers. B2B platform integration enables direct manufacturer relationships, disintermediating regional distributors.
- Cans:Metal containers with nitrogen flushing extend shelf life for premium retail positioning in Latin American markets.
- Cartons:Paperboard with polyethylene liners balance sustainability messaging with moisture protection for European retail channels.
Bulk bags dominate industrial procurement. Pouches are where channel innovation concentrates.
Form:
Rehydration kinetics determine equipment requirements and labor intensity, creating segmentation between capital-light instant formats and traditional powders requiring controlled processing.
- Instant:Sub-100-micron particle architecture enables cold-water dispersibility without mechanical shear. Encapsulated fat microsphere technology is collapsing the functional boundary with non-instant categories, compressing premium pricing tiers in Indonesian cloud-kitchen channels.
- Non-Instant:Larger particle sizes require temperature-controlled blending and resting periods, retaining cost advantage in industrial settings with existing hydration infrastructure.
- Powdered:Standard spray-dried particles serving legacy bakery and confectionery specifications with established reconstitution protocols.
- Granulated:Agglomerated particles with improved flow properties for automated dosing systems in large-scale dairy recombination.
Non-instant retains installed base dominance. Instant is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA dairy fat labeling requirements are reshaping procurement protocols across European food service channels, while Southeast Asian bakery chains drive volume expansion through direct manufacturer relationships. The regulatory divergence between EU identity preservation rules and emerging market shelf-stability priorities is fragmenting competitive strategies by geography.
Germany
Industrial bakery procurement departments in Bavaria and North Rhine-Westphalia are consolidating vendor panels around EFSA-compliant spray-drying facilities. The EU Green Deal's Farm to Fork Strategy mandates processing method transparency for retail-facing cream powders. Cologne-based food service distributors are restructuring supplier qualification protocols to preempt enforcement actions on dairy fat origin disclosure.
Indonesia
Cloud-kitchen operators in Jakarta and Surabaya are adopting encapsulated fat microsphere technology for equipment-minimal workflows. The country's national food regulator enforces compositional standards on imported powders that constrain non-dairy fat adulteration. National bakery franchises in Metro Manila are standardizing single-source specifications across outlet networks, bypassing traditional ingredient distributors.
United States
Snack seasoning manufacturers in the Midwest are expanding sour cream powder procurement for acidified dip formulations. FDA Grade A Pasteurized Milk Ordinance moisture-content thresholds shape cross-border trade with Canadian recombination plants. Chicago-area dairy processors are negotiating multi-year supply agreements with fixed-volume escalators for industrial bakery accounts.
Vietnam
Hotel catering operations in Ho Chi Minh City are driving instant formulation adoption for one-step rehydration protocols. The central bank's monetary policy is influencing import financing terms for spray-drying equipment from German engineering firms. Da Nang food service clusters are prioritizing ambient-stable powders where cold-chain infrastructure remains underdeveloped.
Philippines
Regional bakery chains are consolidating heavy cream powder specifications for consistent ganache production across franchise networks. The Bureau of Customs enforces dairy import licensing that filters subscale powder distributors. Cebu-based procurement departments are integrating B2B platform relationships to disintermediate regional ingredient distributors.
Cream Powder Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital-rich operators capturing automated spray-drying capacity while regional blenders serve price-sensitive channels. The upper tier commands export-grade certification premiums through blockchain traceability systems. Two strategic archetypes dominate: milk pool-anchored cooperatives with forward-contracted raw material access, and clean-label specialists leveraging single-origin sourcing documentation. Capacity expansion and direct-to-bakery e-procurement integration represent the dominant competitive moves.
Among milk pool-anchored cooperatives, Fonterra Co-operative Group Limited occupies a position exemplifying New Zealand-origin bulk powder exports into Asian bakery chains. Nestlé and Danone sit within the clean-label tier, with the former anchoring retail shelf presence through instant formulations and the latter representing EFSA-aligned positioning in European food service channels. These three names illustrate the geographic and regulatory bifurcation shaping competitive strategy.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Kraft Heinz |
| Nestlé |
| Danone |
| Mondelez International |
| The Food Source International, Inc. |
| Bluegrass Ingredients, Inc. |
| Commercial Creamery Company |
| Arion Dairy Products B.V. |
| Others |
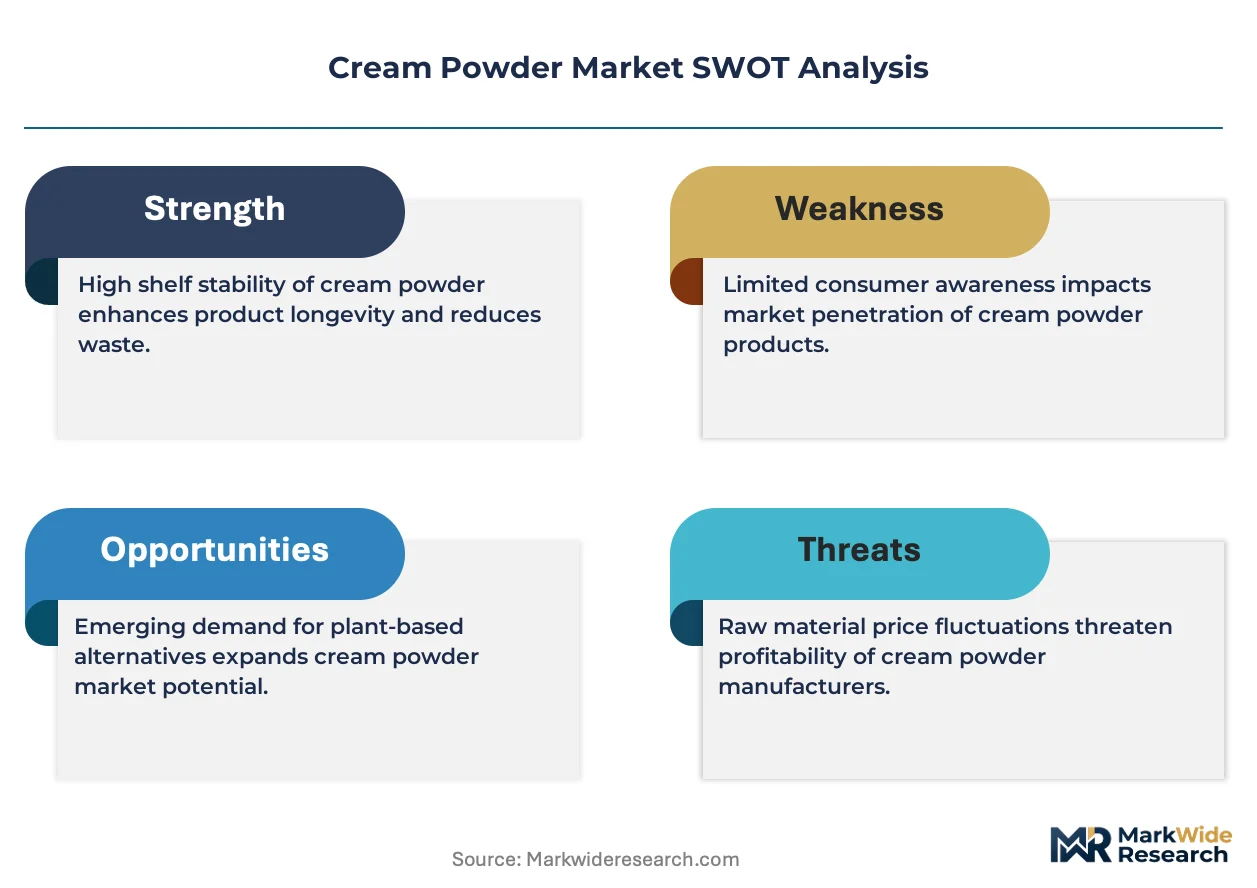
Value Chain & Pricing Dynamics
Spray-drying facility utilization rates above 85 percent in New Zealand and the Netherlands establish price floors that smaller toll processors cannot match, compressing margin structures across Asian import markets while concentrating export-grade capacity among capital-rich operators with forward-contracted milk pools.
Pricing Analysis
European food service channels command 15-25 percent premiums over Southeast Asian bakery procurement for EFSA-certified identity-preserved powders. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and geographic origin disclosure. Cost compression in economy tiers is intensifying because Indonesian cloud-kitchen operators are adopting encapsulated microsphere formulations that collapse functional distinctions. Industrial bakery chains in the Philippines exhibit lowest price sensitivity due to multi-year volume commitments, while unaffiliated regional distributors in Vietnam face margin erosion from direct-to-manufacturer B2B platforms.
Supply Chain Analysis
New Zealand and the Netherlands anchor global spray-dried cream powder production through automated drying tower networks with 12-24 month stability engineering. Manufacturing draws from seasonal milk pool auctions, German-engineered atomization equipment, and nitrogen-flushing packaging systems. Single-source vulnerability concentrates in turnkey drying tower supply from Danish and German engineering firms, creating capex bottlenecks for African and South Asian market entrants. Distribution runs through consolidated food service distributors in Europe, direct manufacturer relationships in Southeast Asian urban centers, and traditional ingredient traders in underdeveloped cold-chain markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled traceability subscriptions and certification documentation services are expanding faster than base powder volumes, creating recurring-revenue layers that anchor long-term customer retention in EFSA-aligned channels.
For Market Incumbents: Shield export-grade certification premiums by embedding blockchain traceability into customer workflows before Codex Alimentarius finalizes dairy fat identity standards. Accelerate backward integration into captive milk pools in New Zealand and EU auction markets to buffer butterfat price volatility. Prioritize spray-drying automation upgrades that filter subscale competitors from compliant supplier lists. For New Entrants and Emerging Players: Lead with equipment-minimal instant formulations targeting Nigerian and Kenyan hotel catering procurement where cold-chain gaps favor ambient-stable inputs. Penetrate Indonesian cloud-kitchen channels through B2B platform integration that disintermediates legacy distributors. Anchor go-to-market positioning on one-step rehydration protocols that eliminate temperature-controlled blending capital for small-format operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors spray-drying specialists with installed automation capacity and EFSA pre-qualification status. Long-term viability hinges on certification moats widening as regulatory disclosure requirements tighten across European food service channels. Monitor Codex Alimentarius draft standard finalization as the inflection signal determining which facilities capture premium export certification.| Strategic Initiative | Industry Significance |
|---|---|
| Spray-Drying Automation Upgrade | EFSA compliance filtering subscale operators from European food service vendor panels. |
| Backward Integration into Milk Pools | Forward-contracted raw material access buffers Fonterra-style margin volatility. |
| Blockchain Traceability Deployment | Single-origin documentation commands certification premiums in German confectionery procurement. |
| B2B Platform Direct Integration | Disintermediation captures distributor margins in Jakarta and Ho Chi Minh City channels. |
| Encapsulated Microsphere Launch | Cold-water dispersibility collapses equipment requirements for Indonesian cloud kitchens. |
Study Parameters
Operator-level perspectives from spray-drying plant managers, Southeast Asian bakery procurement directors, European food service distributors, and German engineering firm sales engineers anchored the qualitative base. Secondary validation drew from Fonterra auction data, EFSA guidance documents, FDA Grade A Pasteurized Milk Ordinance filings, and Indonesian customs import records. Bottom-up volume modeling triangulated against top-down dairy fat consumption estimates across food service and industrial channels.
Sensitivity analysis tested forecast outputs against butterfat price volatility scenarios and regulatory timeline slippage for Codex Alimentarius finalization. Segmentation dimensions modeled include fat content tier, rehydration form, packaging format, end-use industry, and regional regulatory cluster across the analysis window. CAGRs derived from installed base growth rates in instant formulations and displacement curves for traditional non-instant powders. Forecast inputs incorporated spray-drying capacity utilization data and cloud-kitchen expansion trajectories in Southeast Asian urban centers.
The analysis sits within stated boundaries; outcomes outside EFSA enforcement intensity assumptions or Southeast Asian cold-chain development trajectories would require recalibration. Forecasts reflect documented assumptions on regulatory timeline convergence and butterfat auction cycle stability. Recalibration cycles align with material shifts in Codex Alimentarius standard finalization and encapsulated microsphere adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Emmental Cheese Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
India Dairy Market
Dairy Products
North America Yogurt Market
Dairy Products
Malted Milk Powder Market
Dairy Products
White Cheese Market
Dairy Products
North America Cheese Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Europe Casein and Caseinates Market
Dairy Products
Europe Cheese Market
Dairy Products
Goat Milk Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
South America Dairy Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Milk Retentate Market