
 India Dairy Market | 2026-2036
India Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
India Dairy Market Insights
Buyer concentration across India's dairy sector is decoupling as organized food service chains and quick-service restaurants fragment procurement away from traditional wholesale mandis. Gujarat Cooperative Milk Marketing Federation Ltd. (GCMMF) (Amul) anchors cooperative supply networks across western India, while Hatsun Agro Product Ltd. competes through specialized ice cream and curd portfolios in southern markets. Parag Milk Foods Ltd. leverages premium cheese manufacturing to differentiate in urban retail channels.
Dairy encompasses fluid milk and derived products processed through pasteurization, homogenization, fermentation, or churning, with fat content and microbial load serving as critical quality parameters for commercial distribution. Milk remains the volume foundation, though cheese and yogurt segments attract widening margin pools as urban consumers shift toward value-added formats. Food service applications now represent the fastest-growing demand channel, outpacing traditional retail consumption as hotel, restaurant, and institutional buyers scale direct procurement from processors.
FSSAI fortification rules, BIS quality certifications, and state-level dairy development boards collectively tighten product standards and market access across Indian states. These frameworks elevate compliance costs for unorganized players while creating structured pathways for organized processors to expand distribution. Stakeholders must monitor evolving state cooperative policies and cold chain infrastructure investments that will determine which processing clusters capture disproportionate volume growth.
Market Dynamics
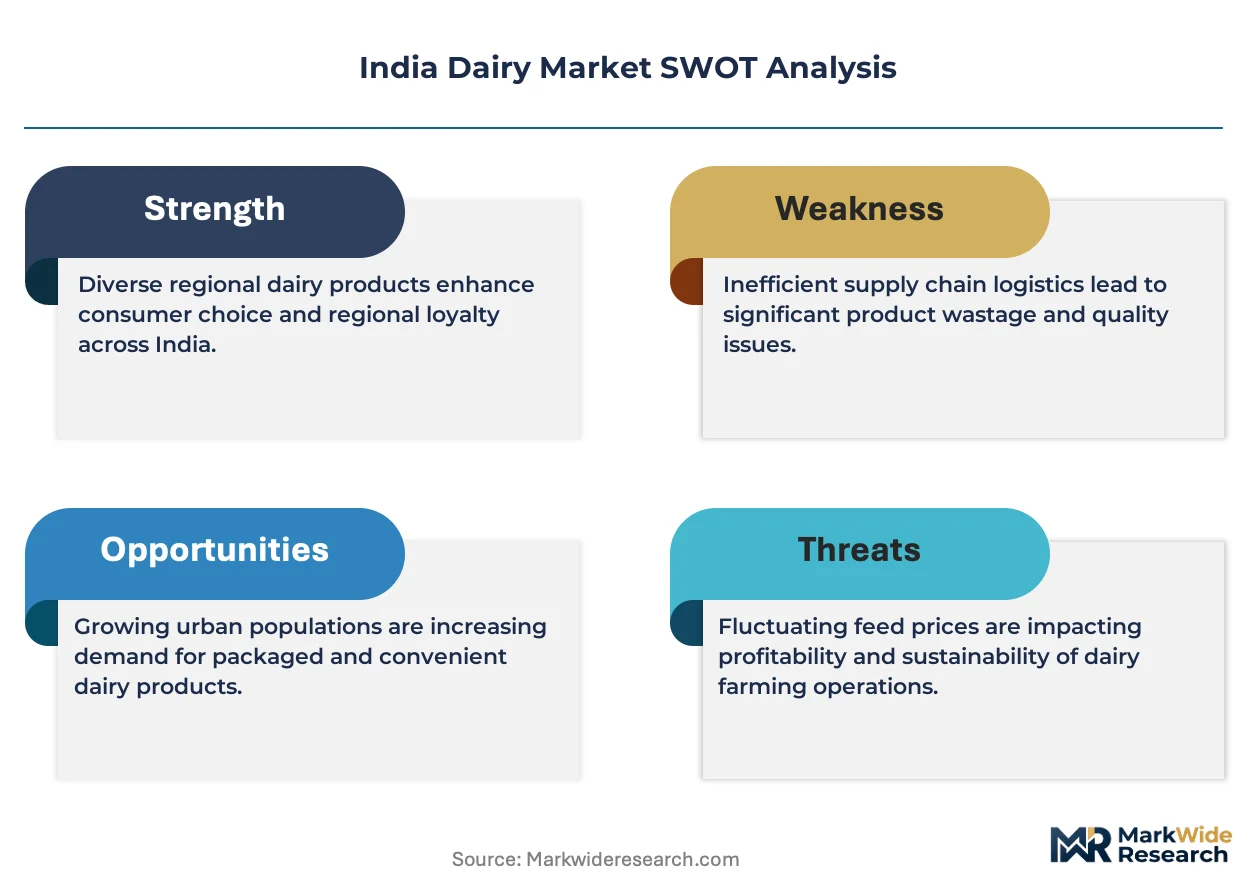
FSSAI fortification mandates and cold chain infrastructure investments are restructuring procurement relationships between organized processors and institutional buyers across Indian states.
Growth Catalysts
- Institutional procurement expansion:Quick-service restaurants and hotel chains are scaling direct sourcing agreements with organized dairies, bypassing traditional wholesale mandis in Maharashtra and Gujarat.
- FSSAI micronutrient rules:Mandatory fortification of packaged milk with Vitamin A and D is accelerating formalization of processing capacity and quality certification uptake.
- Cooperative network density:Gujarat and Karnataka cooperative federations are extending chilling center coverage into secondary towns, reducing raw milk spoilage and expanding catchment areas.
Market Restraints
- Fodder cost volatility:Fluctuating prices of dry fodder and oil cakes squeeze margins for smallholder dairy farmers who supply 70% of India's raw milk.
- Cold chain gaps:Inadequate refrigerated transport and bulk milk cooler penetration in eastern and northeastern states limits shelf-life extension for value-added products.
- Substitute protein competition:Plant-based beverages and soy milk alternatives are capturing trial among urban health-conscious consumers in metro markets.
Strategic Opportunities
- Eastern India underpenetration:West Bengal, Odisha, and Bihar present white space for organized players to establish processing clusters where cooperative presence remains thin.
- Cheese manufacturing specialization:Pizza chain expansion and bakery ingredient demand create pull for mozzarella and processed cheese production capacity.
- Export channel development:FSSAI harmonization with Codex standards and bilateral dairy protocols with Gulf Cooperation Council markets enable formal export qualification.
Industry Challenges
- Veterinary extension capacity:Shortage of artificial insemination technicians and livestock health workers constrains genetic improvement programs at village cooperative societies.
- Compliance timeline compression:BIS certification and FSSAI license renewal processes create bottlenecks for small processors upgrading to packaged product formats.
- Legacy equipment integration:Retrofitting existing chilling centers with automated milk analyzers and electronic weighing systems requires capital outlay that fragments processor tiering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Dairy Market |
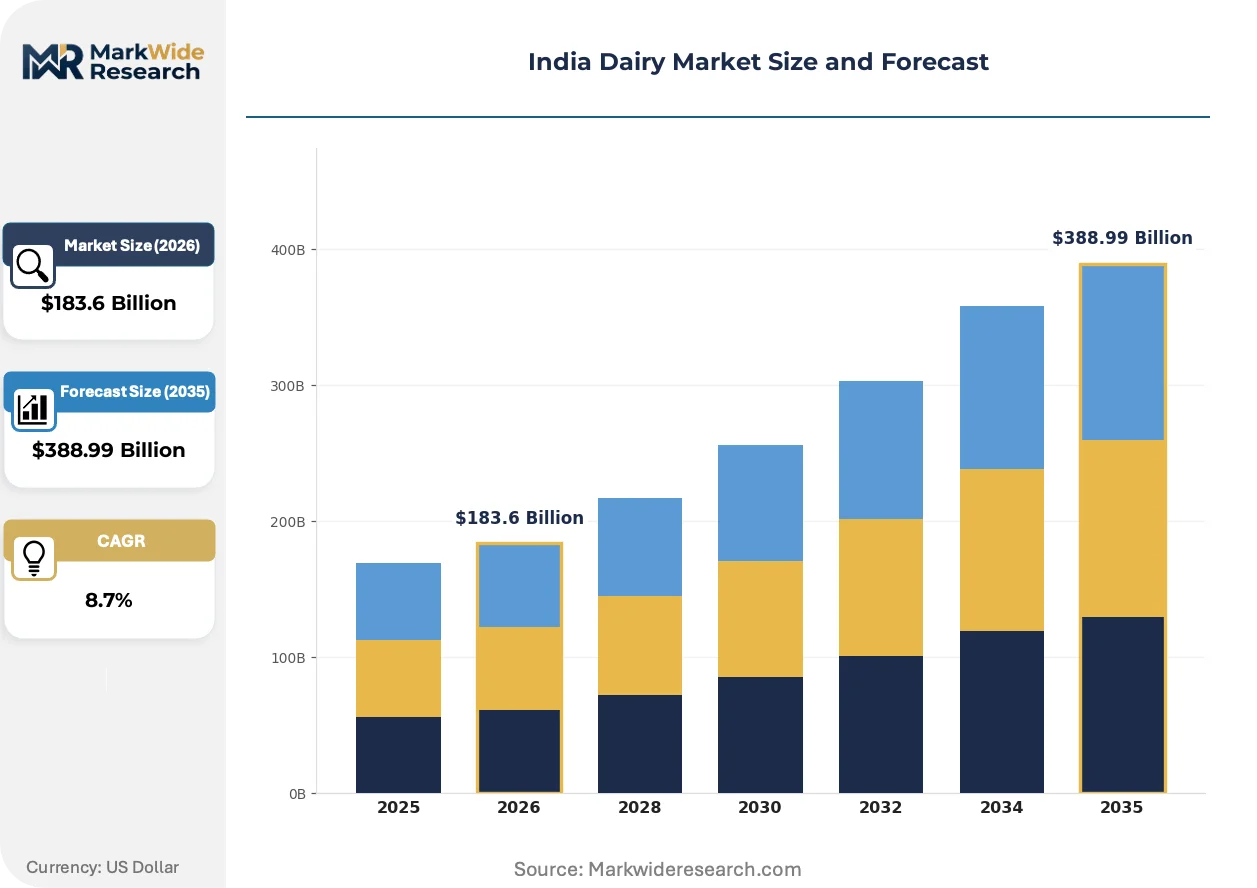
| Market Size in 2026 | $183.6 Billion |
| Market Size in 2035 | $388.99 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Butter, Cheese, Yogurt Application: Dairy Foods, Ice Cream, Infant Formula, Bakery End User: Retail Consumers, Food Service, Food Processing, Institutions Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale |
| Companies Covered | Parag Milk Foods Ltd., Creamline Dairy Products Ltd., Gujarat Cooperative Milk Marketing Federation Ltd. (GCMMF) (Amul), Heritage Foods Ltd., Milky Mist Dairy Food Pvt Ltd, Mother Dairy Fruits & Vegetables Pvt. Limited, Dodla Dairy Ltd., Tirumala Milk Products Pvt Ltd, Hatsun Agro Product Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Dairy Market Trends and Innovations
Automation in milk testing and blockchain-based traceability systems are reconfiguring quality assurance workflows across Indian dairy supply chains.
Automated milk analyzers equipped with infrared spectroscopy are overtaking manual lactometer readings at village collection centers. Dairy cooperatives in Gujarat and Maharashtra are deploying these units to standardize fat and SNF measurement before chilling. The technology is compressing payment cycle disputes between farmers and procurement agents while enabling real-time quality grading.
FSSAI's 2022 amendment to the Food Safety and Standards (Food Products Standards and Food Additives) Regulations tightened residual antibiotic limits in milk. Processing facilities must now maintain documented testing protocols and third-party audit trails. Large organized dairies have responded by investing in in-house ELISA testing laboratories, widening compliance cost gaps against unorganized competitors.
Direct sourcing contracts between quick-service restaurant chains and dairy processors are displacing traditional distributor networks in urban corridors. Burger and pizza chains now specify chilled paneer and cheese specifications in master service agreements. This pattern concentrates most visibly in Bangalore, Mumbai, and Delhi NCR where food service density supports dedicated supply lines.
India Dairy Market Segmentation
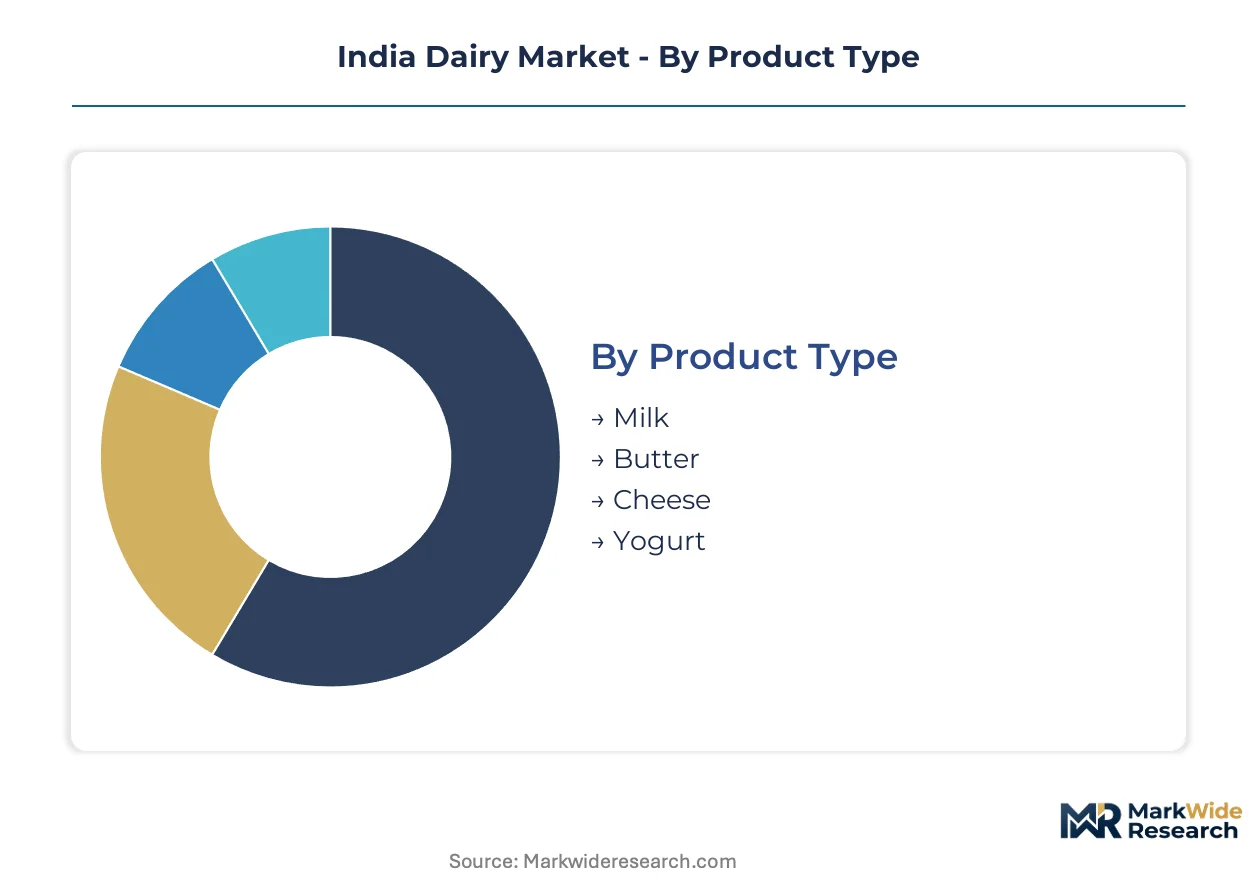
Segmentation in India's dairy sector reveals how procurement relationships and consumption patterns diverge across product formats and buyer types. Understanding these divides helps processors allocate capacity between commodity fluid milk and higher-margin value-added categories.
Product Type:
Buyer decisions here pivot on shelf-life requirements versus freshness preferences, with fat content and processing intensity driving price premiums.
- Milk:Fluid milk dominates procurement volumes through village cooperative societies and bulk chilling centers. Maharashtra and Gujarat processing hubs concentrate procurement from smallholder farmers supplying unprocessed raw milk with fat content between 3.5% and 4.5%.
- Cheese:Mozzarella and processed cheese varieties attract dedicated manufacturing lines as pizza chains and bakery ingredient buyers specify melt characteristics and stretch indices in procurement contracts. Urban food service density in Bangalore and Delhi NCR pulls capacity expansion toward these formats.
- Butter:Clarified butter and table butter serve distinct regional preferences across western and northern states.
- Yogurt:Probiotic and flavored curd variants target health-conscious urban retail segments.
Volume sits with Milk; growth tilts toward Cheese.
Application:
Cost tier separation distinguishes commodity ingredient supply from branded consumer positioning.
- Dairy Foods:Direct consumption products including flavored milk and traditional sweets carry regional taste formulations. Gujarat Cooperative Milk Marketing Federation anchors this segment through Amul's chilled distribution network reaching tier-2 towns.
- Ice Cream:Hardened and soft-serve formats require -18°C cold chain maintenance through dedicated freezer cabinets. Southern markets show higher per-capita consumption intensity, pulling Hatsun Agro Product's specialized manufacturing investments toward Tamil Nadu and Karnataka.
- Infant Formula:Nutritional compliance with FSSAI compositional standards mandates specialized fortification protocols.
- Bakery:Industrial cheese and butter volumes serve commercial baking operations.
Volume concentrates in Dairy Foods; margin expansion favors Ice Cream.
End User:
Customer type determines packaging specifications, delivery frequency, and payment terms across the procurement spectrum.
- Food Service:Quick-service restaurants and hotel chains negotiate master service agreements specifying chilled paneer hardness and cheese shred dimensions. Direct sourcing bypasses traditional wholesale mandis in Mumbai and Hyderabad corridors.
- Retail Consumers:Packaged milk pouches and UHT tetrapaks dominate household purchase patterns through morning delivery networks and supermarket shelves.
- Food Processing:Industrial buyers procure bulk butter and milk powders for confectionery and ready-meal manufacturing.
- Institutions:Schools, hospitals, and defense canteens source through tender-based procurement with FSSAI fortification compliance requirements.
Volume remains with Retail Consumers; Food Service captures the steepest expansion trajectory.
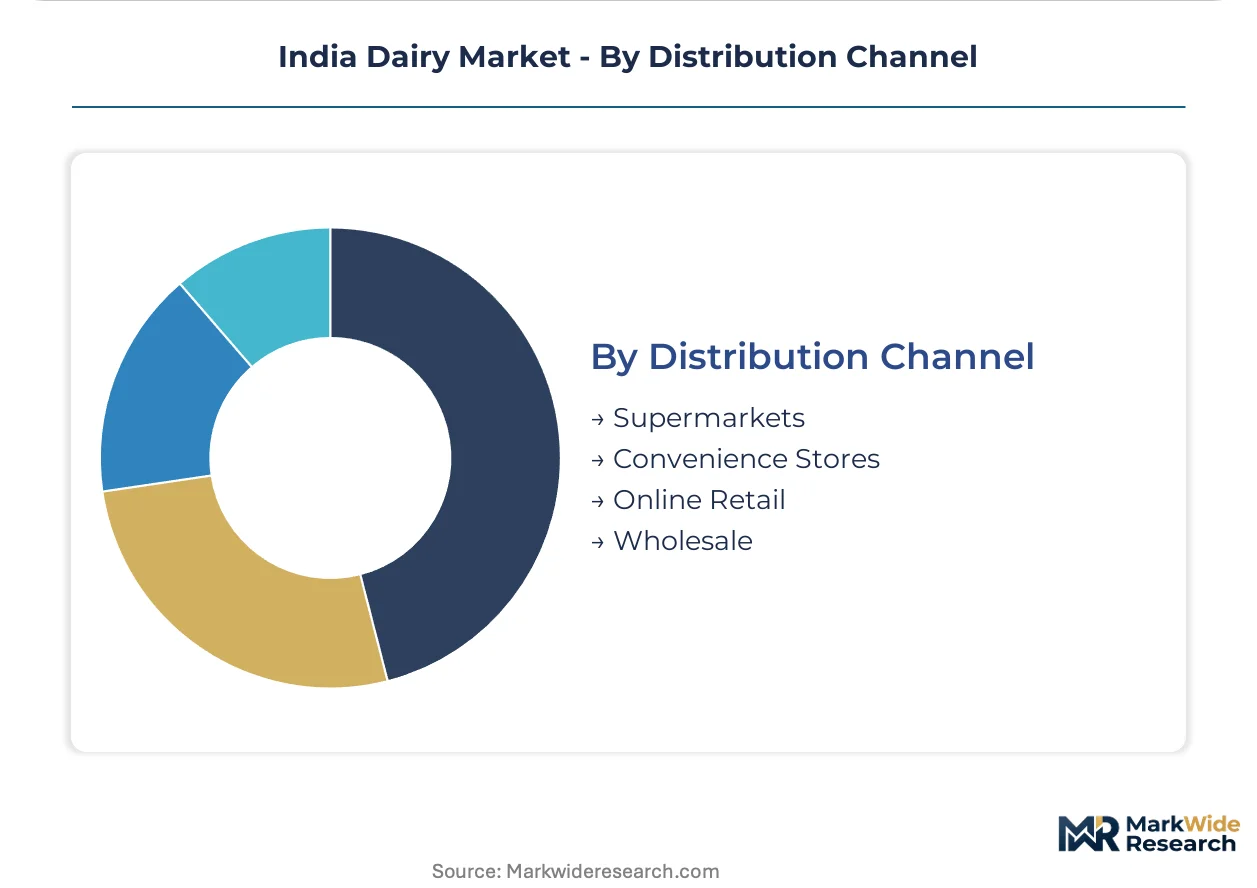
Distribution Channel:
Supply concentration in western India shapes channel effectiveness for temperature-sensitive products.
- Supermarkets:Organized retail chains in Delhi NCR and Mumbai maintain dedicated dairy sections with controlled 4°C display cases. Modern trade expansion into tier-2 cities pulls branded yogurt and cheese portfolio listings.
- Wholesale:Traditional mandi networks continue serving kirana stores and small food service operators through morning auction systems in Ahmedabad and Pune.
- Convenience Stores:Extended-hour outlets in urban clusters stock UHT milk and probiotic drinks for immediate consumption.
- Online Retail:Quick-commerce platforms promise 10-minute delivery for chilled products in dense metro catchments.
Volume flows through Wholesale; Supermarkets gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement relationships concentrate in western and southern India where cooperative networks and private processing clusters have achieved critical density. FSSAI fortification mandates and cold chain investments are redrawing competitive boundaries across state-level markets.
Maharashtra
Urban food service chains in Mumbai and Pune are scaling direct sourcing agreements for paneer and processed cheese, bypassing traditional wholesale mandis. The state's dairy development board coordinates with FSSAI to enforce Vitamin A and D fortification standards across packaged milk distribution. Chilling center clusters around Nashik and Kolhapur are extending procurement catchments into secondary towns.
Gujarat
The Gujarat Cooperative Milk Marketing Federation anchors cooperative supply networks with village-level collection infrastructure reaching into Saurashtra and North Gujarat. State-level dairy development policies prioritize artificial insemination extension and fodder security programs for smallholder suppliers. Anand and Banaskantha districts host the densest processing hub concentration for fluid milk and butter production.
Karnataka
Bangalore's quick-service restaurant density is pulling dedicated cheese and paneer supply lines from organized processors in the surrounding districts. The Karnataka Milk Federation extends chilling coverage into tier-2 towns under state cooperative modernization schemes. Mysore and Hassan districts are emerging as secondary processing clusters for value-added curd and flavored milk portfolios.
Tamil Nadu
Higher per-capita ice cream consumption intensity in Chennai and Coimbatore is attracting specialized manufacturing investments from southern-focused dairy groups. State dairy development initiatives target veterinary extension capacity building and bulk milk cooler deployment. The Salem-Erode corridor is consolidating as a procurement zone for industrial cheese ingredients serving bakery and confectionery buyers.
Delhi-NCR
Quick-commerce platforms promising 10-minute chilled delivery are reshaping last-mile distribution economics across Gurugram, Noida, and Faridabad. FSSAI license enforcement is tightest in this jurisdiction, accelerating formalization of packaged product formats. Ghaziabad and Sonipat processing facilities are capturing food service procurement contracts from hotel and institutional buyers in the capital region.
India Dairy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue premium cheese specialization and direct food service contracting. The market structures around cooperative federations with village-level procurement density and private processors with urban retail channel control. Three archetypes dominate: cooperative anchors with backward-integrated farmer networks, private integrated dairies with cold chain assets, and regional specialists with single-category depth. Competitive moves concentrate on capacity expansion in eastern underpenetrated markets and strategic partnerships with quick-service restaurant chains.
Within the cooperative anchor tier, Gujarat Cooperative Milk Marketing Federation Ltd. (GCMMF) (Amul) and Mother Dairy Fruits & Vegetables Pvt. Limited exemplify procurement-network scale. Among private integrated processors, Hatsun Agro Product Ltd. and Heritage Foods Ltd. occupy positions emphasizing southern market density and chilled distribution infrastructure. Parag Milk Foods Ltd. represents the specialist archetype with premium cheese manufacturing orientation.
| Leading Market Players |
|---|
| Parag Milk Foods Ltd. |
| Creamline Dairy Products Ltd. |
| Gujarat Cooperative Milk Marketing Federation Ltd. (GCMMF) (Amul) |
| Heritage Foods Ltd. |
| Milky Mist Dairy Food Pvt Ltd |
| Mother Dairy Fruits & Vegetables Pvt. Limited |
| Dodla Dairy Ltd. |
| Tirumala Milk Products Pvt Ltd |
| Hatsun Agro Product Ltd. |
| Others |
Pricing and Supply Chain Analysis
Fodder cost volatility at the smallholder farmgate cascades through Maharashtra and Gujarat procurement networks, compressing margins for unorganized collectors while organized cooperatives absorb shocks through backward integration into cattle feed production. This upstream cost pressure stratifies fluid milk pricing across premium FSSAI-certified pouches, standard bulk supplies to institutional buyers, and economy-grade loose milk circulating through traditional mandis.
Pricing Analysis
Volume concentrates in commodity fluid milk while margin expansion tilts toward cheese and probiotic yogurt formats. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-fortified branded pouches from bulk institutional contracts and unorganized loose milk. Pricing pressure stems from fodder inflation squeezing smallholder suppliers who feed seventy percent of raw milk into the system. Quick-service restaurant chains show least price sensitivity, locking long-term paneer and cheese specifications in master service agreements.
Supply Chain Analysis
Return flows of expired packaged milk from supermarket shelves and quick-commerce dark stores feed into industrial whey processing and animal feed manufacturing, closing material loops for organized processors. Supply concentrates in India, with Gujarat and Maharashtra hosting densest chilling center clusters and Karnataka emerging as southern processing hub. Raw material dependencies center on crossbred cattle semen imports, veterinary pharmaceuticals, and automated milk analyzer components. Single-source vulnerability runs through artificial insemination technician shortages constraining genetic improvement programs. Distribution runs through cooperative village collection societies feeding bulk milk coolers, then onward to state-level processing federations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's dairy market reads as supply-constrained: veterinary extension capacity bottlenecks and chilling center gaps in eastern states prop pricing premiums for organized players with procurement network density.
For Market Incumbents: Deploy artificial insemination technician training programs as the anchor lever for genetic yield improvement. Consolidate position by acquiring distressed chilling centers in Odisha and Bihar before cooperative federations extend coverage. Channel control investments in quick-commerce partnerships defend against unorganized loose milk price undercutting in Delhi-NCR and Bangalore. For New Entrants and Emerging Players: Direct-to-food-service digital platforms offer the lowest-friction entry vector for bypassing established distributor networks. Target West Bengal and Bihar processing clusters where cooperative presence remains thin and land costs for greenfield facilities run below western India benchmarks. White space sits in mozzarella manufacturing for pizza chain expansion; anchor go-to-market through master service agreements specifying melt characteristics rather than retail brand building. For Investors and Strategic Acquirers: FSSAI license acceleration timelines for eastern India entrants is the leading indicator that regulatory arbitrage windows are narrowing. Five-to-ten year viability favors processors with captive milk supply through farmer-producer organizations rather than spot market dependence. Acquisition target archetype: regional cheese specialists with existing quick-service restaurant contracts and unused plant capacity for mozzarella line expansion. Monitor state cooperative modernization scheme budget allocations for early signals of competitive pressure intensification.| Strategic Initiative | Industry Significance |
|---|---|
| Chilling Center Network Expansion | Extends procurement catchments into Bihar and Odisha where spoilage rates exceed western India benchmarks. |
| Direct Food Service Contracting | Bypasses wholesale mandi intermediaries that extract margin from pizza and burger chain supply lines. |
| FSSAI Fortification Compliance Investment | Creates regulatory moat against unorganized loose milk competitors lacking Vitamin A and D testing infrastructure. |
| Artificial Insemination Extension Programs | Addresses technician shortage constraining genetic improvement for smallholder suppliers across village societies. |
| Quick-Commerce Partnership Development | Captures ten-minute delivery economics in Delhi-NCR and Bangalore dense metro catchments. |
Research Methodology
Annual reports from GCMMF, Hatsun Agro Product, and Heritage Foods, combined with FSSAI compliance filings and state dairy development board publications, formed the secondary backbone for production capacity and regulatory trajectory assessment. Primary interviews with procurement managers at quick-service restaurant chains, chilling center operators in Nashik and Kolhapur, and veterinary extension officers at Karnataka Milk Federation supplemented secondary validation. Bottom-up triangulation across product-level volume estimates and top-down macroeconomic anchoring ensured cross-verified outputs.
Historical trendline analysis of fluid milk procurement volumes, value-added product mix shifts, and cooperative membership growth rates established baseline momentum parameters across the projection horizon. Segmentation modeling incorporated product format, application category, end-user archetype, and distribution channel dimensions. CAGRs derived from curve-fitting approaches applied to documented capacity expansion timelines and food service procurement contract disclosures. Forecast inputs included fodder price indices and cold chain infrastructure investment flows from state cooperative modernization schemes.
The model holds under continued FSSAI enforcement intensity and steady smallholder supply participation; deviation in veterinary extension capacity deployment or abrupt fodder cost spikes would shift volume trajectories. Practitioners should monitor state budget allocations for artificial insemination programs and eastern India chilling center deployment schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cheese Concentrate Market
Dairy Products
Clotted Cream Market
Dairy Products
Flavoured Milk Market
Dairy Products
Europe Drinkable Yogurt Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Lactose-Free Sour Cream Market
Dairy Products
Green Tea Butter Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Global Milk Powder Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Dairy Concentrates Market