
 High-Concentrated Protein Market | 2026-2036
High-Concentrated Protein Market Size, Share, and Industry Trends Forecast 2026-2036
High-Concentrated Protein Market Analytics
Sports nutrition is rebalancing toward recovery and endurance segments as bodybuilding's historical dominance moderates. Fonterra Co-operative Group leverages its New Zealand dairy supply base to anchor whey protein concentrate output for Asia-Pacific contract manufacturers. Glanbia plc sustains R&D intensity in hydrolyzed protein isolates, while Arla Foods Ingredients Group P/S specializes in micellar casein for overnight recovery formulations.
High-concentrated protein denotes protein preparations containing substantially elevated protein content per unit mass relative to standard concentrates, typically achieved through ultrafiltration, ion exchange, or microfiltration processes that remove non-protein constituents such as lactose and lipids. These preparations serve primarily as functional ingredients enabling precise macronutrient engineering in formulated foods and supplements. Whey protein occupies the largest existing volume position due to its complete amino acid profile and rapid absorption kinetics, while pea protein represents the fastest-expanding category as formulators address allergen and sustainability constraints in plant-based lines. Casein protein retains premium positioning in meal replacement and overnight recovery applications where slow amino acid release delivers functional differentiation.
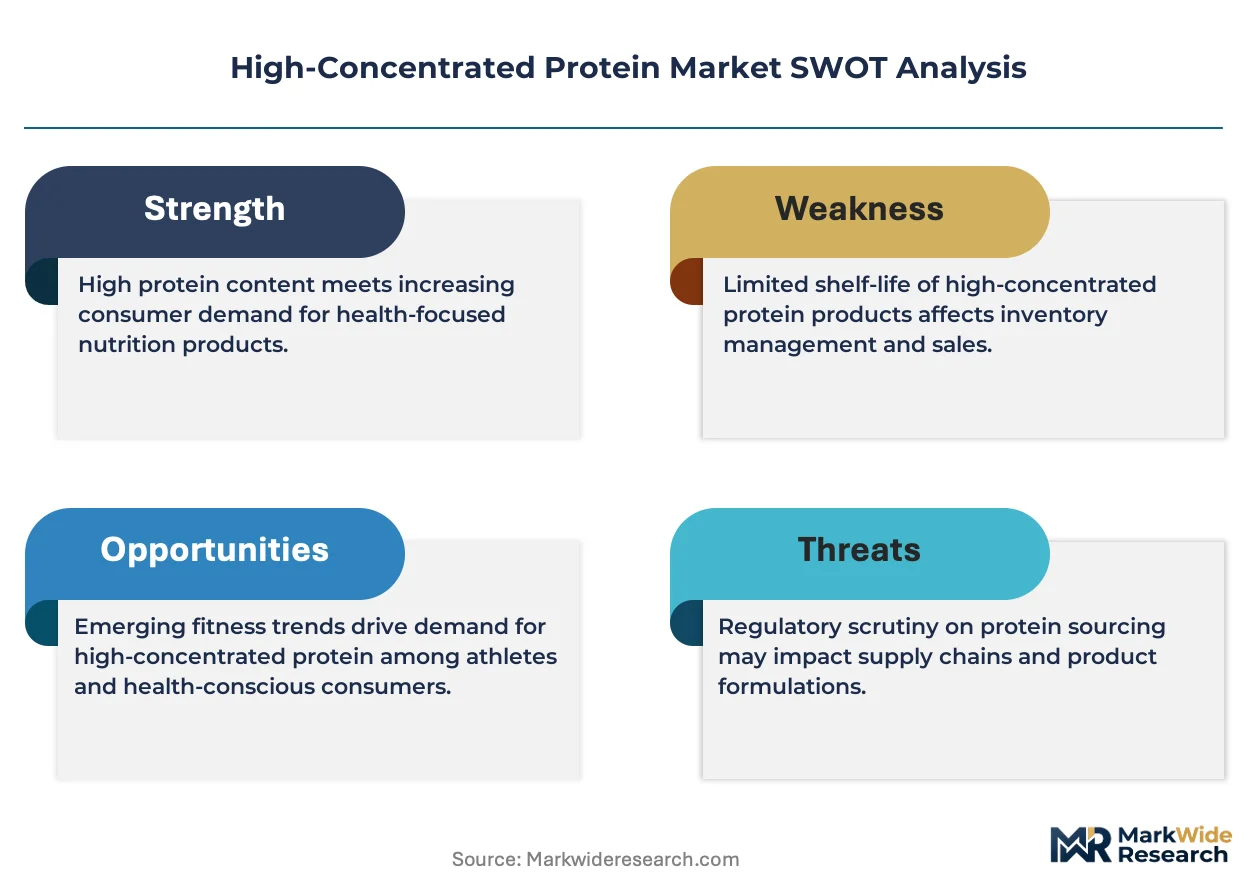
EFSA novel food authorizations and FDA GRAS self-affirmation pathways shape ingredient market access timelines and label claim permissibility across Europe and North America. BIS protein quality standards in India and China's NMPA filing requirements for imported nutritional ingredients add compliance layers for multinational suppliers. Stakeholders must monitor evolving amino acid scoring methodologies and front-of-pack protein claim regulations as these technical standards increasingly determine competitive eligibility in key retail channels.
Market Dynamics
Clean-label formulation pressures from EFSA and FDA are compressing ingredient sourcing timelines and elevating protein purity thresholds, forcing manufacturers to revalidate entire supply chains for label claim permissibility.
Growth Catalysts
- EFSA novel food authorizations:Streamlined pathways for pea and alternative proteins accelerate European market entry for plant-based formulators seeking clean-label positioning.
- Endurance sports nutrition retail:German sports nutrition chains are scaling whey and plant-protein portfolios to serve recovery-focused consumers beyond traditional bodybuilding segments.
- Ultrafiltration process intensification:Membrane technology advances reduce lactose and lipid retention, enabling higher protein concentrations per unit mass in whey isolate production.
Market Restraints
- Dairy input cost volatility:New Zealand milk powder pricing swings transmit directly to whey protein concentrate margins, compressing formulator profitability during supply shocks.
- Supply concentration risk:Micellar casein production clusters in Scandinavian dairy cooperatives, creating single-source vulnerability for overnight recovery formulations.
- Regulatory friction:China's NMPA filing requirements for imported nutritional ingredients extend market access timelines by 12-18 months for multinational suppliers.
Strategic Opportunities
- Underpenetrated Indian market:BIS protein quality standard harmonization creates first-mover advantage for suppliers establishing local blending and packaging infrastructure.
- Regulatory tailwind:EU Green Deal bioeconomy incentives favor pea protein expansion through carbon footprint reduction credits in sustainable formulation claims.
- Direct-to-consumer channel innovation:Subscription-based personalized protein services bypass traditional sports nutrition retail markups in North American metropolitan markets.
Industry Challenges
- Specialized talent scarcity:Food protein chemists with membrane filtration expertise command premium compensation, constraining R&D scaling for mid-tier manufacturers.
- Certification timeline compression:FDA GRAS self-affirmation documentation requirements consume 6-9 months of technical resources per novel protein ingredient.
- Legacy system integration:ERP platforms at established dairy processors require costly customization to trace protein lot purity for clean-label compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Concentrated Protein Market |
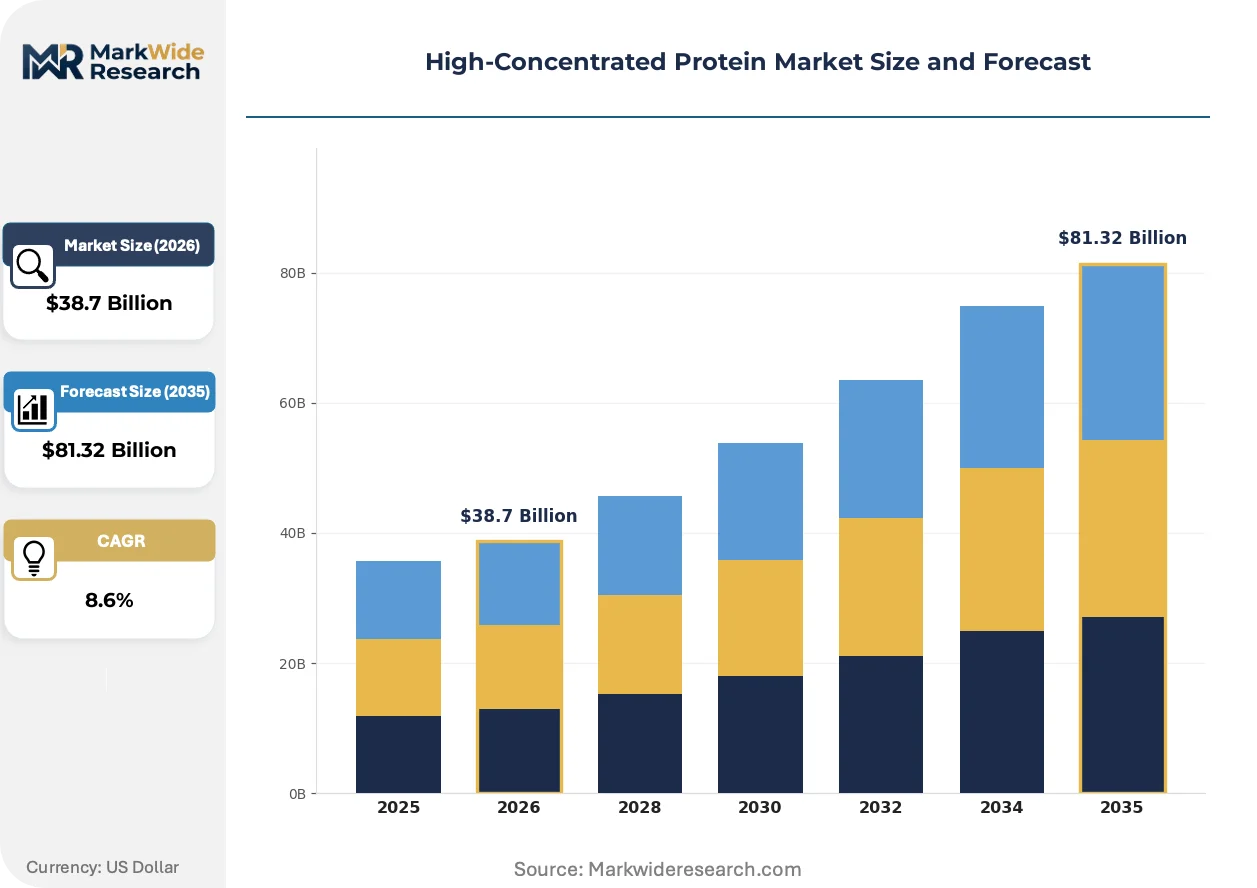
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Soy Protein, Pea Protein Application: Sports Nutrition, Meal Replacement, Dietary Supplements, Functional Foods End User: Athletes, Bodybuilders, Health-conscious Consumers, Nutritional Seekers Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops |
| Companies Covered | Fonterra Co-operative Group, Glanbia plc, Arla Foods Ingredients Group P/S, Cargill, Archer Daniels Midland Company, Idaho Milk Products, AMCO Proteins, Hilmar Cheese Company, Lactalis Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Concentrated Protein Market Evolving Landscape
Precision fermentation and cellular agriculture are beginning to intersect with traditional protein extraction, while regulatory frameworks on both sides of the Atlantic tighten purity disclosure requirements.
Membrane filtration cascade systems are electrifying protein fractionation economics by enabling simultaneous isolation of whey protein isolate, micellar casein, and milk fat globule membrane from single milk streams. European functional food manufacturers are retrofitting existing dairy plants with these integrated systems at accelerating pace. This convergence is compressing capital recovery timelines for multiproduct facilities while elevating minimum efficient scale thresholds for new market entrants.
EFSA's updated guidance on protein quality claims requires PDCAAS or DIAAS scoring disclosure on all front-of-pack positioning, forcing reformulation of blended proteins to maintain competitive amino acid profiles. The industrial consequence is accelerated R&D investment in enzyme hydrolysis to improve digestibility scores of plant-based alternatives. Sports nutrition brands targeting German and French retail channels are most affected, with several reformulating entire product lines to meet the 2026 compliance deadline.
Athlete and consumer purchasing is consolidating around certified clean-label products with third-party testing verification, displacing unverified bulk protein powders in specialty retail. Amazon and specialized sports nutrition e-commerce platforms are capturing this shift through subscription models and loyalty programs. This pattern is most visible in metropolitan markets across Germany, the United Kingdom, and the coastal United States where transparency expectations outpace price sensitivity.
High-Concentrated Protein Market Segmentation
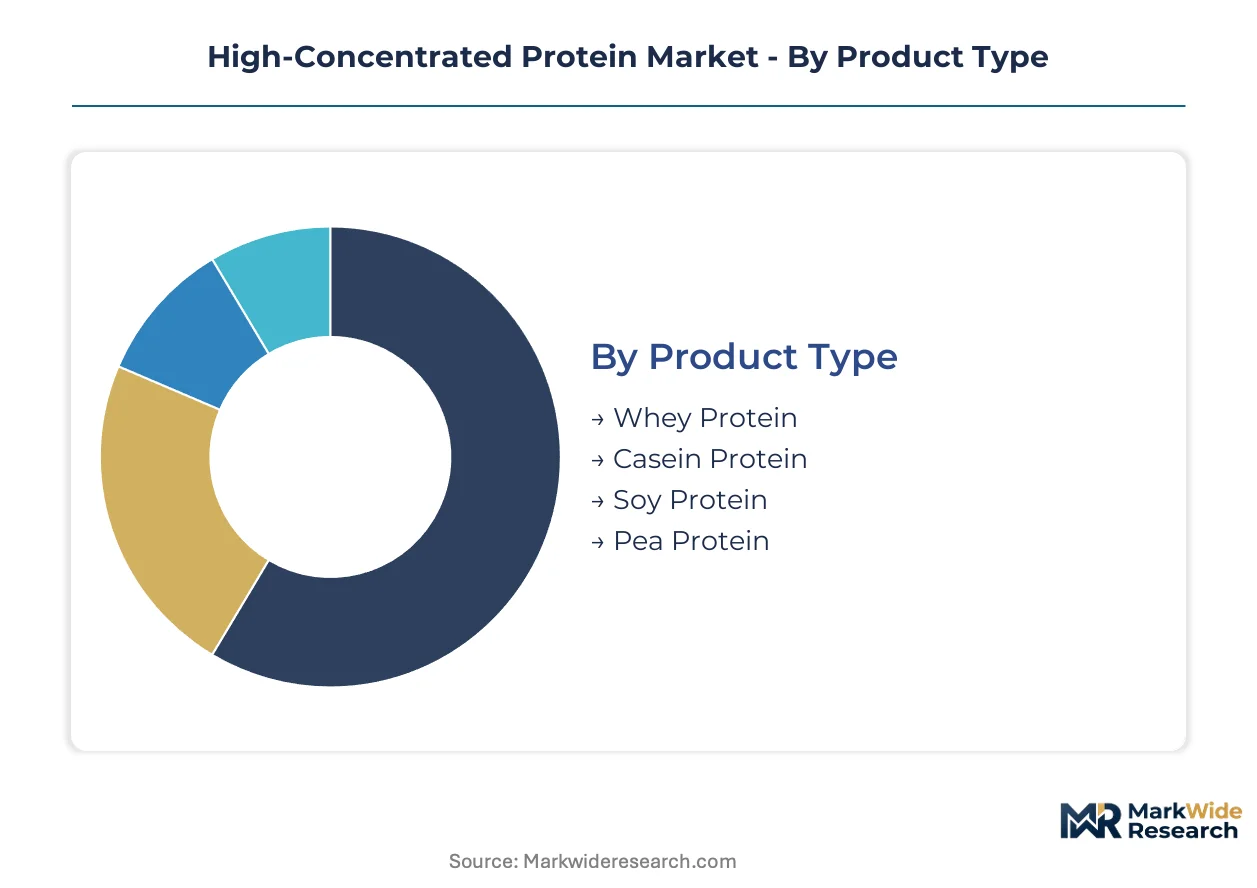
Segmentation in high-concentrated protein markets reveals how regulatory pathways and formulation requirements fragment commercial opportunity. Each dimension carries distinct certification burdens that determine market access velocity and margin structure.
Product Type:
Whey protein isolate and concentrate formulations require FDA GRAS self-affirmation for US market entry, while EFSA novel food authorizations govern pea protein positioning in European clean-label applications.
- Whey Protein:Ultrafiltration and ion exchange processes yield protein concentrations from 80% to 95%, with rapid absorption kinetics driving sports nutrition formulation. Demand concentrates in German retail chains serving endurance athletes, though New Zealand milk powder pricing volatility compresses margins during supply shocks.
- Pea Protein:Mechanical fractionation and aqueous extraction achieve 80-85% protein content with favorable allergen profiles. German and French functional food manufacturers are scaling formulations to meet EU Green Deal bioeconomy incentives for carbon footprint reduction claims.
- Casein Protein:Micellar casein production clusters in Scandinavian dairy cooperatives, creating single-source vulnerability for overnight recovery formulations requiring slow amino acid release kinetics.
- Soy Protein:Established supply chains and mature processing infrastructure support cost-competitive positioning, though allergen labeling requirements constrain clean-label applications in premium channels.
Whey protein sits at the top of the volume ranking, with pea protein climbing the fastest.
Application:
Formulation complexity and claim substantiation requirements vary sharply across end-use categories, with sports nutrition demanding the most intensive third-party testing protocols.
- Sports Nutrition:Powder and ready-to-drink formats targeting pre-workout, intra-workout, and recovery windows dominate commercial investment. German sports nutrition chains are expanding shelf space for endurance-focused formulations beyond historical bodybuilding concentration.
- Meal Replacement:Complete macronutrient profiles with sustained satiety positioning require micellar casein integration for overnight amino acid release functionality.
- Dietary Supplements:Capsule and tablet formats emphasize purity verification through third-party testing, with Amazon subscription models capturing transparency-focused consumers in metropolitan US markets.
- Functional Foods:Protein fortification of bakery, dairy, and snack applications demands heat-stable isolates that maintain functional integrity through processing.
Sports nutrition commands the largest revenue pool, while functional foods gain share fastest through mainstream retail penetration.
End User:
Purchasing behavior and price sensitivity diverge sharply across user archetypes, with performance-oriented segments accepting premium positioning for verified purity.
- Athletes:Endurance and team sport competitors prioritize batch-tested formulations with Informed Sport or NSF certification, driving consolidation around verified brands in specialty retail.
- Bodybuilders:Historical market anchor with high per-capita consumption, though segment growth moderates as recovery-focused positioning broadens appeal.
- Health-conscious Consumers:Clean-label and sustainability credentials drive purchasing decisions, with pea protein penetration strongest among this cohort.
- Nutritional Seekers:Aging demographics and wellness-focused populations seeking convenient protein supplementation represent emerging volume opportunity.
Athletes generate the highest per-unit margins, with nutritional seekers expanding most quickly through mainstream channel access.
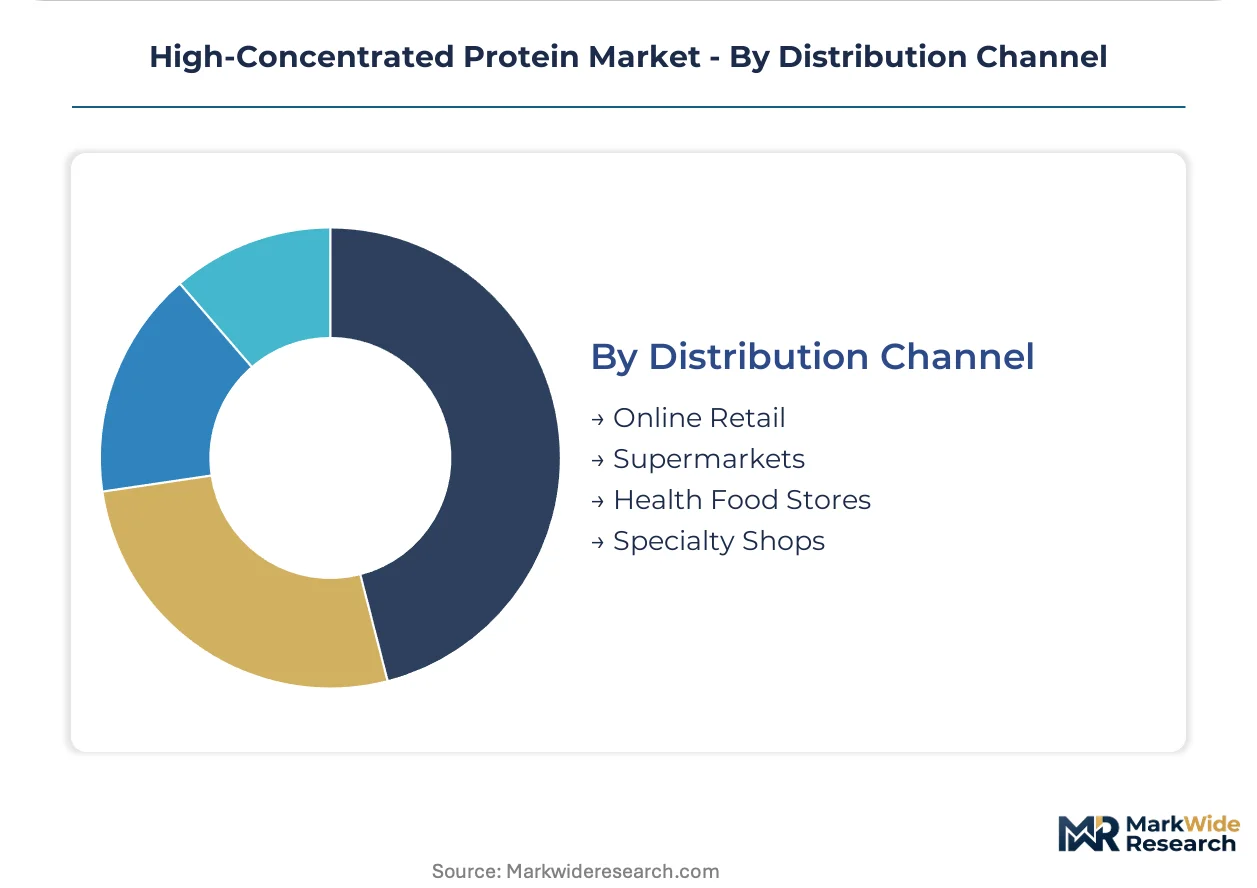
Distribution Channel:
Channel economics and customer acquisition costs determine viable product formats and pricing architecture, with direct-to-consumer models bypassing traditional retail markups.
- Online Retail:Amazon and specialized sports nutrition platforms capture subscription-based purchasing with loyalty programs, consolidating around certified clean-label products.
- Supermarkets:Mass-market penetration requires price-competitive positioning and simplified messaging, favoring established whey protein brands with consumer recognition.
- Health Food Stores:Staff recommendation influence and premium positioning support plant-protein and specialty isolate formats with higher margins.
- Specialty Shops:Gym-affiliated and independent sports nutrition retailers serve enthusiast consumers with personalized consultation and exclusive formulations.
Online retail leads volume contribution, with supermarkets advancing fastest through protein fortification of conventional food categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers seek jurisdictions with streamlined novel-food pathways and lower compliance friction. Cost-of-compliance gaps between EFSA-administered Europe and FDA-governed North America drive differential investment patterns in capacity expansion.
Germany
Sports nutrition retail chains in Munich and Frankfurt are scaling whey and plant-protein portfolios to serve endurance athletes beyond traditional bodybuilding segments. EFSA novel food authorizations for pea protein create streamlined market entry for clean-label formulators. The Bavarian dairy processing cluster around Ingolstadt anchors micellar casein production for overnight recovery formulations.
United States
Amazon and specialized sports nutrition platforms capture subscription-based purchasing with loyalty programs in metropolitan markets. FDA GRAS self-affirmation pathways enable faster ingredient market access compared to European counterparts. Idaho and California dairy cooperatives concentrate whey protein isolate capacity serving contract manufacturers nationwide.
China
NMPA filing requirements for imported nutritional ingredients extend market access timelines by 12-18 months for multinational suppliers. Domestic functional food manufacturers in Shanghai and Guangzhou are retrofitting facilities with membrane filtration cascade systems. The Yangtze River Delta cluster drives local pea protein fractionation capacity to reduce import dependency.
India
BIS protein quality standard harmonization creates first-mover advantage for suppliers establishing local blending and packaging infrastructure. Urban health-conscious consumers in Mumbai and Delhi-NCR drive pea protein penetration through e-commerce channels. The Maharashtra food processing corridor attracts contract manufacturing investment from Asia-Pacific ingredient suppliers.
United Kingdom
Clean-label certification requirements from major retailers displace unverified bulk protein powders in specialty channels. EFSA-aligned post-Brexit regulatory continuity maintains PDCAAS scoring disclosure obligations for front-of-pack claims. Greater London serves as the European headquarters location for sports nutrition brands targeting German and French retail expansion.
High-Concentrated Protein Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with dairy cooperatives dominating upstream concentrate supply and independent formulators capturing downstream margin. The vendor base clusters around three tiers: integrated dairy processors with captive milk supply, specialized ingredient refiners with membrane filtration expertise, and brand-holding marketers outsourcing production. Strategic moves concentrate on backward integration into milk powder sourcing and geographic expansion through regional distribution partnerships.
Within the integrated dairy processor tier, Fonterra Co-operative Group and Arla Foods Ingredients Group P/S exemplify New Zealand and Scandinavian supply-base anchoring respectively. Glanbia plc occupies a position among specialized ingredient refiners with Irish operational heritage. These three entities represent distinct geographic and structural archetypes: cooperative ownership with federated farmer supply, Scandinavian dairy cooperative concentration, and publicly listed specialist with R&D intensity.
| Leading Market Players |
|---|
| Fonterra Co-operative Group |
| Glanbia plc |
| Arla Foods Ingredients Group P/S |
| Cargill |
| Archer Daniels Midland Company |
| Idaho Milk Products |
| AMCO Proteins |
| Hilmar Cheese Company |
| Lactalis Ingredients |
| Others |
Value Network & Pricing Analysis
Food protein chemists with membrane filtration expertise in the Bavarian dairy processing cluster command premium compensation, widening the spread between economy-grade whey concentrates and pharmaceutical-grade isolates as labor-cost differentials transmit through tiered pricing structures.
Pricing Analysis
Distributor margins in German sports nutrition retail chains absorb 25-35 points before shelf placement, compressing formulator returns unless brands bypass intermediaries through Amazon subscription models or direct-to-consumer platforms. Three-tier pricing structure across premium, standard, and economy levels separates Informed Sport-certified isolates from conventional concentrates and unbranded bulk powders. Price differentiation hinges on third-party certification grade and volume scale, with endurance-focused athletes accepting 40-60% premiums for verified purity. Pricing pressure stems from New Zealand milk powder volatility transmitting directly to whey protein concentrate input costs. Health-conscious consumers in metropolitan markets exhibit lowest price sensitivity, while nutritional seekers in mass-market channels drive economy-tier volume.
Supply Chain Analysis
India's BIS protein quality standard harmonization and China's NMPA domestic-content preferences are reshaping sourcing patterns for multinational suppliers seeking streamlined market access. Production gravity centers on New Zealand for whey protein isolate, Germany for micellar casein, and the Yangtze River Delta for pea protein fractionation. Raw material dependencies include New Zealand skim milk powder, Canadian yellow pea protein isolate, and Scandinavian micellar casein. Single-source vulnerability clusters in Scandinavian dairy cooperatives for overnight recovery formulations. Distribution runs through Amazon and specialized sports nutrition platforms in metropolitan markets, with German retail chains anchoring European wholesale volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as athlete purchasing consolidates around certified clean-label products with third-party testing verification, displacing unverified bulk powders.
For Market Incumbents: Deepen backward integration into New Zealand milk powder sourcing to buffer margin compression from dairy input volatility. Expand micellar casein capacity in the Bavarian dairy cluster to reduce single-source dependency on Scandinavian cooperatives. Invest in FDA GRAS self-affirmation documentation capabilities to accelerate novel protein ingredient timelines against emerging plant-based competitors. For New Entrants and Emerging Players: Enter via the underpenetrated Indian market through local blending and packaging infrastructure in the Maharashtra food processing corridor. Target health-conscious consumers in Mumbai and Delhi-NCR with pea protein formulations leveraging EU Green Deal carbon footprint positioning. Pursue direct-to-consumer subscription models in North American metropolitan markets to bypass traditional retail markups. For Investors and Strategic Acquirers: Dairy cooperatives with captive milk supply are the most active acquirer in this space, consolidating membrane filtration expertise through specialist ingredient refiner acquisitions. Over the medium-term horizon, vertically integrated processors with multiproduct cascade systems represent the most defensible target archetype. Watch EFSA amino acid scoring methodology updates as the signal for reformulation investment cycles and premium-tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Cascade Retrofit | European functional food manufacturers in Germany compress capital recovery timelines while elevating minimum efficient scale thresholds. |
| Backward Integration into Milk Powder Sourcing | Fonterra and Arla anchor supply security against New Zealand pricing volatility through federated farmer supply bases. |
| Direct-to-Consumer Channel Launch | Subscription-based personalized protein services bypass traditional sports nutrition retail markups in metropolitan US markets. |
| Pea Protein Fractionation Capacity Buildout | Yangtze River Delta manufacturers reduce China NMPA import dependency while capturing EU Green Deal bioeconomy incentives. |
| Third-Party Certification Investment | Informed Sport and NSF verification displaces unverified bulk powders in German and UK specialty retail channels. |
Research Methodology
Multiple input streams — regulatory filing databases, trade flow records, and executive interview transcripts — were reconciled to construct supply-side and demand-side estimates. Primary interviews with membrane filtration R&D directors, sports nutrition brand managers, German retail category buyers, and dairy cooperative procurement leads informed operational assumptions. Secondary validation drew from EFSA novel food authorization registers, FDA GRAS notification logs, BIS protein quality standards, and New Zealand milk powder pricing indices. Bottom-up capacity modeling and top-down consumption estimates were triangulated against customs data and channel shipment records.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions anchored volume and value projections over the analysis window. Segmentation modeling captured whey, pea, casein, and soy protein variants across sports nutrition, meal replacement, dietary supplement, and functional food applications. CAGRs were derived from trend extrapolation of historical pricing and volume trajectories, adjusted for regulatory timeline impacts and channel shift dynamics. Forecast inputs included EFSA PDCAAS scoring compliance deadlines, China NMPA filing velocity, and Amazon subscription penetration rates in metropolitan markets.
Inputs from EFSA, FDA, and BIS regulatory databases were available through the study window; gaps in real-time channel inventory data introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions on clean-label certification adoption curves and membrane technology diffusion rates. A small set of triggers — EFSA amino acid scoring enforcement actions, New Zealand dairy cooperative supply disruptions, and China NMPA import policy shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Iron Supplement Market
Nutritional Supplements
Cod Liver Oil Market
Nutritional Supplements
Vegan Protein Powder Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Marine Collagen Powder Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Nutraceutical Gummies Market
Nutritional Supplements
US and Canada Beta Glucan Market
Nutritional Supplements
Hydrolyzed Whey Protein Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
Medium-Chain Triglycerides Market