
 Filled Cheese Market | 2026-2036
Filled Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Filled Cheese Market Analytics
Asset-light contract manufacturing and third-party dairy processing leases is fragmenting competitive access across the filled cheese value chain. Arla Foods leverages its European cooperative structure to sustain integrated milk sourcing advantages. Hochland SE specializes in private-label filled cheese production, occupying a defensible position in Central European retail channels. Lactalis Group controls extensive aging and blending infrastructure that anchors its supply reliability for industrial buyers.
Filled cheese denotes a processed dairy product wherein vegetable oils or fats partially or wholly replace milkfat, achieving target moisture and fat-in-dry-matter specifications through emulsification and heat treatment. Manufacturers employ melting salts and continuous cookers to secure sliceability, melt uniformity, and extended shelf stability for food service and retail applications. Cream cheese formulations command premium positioning in Southeast Asian supermarkets due to dessert and bakery application expansion. Food service distribution channels exhibit the fastest structural growth as hotel and restaurant chains standardize procurement across multi-country networks. Vacuum pack formats dominate industrial customer segments where portion control and logistics efficiency determine supplier selection.
EU EFSA compositional standards and FDA labeling requirements in the United States govern fat substitution disclosure and product identity definitions, directly constraining formulation flexibility and cross-border market access. BIS certification mandates in India create additional compliance layers for imported filled cheese derivatives. Stakeholders must monitor evolving dairy analogue regulations in target jurisdictions to preempt reformulation costs and secure sustained market participation.
Market Dynamics
EU dairy reform standards under the European Commission are tightening compositional thresholds for cheese analogues, forcing manufacturers to reconfigure fat substitution ratios and emulsification protocols across export-bound production lines.
Growth Catalysts
- Quick-service restaurant expansion:Southeast Asian chains are localizing menus with filled cheese variants tailored to regional taste profiles, creating sustained procurement pull from industrial processors in Indonesia and Vietnam.
- FSSAI harmonization efforts:India's food safety regulator is streamlining import clearance pathways for dairy analogues, reducing time-to-market for European and Southeast Asian suppliers targeting urban food processing corridors.
- Emulsification technology advances:Continuous cooker systems with precision moisture control are enabling cleaner-label formulations that meet both EU EFSA disclosure requirements and food service melt-performance specifications.
Market Restraints
- Palm oil price volatility:Vegetable fat inputs face commodity swings tied to Malaysian and Indonesian harvest cycles, compressing margin predictability for cost-plus contract manufacturers.
- EU supply concentration:Blending and aging infrastructure clusters in Germany, France, and the Netherlands create geographic vulnerability for buyers dependent on just-in-time industrial deliveries.
- Clean-label substitution threat:Natural cheese alternatives with modified milkfat profiles are capturing premium positioning in European retail channels where EFSA disclosure mandates heighten analogue stigma.
Strategic Opportunities
- Indonesian urban corridors:Jakarta and Surabaya food processing zones exhibit underpenetrated demand for cream cheese formulations targeting bakery and dessert manufacturing expansion.
- Hotel chain standardization:Multi-country procurement networks operated by regional hospitality groups are consolidating supplier lists, creating entry points for certified processors with vacuum-pack logistics capabilities.
- BIS certification leverage:India's quality standards body offers accelerated pathways for facilities meeting ISO dairy processing protocols, enabling first-mover positioning ahead of domestic capacity buildout.
Industry Challenges
- Emulsification chemistry expertise:Formulation scientists capable of balancing melt uniformity with extended shelf stability remain scarce across Southeast Asian technical centers.
- Dual-jurisdiction compliance timelines:Simultaneous FDA labeling reviews and EU EFSA compositional validations extend product launch cycles for cross-Atlantic suppliers.
- Legacy equipment retrofit costs:Continuous cooker upgrades required for precision moisture control demand capital commitments that strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Filled Cheese Market |
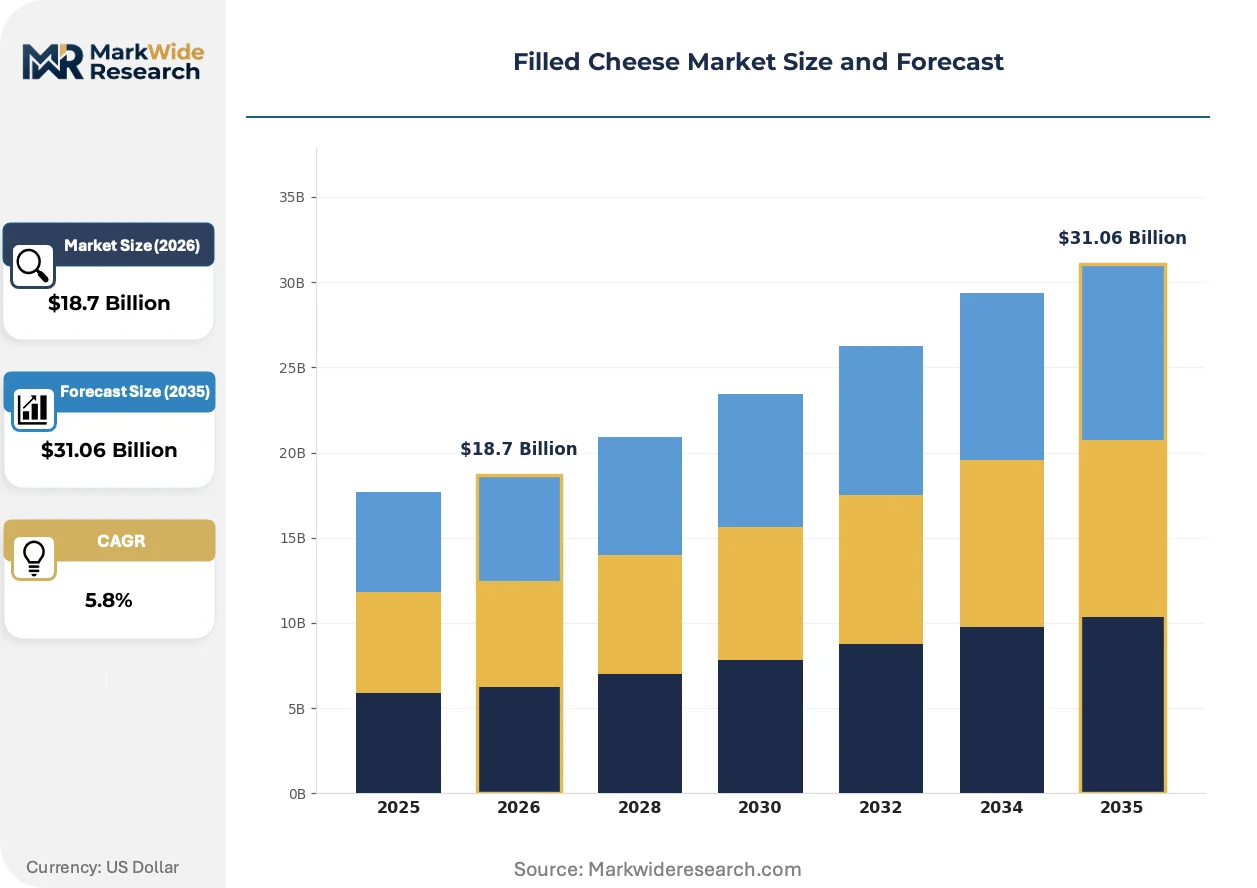
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Cheese, Cream Cheese, Processed Cheese, Spreadable Cheese Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Customer Type: Residential, Commercial, Industrial, Retail Packaging Type: Plastic Tub, Glass Jar, Vacuum Pack, Sachet |
| Companies Covered | Arla Foods, Fonterra Co-operative Group, Almarai, Bel Group, Hochland SE, Lactalis Group, Kraft Heinz Company, Savencia Fromage & Dairy, FrieslandCampina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Filled Cheese Market Evolving Landscape
Processing technology and regulatory disclosure mandates are compressing formulation flexibility while opening channel-specific positioning strategies for compliant manufacturers.
Enzyme-modified cheese (EMC) concentrates are achieving fat reduction targets without vegetable oil substitution, preserving dairy-origin labeling claims. Food service distributors in Singapore and Thailand are adopting EMC-based formulations at pace to meet hotel chain procurement specifications. Traditional filled cheese production reliant on palm oil and coconut fat blends is rendering obsolete for premium positioning segments.
REACH-aligned substance restrictions in the European Union are extending to food-contact materials used in vacuum packaging systems, forcing film supplier transitions. Industrial buyers dependent on extended shelf-life logistics face reformulation costs for compliant barrier layers. Southeast Asian exporters targeting EU markets are accelerating packaging material audits to preempt border rejection risks.
Consolidated procurement desks at regional quick-service restaurant headquarters are displacing fragmented distributor relationships with direct manufacturer contracts. Centralized tender processes in Indonesia and Malaysia now specify melt-performance benchmarks and certificate-of-analysis requirements previously handled informally. This pattern concentrates supplier selection power with processors capable of multi-country certification maintenance.
Filled Cheese Market Segmentation
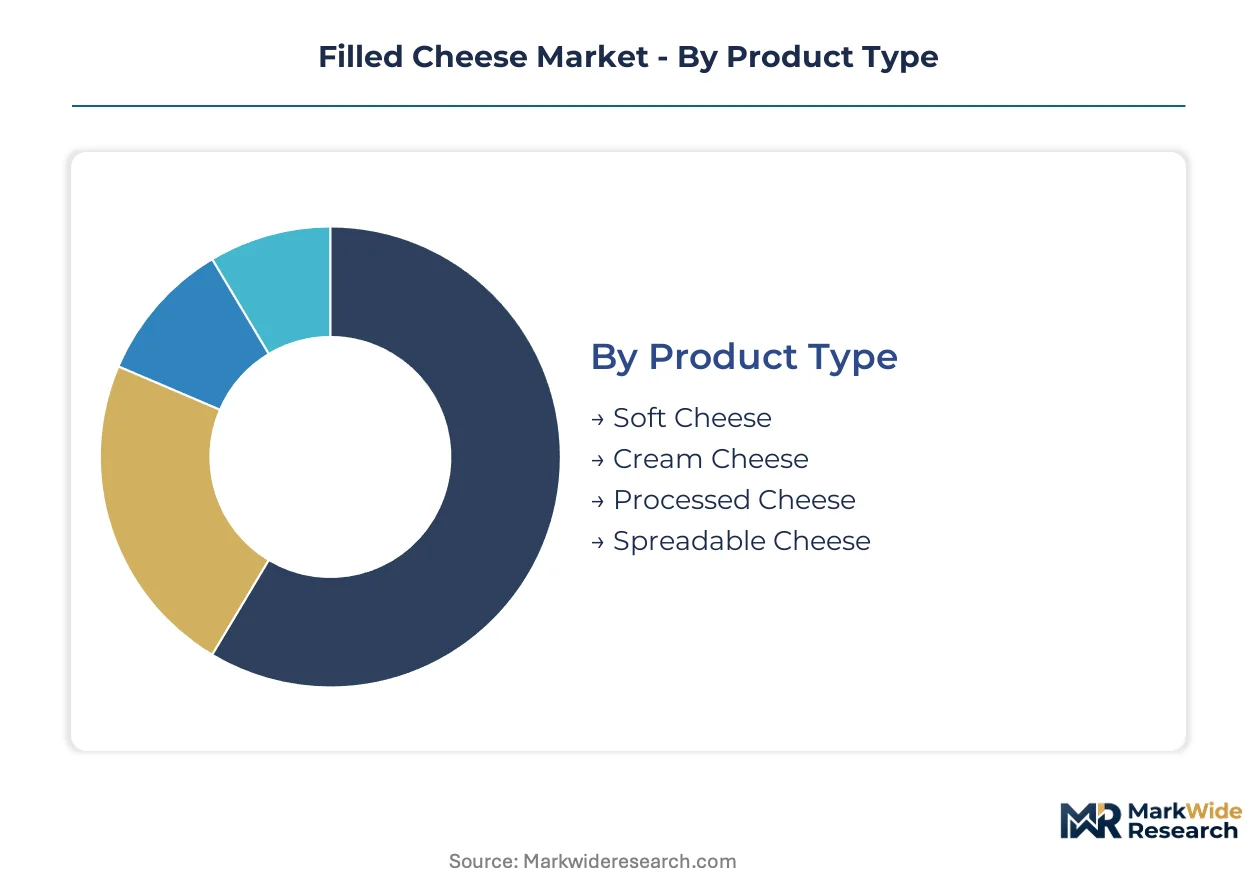
Segmentation in filled cheese markets reveals divergent technical requirements across distribution channels and end-use applications. Product formulation standards, packaging specifications, and procurement volumes vary sharply between industrial food processors and retail consumers, creating distinct competitive arenas for manufacturers.
Product Type:
Mature formats dominate volume throughput while emerging variants capture premium positioning through specialized functionality.
- Soft Cheese:Lower moisture content and reduced fat-in-dry-matter specifications suit industrial slicing and shredding operations. Bakery manufacturers in Indonesia's urban corridors specify soft cheese for consistent melt behavior in high-heat applications.
- Cream Cheese:Higher fat content and stabilized emulsion systems support dessert and confectionery applications. Southeast Asian supermarket chains report concentrated demand for cream cheese formulations targeting home baking expansion.
- Processed Cheese:Emulsifying salts and continuous cooker production enable extended shelf stability for food service distribution.
- Spreadable Cheese:Modified starch and hydrocolloid systems achieve pumpable textures for portion-controlled dispensing.
Processed cheese handles the majority of throughput; cream cheese is climbing the fastest on share.
Distribution Channel:
Channel economics separate high-volume contract supply from fragmented retail procurement with divergent margin structures.
- Food Service:Direct manufacturer relationships with hotel and restaurant chains specify melt-performance benchmarks and certificate-of-analysis requirements. Centralized procurement desks in Indonesia and Malaysia consolidate supplier lists around vacuum-pack logistics capabilities.
- Supermarkets:Private-label filled cheese occupies shelf space through standardized block and slice formats. Retail buyers in Vietnam prioritize cream cheese variants for dessert ingredient positioning.
- Online Retail:Cold-chain logistics constraints limit penetration to ambient-stable formulations in secondary cities.
- Specialty Stores:Curated import selections target expatriate and premium consumer segments with European-origin labeling.
Food service channels command the highest absolute volumes; online retail is expanding most quickly from a small base.
Customer Type:
Procurement scale and technical specification intensity create four distinct customer archetypes with non-overlapping supplier requirements.
- Industrial:Food processors in Jakarta and Surabaya specify filled cheese for standardized ingredient inputs across bakery and ready-meal production lines. Volume contracts tie pricing to palm oil commodity indices with quarterly adjustments.
- Commercial:Hotel chains operating multi-country networks demand consistent melt performance across kitchen equipment variations. Procurement standardization drives consolidation toward certified processors with multi-jurisdiction compliance.
- Retail:Supermarket and specialty store buyers manage SKU proliferation with turnover-based shelf allocation.
- Residential:Direct-to-consumer sales remain negligible outside premium import channels.
Industrial customers absorb the largest share of production volume; commercial procurement is gaining share fastest through chain standardization.
Packaging Type:
Packaging selection balances shelf-life extension against unit economics and regulatory compliance for target export markets.
- Vacuum Pack:Barrier film systems achieve extended ambient stability for industrial logistics and food service distribution. REACH-aligned substance restrictions in the European Union force film supplier transitions for exporters targeting EU markets.
- Plastic Tub:Injection-molded containers with tamper-evident closures dominate retail cream cheese presentation. Indonesian supermarkets specify tub formats for refrigerated display efficiency.
- Glass Jar:Premium positioning supports spreadable cheese variants in specialty retail channels.
- Sachet:Single-serve portions target food service condiment applications with portion control requirements.
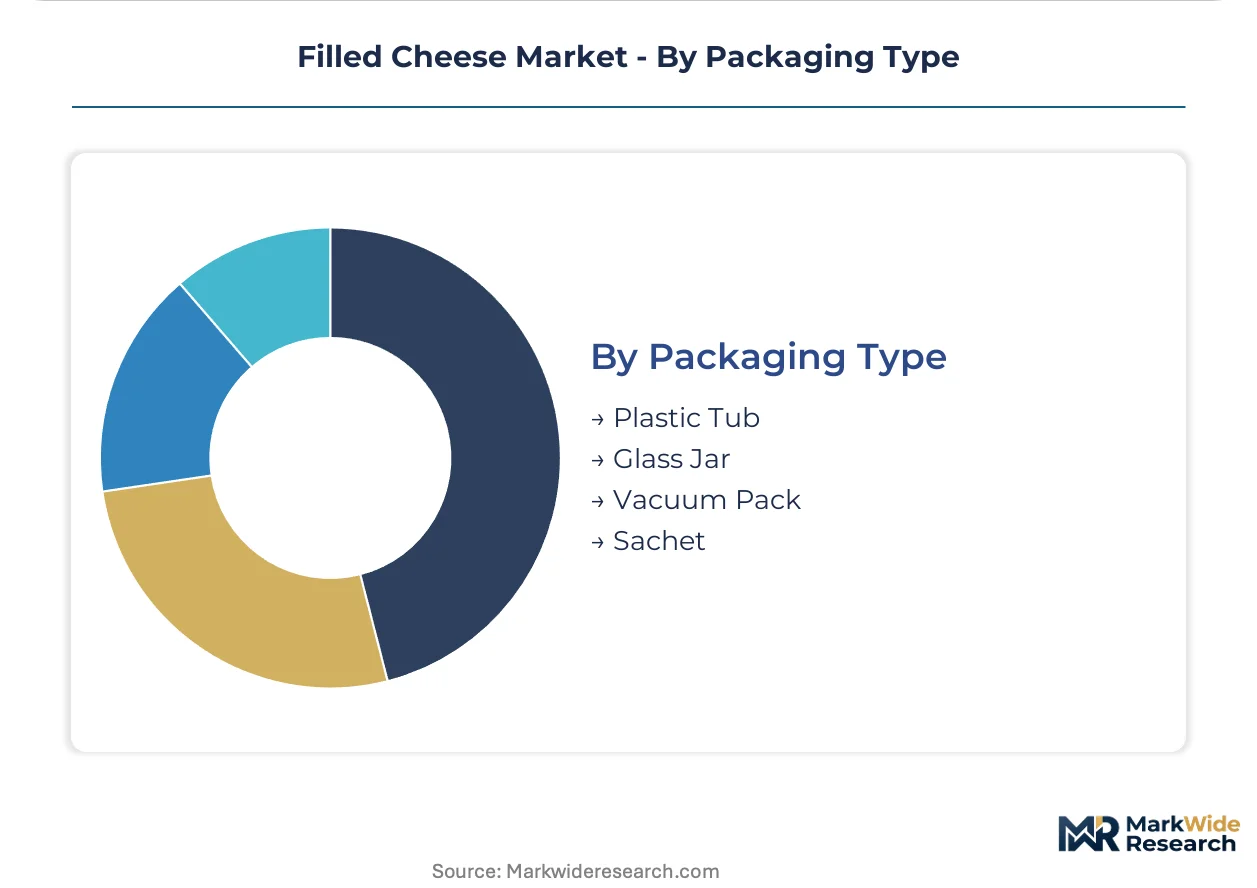
Vacuum pack formats handle the majority of industrial throughput; plastic tub configurations are expanding fastest in retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU EFSA compositional standards are tightening fat substitution thresholds, reshaping export-bound production configurations across multiple jurisdictions. FSSAI harmonization in India is streamlining import pathways for dairy analogues. Southeast Asian procurement desks are consolidating supplier lists around multi-country certification capabilities.
Germany
Blending and aging infrastructure clusters in Bavaria and Baden-Württemberg anchor industrial supply reliability for EU-wide distribution. REACH-aligned substance restrictions extend to food-contact materials, forcing film supplier transitions for vacuum-pack exporters. Hochland SE maintains private-label production dominance across Central European retail channels through cooperative milk sourcing structures.
United States
FDA labeling requirements govern fat substitution disclosure and product identity definitions, constraining formulation flexibility for cross-Atlantic suppliers. Commercial procurement desks at quick-service restaurant headquarters are displacing fragmented distributor relationships with direct manufacturer contracts. Kraft Heinz Company occupies a defensible position in retail processed cheese segments through brand portfolio depth.
Indonesia
Jakarta and Surabaya food processing corridors exhibit concentrated demand for cream cheese formulations targeting bakery and dessert manufacturing expansion. BIS certification creates compliance layers for imported filled cheese derivatives entering through regional distribution networks. Lactalis Group leverages extensive aging infrastructure to secure volume contracts with industrial processors specifying palm oil-indexed pricing adjustments.
India
FSSAI import clearance pathway streamlining reduces time-to-market for European and Southeast Asian suppliers targeting urban food processing corridors. Maharashtra and Gujarat dairy processing zones are accelerating domestic capacity buildout ahead of accelerated foreign supplier entry. Arla Foods sustains integrated milk sourcing advantages through cooperative structures that bypass commodity input volatility.
France
EMA-aligned quality protocols intersect with EFSA analogue compositional mandates, creating dual compliance timelines for export-oriented processors. Île-de-France and Auvergne-Rhône-Alpes clusters concentrate industrial R&D capabilities for emulsification chemistry advancement. Savencia Fromage & Dairy exemplifies the specialty dairy processor archetype with positioning across both traditional and analogue cheese categories.
Filled Cheese Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. Food service distribution consolidation favors processors with multi-country certification maintenance capabilities, while retail private-label contracts reward scale-efficient block and slice producers. Three archetypes dominate: cooperative-structured milk integrators, private-label contract manufacturers, and brand-holding consumer goods conglomerates. Competitive moves concentrate on strategic partnerships with quick-service restaurant procurement desks and packaging material compliance upgrades for REACH-aligned export markets.
Within the cooperative-structured tier, Arla Foods and Fonterra Co-operative Group exemplify milk supply integration models that buffer input cost volatility. Hochland SE occupies a position among Central European private-label specialists serving retail channel consolidation trends. At the diversified conglomerate end, Lactalis Group anchors industrial buyer relationships through captive blending and aging infrastructure spanning multiple jurisdictions.
| Leading Market Players |
|---|
| Arla Foods |
| Fonterra Co-operative Group |
| Almarai |
| Bel Group |
| Hochland SE |
| Lactalis Group |
| Kraft Heinz Company |
| Savencia Fromage & Dairy |
| FrieslandCampina |
| Others |
Value Network & Pricing Analysis
Undercapacity in Indonesian blending facilities drives aggressive contract bidding from European exporters while compressing margin buffers for mid-scale processors caught between palm oil-indexed input volatility and fixed-price food service commitments.
Pricing Analysis
Certification level creates the primary spread between EU EFSA-compliant export grades and domestic-market formulations. Contract-based long-term offtake dominates industrial procurement, with volume scale and multi-jurisdiction compliance as the principal differentiation drivers. Pricing pressure stems from palm oil commodity swings tied to Malaysian and Indonesian harvest cycles, eroding predictability for cost-plus manufacturers. Industrial food processors exhibit highest price sensitivity due to ingredient cost pass-through limitations, while hotel chains operating multi-country networks prioritize melt-performance consistency over unit cost.
Supply Chain Analysis
Extended payment terms from Indonesian quick-service restaurant procurement desks strain working capital for mid-tier processors without supply-chain finance facilities. Production gravity centers on Germany, France, and the Netherlands for blending and aging infrastructure, with Indonesia and Vietnam as emerging processing corridors. Raw material flows draw from Malaysian palm oil estates, European dairy protein concentrates, and Southeast Asian coconut fat refineries. Single-source vulnerability concentrates in REACH-aligned barrier film suppliers facing forced transitions. Distribution runs through food service distributors consolidating around vacuum-pack logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping supplier-buyer relationships as quick-service restaurant procurement desks consolidate tender processes around interoperable melt-performance benchmarks and certificate-of-analysis standards.
For Market Incumbents: Build regulatory moats through preemptive EU EFSA and FDA dual-certification investments ahead of compositional threshold tightening. Anchor supply reliability by securing captive blending infrastructure in Indonesia's urban food processing corridors. Deepen backward integration into palm oil refining to buffer commodity input volatility threatening margin stability.
For New Entrants and Emerging Players: Build out cream cheese formulation capabilities targeting Jakarta and Surabaya bakery manufacturing expansion, the most penetrable white-space segment. Exploit BIS certification accelerated pathways for ISO-compliant facilities entering India's urban corridors. Lead with direct manufacturer contracts displacing fragmented distributor relationships in Indonesian hotel chain procurement.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous cooker upgrade cycles required for precision moisture control compliance. Target acquisition archetypes are private-label contract manufacturers with established Central European retail channel positioning and REACH-aligned packaging material audit completion. Monitor emulsification chemistry talent scarcity across Southeast Asian technical centers as inflection indicator for competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Jurisdiction Certification Investment | Preemptive EU EFSA and FDA alignment secures cross-Atlantic market access ahead of reformulation mandates. |
| Backward Integration into Palm Oil Refining | Captive supply of vegetable fat inputs buffers margin compression from Malaysian and Indonesian harvest volatility. |
| Continuous Cooker Technology Upgrade | Precision moisture control enables cleaner-label formulations meeting both regulatory disclosure and melt-performance specifications. |
| Indonesian Urban Corridor Capacity Buildout | Jakarta and Surabaya proximity reduces logistics costs for cream cheese formulations targeting bakery expansion. |
| REACH-Aligned Packaging Material Transition | Barrier film supplier audits preempt EU border rejection risks for vacuum-pack exporters. |
Research Methodology
Cross-validation between executive interviews and trade data anchors the qualitative findings in observable procurement patterns. Primary fieldwork engaged formulation scientists at emulsification technology providers, procurement directors at Indonesian quick-service restaurant headquarters, and logistics managers at food service distribution networks. Secondary validation drew from EU EFSA compositional standard filings, FSSAI import clearance records, BIS certification registries, and palm oil commodity exchange data. Bottom-up volume modeling triangulated against top-down spending estimates across the analysis window.
Calibration against historical capacity utilization rates and contract announcement patterns shaped the projection framework. Segmentation dimensions modeled include product type, distribution channel, customer archetype, and packaging format, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from slope analysis of segment-level growth trajectories. Forecast inputs incorporated emulsification technology adoption curves and quick-service restaurant procurement desk consolidation timelines.
Sensitivities concentrate around EU dairy reform standard implementation timelines and palm oil price volatility amplitude. Forecasts reflect documented assumptions regarding FSSAI harmonization progress and BIS certification pathway efficiency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
UHT Milk Market
Dairy Products
Global Dairy Cream Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Cream Powder Market
Dairy Products
North America Casein Market
Dairy Products
Milk Retentate Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Organic Milk Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Europe Dairy Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Low Cholesterol Cheese Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Canada Dairy Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Probiotic Fermented Milk Market