
 Sour Milk Drinks Market | 2026-2036
Sour Milk Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Sour Milk Drinks Market Analysis
Supermarket dairy aisles is reconfiguring around functional probiotic positioning as sour milk drinks migrate from ethnic niches to mainstream refrigerated sets. Yakult Honsha Co., Ltd. leverages its dedicated cooler infrastructure to control point-of-sale placement in Asian and European markets. Danone S.A. competes through broad yogurt drink portfolios that span multiple price tiers and flavor profiles. Lifeway Foods, Inc. specializes in kefir-based formulations that target digestive wellness claims in North American retail channels.
Sour milk drinks comprise fermented dairy beverages produced through controlled bacterial culture of lactose into lactic acid, typically containing live probiotic colonies exceeding 10^6 CFU per milliliter at consumption, with pH ranges between 3.8 and 4.6 depending on fermentation duration and strain selection. These products serve commercial purposes spanning digestive health supplementation, meal replacement convenience, and culinary ingredient applications across food service and home consumption. Kefir commands premium shelf positioning due to its complex symbiotic culture matrix and associated gut microbiome marketing, while yogurt drinks dominate volume throughput through familiar taste profiles and lower per-unit pricing. Tetra packs capture ambient distribution advantages in emerging markets where cold-chain infrastructure remains fragmented, though bottles sustain refrigerated premium positioning in mature European and North American retail environments.
FDA oversees probiotic labeling claims and GRAS determinations for bacterial strains used in US-manufactured sour milk drinks, while EFSA evaluates health claim substantiation across European Union member states under Nutrition and Health Claims Regulation 1924/2006. BIS standards in India govern microbial limits and adulteration testing for cultured milk products entering formal retail channels. Stakeholders must monitor evolving strain-specific approval pathways and refrigeration energy standards as regulatory frameworks tighten around live-culture viability thresholds and sustainability reporting obligations.
Market Dynamics
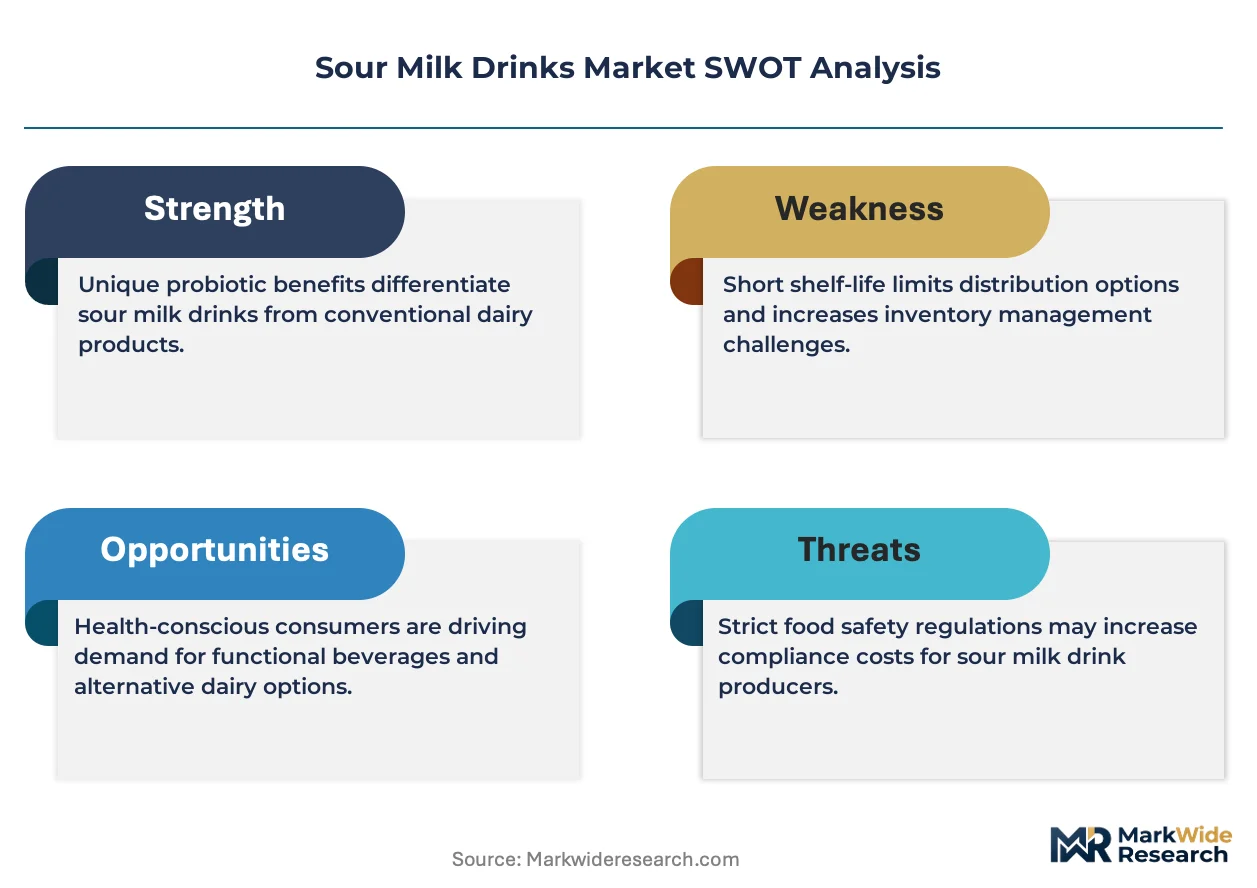
The EU Green Deal and F-Gas Regulation are compressing cold-chain economics for probiotic beverages, forcing logistics networks to absorb refrigerant transition costs while shelf-space competition intensifies in German retail channels.
Growth Catalysts
- Probiotic health claim frameworks:EFSA's evolving guidance on gut microbiome substantiation is opening formal marketing pathways for kefir and yogurt drink manufacturers across EU member states.
- India:BIS standards for cultured milk products are formalizing quality benchmarks that accelerate branded product penetration into organized retail channels previously dominated by unorganized vendors.
- Precision fermentation:Strain optimization technologies are reducing production variability and extending viable shelf life for ambient-stable sour milk formulations in emerging markets.
Market Restraints
- Refrigerant cost volatility:F-Gas Regulation phase-down schedules are elevating cold-chain operating expenses for live-culture distribution networks dependent on conventional cooling systems.
- Supply concentration in German retail:Discounter consolidation in Germany's grocery sector is compressing supplier margins and limiting shelf access for mid-tier kefir brands.
- Plant-based substitution:Oat and almond fermented beverages are capturing digestive health positioning without cold-chain dependency, eroding sour milk's functional differentiation.
Strategic Opportunities
- Indonesia:Cold-chain infrastructure gaps in Indonesian retail create first-mover advantage for ambient-stable tetra-pack kefir formats with extended shelf stability.
- Direct-to-subscription channels:Recurring delivery models for probiotic beverages are bypassing traditional retail slotting fees while capturing consumer loyalty through personalized strain formulations.
- EU CSRD alignment:Sustainability reporting mandates are creating procurement preference for suppliers with verified carbon footprint reductions in fermentation energy use.
Industry Challenges
- Microbiome assay standardization:Inconsistent CFU enumeration methodologies across laboratories are complicating label claim defensibility and cross-border regulatory approvals.
- Legacy dairy infrastructure retrofitting:Converting conventional fluid milk plants to aseptic probiotic processing requires capital-intensive clean-room installations and specialized CIP systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sour Milk Drinks Market |
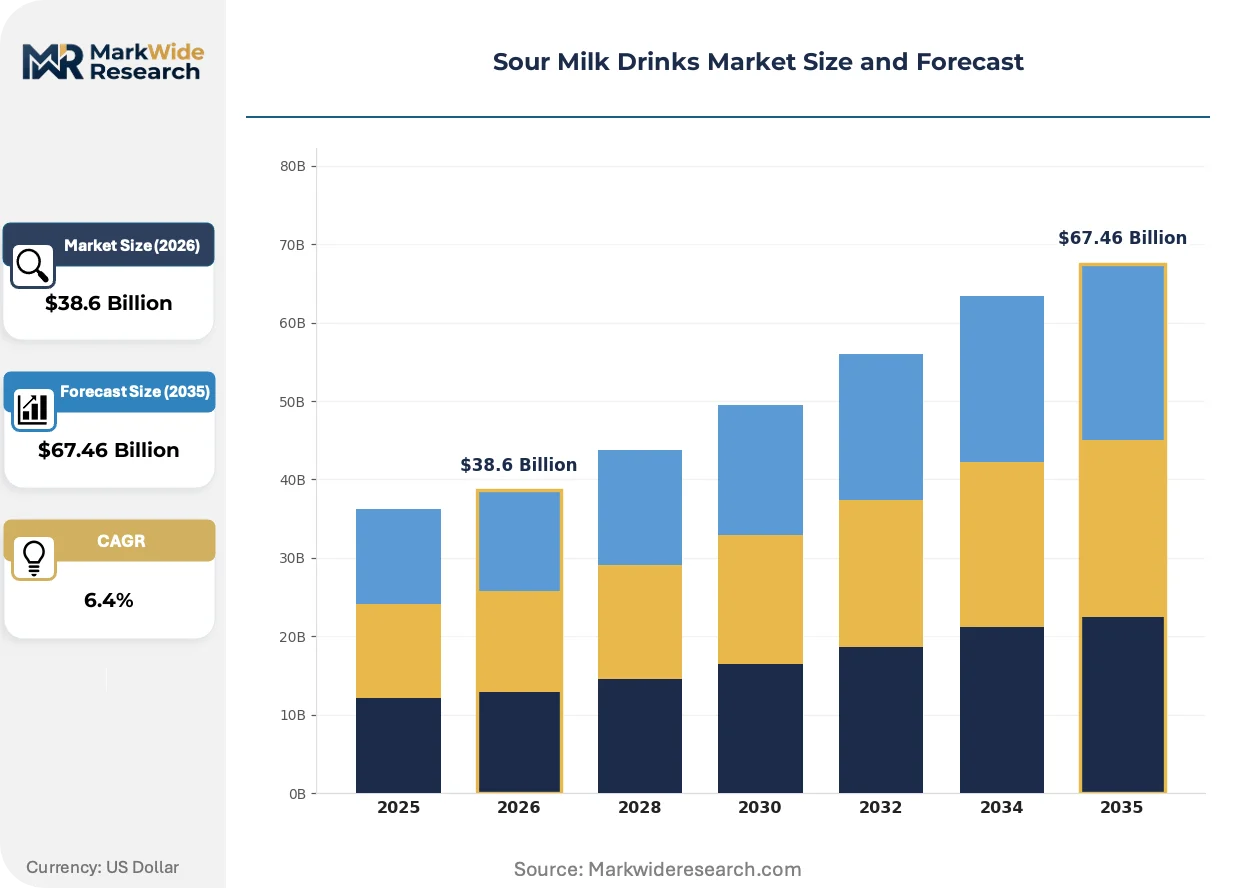
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kefir, Yogurt Drink, Buttermilk, Cultured Milk End User: Retail Consumers, Food Service, Health Enthusiasts, Older Adults Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops |
| Companies Covered | Yakult Honsha Co., Ltd., Lifeway Foods, Inc., Danone S.A., FrieslandCampina, Amul Dairy, Nestlé S.A., Arla Foods amba, Meiji Holdings Co., Ltd., Lactalis Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sour Milk Drinks Market Emerging Trajectories
Controlled-atmosphere packaging and strain-specific formulation are redefining how sour milk drinks compete on viability claims and convenience dimensions.
High-pressure processing is rendering obsolete conventional thermal pasteurization for ambient kefir lines. German and Japanese manufacturers are adopting HPP for extended-shelf-life products without probiotic kill-off. This technology is rendering obsolete the traditional trade-off between distribution reach and live-culture guarantees.
REACH chemical safety assessments are expanding scrutiny of packaging migrants into fermented dairy matrices. Industrial consequence includes accelerated migration toward glass and certified polymer barriers. Premium kefir segments in France and Benelux markets are responding with explicit non-BPA labeling and supply chain audit disclosures.
Health-conscious consumers are prioritizing strain-specific transparency over generic probiotic counts. German retail buyers are demanding QR-linked batch traceability showing documented CFU stability through shelf life. This behavioral pivot is most visible in Berlin and Munich organic retail channels where kefir price premiums correlate directly with verifiable culture matrices.
Sour Milk Drinks Market Segmentation
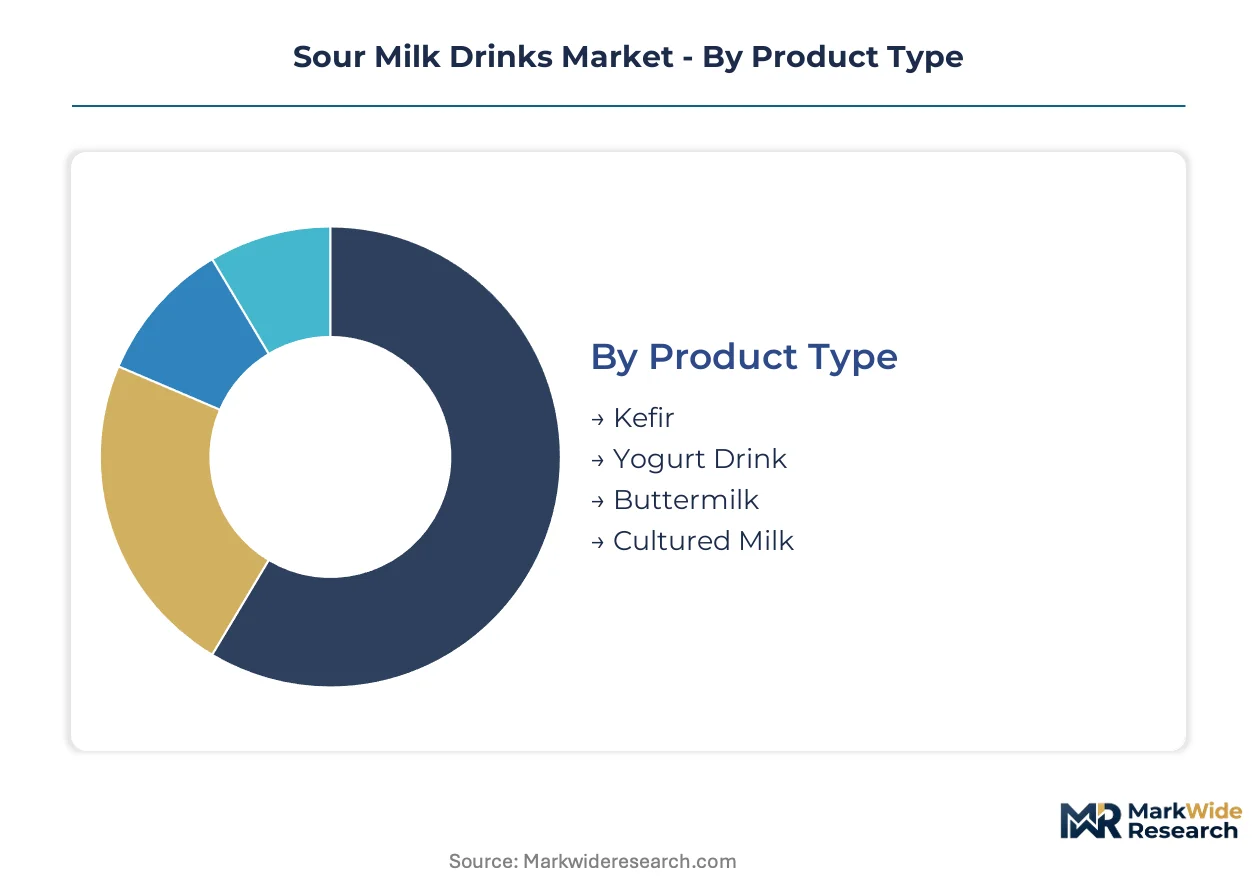
Sour milk drinks demand fragments across consumption occasions, health positioning, and cold-chain accessibility. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape competitive strategy.
Product Type:
Use-case spectrum spans meal replacement convenience through targeted digestive supplementation, with fermentation complexity driving price tier separation.
- Kefir:Complex symbiotic culture matrix of bacteria and yeast delivers broader microbiome diversity claims. German organic retail channels in Berlin and Munich command price premiums correlating with verifiable CFU stability through shelf life. Established volume favors Kefir; emerging adoption favors Cultured Milk.
- Yogurt Drink:Standardized Lactobacillus and Streptococcus thermophilus fermentation yields familiar taste profiles at accessible price points. Volume concentrates in mass-market retail sets across US and European supermarket dairy aisles where brand recognition reduces education costs.
- Buttermilk:Traditional lactic acid fermentation of residual cream liquid, positioned for baking and culinary applications rather than direct probiotic consumption.
- Cultured Milk:Simplified fermentation protocols enable ambient-stable tetra-pack formats for cold-chain-constrained emerging markets.
Established volume favors Yogurt Drink; emerging adoption favors Kefir.
End User:
Customer type determines strain specificity requirements and channel access economics.
- Health Enthusiasts:Strain-level transparency demands dominate purchasing decisions, with QR-linked batch traceability becoming table stakes. Direct-to-subscription channels capture loyalty through personalized formulations bypassing retail slotting fees. Established volume favors Retail Consumers; emerging adoption favors Health Enthusiasts.
- Retail Consumers:Familiarity-driven purchasing in supermarket dairy aisles prioritizes taste consistency and price predictability over microbiome complexity.
- Food Service:Bulk format requirements and inventory turnover constraints favor extended-shelf-life ambient products over refrigerated live-culture lines.
- Older Adults:Digestive wellness claims with texture-modified formulations address swallowing difficulty and medication interaction concerns.
Established volume favors Retail Consumers; emerging adoption favors Health Enthusiasts.
Packaging Type:
Margin tier tracks cold-chain dependency and shelf-stability engineering investment.
- Tetra Packs:Aseptic filling technology enables ambient distribution in Indonesian and Indian retail where refrigeration infrastructure remains fragmented. REACH chemical safety assessments are accelerating migration toward certified polymer barriers. Established volume favors Bottles; emerging adoption favors Tetra Packs.
- Bottles:Refrigerated premium positioning in mature European and North American markets sustains live-culture viability guarantees and transparent branding.
- Cans:Aluminum barrier properties suit extended ambient shelf life for outdoor and convenience store channels.
- Pouches:Flexible format reduces shipping cube and material cost for single-serve children's products.
Established volume favors Bottles; emerging adoption favors Tetra Packs.
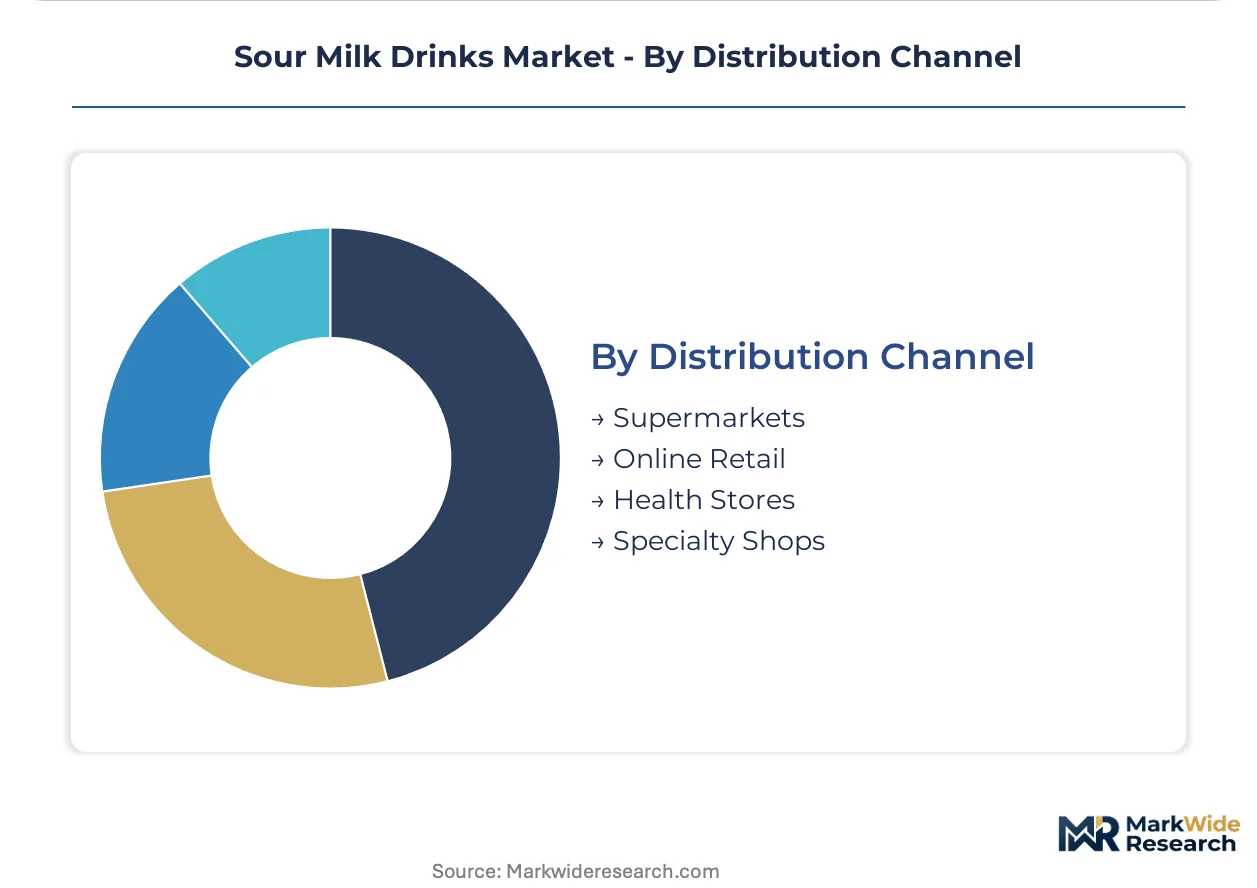
Distribution Channel:
Supply concentration shapes margin retention and regulatory compliance burden.
- Supermarkets:Discounter consolidation in Germany compresses supplier margins while controlling shelf access for mid-tier brands. F-Gas Regulation refrigerant transition costs concentrate in this channel's cold-chain infrastructure. Established volume favors Supermarkets; emerging adoption favors Online Retail.
- Online Retail:Recurring delivery models capture consumer loyalty through subscription mechanics while avoiding slotting fee structures.
- Health Stores:Strain-specific transparency and organic certification requirements align with premium kefir positioning in urban clusters.
- Specialty Shops:Ethnic grocery channels sustain traditional buttermilk and kefir varieties for diaspora populations.
Established volume favors Supermarkets; emerging adoption favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cold-chain rail corridors linking Rotterdam to Duisburg anchor European distribution networks for temperature-sensitive probiotic beverages. This infrastructure underwrites Germany's dominance in kefir throughput while shaping logistics economics across adjacent markets.
Germany
Discounter consolidation in grocery retail compresses supplier margins while expanding shelf space for functional dairy. The F-Gas Regulation forces refrigerant transitions across cold-chain networks, elevating operating costs for live-culture distribution. Berlin and Munich organic retail channels command price premiums correlating with verifiable CFU stability claims.
United States
FDA GRAS determinations for novel bacterial strains open formulation pathways for digestive wellness positioning. Health enthusiasts drive demand for QR-linked batch traceability showing documented viability through shelf life. Direct-to-subscription channels in California and New York Metro bypass traditional retail slotting fees while capturing consumer loyalty.
India
BIS standards for cultured milk products formalize quality benchmarks that accelerate branded penetration into organized retail. Cold-chain fragmentation favors ambient-stable tetra-pack formats for mass-market distribution. Maharashtra and Gujarat dairy cooperatives leverage existing fluid milk infrastructure to enter fermented beverage segments.
Japan
METI energy efficiency standards reshape refrigeration requirements for probiotic beverage logistics. Dedicated cooler infrastructure controls point-of-sale placement in convenience retail channels. Tokyo-Osaka urban corridors sustain premium positioning for strain-specific live-culture products with documented viability guarantees.
Indonesia
Port infrastructure gaps in cold-chain distribution create first-mover advantage for shelf-stable formulations. Ambient tetra-pack kefir formats bypass refrigeration dependency in Java and Sumatra retail networks. Local dairy processors partner with multinational technology licensors to establish aseptic filling capacity.
Sour Milk Drinks Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational dairy conglomerates with dedicated probiotic infrastructure, regional specialists in kefir and yogurt drink formulations, and emerging ambient-stable processors targeting cold-chain-constrained markets. Dominant competitive moves include backward integration into bacterial strain development and geographic licensing partnerships to bypass capital-intensive clean-room installations.
Within the multinational tier, Yakult Honsha Co., Ltd., Danone S.A., and Lifeway Foods, Inc. exemplify divergent infrastructure strategies. Yakult Honsha Co., Ltd. anchors its positioning through controlled point-of-sale cooler networks. Danone S.A. occupies a broad portfolio position spanning multiple price tiers and flavor profiles. Lifeway Foods, Inc. represents the specialist archetype with concentrated kefir-based formulations targeting digestive wellness claims in North American channels.
| Leading Market Players |
|---|
| Yakult Honsha Co., Ltd. |
| Lifeway Foods, Inc. |
| Danone S.A. |
| FrieslandCampina |
| Amul Dairy |
| Nestlé S.A. |
| Arla Foods amba |
| Meiji Holdings Co., Ltd. |
| Lactalis Group |
| Others |
Supply Flow & Price Mechanics
F-Gas Regulation refrigerant phase-down schedules compress cold-chain operating margins while simultaneously dictating distribution network topology for live-culture beverages. This regulatory chokepoint forces pricing tier spreads that penalize refrigerated premium positioning and reward ambient-stable formulations, reshaping supplier investment priorities across German retail channels and emerging market entry strategies.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between kefir manufacturers and German discounter chains, with annual offtake commitments commanding double-digit percentage reductions against spot pricing. Certification grade under EFSA health claim frameworks and organic accreditation status drive price differentiation between mass-market yogurt drinks and premium kefir lines. Pricing pressure stems from plant-based fermented beverage substitution eroding functional positioning premiums. Health enthusiasts exhibit lowest price sensitivity, while retail consumers in supermarket dairy aisles prioritize per-unit affordability over strain-specific transparency.
Supply Chain Analysis
Upstream feedstock sourcing draws from dairy cooperative networks concentrated in Germany, India, and the United States, with regional fluid milk prices directly determining fermentation input costs. Bacterial strain libraries, aseptic packaging films, and refrigerated logistics capacity constitute critical component dependencies. Single-source vulnerability concentrates in specialized probiotic culture suppliers holding exclusive strain patents. Distribution runs through cold-chain rail corridors in Europe and direct-to-subscription channels in North America, with ambient tetra-pack formats bypassing refrigeration requirements in Indonesian and Indian retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: EFSA health claim substantiation requirements and FDA GRAS determinations for novel strains create multi-year approval barriers that protect incumbent formulation advantages against rapid competitive replication.
For Market Incumbents: Insulate refrigerated premium positioning by securing dedicated cooler infrastructure contracts with German discounter chains before F-Gas Regulation compliance costs escalate. Backward integration into bacterial strain development reduces dependency on external culture suppliers while building proprietary microbiome diversity claims that resist plant-based substitution threats.
For New Entrants and Emerging Players: Pursue ambient-stable tetra-pack kefir formats for Indonesian and Indian retail channels where cold-chain fragmentation blocks incumbent refrigerated distribution. Direct-to-subscription models in California and New York Metro bypass supermarket slotting fee structures while capturing health enthusiast loyalty through personalized strain formulations.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialists with verified CFU stability documentation and clean-room fermentation capacity. Acquisition targets should demonstrate strain-specific IP portfolios and established relationships with dairy cooperatives in Maharashtra or Gujarat. Watch EFSA guidance evolution on gut microbiome substantiation as the inflection signal for premium pricing power expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | HPP technology eliminates thermal pasteurization trade-offs for ambient kefir lines in Japanese and German manufacturing. |
| Strain Patent Portfolio Expansion | Exclusive bacterial culture IP blocks competitor replication of documented CFU stability claims in organic retail channels. |
| Direct-to-Subscription Channel Launch | Recurring delivery mechanics capture health enthusiast loyalty while avoiding German discounter margin compression. |
| Aseptic Tetra-Pack Capacity Buildout | Ambient distribution enables Indonesian and Indian market entry without cold-chain infrastructure investment. |
| EFSA Health Claim Substantiation Investment | Formal marketing pathways for gut microbiome positioning unlock premium pricing in EU member state retail. |
Methodological Framework
A spread of perspectives from dairy cooperative procurement directors, kefir brand managers, refrigerated logistics operators, and EFSA regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against BIS standards documentation, EU Green Deal implementation reports, FDA GRAS notification databases, and Nielsen retail audit data for fermented dairy categories. Bottom-up volume modeling triangulated against top-down market sizing from customs trade records and dairy industry association statistics.
Demand-supply-balance framing anchored the forecast framework, with consumption occasion segmentation, health positioning tiers, and cold-chain accessibility dimensions modeled across the projection horizon. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory intervention effects and technology adoption curves. Strain-specific approval pathways and F-Gas Regulation compliance cost curves served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in dairy commodity prices, refrigerant cost volatility, or consumer discretionary spending would shift the trajectory. Cross-checking against external benchmarks including dairy cooperative production disclosures and refrigerated logistics capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cheese Concentrate Market
Dairy Products
United States Dairy Market
Dairy Products
Disposable Curd Cups Market
Dairy Products
Solidified Yogurt Market
Dairy Products
Hydrolyzed Casein Market
Dairy Products
Fat-Rich Dairy Products Market
Dairy Products
Organic Cheese Powder Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Canada Dairy Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Lactic Butter Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Europe Cow Milk Minerals Market