
 Europe Chocolate Milk Market | 2026-2036
Europe Chocolate Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Chocolate Milk Market Foresight
Supermarket private-label expansion is reshaping how chocolate milk reaches European households. Royal FrieslandCampina NV leverages its dairy cooperative structure to secure raw milk supply across the Netherlands and Germany. Danone SA anchors its position through specialized nutrition positioning in adult and sports-oriented chocolate milk variants. Arla Foods competes via farmer-owned distribution scale that spans Nordic and British retail channels.
Europe chocolate milk comprises pasteurized or UHT-treated dairy liquid blended with cocoa solids, sugar, and emulsifiers, typically containing 1-3% fat and standardized to 8-12% milk solids non-fat for shelf-stable or refrigerated distribution. Its primary commercial purpose is to deliver flavored dairy nutrition to children, athletes, and convenience-seeking adults. Ready-to-drink formats dominate volume through impulse-purchase placement in supermarket chilled aisles, while powdered variants sustain margin pools in household bulk buying and foodservice preparation. Organic certification segments command premium positioning as EFSA-aligned clean-label expectations tighten across French and German retail assortments.
EFSA nutrition and health claims regulation governs permissible marketing language around protein content and recovery benefits, while EU Farm to Fork Strategy mandates constrain added sugar thresholds and dairy sourcing transparency. CE marking and EU packaging waste directives further shape material selection across Tetra Pak and recyclable bottle formats. Stakeholders must monitor evolving ECHA food-contact material standards and national sugar tax implementations in France, the United Kingdom, and Ireland to anticipate reformulation costs and channel-specific compliance burdens.
Market Dynamics
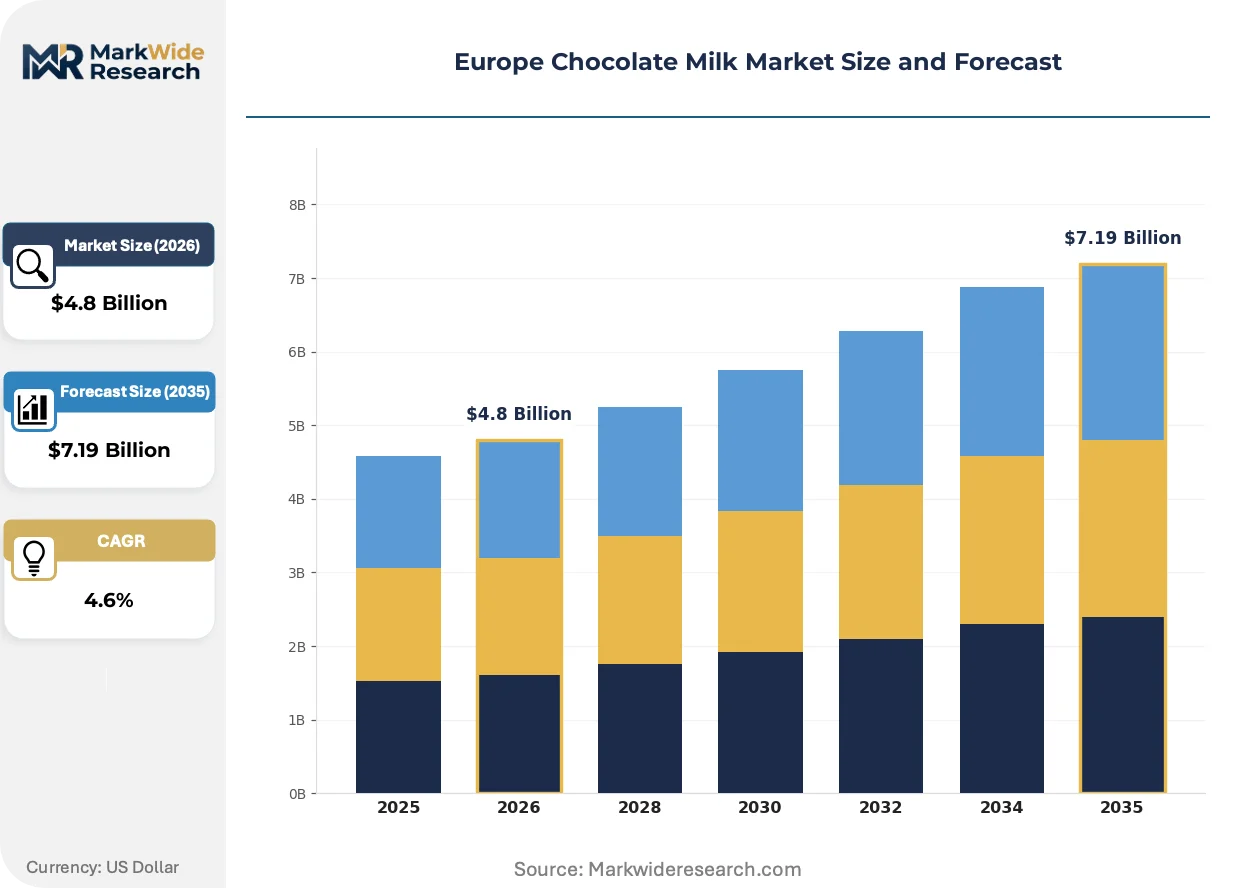
The EU Farm to Fork Strategy is compressing formulation timelines across European dairy processors, forcing simultaneous sugar reduction and clean-label transitions while procurement volumes from German school nutrition programs expand institutional demand.
Growth Catalysts
- German institutional procurement:School nutrition programs in North Rhine-Westphalia and Bavaria are expanding chocolate milk distribution through municipal tender frameworks, creating predictable offtake volumes for UHT processors.
- EFSA-aligned clean-label positioning:Organic certification and additive-free claims are capturing shelf space in French hypermarkets as EFSA nutrition claim regulations tighten permissible marketing language around recovery benefits.
- Aseptic filling technology:Advanced ESL (extended shelf life) processing lines are enabling ambient distribution without preservatives, opening convenience store channels previously blocked by cold-chain requirements.
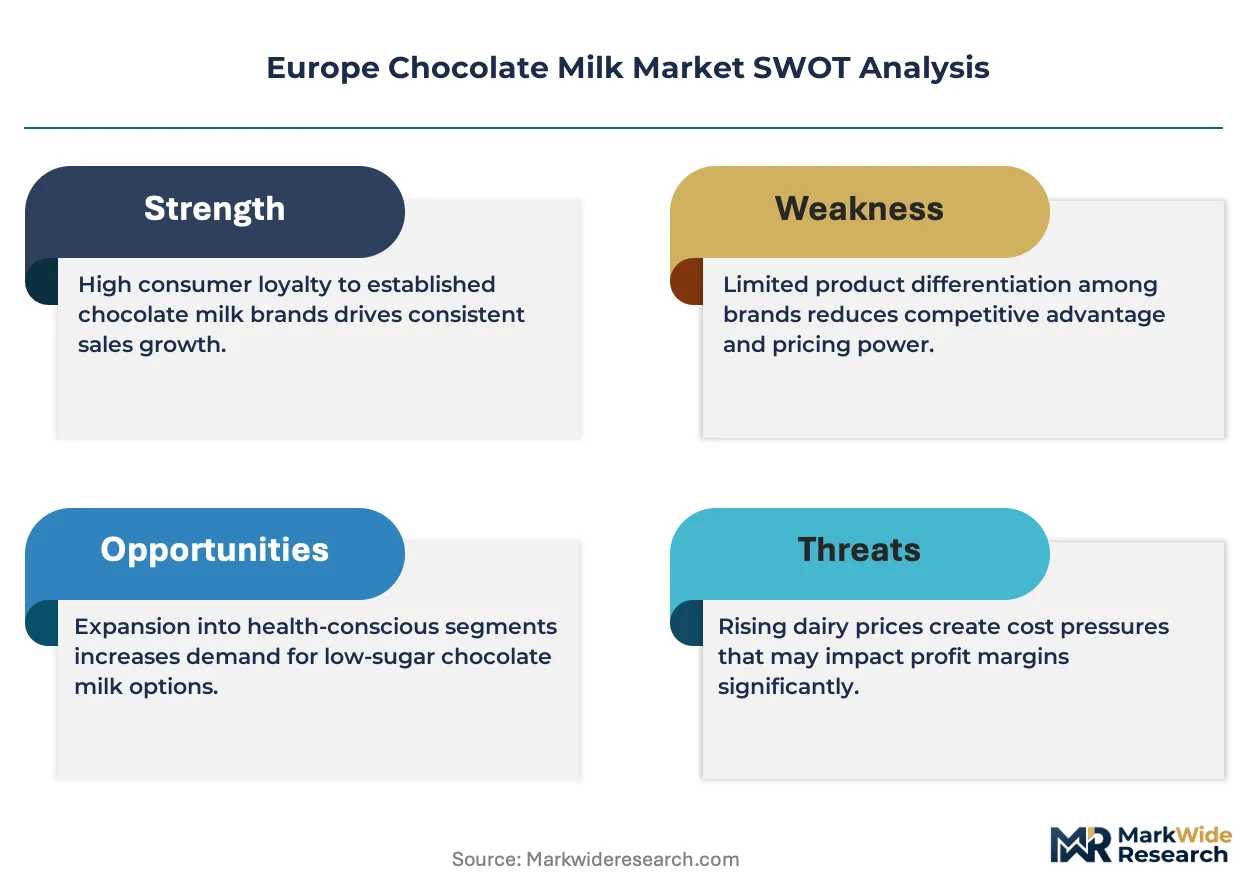
Market Restraints
- Cocoa butter price volatility:West African supply disruptions and currency fluctuations in Côte d'Ivoire and Ghana are compressing margins for processors locked into annual cocoa contracts.
- Dairy cooperative supply concentration:Netherlands-based raw milk procurement networks control approximately 60% of northern European liquid milk supply, limiting negotiating leverage for independent chocolate milk brands.
- France sugar tax escalation:The French public health levy on added sugars has forced multiple reformulation cycles since 2018, raising R&D costs and consumer acceptance risk for reduced-sugar variants.
Strategic Opportunities
- Polish and Romanian convenience retail:Underpenetrated chilled dairy aisles in Warsaw and Bucharest supermarket chains offer first-mover positioning for ESL-format chocolate milk before private-label saturation.
- Sports nutrition application expansion:Adult-oriented protein-fortified variants are capturing gym and pharmacy channels previously dominated by powder supplements, with Dutch sports retailers piloting dedicated chilled sections.
- EU packaging waste directive compliance:Recyclable bottle and tethered-cap mandates are creating premium positioning for early adopters of mono-material PET and paperboard alternatives in German retail.
Industry Challenges
- Reformulation talent scarcity:Food technologists with simultaneous expertise in dairy stabilization and clean-label emulsifier systems command premium salaries, constraining mid-tier processor innovation timelines.
- Dual certification complexity:Simultaneous organic and UTZ/Rainforest Alliance cocoa sourcing requires parallel audit trails, extending new product development cycles by 8-14 months for multinational retail listings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Chocolate Milk Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink, Powdered, Concentrate, Organic Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Children, Adults, Sports Enthusiasts, Health-Conscious Consumers Packaging Type: Bottles, Cartons, Pouches, Tetra Packs |
| Companies Covered | Royal FrieslandCampina NV, Danone SA, Arla Foods, Groupe Sodiaal, OMIRA, Nestlé SA, Unternehmensgruppe Theo Müller, Barry Callebaut, Mars Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Chocolate Milk Market Shifts & Advancements
Aseptic processing advances and regulatory pressure on sugar content are converging to reshape European chocolate milk formulation, packaging, and channel strategy across conventional and functional positioning tiers.
High-pressure processing (HPP) technology is rendering obsolete traditional thermal pasteurization for premium chilled chocolate milk segments. German organic processors in Bavaria and Baden-Württemberg are adopting HPP lines at 15-20% annual capacity expansion rates. This shift is enabling 45-day refrigerated shelf life without the cooked flavor notes that previously limited adult consumer acceptance.
EFSA's 2023 updated guidance on nutrition and health claims is tightening protein recovery messaging across sports-oriented chocolate milk variants. The regulation now requires clinical substantiation for post-exercise benefit claims, forcing Dutch and Danish brands to either commission new studies or retreat to generic taste positioning. French adult nutrition lines face the strictest enforcement, with ANSM coordinating retail surveillance.
Convenience retailers are unbundling chocolate milk from traditional dairy case placement into standalone grab-and-go fixtures near checkout zones. This channel migration is displacing volume-driven multipack promotions with single-serve premium pricing in German REWE and EDEKA networks. The shift is most visible in urban catchments where commuter consumption patterns favor immediate consumption over household stockpiling.
Europe Chocolate Milk Market Segmentation
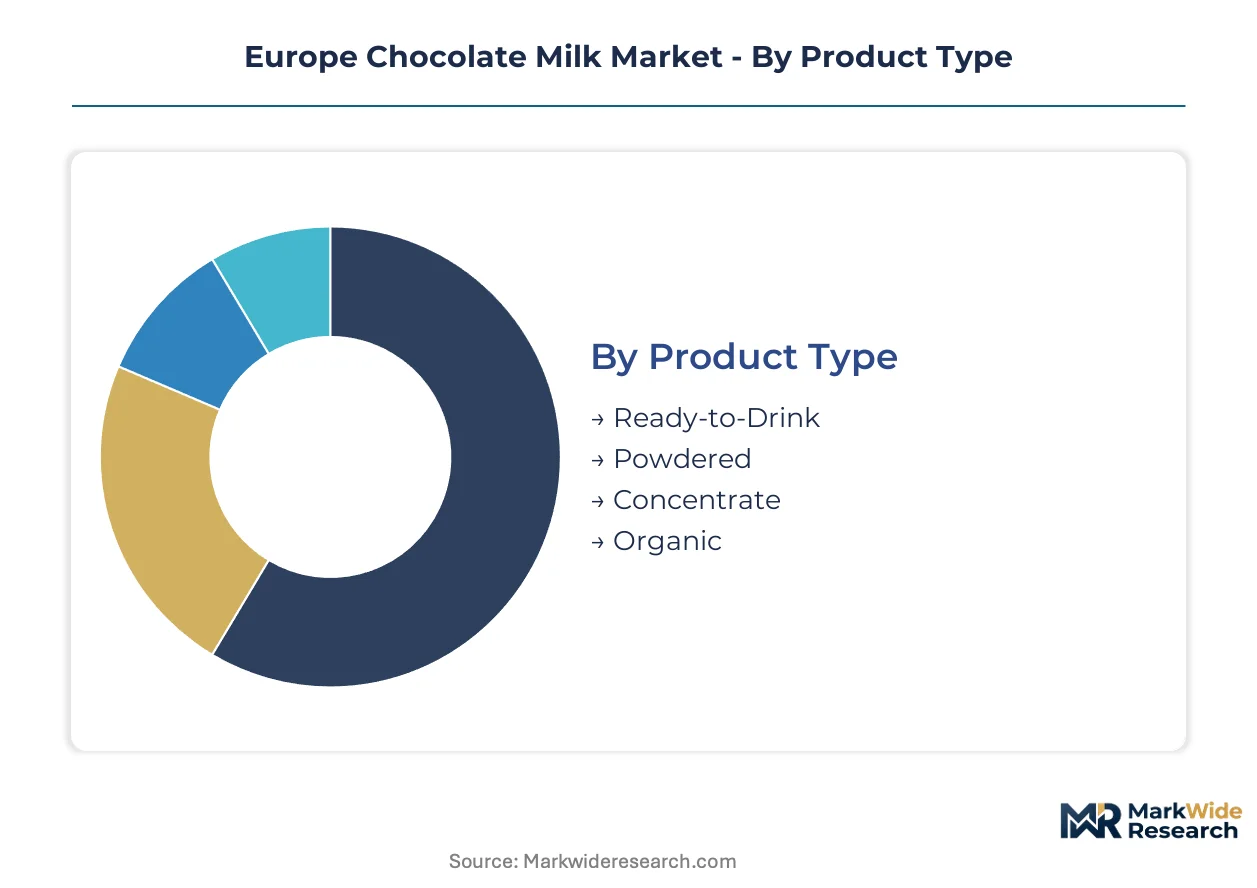
Chocolate milk segmentation in Europe reflects divergent consumption occasions and regulatory pressures. Product format determines shelf-life engineering and channel access, while end-user targeting shapes formulation architecture from sugar content to protein fortification.
Product Type:
Mature liquid formats dominate volume, yet emerging concentrate and organic tiers are capturing margin expansion as clean-label mandates tighten.
- Ready-to-Drink:UHT-processed dairy liquid in single-serve bottles or cartons, standardized to 1-3% fat with 8-12% milk solids non-fat. German REWE and EDEKA chains drive volume through chilled-aisle impulse placement, though sugar tax exposure in France forces reformulation cycles.
- Powdered:Spray-dried milk solids blended with alkalized cocoa and stabilizers for household reconstitution. Bulk procurement from Dutch institutional buyers sustains this segment, with Bavarian school nutrition programs accounting for predictable offtake.
- Concentrate:Reduced-water formulations requiring dilution prior to consumption.
- Organic:EFSA-aligned certification commanding shelf-space premiums in French hypermarkets.
Ready-to-Drink retains volume leadership; Organic holds the steepest expansion curve.
Distribution Channel:
Cost tier stratification separates mass-market supermarket penetration from premium convenience and specialty positioning.
- Supermarkets:Full-range chilled and ambient dairy aisles across German, French, and Dutch retail networks. Private-label expansion by FrieslandCampina and Arla Foods compresses branded margin pools, yet institutional tender frameworks in North Rhine-Westphalia secure predictable volumes for UHT processors.
- Convenience Stores:Grab-and-go fixtures near checkout zones displacing traditional dairy case placement. ESL-format chocolate milk enables ambient distribution without cold-chain investment, opening Warsaw and Bucharter urban catchments.
- Online Retail:Subscription and bulk delivery platforms.
- Specialty Shops:Organic and sports-nutrition focused channels.
Supermarkets anchor volume throughput; Convenience Stores are climbing the fastest as commuter consumption patterns shift toward immediate consumption.
End User:
Application-driven formulation separates childhood nutrition from adult functional positioning.
- Children:Standardized 200ml school-portion formats with controlled sugar thresholds per EU Farm to Fork guidelines. Municipal procurement in Bavaria and the Netherlands mandates specific nutritional profiles, creating tender-driven demand concentration.
- Adults:Protein-fortified and reduced-lactose variants targeting convenience-seeking professionals. Dutch sports retailers pilot dedicated chilled sections, though EFSA's tightened recovery-benefit claim enforcement forces clinical substantiation investment.
- Sports Enthusiasts:High-protein post-workout formulations.
- Health-Conscious Consumers:Clean-label and reduced-sugar alternatives.
Children's nutrition retains institutional volume leadership; Sports Enthusiasts show the steepest expansion trajectory as gym-channel penetration deepens.
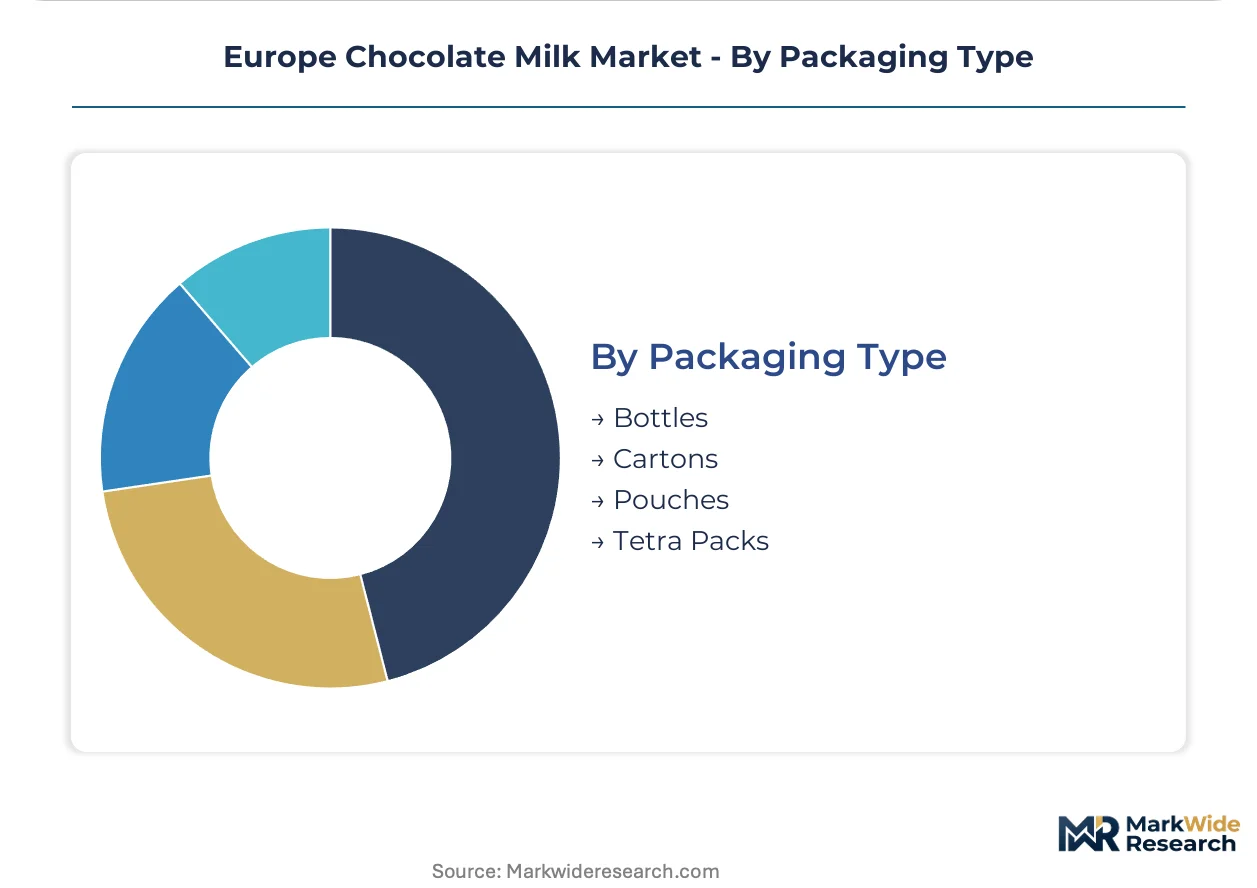
Packaging Type:
Supply concentration in aseptic filling technology shapes material selection and sustainability compliance.
- Bottles:Mono-material PET and tethered-cap formats aligning with EU packaging waste directive mandates. German retail early adoption creates premium positioning for recyclability claims, with REWE networks prioritizing closed-loop material flows.
- Cartons:Paperboard-based liquid packaging with aluminum barrier layers.
- Pouches:Flexible film formats for single-serve and multipack configurations.
- Tetra Packs:Aseptic brick and gable-top cartons dominating ambient distribution.
Bottles gain share fastest on regulatory tailwinds; Tetra Packs retain ambient-channel volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German supermarket chains extract sharper procurement terms than French convenience networks, creating a pricing-power asymmetry that compresses branded margin pools in Central Europe while sustaining premium positioning in Western markets.
Germany
Municipal school nutrition programs in North Rhine-Westphalia and Bavaria drive predictable UHT offtake through tender frameworks. The KBA enforces strict dairy transport standards that shape cold-chain logistics costs. Baden-Württemberg processors are adopting high-pressure processing lines at double-digit annual rates to extend refrigerated shelf life without thermal degradation.
France
Hypermarket chains in Île-de-France prioritize EFSA-aligned organic certification for shelf-space premiums. ANSM coordinates retail surveillance on protein recovery claims, tightening enforcement since the 2023 guidance update. Auvergne-Rhône-Alpes dairy cooperatives face escalating public health levies on added sugars that force repeated reformulation cycles.
Netherlands
FrieslandCampina's cooperative structure secures raw milk supply across Randstad dairy networks. EFSA nutrition claim regulations constrain permissible marketing language on adult sports variants. Eindhoven Region filling technology providers are shipping aseptic ESL lines to Polish and Romanian convenience retail entrants.
Poland
Warsaw supermarket chains present underpenetrated chilled dairy aisles for ESL-format chocolate milk before private-label saturation. The country's national food safety regulator aligns with EU Farm to Fork sugar reduction timelines. Silesian industrial dairy clusters are retrofitting ambient distribution capacity to bypass cold-chain infrastructure gaps.
United Kingdom
Gym and pharmacy channels in London and the Southeast pilot dedicated chilled sections for protein-fortified adult variants. The national food standards agency implements sugar tax thresholds that parallel French public health levies. Midlands dairy processors are navigating post-EU packaging waste directive compliance through mono-material PET transitions.
Europe Chocolate Milk Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cocoa processing and aseptic filling technology. The vendor base clusters around three strategic archetypes: cooperative-structured dairy giants with captive milk supply, multinational nutrition platforms with sports-brand extensions, and private-label manufacturers serving supermarket chains. Competitive moves concentrate on backward integration into dairy farming and strategic partnerships with convenience retail distributors.
Within the cooperative-structured tier, Royal FrieslandCampina NV and Arla Foods occupy positions defined by farmer-owned supply networks spanning Nordic and Central European procurement zones. Danone SA exemplifies the nutrition-platform archetype, anchoring specialized positioning in adult and sports-oriented variants. These three entities represent distinct competitive vectors: captive raw material access, functional nutrition branding, and distribution scale across refrigerated retail channels.
| Leading Market Players |
|---|
| Royal FrieslandCampina NV |
| Danone SA |
| Arla Foods |
| Groupe Sodiaal |
| OMIRA |
| Nestlé SA |
| Unternehmensgruppe Theo Müller |
| Barry Callebaut |
| Mars Inc. |
| Others |
Supply & Pricing Matrix
Cocoa butter price volatility from West African supply disruptions determines both the premium spread for certified-sustainable variants and the geographic shape of European dairy processor sourcing networks. This commodity exposure compresses margins on standard formulations while widening price tiers between mass-market UHT and organic-certified chilled products.
Pricing Analysis
Configured-to-order pricing for organic and sports-nutrition variants commands substantial premiums over standard UHT formulations. Three-tier pricing structure across premium, standard, and economy levels segments the market: EFSA-aligned clean-label certifications and protein fortification drive premium tiers, while private-label UHT competes on volume scale in German supermarket chains. Pricing pressure stems from French public health levies on added sugars that force repeated reformulation investments. Institutional buyers in Bavarian school nutrition programs exhibit lowest price sensitivity due to tender-locked volumes, while Polish convenience retail entrants face acute margin compression.
Supply Chain Analysis
Tariff exposure between EU dairy processors and West African cocoa exporters dominates supply chain risk planning for European chocolate milk manufacturers. Raw milk procurement concentrates in the Netherlands, Germany, and Denmark through cooperative-structured networks that control approximately sixty percent of northern European liquid supply. Cocoa solids and dairy emulsifiers constitute critical input dependencies, with alkalized cocoa powder sourcing resting on Côte d'Ivoire and Ghana harvest cycles. Single-source vulnerability in aseptic filling technology—particularly ESL processing lines from Eindhoven Region suppliers—creates equipment procurement bottlenecks. Distribution runs through German REWE and EDEKA supermarket chains for volume throughput, with ambient-format convenience store penetration expanding in Warsaw and Bucharest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food technologists capable of simultaneous dairy stabilization and clean-label emulsifier expertise command premium compensation, creating a talent bottleneck that constrains mid-tier processor innovation velocity and consolidates competitive advantage among cooperative-structured dairy giants with captive R&D resources.
For Market Incumbents: Build captive raw material access through backward integration into Dutch and German dairy farming cooperatives. Secure long-term cocoa supply agreements with Rainforest Alliance-certified West African exporters to buffer price volatility exposure. Expand aseptic ESL processing capacity in Baden-Württemberg to capture refrigerated shelf-life advantages. Channel control through dedicated chilled-section partnerships with Dutch sports retailers reinforces positioning against private-label encroachment. For New Entrants and Emerging Players: Polish and Romanian convenience retail represents the most penetrable entry point before private-label saturation hardens. Warsaw supermarket chains present underpenetrated chilled dairy aisles where ESL-format ambient distribution bypasses cold-chain infrastructure gaps. Sports nutrition application expansion into gym and pharmacy channels offers alternative positioning outside supermarket price wars. Direct-to-sports-retailer distribution agreements with Dutch fitness chains provide viable go-to-market traction. For Investors and Strategic Acquirers: EU Farm to Fork Strategy sugar reduction mandates reshape the acquisition landscape toward processors with demonstrated reformulation capabilities and organic certification infrastructure. Long-term viability favors cooperative-structured dairy platforms with captive milk supply and established EFSA-aligned clean-label positioning. Acquisition target archetype: mid-tier processors with underutilized aseptic filling capacity and untapped convenience retail channel relationships. Signal to watch: ANSM enforcement patterns on protein recovery claims as indicator of regulatory compliance burden escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Farming | Captive raw milk supply secures procurement stability against cooperative concentration in Netherlands and Germany. |
| ESL Processing Capacity Expansion | Extended shelf-life technology opens convenience store channels in Warsaw and Bucharest without cold-chain investment. |
| Organic Certification Investment | EFSA-aligned clean-label positioning commands shelf-space premiums in French hypermarket networks. |
| Sports Nutrition Channel Partnership | Dedicated chilled sections in Dutch fitness retailers capture adult consumer migration from powder supplements. |
| Mono-Material PET Transition | EU packaging waste directive compliance creates premium positioning in German REWE closed-loop material flows. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with dairy cooperative procurement directors, UHT processing plant managers, French hypermarket category buyers, Dutch sports retail channel heads, and EFSA regulatory affairs specialists. Secondary validation drew from EU Farm to Fork Strategy implementation documents, EFSA nutrition claim guidance updates, Bavarian school nutrition program tender records, and Nielsen retail audit data for German supermarket chains. Bottom-up volume modeling across product format, distribution channel, and end-user segments was triangulated against top-down dairy industry production statistics.
Calibration against historical volume trajectories and documented regulatory implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end-user application, packaging format, and regional regulatory cluster. CAGRs were derived through regression analysis of documented procurement volumes and disclosed processor capacity expansions. Forecast inputs incorporated cocoa futures price volatility bands and municipal school nutrition program expansion announcements.
Practitioners should monitor West African harvest disruptions, French sugar tax threshold adjustments, and EFSA claim enforcement patterns for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Cream Powder Market
Dairy Products
Organic Milk Market
Dairy Products
Halal Cheese Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Global Goat Milk Derivatives Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
United States Milk Protein Market
Dairy Products
Textured Butter Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Fluid Milk Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Plain Yogurt Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
North America Organic Dairy Market