
 Global Goat Milk Derivatives Market | 2026-2036
Global Goat Milk Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Goat Milk Derivatives Market Foresight
Premium-grade protein specification tiers is unwinding commoditization pressures across goat milk derivatives. Ausnutria Dairy Corporation leverages captive goat farm networks in China to secure traceable whey protein supply chains. Prolactal anchors Central European production of pharmaceutical-grade casein isolates through controlled herd management protocols. Emmi Group differentiates its goat butterfat offerings via integrated alpine dairy operations that sustain organic certification premiums.
Goat milk derivatives encompass fractionated and dried dairy ingredients extracted from Capra species milk, typically containing beta-casein profiles distinct from bovine sources and protein concentrations ranging from 3.0% to 3.5% by weight. These derivatives serve as hypoallergenic base materials for infant nutrition, functional foods, and cosmetic formulations where reduced alpha-s1 casein content matters. Powdered milk retains the largest volume share among product types due to its stability in long-distance supply chains and versatility across bakery and nutritional supplement applications. Whey protein is gaining fastest within the infant formula application segment as manufacturers reformulate for digestibility claims targeting sensitive neonatal populations. Casein fractions command concentrated margin pools in the pharmaceutical customer channel where excipient purity standards and batch traceability requirements limit supplier qualification.
FDA GRAS notifications and EFSA novel food opinions shape ingredient approval pathways for goat-derived proteins entering US and European infant formula markets. China's NMPA and SAMR enforce formula registration rules that favor documented supply chain segregation between goat and cow milk processing lines. Stakeholders must monitor evolving allergen labeling mandates from EFSA and FDA that could redefine competitive positioning between goat and A2 bovine protein alternatives.
Market Dynamics
Infant formula manufacturers in China and Southeast Asia are consolidating procurement around traceable goat whey protein supply chains, compressing margins for commodity-grade processors while rewarding integrated operators with captive herd networks.
Growth Catalysts
- EU F-Gas Regulation:The regulation mandates lower-global-warming-potential refrigerants in whey drying equipment, accelerating capital replacement cycles that favor energy-efficient fractionation systems in Dutch and Austrian processing clusters.
- Pharmaceutical excipient demand:Casein isolates for tablet binding and controlled-release formulations are drawing new investment from ingredient houses serving FDA-regulated drug manufacturers in the United States.
- Controlled herd management protocols:Alpine dairy cooperatives in Switzerland and France are securing organic certification premiums through documented pasture rotation and antibiotic-free milk collection systems.
Market Restraints
- Raw milk supply concentration:Over sixty percent of European goat milk supply originates from smallholder farms in France and Spain, creating volume volatility and quality inconsistency for industrial-scale processors.
- Alpha-s1 casein detection costs:Laboratory verification of hypoallergenic protein profiles adds USD 12,000–18,000 per batch for manufacturers targeting neonatal nutrition claims.
- A2 bovine protein substitution:Dairy processors in Australia and New Zealand are marketing A2 cow milk derivatives as digestibility-equivalent alternatives at fifteen to twenty percent lower ingredient cost.
Strategic Opportunities
- South Korean functional foods:MFDS novel food approval pathways for goat milk peptides are opening positioning opportunities in collagen-boosting beauty nutrition segments.
- Spray-drying technology convergence:Integration of low-temperature spray drying with inline protein fractionation is enabling custom whey-to-casein ratio specifications for contract manufacturers.
- Direct-to-brand e-commerce channels:Specialty ingredient platforms are bypassing traditional distributor markups for mid-sized nutritional supplement formulators in Germany and the United Kingdom.
Industry Challenges
- Pharmaceutical-grade certification timelines:Excipient GMP compliance for casein isolates requires eighteen to twenty-four month qualification periods with FDA and EMA inspectorates.
- Legacy ERP integration:Small and mid-sized processors in Southern Europe face system incompatibility when connecting batch traceability data to customer quality management portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Goat Milk Derivatives Market |
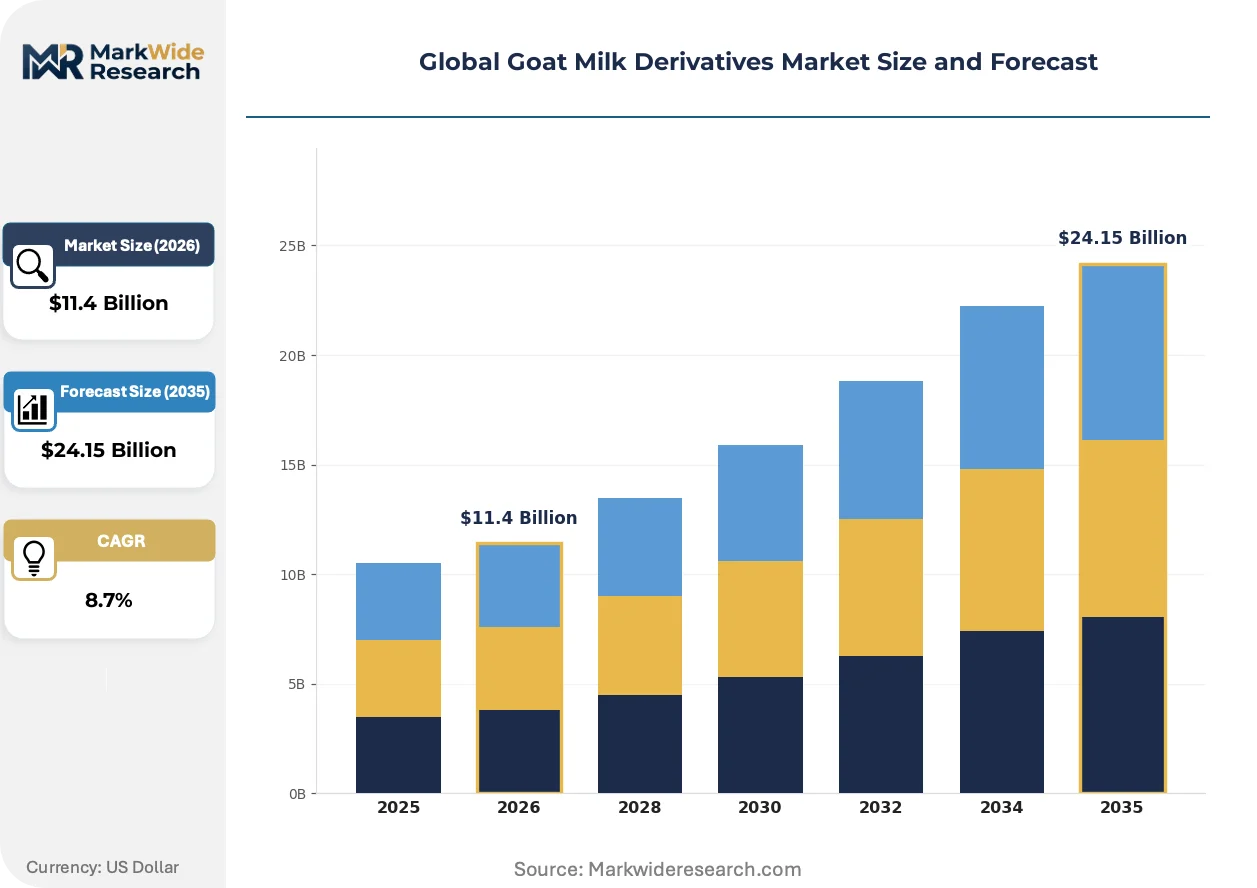
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $24.15 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Milk, Whey Protein, Casein, Butterfat, Lactose Application: Infant Formula, Nutritional Supplements, Bakery, Cosmetics, Pharmaceuticals Packaging Type: Pouches, Tins, Bottles, Sachets, Cartons Customer Type: Food & Beverage Manufacturers, Personal Care Producers, Nutraceutical Companies, Pharmaceutical Firms |
| Companies Covered | AVH Dairy Trade B.V., Lacteas Cobreros SA, Ausnutria Dairy Corporation Ltd, Goat Partners International Inc., Prolactal, Saputo Inc, Hoogwegt Groep B.V., Eurial, Emmi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Goat Milk Derivatives Market Shifts & Advancements
Membrane filtration advances and regulatory tightening around infant nutrition claims are compressing the viable supplier base while rewarding operators with integrated quality verification systems.
Microfiltration coupled with ceramic membrane technology is displacing traditional centrifugal separation in whey protein concentration lines. German and Dutch equipment suppliers are installing these systems for infant formula ingredient houses seeking tighter control over protein aggregate size distribution. The technology is displacing legacy thermally processed whey isolates in premium neonatal nutrition specifications.
China's SAMR formula registration rules now require documented supply chain segregation between goat and cow milk processing lines. Manufacturers must maintain separate drying towers, packaging lines, and cleaning protocols. Dutch exporters are responding by constructing dedicated goat-only facilities to maintain eligibility for Chinese infant formula ingredient procurement.
Brand-direct sourcing contracts are replacing spot-market purchasing for pharmaceutical-grade casein. Large excipient buyers in the United States and Germany are negotiating multi-year volume commitments with single-source suppliers in exchange of batch-level genomic traceability. This pattern is most visible among FDA-regulated generic drug manufacturers consolidating their excipient qualification portfolios.
Global Goat Milk Derivatives Market Segmentation
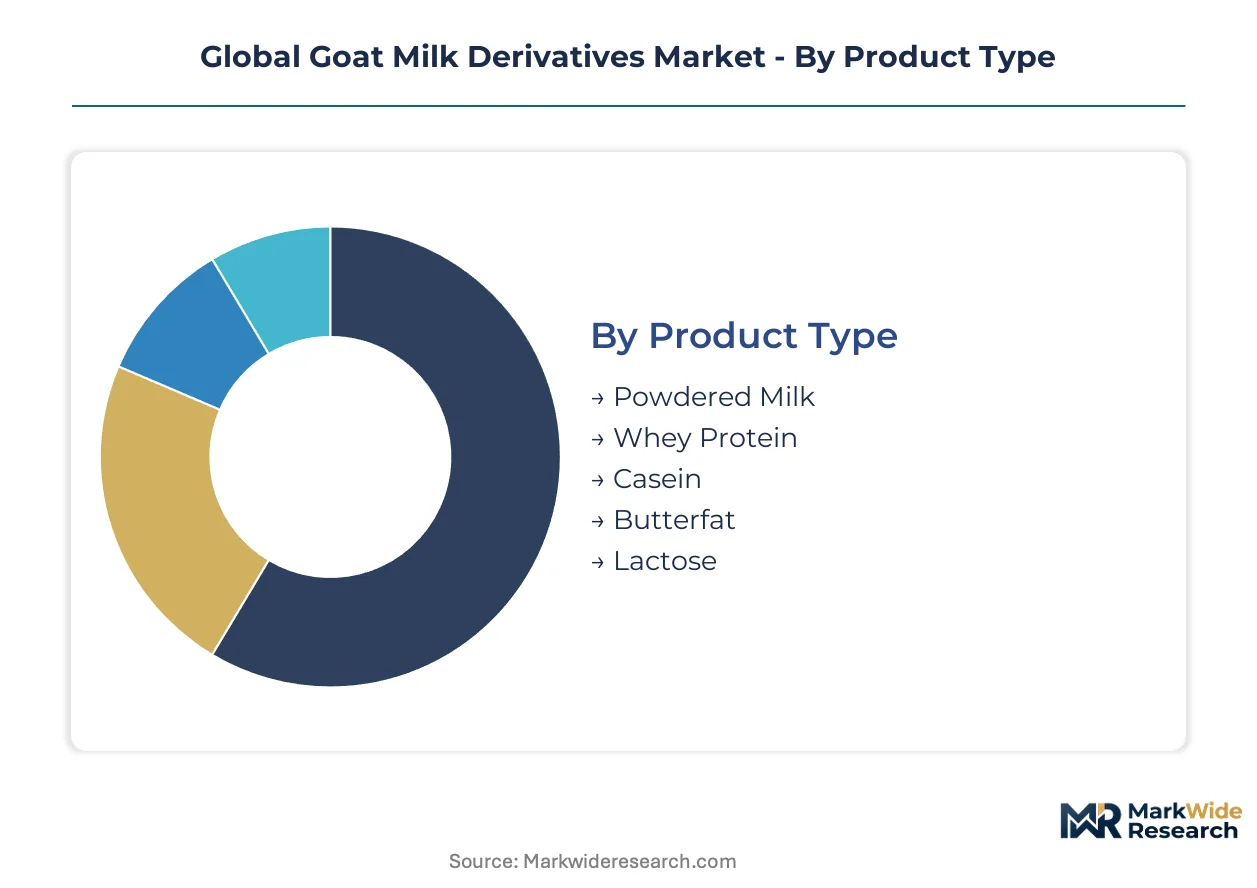
Segmentation in goat milk derivatives reveals distinct procurement patterns between domestic dairy processors and export-oriented ingredient houses. Understanding these divisions exposes where margin pools concentrate and which specifications command premium positioning across regulatory jurisdictions.
Product Type:
Powdered milk dominates domestic consumption channels across France and Spain, while whey protein and casein fractions flow predominantly toward export markets in China and Southeast Asia.
- Powdered Milk:Standardized dried whole and skim milk powders retain stability in ambient supply chains. French and Spanish dairy cooperatives supply domestic bakery and confectionery manufacturers, though volume volatility from smallholder sourcing constrains industrial-scale contract reliability.
- Whey Protein:Fractionated protein concentrates and isolates serve infant formula manufacturers seeking digestibility claims. Procurement from Dutch and Austrian processors is accelerating as China's SAMR enforces segregated goat-cow processing line documentation.
- Casein:Pharmaceutical-grade isolates for tablet binding command concentrated margin pools.
- Butterfat:Alpine-sourced organic variants sustain certification premiums in premium confectionery.
- Lactose:Purified crystalline grades function as excipient fillers and infant formula carbohydrate sources.
Powdered milk commands the established base. The steepest expansion runs through whey protein.
Application:
Cost tier stratification separates commodity food applications from premium pharmaceutical and neonatal nutrition segments with divergent specification tolerances.
- Infant Formula:Hypoallergenic base materials with reduced alpha-s1 casein content target sensitive neonatal populations. Chinese and Southeast Asian manufacturers are consolidating procurement around traceable supply chains, compressing margins for commodity-grade processors.
- Pharmaceuticals:Casein isolates for controlled-release tablet binding require eighteen to twenty-four month GMP qualification periods with FDA and EMA inspectorates. Batch-level genomic traceability is becoming a non-negotiable specification for US generic drug manufacturers.
- Nutritional Supplements:Functional food positioning in South Korean beauty nutrition segments leverages MFDS novel food approval pathways for bioactive peptides.
- Bakery:Powdered milk incorporation into long-shelf-life baked goods emphasizes emulsification stability.
- Cosmetics:Goat milk proteins in topical formulations exploit moisturizing and barrier-function claims.
Infant formula anchors volume demand. The climbing trajectory belongs to pharmaceuticals.
Packaging Type:
Volume scale and customer type dictate packaging selection, with industrial bulk formats contrasting retail-ready configurations.
- Tins:Airtight metal containers preserve protein integrity in humid climates for Southeast Asian export shipments.
- Pouches:Flexible laminated films reduce freight costs for bulk whey protein concentrate movements.
- Sachets:Single-serve formats serve sampling programs and travel-retail nutritional supplements.
- Bottles:PET and glass containers target liquid goat milk derivatives in premium retail channels.
- Cartons:Aseptic brick packs extend ambient shelf life for UHT-processed liquid products.
Tins retain institutional preference. Pouches are gaining share fastest in cost-sensitive bulk procurement.
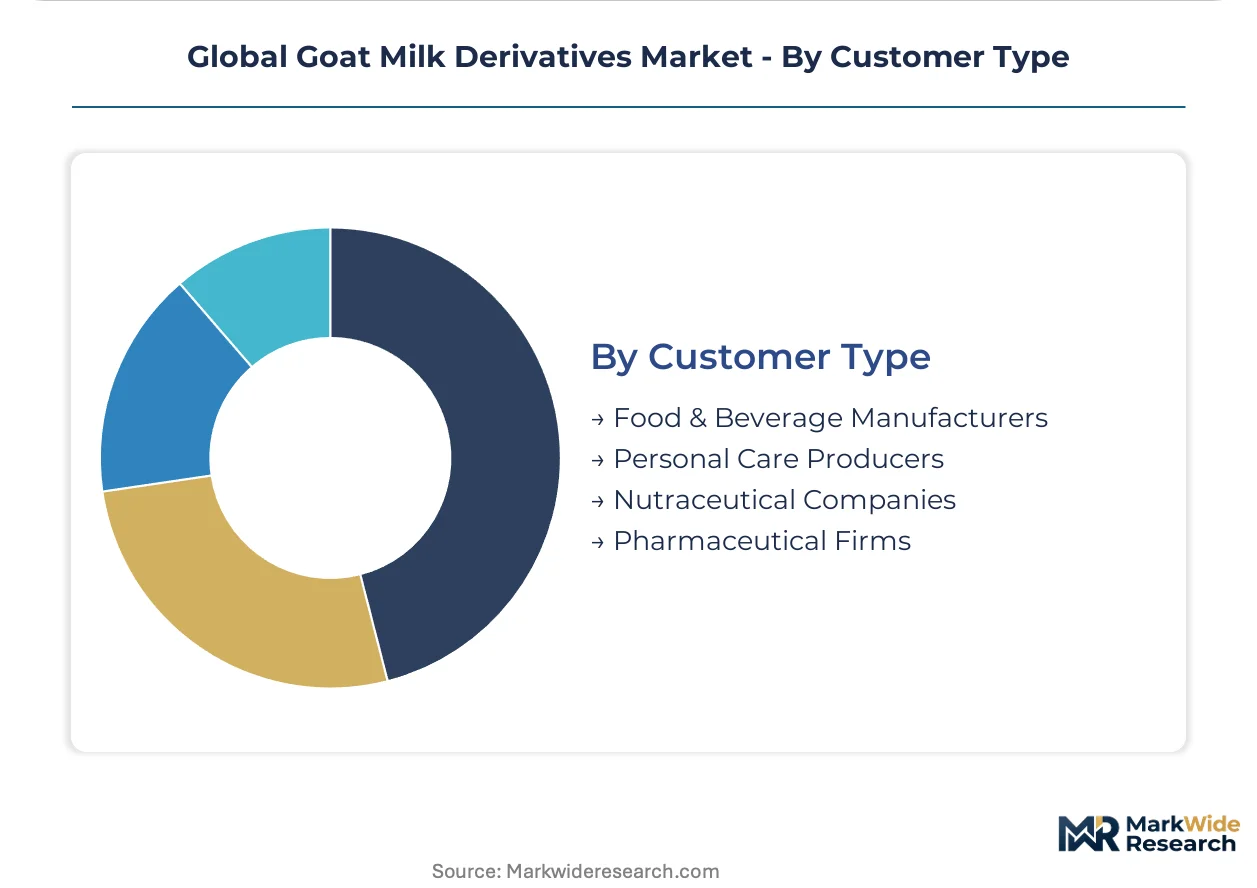
Customer Type:
Supply concentration varies sharply between fragmented food manufacturers and consolidated pharmaceutical excipient buyers with stringent qualification protocols.
- Food & Beverage Manufacturers:Bakery and confectionery processors in France, Italy, and Germany source standardized powdered milk through spot-market and quarterly contract structures.
- Pharmaceutical Firms:FDA-regulated generic drug manufacturers in the United States are negotiating multi-year volume commitments with single-source casein suppliers in exchange for batch traceability documentation.
- Nutraceutical Companies:German and UK mid-sized formulators are bypassing traditional distributor markups through specialty ingredient e-commerce platforms.
- Personal Care Producers:Cosmetic houses in South Korea and France incorporate goat milk proteins into collagen-boosting beauty nutrition lines.
Food and beverage manufacturers represent the broadest customer base. Pharmaceutical firms deliver the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented processing clusters in the Netherlands and Austria generate trade surpluses in whey protein and casein fractions, while France and Spain remain net exporters of raw goat milk to these industrial hubs. Chinese import demand is restructuring procurement relationships across European supplier networks.
Netherlands
AVH Dairy Trade and Prolactal anchor specialized ingredient clusters serving Asian infant formula manufacturers. The EU F-Gas Regulation mandates refrigerant transitions in whey drying equipment, accelerating capital replacement in Dutch processing facilities. Dedicated goat-only drying towers near Rotterdam maintain SAMR compliance for Chinese export eligibility.
China
Infant formula manufacturers in Hunan and Zhejiang provinces are consolidating procurement around traceable supply chains. NMPA and SAMR enforce formula registration rules requiring documented segregation between goat and cow milk processing lines. Ausnutria Dairy Corporation leverages captive goat farm networks in Shaanxi to secure integrated whey protein supply.
France
Alpine dairy cooperatives in Rhône-Alpes and Provence-Alpes-Côte d'Azur secure organic certification premiums through pasture rotation protocols. EFSA novel food opinions shape approval pathways for goat-derived proteins entering European markets. Emmi Group's integrated operations in the French Alps sustain butterfat differentiation via documented antibiotic-free collection systems.
Austria
Prolactal anchors Central European production of pharmaceutical-grade casein isolates through controlled herd management. The country's national pharmaceutical regulator aligns with EMA inspectorate standards for excipient GMP compliance. Processing facilities in Upper Austria specialize in custom whey-to-casein ratio specifications for contract manufacturers.
Spain
Smallholder farms in Castile and León supply over sixty percent of European raw goat milk volume, creating quality inconsistency for industrial-scale processors. The country's national food safety authority enforces traceability standards that constrain spot-market reliability. Lacteas Cobreros SA represents consolidation pressure among Spanish processors seeking export market qualification.
Global Goat Milk Derivatives Market Competitive Landscape
Concentration sits with integrated processors controlling captive herd networks and dedicated fractionation facilities. The supplier base stratifies between commodity-grade powdered milk producers and premium-tier whey protein houses serving regulated infant nutrition markets. Three archetypes dominate: alpine dairy cooperatives with organic certification, Dutch-Austrian ingredient specialists with pharmaceutical-grade capabilities, and Chinese integrated operators with domestic farm control. Competitive dynamics center on capacity expansion for segregated processing lines and multi-year procurement contracts with genomic traceability terms.
Among Dutch and Austrian specialists, AVH Dairy Trade B.V., Prolactal, and Hoogwegt Groep B.V. exemplify the export-oriented ingredient house archetype with established positions in Asian procurement networks. These entities represent the premium-tier vector where pharmaceutical-grade certification and SAMR-compliant segregation capabilities create supplier qualification barriers. At the integrated Chinese operator position, Ausnutria Dairy Corporation Ltd. anchors domestic supply chain control through backward integration into captive goat farming operations.
| Leading Market Players |
|---|
| AVH Dairy Trade B.V. |
| Lacteas Cobreros SA |
| Ausnutria Dairy Corporation Ltd |
| Goat Partners International Inc. |
| Prolactal |
| Saputo Inc |
| Hoogwegt Groep B.V. |
| Eurial |
| Emmi Group |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with genomic traceability clauses lock in supply access for Chinese infant formula manufacturers while anchoring price visibility for Dutch and Austrian processors serving export markets. These arrangements compress spot-market liquidity for commodity-grade powdered milk while securing margin premiums for segregated goat-only processing lines compliant with SAMR registration rules.
Pricing Analysis
Industrial OEM buyers anchor pharmaceutical-grade casein pricing through multi-year volume commitments with single-source suppliers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and batch traceability depth. Cost compression in commodity whey concentrates is intensifying because A2 bovine protein substitutes undercut goat derivatives on ingredient cost. Nutritional supplement formulators exhibit highest price sensitivity, while FDA-regulated drug manufacturers accept premium positioning for excipient GMP compliance.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes are extending lead times for bulk whey protein concentrate shipments. Raw goat milk supply draws from smallholder farms in France, Spain, and the Netherlands, creating quality inconsistency for industrial-scale fractionation. Single-source vulnerability sits with alpine dairy cooperatives supplying organic-certified butterfat to premium confectionery channels. Distribution runs through specialized ingredient houses in the Netherlands and Austria before reaching Asian infant formula manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement relationships as direct-to-brand e-commerce channels disintermediate traditional distributor networks, creating interoperability between mid-sized formulators and specialty ingredient suppliers.
For Market Incumbents: Fortify SAMR-compliant segregation capabilities through dedicated goat-only drying tower investments in Dutch processing clusters. Deepen backward integration into captive herd networks to defend against A2 bovine protein substitution threats in the infant nutrition segment. Secure pharmaceutical-grade certification timelines with FDA and EMA inspectorates to maintain excipient supplier qualification barriers. For New Entrants and Emerging Players: Lead with MFDS novel food approval pathways for bioactive goat milk peptides targeting South Korean beauty nutrition segments. South Korean functional foods represent the most penetrable white space, with collagen-boosting positioning offering differentiation from established infant formula channels. Deploy spray-drying technology convergence with inline protein fractionation as a contract manufacturing entry angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated operators with captive goat farm networks and pharmaceutical-grade fractionation capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity volume scale. Watch for SAMR enforcement actions against non-compliant processors as an inflection indicator for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Herd Networks | Ausnutria Dairy Corporation's Shaanxi farm control secures traceable whey protein supply chains for Chinese infant formula manufacturers. |
| Pharmaceutical-Grade Certification Investment | Prolactal's EMA-aligned GMP compliance in Upper Austria creates eighteen-to-twenty-four-month qualification barriers for casein isolate competitors. |
| Dedicated Goat-Only Processing Facility Construction | Dutch exporters near Rotterdam maintain SAMR eligibility through segregated drying towers serving Asian procurement networks. |
| Direct-to-Brand E-Channel Development | Specialty ingredient platforms in Germany and the United Kingdom bypass distributor markups for mid-sized nutraceutical formulators. |
| Low-Temperature Spray Drying Technology Deployment | German and Dutch equipment suppliers install ceramic membrane systems displacing legacy thermally processed whey isolates in premium neonatal specifications. |
Research Methodology
Desk research of EU F-Gas Regulation filings, SAMR formula registration databases, and EFSA novel food opinions preceded structured interviews with infant formula procurement directors, pharmaceutical excipient quality managers, and alpine dairy cooperative technical leads. Primary fieldwork with Dutch and Austrian processing facility operators combined with secondary validation from customs trade data and dairy cooperative annual reports. Bottom-up volume modeling across product type and application segments triangulated with top-down market sizing from ingredient house revenue disclosures.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in pharmaceutical versus food-grade channels. Segmentation dimensions modeled include product type, application, customer archetype, and regional regulatory cluster. CAGRs derive from installed capacity expansion timelines and import demand elasticity estimates for Chinese infant formula manufacturers. Forecast inputs incorporate EU refrigerant transition compliance costs and MFDS novel food approval velocity for bioactive peptide positioning.
The analysis sits within stated boundaries; outcomes outside sustained SAMR enforcement rigor or accelerated A2 bovine protein substitution would require recalibration. Forecasts reflect assumptions regarding alpine dairy cooperative organic certification retention and pharmaceutical excipient GMP inspectorate backlog clearance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
GCC Fresh Milk Market
Dairy Products
Green Tea Butter Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Dairy Products Market
Dairy Products
North America Yogurt Market
Dairy Products
Dry Buttermilk Market
Dairy Products
US Cheese Market
Dairy Products
Europe Flavored Milk Market
Dairy Products
Colombia Dairy Market
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Cheese Shreds Market
Dairy Products
A2 Protein Milk Market
Dairy Products
Hydrolyzed Casein Market