
 Juice Market | 2026-2036
Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Juice Market Outlook
Not-from-concentrate orange juice is pivoting toward high-pressure processing as brands seek cleaner labels without thermal degradation. The Coca-Cola Company leverages its Minute Maid supply chain to control citrus sourcing across Florida and Brazil. PepsiCo Inc. sustains Tropicana's refrigerated logistics network as a competitive moat in North American retail. Nestle S.A. differentiates through botanical-infused premium lines that command shelf-space premiums in European supermarkets.
Juice comprises aqueous extracts from fruits or vegetables, typically retaining soluble solids above 10.5 degrees Brix for orange juice and processed through extraction, pasteurization, and aseptic filling to preserve sensory and nutritional integrity. Packaged juice occupies the largest revenue pool due to extended shelf life and global distribution feasibility, while organic juice captures the fastest expansion as certification requirements tighten and consumer willingness-to-pay for residue-free products climbs. Tetra Pak cartons dominate ambient distribution channels, though pouches gain traction in foodservice and on-premise consumption formats.
The FDA governs juice safety through Hazard Analysis and Critical Control Points mandates and the Juice HACCP regulation, while the USDA administers organic certification standards that gate premium positioning. The EU Green Deal's Farm-to-Fork strategy pressures exporters to demonstrate sustainable sourcing and reduced pesticide residues. Stakeholders must monitor evolving sugar taxation frameworks and front-of-pack labeling mandates that threaten conventional sweetened juice volumes while rewarding no-added-sugar and vegetable-blend innovations.
Market Dynamics
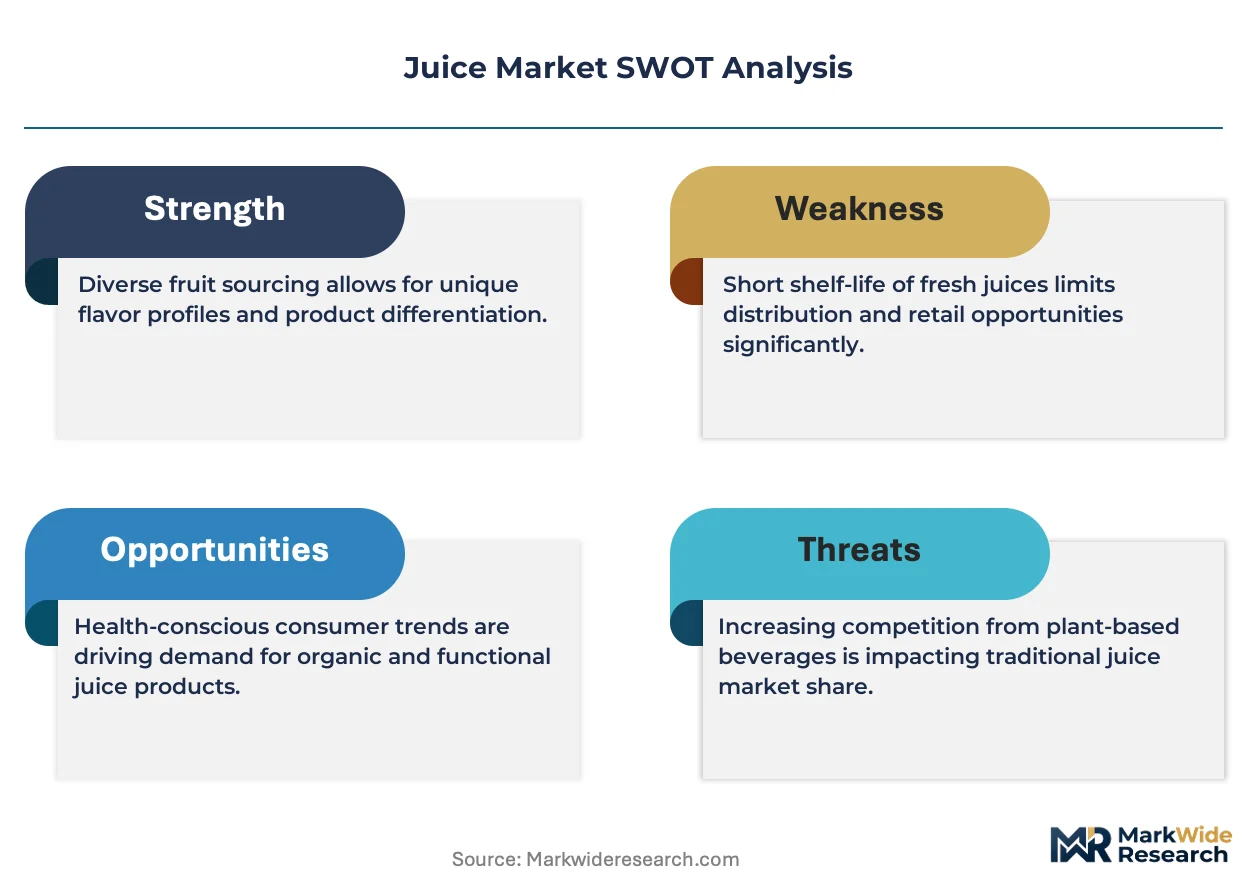
Cold-pressed extraction technology and high-pressure processing are compressing thermal pasteurization's dominance as brands chase nutrient retention and clean-label positioning without sacrificing shelf stability.
Growth Catalysts
- Clean-label mandates:The FDA's updated Nutrition Facts label rules force reformulation toward no-added-sugar variants, pulling investment into natural preservation technologies.
- Certification premiums:USDA organic standards gate access to shelf-space premiums in North American retail, rewarding residue-free supply chains with price realization advantages.
- São Paulo citrus clustering:Brazil's concentrated processing infrastructure delivers scale economies that lower input costs for not-from-concentrate orange juice exports.
Market Restraints
- Input cost volatility:Weather-driven citrus harvest fluctuations in Florida and São Paulo state squeeze processor margins unpredictably.
- Supply concentration risk:Tetra Pak's dominance in aseptic carton supply creates single-source vulnerability for ambient distribution channels.
- Sugar taxation friction:Front-of-pack labeling mandates in EU member states compress conventional sweetened juice volumes and threaten brand equity.
Strategic Opportunities
- Botanical infusion convergence:Adaptogen and functional ingredient pairing with base juices opens premium positioning in European supermarket channels.
- Pouch format penetration:Flexible packaging gains traction in foodservice and on-premise consumption, displacing rigid containers in grab-and-go occasions.
- EU Green Deal alignment:Farm-to-Fork strategy compliance creates competitive moat for exporters demonstrating pesticide reduction and sustainable sourcing.
Industry Challenges
- HACCP compliance complexity:FDA Juice HACCP regulation mandates hazard analysis investments that strain mid-scale processor resources.
- Refrigerated logistics capex:Cold-chain infrastructure requirements for not-from-concentrate products demand capital deployment that favors integrated beverage conglomerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Juice Market |
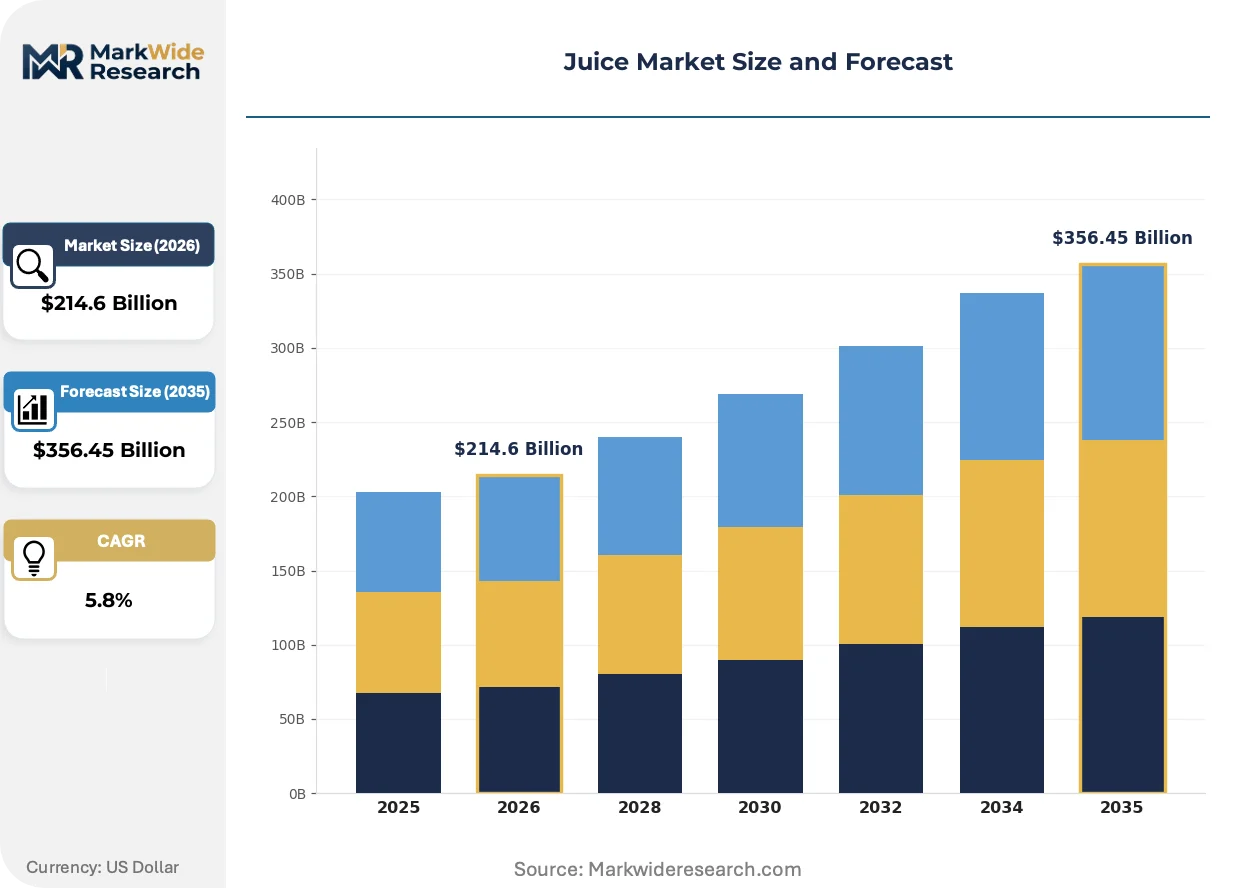
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $356.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Juice, Packaged Juice, Concentrated Juice, Organic Juice Ingredient: Citrus, Berries, Tropical Fruits, Stone Fruits Packaging Type: Bottles, Cartons, Pouches, Tetra Packs Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc., Tropicana Brands Group, Keurig Dr Pepper Inc., Nestle S.A., Ocean Spray, Del Monte Foods Corporation, Dole Packaged Foods LLC, Suntory Holdings Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Juice Market Strategic Shifts
Processing technology convergence, regulatory disclosure tightening, and consumption occasion fragmentation are simultaneously elevating quality thresholds and compressing traditional category boundaries.
High-pressure processing is unifying pasteurization efficacy with sensory preservation in not-from-concentrate orange juice. Premium brands in North American retail adopt this technology to eliminate thermal degradation while maintaining the extended shelf life required by mass distribution. This unification is compressing the historical trade-off between clean labels and supply chain feasibility that has constrained cold-pressed expansion.
The EU Green Deal's Farm-to-Fork strategy is mandating pesticide residue disclosure and sustainable sourcing documentation for juice imports. Exporters to European markets must now demonstrate supply chain traceability and reduced chemical inputs to maintain market access. Organic-certified and residue-tested products capture disproportionate shelf space as retailers preempt compliance risk.
On-premise consumption patterns are fragmenting traditional retail-centric distribution models. Foodservice operators and convenience channels demand single-serve pouches and ambient-stable formats that depart from refrigerated carton conventions. Brazil's São Paulo state and Florida's processing clusters are adapting export packaging configurations to serve this channel rotation.
Juice Market Segmentation
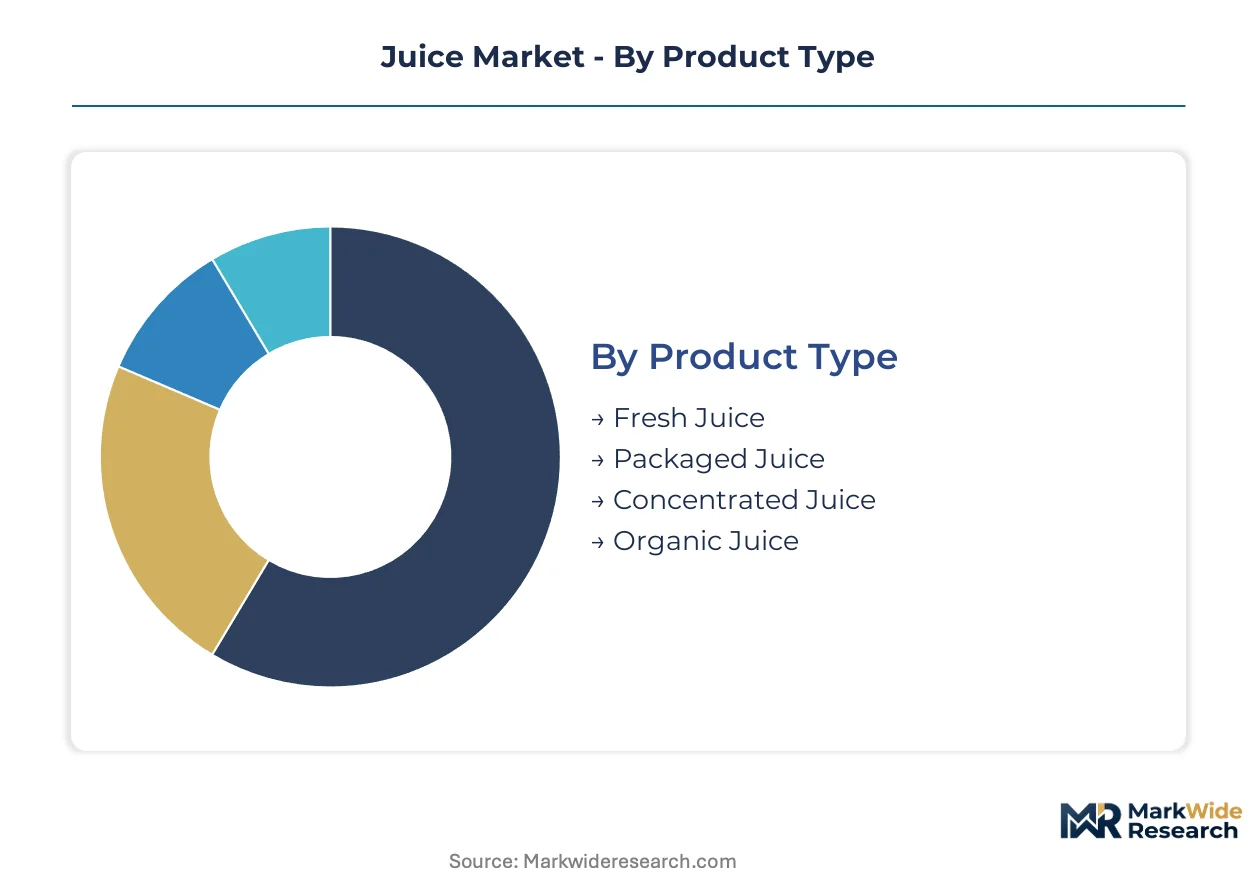
Juice market segmentation reveals how processing intensity, ingredient sourcing, and channel economics fragment commercial opportunity. Manufacturers must align formulation and packaging investments to distinct margin profiles and shelf-life requirements across these dimensions.
Product Type:
Standardization dominates at volume scale while premium tiers demand customized processing infrastructure and shorter supply chains.
- Fresh Juice:Unpasteurized extracts with shelf lives under 45 days requiring continuous cold-chain integrity. Demand concentrates in urban foodservice clusters across São Paulo and Florida where health-conscious consumers pay premiums for enzyme retention.
- Packaged Juice:Thermally stabilized or HPP-treated products in shelf-stable formats enabling mass retail distribution. This segment commands the largest revenue pool through extended distribution reach and lower logistics costs.
- Concentrated Juice:Water-reduced extracts reconstituted at point of sale, favored by institutional buyers and private-label retailers seeking transport efficiency.
- Organic Juice:USDA-certified or equivalent residue-free products with audited supply chains. Expansion is steepest in this segment as certification gates access to premium shelf space in North American and European retail.
Most installed capacity flows through Packaged Juice. Expansion is steepest in Organic Juice.
Ingredient:
Geographic sourcing concentration creates divergent cost structures and supply security profiles across fruit categories.
- Citrus:Orange, grapefruit, and lemon derivatives processed through extraction and pasteurization. Brazil's São Paulo state and Florida's Indian River district anchor global supply, with not-from-concentrate orange juice commanding the highest price realization.
- Berries:Blueberry, cranberry, and raspberry blends with high antioxidant positioning. Demand concentrates in European supermarket premium tiers where functional health claims drive placement.
- Tropical Fruits:Pineapple, mango, and passion fruit extracts sourced from Costa Rica and Southeast Asian processing clusters.
- Stone Fruits:Peach, apricot, and nectarine nectars with higher pulp content and thicker viscosity profiles.
Citrus maintains the deepest processing infrastructure. Berry blends are climbing the fastest on functional positioning.
Packaging Type:
Format selection trades shelf stability, branding surface area, and logistics cube efficiency against per-unit cost.
- Bottles:PET and glass containers offering premium visibility and resealability for refrigerated not-from-concentrate products. Major brands deploy shaped bottles as shelf differentiation in North American retail.
- Cartons:Paperboard laminates for ambient-stable juices in multi-serve family formats. This format dominates volume throughput in European and Latin American retail channels.
- Pouches:Flexible film structures with fitments or straws for single-serve consumption. Foodservice and convenience channels are displacing rigid containers with this format for grab-and-go occasions.
- Tetra Packs:Aseptic brick cartons enabling unrefrigerated distribution with 12-month shelf life. Tetra Pak's equipment lock-in creates high switching costs for processors.
Cartons and Tetra Packs together carry the majority of ambient volume. Pouch penetration is gaining share fastest in foodservice rotation.
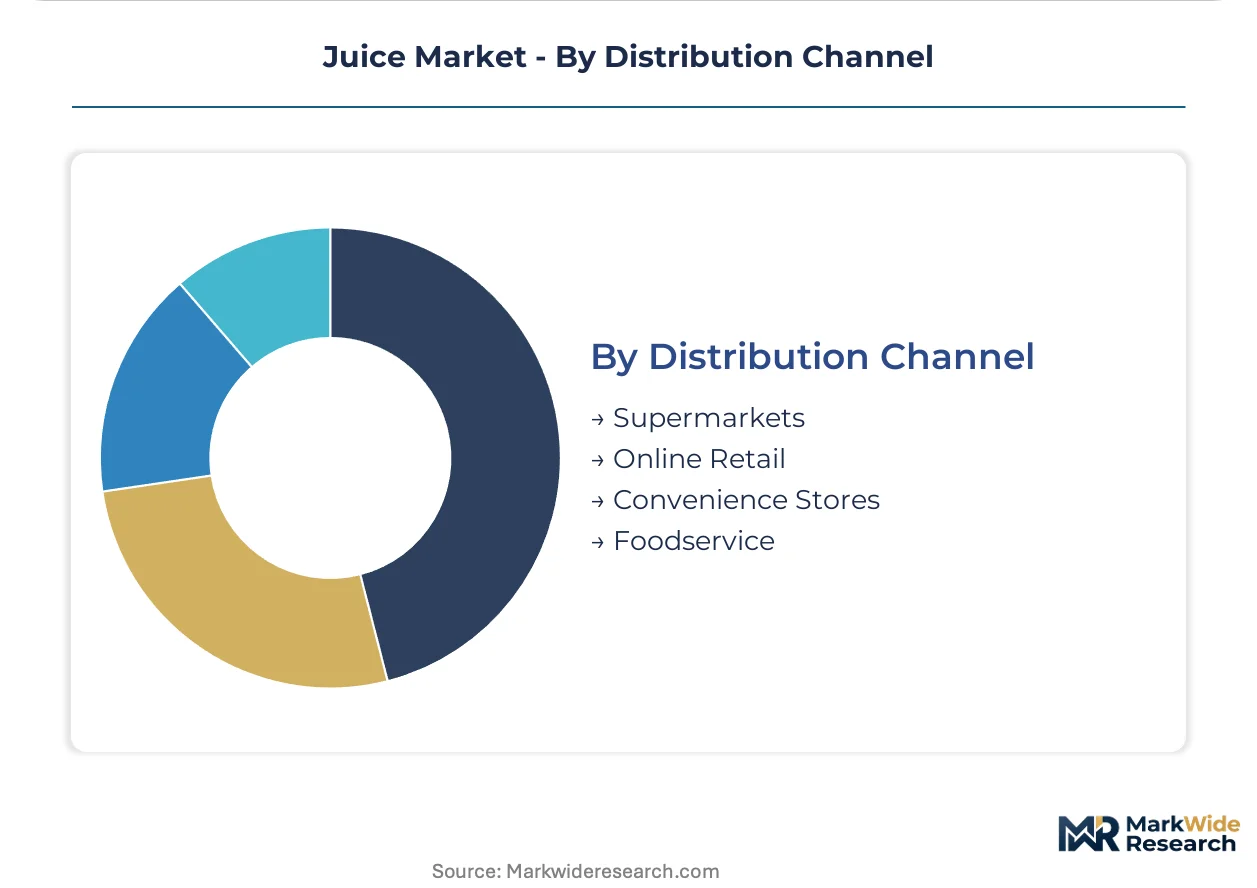
Distribution Channel:
Channel economics separate high-frequency replenishment models from destination shopping and impulse capture formats.
- Supermarkets:Full-assortment retail with refrigerated and ambient sets, private-label competition, and promotional intensity. This channel demands slotting fees and category management investment that favors integrated beverage conglomerates.
- Online Retail:Direct-to-consumer and platform-mediated sales with subscription models for organic and cold-pressed variants. Urban millennial households in São Paulo and US coastal metros drive trial and reorder frequency.
- Convenience Stores:Single-serve ambient and chilled grab-and-go placement with high margin compression and rapid inventory turns.
- Foodservice:Fountain, pre-portioned, and bulk formats for restaurants, cafeterias, and hospitality. This channel requires customized packaging configurations and food-safety documentation distinct from retail.
Supermarkets retain the largest absolute volume. Online Retail is expanding most quickly on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's citrus processing clusters anchor the industry's geographic configuration, concentrating extraction capacity and export logistics for not-from-concentrate orange juice. Brazil's infrastructure connects to Florida's Indian River district and Mediterranean packing houses in Spain and Italy. Regulatory divergence across FDA, EFSA, and ANVISA jurisdictions shapes formulation and labeling investments.
Brazil
ANVISA's updated food labeling regulations mandate front-of-pack nutritional warnings that compress conventional sweetened juice volumes. São Paulo state's processing corridor delivers scale economies for not-from-concentrate exports to North American and European buyers. Citrosuco and Louis Dreyfus operate integrated extraction-to-port facilities in the Araraquara region.
United States
Millennial households in coastal metros drive cold-pressed and organic juice adoption through subscription and direct-to-channel models. The FDA's Juice HACCP regulation mandates pathogen control investments that favor integrated beverage conglomerates over mid-scale processors. Florida's Indian River district maintains not-from-concentrate orange juice capacity despite hurricane-driven harvest volatility.
Germany
EU Green Deal Farm-to-Fork compliance requirements gate supermarket shelf access for imported juice concentrates. The country's beverage retailers demand pesticide residue documentation and sustainable sourcing certifications from Brazilian and Spanish suppliers. Hamburg's port infrastructure handles bulk concentrate imports for reconstitution and private-label packaging.
China
SAMR's tightened food safety standards for imported juice products require enhanced traceability documentation from foreign suppliers. Yangtze River Delta urban consumers demonstrate willingness-to-pay for premium NFC orange juice and botanical-infused variants. Shanghai's cold-chain logistics networks enable refrigerated distribution for temperature-sensitive products.
India
FSSAI's fortification guidelines and labeling mandates reshape domestic juice formulation toward micronutrient-enhanced products. Maharashtra's Nashik district hosts mango and pomegranate processing clusters serving both export and urban retail channels. Mumbai and Delhi metropolitan markets exhibit accelerating demand for packaged juice in Tetra Pak and pouch formats.
Juice Market Competitive Environment
Portfolio diversification dominates the current landscape as conglomerates defend shelf position against insurgent cold-pressed and functional juice specialists. The market exhibits consolidated revenue concentration at the top tier alongside fragmentation in organic and regional premium segments. Two strategic archetypes predominate: integrated beverage giants with captive citrus supply chains, and agile specialists leveraging HPP technology for clean-label positioning. M&A activity and capacity expansion in high-pressure processing represent the dominant competitive vectors.
Within the integrated beverage tier, The Coca-Cola Company and PepsiCo Inc. exemplify scale-driven supply chain control, while Nestle S.A. occupies a position emphasizing botanical-infused premium lines. These three conglomerates anchor the industry's infrastructure investments, with Coca-Cola's Minute Maid operations and PepsiCo's Tropicana refrigerated logistics representing distinct approaches to distribution economics. Keurig Dr Pepper Inc. sits within a hybrid archetype combining mainstream retail presence with emerging functional beverage adjacencies.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc. |
| Tropicana Brands Group |
| Keurig Dr Pepper Inc. |
| Nestle S.A. |
| Ocean Spray |
| Del Monte Foods Corporation |
| Dole Packaged Foods LLC |
| Suntory Holdings Ltd. |
| Others |
Value Chain & Pricing Dynamics
Integrated beverage conglomerates with captive citrus sourcing dominate procurement volumes, anchoring contract-based offtake pricing that insulates them from spot-market volatility in São Paulo and Florida. This buyer concentration compresses margins for mid-scale processors while rewarding scale economies in high-pressure processing infrastructure.
Pricing Analysis
Input-cost pass-through from weather-driven citrus harvest fluctuations in Florida and São Paulo state squeezes processor margins unpredictably. Three-tier pricing structure across premium, standard, and economy levels separates USDA-certified organic lines from conventional not-from-concentrate and private-label reconstituted variants. Price differentiation hinges on certification grade and cold-chain logistics capability, with refrigerated distribution commanding shelf-space premiums. Price erosion runs through economy-tier private-label channels as retailers consolidate procurement, while premium HPP-treated products demonstrate inelastic demand among health-conscious millennials.
Supply Chain Analysis
Direct-to-retail channels handle ambient-stable carton volumes while refrigerated distribution serves not-from-concentrate freshness positioning in North American supermarkets. Geographic supply concentrates in Brazil's São Paulo state, Florida's Indian River district, and Spain's Mediterranean packing houses for citrus extraction. Raw material dependencies center on orange concentrate, aseptic carton laminates, and cold-chain refrigerants. Single-source vulnerability in Tetra Pak's aseptic equipment lock-in threatens ambient distribution continuity. Distribution runs through port-centric export corridors connecting São Paulo's Araraquara region to Hamburg and Shanghai cold-chain terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The juice market functions as a stable compounder where health-conscious consumption shifts and regulatory disclosure tightening generate persistent organic expansion. Clean-label mandates and certification premiums create durable pricing power for compliant supply chains.
For Market Incumbents: Extend high-pressure processing capacity in São Paulo state to capture clean-label shelf-space premiums before mid-scale processors achieve HACCP compliance scale. Defensive consolidation of refrigerated logistics networks protects against insurgent cold-pressed specialists leveraging direct-to-consumer subscription models. Backward integration into Brazilian citrus groves secures input cost insulation from hurricane-driven Florida harvest volatility.
For New Entrants and Emerging Players: Urban millennial households in China's Yangtze River Delta represent an underserved buyer archetype with demonstrated willingness-to-pay for premium NFC orange juice and botanical-infused variants. Foodservice pouch formats in Indian metropolitan markets offer penetrable white-space with lower slotting-fee barriers than supermarket retail. Direct-to-channel subscription models bypass incumbent refrigerated logistics moats.
For Investors and Strategic Acquirers: Integrated beverage conglomerates are the most active acquirer in this space, targeting HPP technology specialists and organic-certified supply chains. Long-term viability frames around residue-free certification and sustainable sourcing documentation as EU Green Deal compliance gates European market access. Watch pesticide residue disclosure mandates as the inflection indicator for premium shelf-space reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | HPP technology unifies pasteurization efficacy with nutrient retention for clean-label positioning in North American retail. |
| Organic Certification Investment | USDA standards gate access to premium shelf-space and price realization advantages in supermarket channels. |
| Foodservice Pouch Format Penetration | Flexible packaging displaces rigid containers in grab-and-go occasions across convenience and on-premise channels. |
| EU Green Deal Compliance Program | Farm-to-Fork alignment creates competitive moat for exporters demonstrating pesticide reduction and traceability documentation. |
| Direct-to-Consumer Subscription Launch | Urban millennial households in São Paulo and US coastal metros drive trial frequency for cold-pressed variants. |
Study Parameters
Bottom-up channel modeling reconciled against top-down citrus processing capacity tracking forms the analytical core of this study. Primary interviews with category buyers at beverage retailers, supply planners at integrated conglomerates, cold-chain logistics operators, and regulatory affairs specialists at exporters were cross-validated against FDA Juice HACCP filings, ANVISA labeling regulations, USDA organic certification databases, and customs trade records for concentrate imports. Triangulation between demand-side consumption pattern analysis and supply-side extraction capacity assessments ensures dimensional consistency.
Input-output matrix framing connects São Paulo state processing volumes to export destination demand across refrigerated and ambient channel configurations. Segmentation dimensions modeled include product type, ingredient sourcing, packaging format, and distribution channel across the analysis window. CAGRs were derived from trend extrapolation of clean-label adoption rates, organic certification growth curves, and HPP technology penetration in not-from-concentrate orange juice. Forecast inputs incorporate weather-driven harvest volatility patterns and regulatory disclosure tightening trajectories.
Inputs from primary stakeholder interviews and secondary regulatory filings were available through the study window; gaps in real-time citrus inventory data and private-label pricing transparency introduce uncertainty bands around volume forecasts. Forecasts reflect assumptions regarding continued health-conscious consumption shifts and sustained certification premium realization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Packaged Natural Mineral Water Market
Beverages
Global Squash Drinks Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Beverage Dispenser Market
Beverages
Bottled Water Processing Market
Beverages
Sports and Energy Drinks Market
Beverages
Europe Probiotic Drinks Market
Beverages
Packaged Milkshake Market
Beverages
South America Energy Drink Market
Beverages
Collagen-Infused Water Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Popping Bobas Market
Beverages
Baby Drinking Water Market
Beverages
Soft Serve Premix Market
Beverages
Europe Animal-Based Food and Beverage Market