
 Sheet Metal Processing Equipment Market | 2026-2036
Sheet Metal Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sheet Metal Processing Equipment Market Analysis
Automotive OEMs is rotating share toward electronics manufacturing as the fastest-growing buyer archetype for precision sheet metal equipment. TRUMPF Group dominates fiber laser cutting systems through its vertical integration into beam source production. Amada Co., Ltd. anchors its position in servo-electric press technology across Asian manufacturing hubs. Salvagnini differentiates through automated panel bending lines that reduce labor dependency in high-mix production environments.
Sheet metal processing equipment encompasses machinery that cuts, forms, joins, or finishes thin-gauge metal stock typically ranging from 0.5 mm to 6 mm thickness, operating through mechanical force, thermal energy, or electromagnetic processes to produce dimensionally precise components for industrial assembly. Laser cutters lead product type revenue due to rising throughput requirements in appliance manufacturing, while punching machines retain stable replacement demand from metal fabrication job shops. Electrical technology is displacing hydraulic systems in press brakes as factory energy audits tighten operational cost scrutiny across European and North American installed bases.
EU machinery directives and China's GB standards enforce mandatory safety interlocks and electromagnetic compatibility certification for imported equipment, elevating compliance costs for non-domestic suppliers. OSHA lockout/tagout rules and EPA air emission limits for cutting operations further shape equipment specification requirements in the United States. Stakeholders must weigh regional certification timelines against localized aftermarket service density when prioritizing geographic expansion investments.
Market Dynamics
Servo-electric press brakes are compressing hydraulic system margins as automotive OEMs pursue factory energy audit compliance and operational cost reduction across European and North American installed bases.
Growth Catalysts
- EU machinery directives:Mandatory safety interlocks and electromagnetic compatibility certification create upgrade cycles among fabricators seeking CE marking compliance for cross-border equipment mobility.
- Appliance manufacturing throughput:Rising production velocity requirements in white goods assembly are pulling fiber laser cutting capacity expansions across China's Yangtze River Delta corridor.
- Servo-electric actuation:Factory energy audits in Germany's precision engineering cluster around Stuttgart are accelerating displacement of hydraulic press brake architectures.
Market Restraints
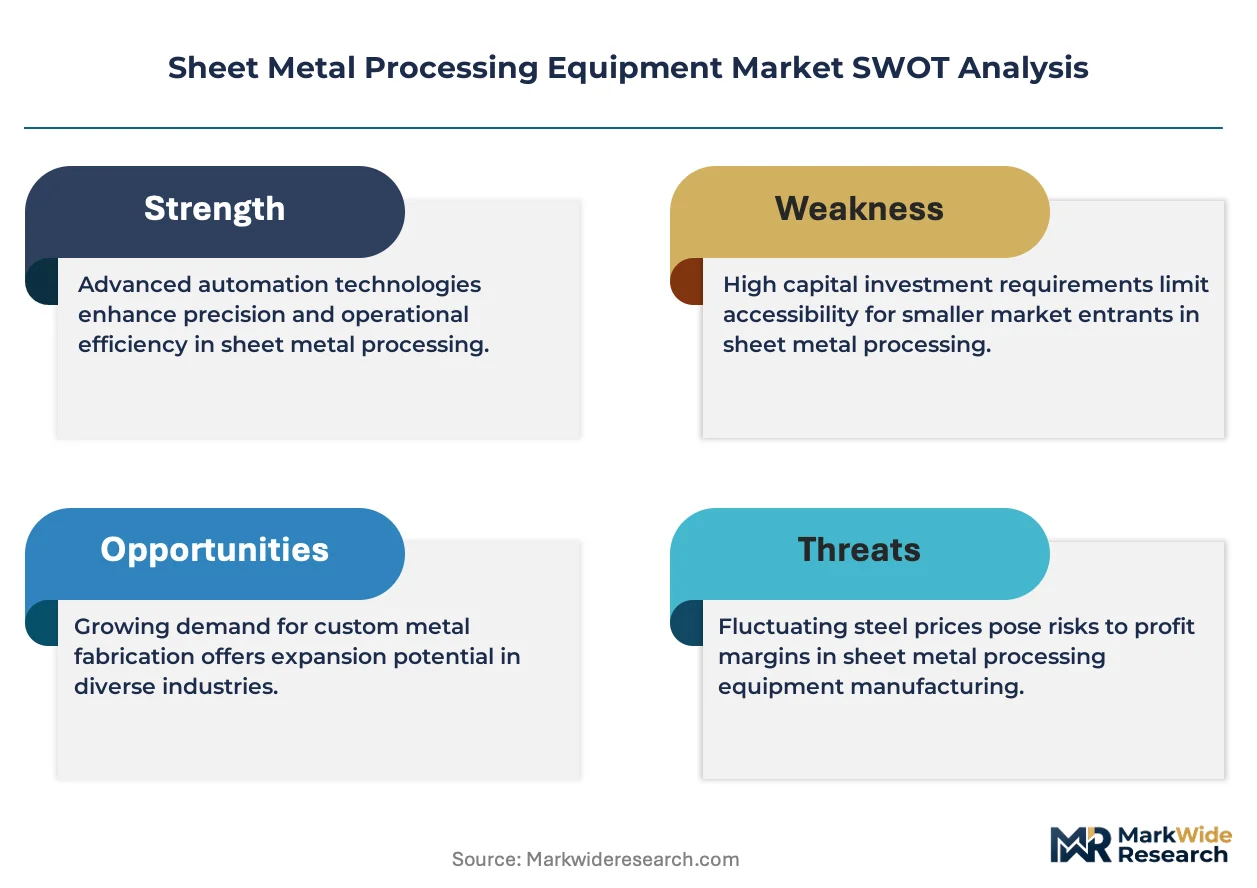
- Steel price volatility:Input cost swings for carbon and stainless steel sheet stock compress job shop equipment investment timelines and financing confidence.
- Beam source supply concentration:Fiber laser resonator manufacturing clusters in Germany and Japan create vulnerability for cutting system assemblers lacking captive photonics capability.
- GB standards friction:China's mandatory electromagnetic compatibility and energy-efficiency testing extends certification timelines for European and Japanese equipment exporters.
Strategic Opportunities
- Vietnam electronics manufacturing:Underpenetrated precision sheet metal fabrication capacity serving smartphone and laptop assembly creates whitespace for automated panel bending line deployment.
- US Inflation Reduction Act:Domestic content incentives for clean energy equipment manufacturing are redirecting solar inverter and battery enclosure fabrication toward North American job shops.
- Machine learning vision:Convergence of real-time defect detection algorithms with servo-electric forming is enabling unattended high-mix production in metal fabrication environments.
Industry Challenges
- CNC programming specialization:Shortage of operators capable of nesting optimization and collision-free toolpath generation for 5-axis laser systems constrains equipment utilization rates.
- Legacy hydraulic integration:Retrofitting existing press brake footprints with servo-electric architectures requires mechanical frame reinforcement and control system replacement, extending downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sheet Metal Processing Equipment Market |
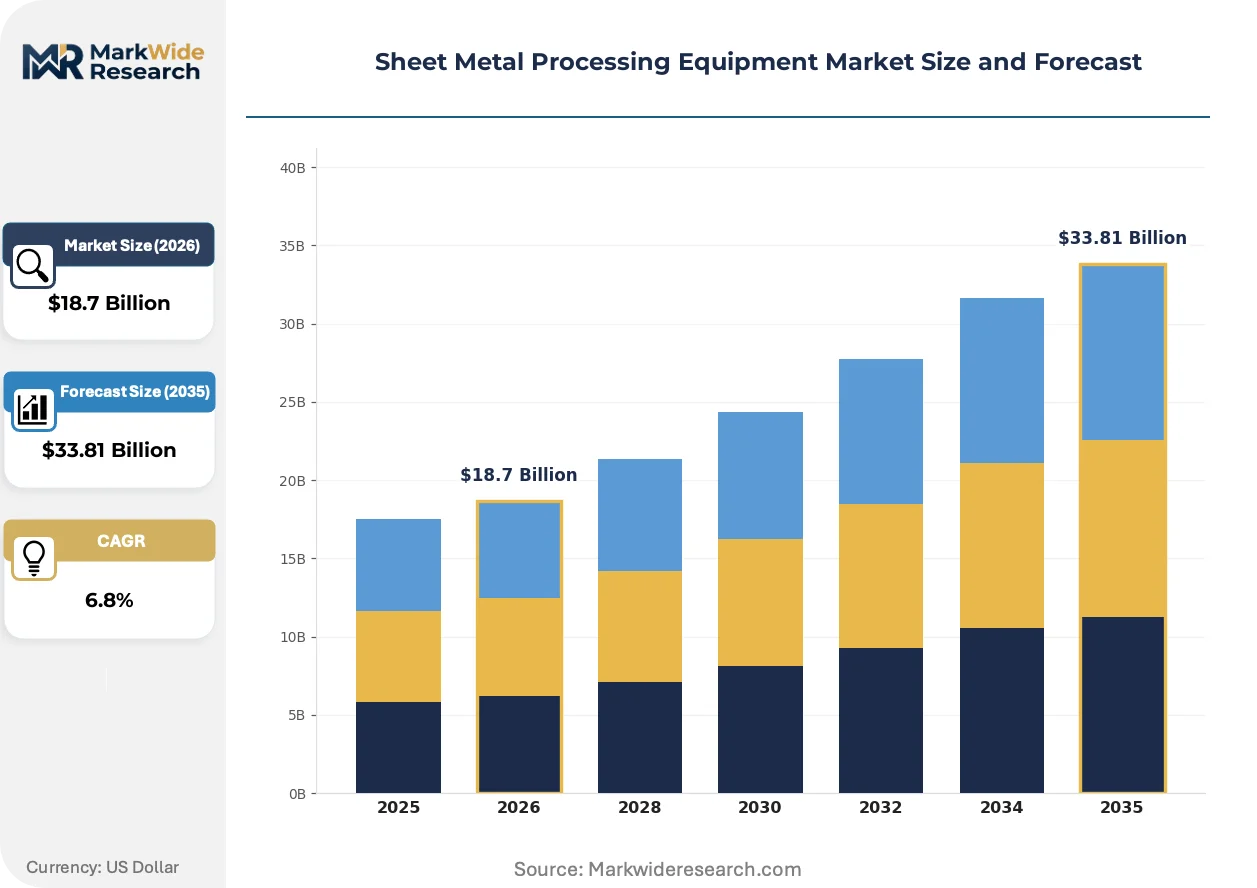
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutters, Press Brakes, Punching Machines, Welding Equipment End User: Aerospace, Automotive OEMs, Construction, Electronics Manufacturing Technology: Hydraulic, Pneumatic, Mechanical, Electrical Application: Metal Fabrication, HVAC, Appliance Manufacturing, Metal Stamping |
| Companies Covered | Schuler AG, Prima Power, TRUMPF Group, DMG Mori, Salvagnini, Amada Co., Ltd., LVD Group, Mitsubishi Electric Corporation, Bystronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sheet Metal Processing Equipment Market Emerging Trajectories
Automation architectures and energy-efficiency mandates are restructuring equipment specification priorities across automotive, electronics, and appliance manufacturing verticals, compressing traditional technology lifecycles.
Fiber laser cutting systems are supplanting CO2 resonator platforms in thick-gauge processing applications through superior wall plug efficiency and reduced mirror maintenance requirements. Automotive OEMs in Germany and appliance manufacturers in China are specifying fiber sources above 12kW for stainless steel processing above 6mm thickness. The technology is supplanting plasma and oxy-fuel alternatives in medium-thickness structural fabrication, compressing downstream grinding and deburring labor requirements.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules are pressuring hydraulic system suppliers to reformulate fluid chemistries and seal compounds. Equipment manufacturers face reformulation costs for biodegradable hydraulic alternatives or accelerated servo-electric migration. Press brake and punching machine categories face the steepest compliance timelines, with German OEMs already certifying mineral-oil-free architectures for 2027 delivery commitments.
Equipment-as-a-service contracting is displacing traditional capital purchase models among metal fabrication job shops with volatile order books. German and US distributors are unbundling maintenance, software updates, and consumable provisioning into per-hour or per-part pricing structures. Electronics contract manufacturers in Mexico and Vietnam exhibit the highest service-contract attachment rates, prioritizing uptime guarantees over asset ownership.
Sheet Metal Processing Equipment Market Segmentation
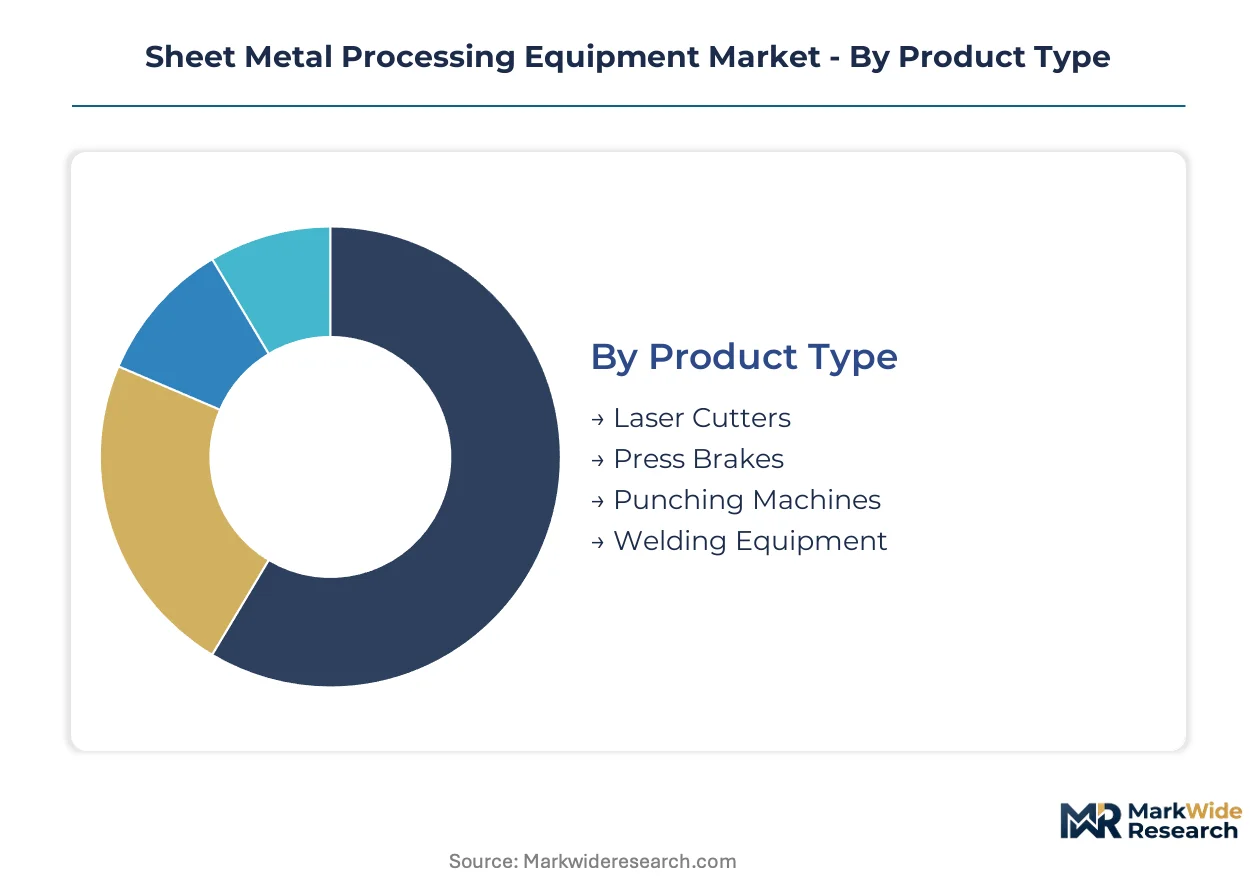
Equipment specification priorities diverge sharply across buyer archetypes in this market. Automotive OEMs demand servo-electric architectures for energy compliance, while job shops prioritize flexible punching-laser combinations for high-mix throughput.
Product Type:
Margin pools concentrate in fiber laser cutting systems where beam source integration and software licensing create recurring revenue streams.
- Laser Cutters:Fiber resonator platforms above 12kW dominate thick-gauge stainless processing through superior wall plug efficiency and reduced mirror maintenance. Appliance manufacturers across China's Yangtze River Delta corridor are specifying these systems for production velocity expansion.
- Press Brakes:Servo-electric actuation architectures displace hydraulic systems as factory energy audits tighten operational cost scrutiny across German and North American installed bases. Automotive OEMs in Stuttgart's precision engineering cluster lead this specification shift.
- Punching Machines:Stable replacement demand persists from metal fabrication job shops seeking flexible tool libraries for high-mix production environments.
- Welding Equipment:Automated seam tracking systems gain specification in electronics contract manufacturing for battery enclosure and inverter cabinet assembly.
The dominant share belongs to laser cutters, while press brakes are closing the gap fastest.
End User:
Volume concentration tracks manufacturing investment cycles across durable goods and infrastructure verticals.
- Automotive OEMs:Factory energy audit compliance mandates accelerate servo-electric press brake procurement across European and North American assembly operations. Electrification platform launches require precision-formed battery tray and motor housing components.
- Electronics Manufacturing:Smartphone and laptop assembly drives automated panel bending line deployment. Vietnam's underpenetrated fabrication capacity creates whitespace for equipment vendors.
- Aerospace:Titanium and aluminum processing specifications favor fiber laser systems with adaptive beam shaping for heat-affected zone control.
- Construction:Structural steel fabrication maintains stable demand for plasma and oxy-fuel alternatives in medium-thickness applications.
Automotive OEMs command the largest equipment procurement budgets, though electronics manufacturing is expanding most quickly.
Technology:
Regulatory pressure on fluid chemistries and energy efficiency is restructuring competitive positioning across actuator architectures.
- Electrical:Servo-motor actuation delivers programmable stroke control and regenerative energy recovery. EU F-Gas Regulation phase-down schedules and REACH substance restrictions accelerate displacement of hydraulic alternatives.
- Hydraulic:Mineral-oil-free fluid formulations face steep compliance timelines under German OEM certification requirements for 2027 delivery commitments.
- Pneumatic:Compressed air systems retain niche positioning in punching applications requiring rapid cycle rates with lower force precision.
- Mechanical:Flywheel and clutch architectures persist in high-volume metal stamping with dedicated tooling configurations.
Electrical technology is gaining share fastest, while hydraulic systems defend installed base replacement cycles.
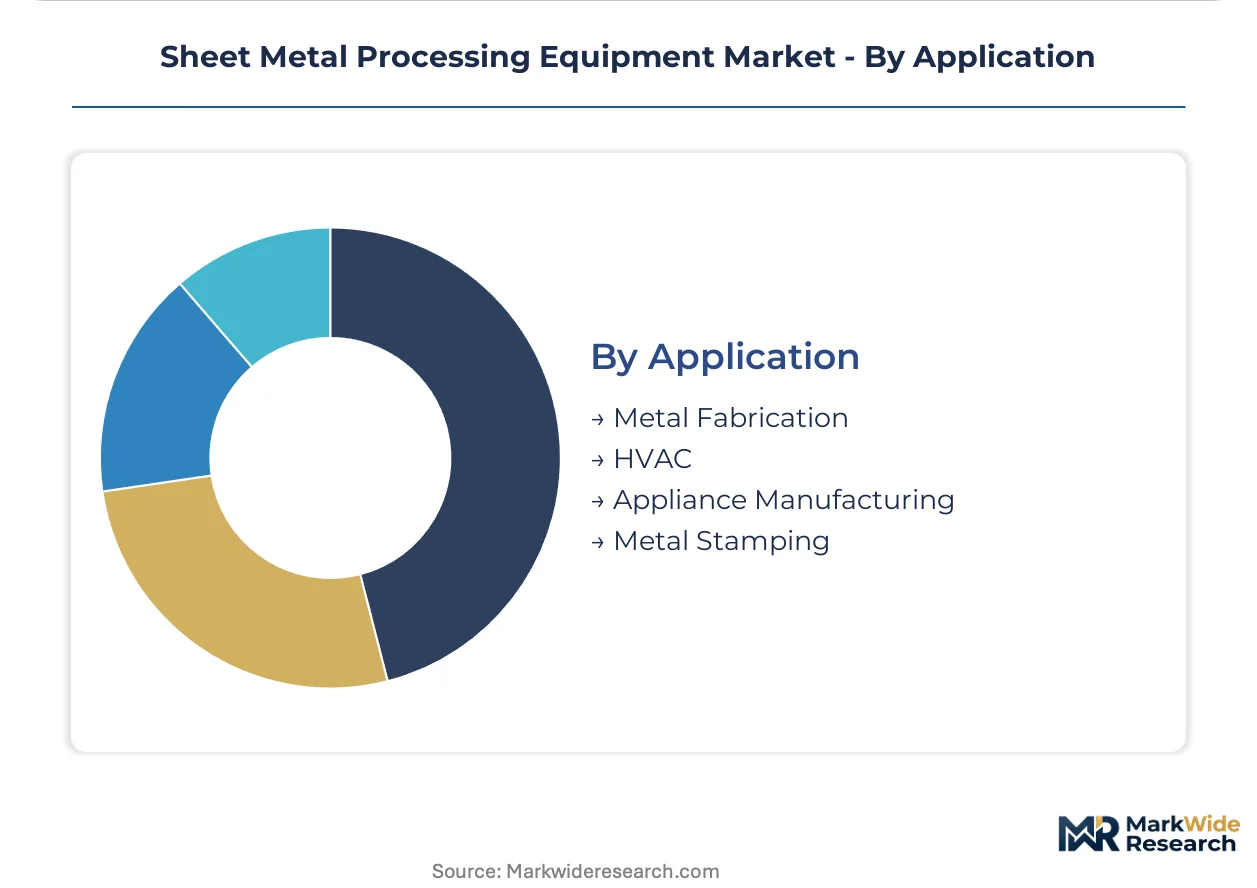
Application:
Customer workflow integration determines equipment specification complexity and aftermarket service attachment rates.
- Metal Fabrication:Job shops with volatile order books favor equipment-as-a-service contracting with per-hour pricing structures. German and US distributors lead this model unbundling.
- Appliance Manufacturing:White goods assembly pulls fiber laser capacity expansions through rising throughput requirements in sheet metal enclosure production.
- Metal Stamping:Dedicated progressive die operations specify mechanical press architectures for high-volume automotive and electronics component output.
- HVAC:Ductwork and enclosure fabrication maintains steady demand for mid-range punching and sheeting combinations.
Metal fabrication captures the broadest equipment mix, while appliance manufacturing drives the steepest capacity expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's machinery export dominance, while China's Ningbo-Zhoushan port complex anchors Asian sheet metal equipment distribution networks.
Germany
Factory energy audits in Stuttgart's precision engineering cluster accelerate servo-electric press brake procurement. The EU F-Gas Regulation phase-down schedules pressure hydraulic system suppliers toward mineral-oil-free architectures. Baden-Württemberg's automotive OEM concentration drives compliance-focused equipment replacement cycles.
China
GB standards enforcement extends certification timelines for European and Japanese equipment exporters. The Yangtze River Delta manufacturing corridor pulls fiber laser capacity expansions from appliance manufacturers seeking production velocity gains. Shanghai's port infrastructure enables rapid import clearance for high-value cutting systems.
United States
OSHA lockout/tagout rules shape press brake specification requirements across metal fabrication job shops. The Inflation Reduction Act redirects solar inverter and battery enclosure fabrication toward domestic suppliers. Texas and Michigan automotive assembly operations drive precision-formed component demand.
Japan
METI industrial efficiency guidelines promote servo-electric actuation adoption in legacy manufacturing facilities. JIS standards certification creates friction for non-domestic equipment suppliers seeking market access. Nagoya's automotive supply chain concentration maintains stable punching machine replacement demand.
Vietnam
Electronics contract manufacturing expansion creates whitespace for automated panel bending line deployment. The country's national industrial standards authority extends electromagnetic compatibility testing timelines for imported machinery. Ho Chi Minh City's emerging fabrication hub serves smartphone and laptop assembly operations.
Sheet Metal Processing Equipment Market Vendor Landscape
Concentration sits with diversified machinery conglomerates controlling captive beam source production and software licensing revenue streams. The vendor base stratifies across three tiers: integrated photonics specialists, regional fabrication equipment houses, and emerging Asian challengers. German and Japanese incumbents defend position through backward integration into resonator manufacturing. Strategic moves center on M&A for software capabilities and capacity expansion in Southeast Asian service hubs.
Among German-based diversified industrials, Schuler AG and TRUMPF Group exemplify the integrated photonics archetype through upstream control over critical component supply. Amada Co., Ltd. anchors the Asian equipment house category with established manufacturing footprint. These three occupy positions defined by geographic origin and structural integration depth rather than segment-specific specialization.
| Leading Market Players |
|---|
| Schuler AG |
| Prima Power |
| TRUMPF Group |
| DMG Mori |
| Salvagnini |
| Amada Co., Ltd. |
| LVD Group |
| Mitsubishi Electric Corporation |
| Bystronic |
| Others |
Supply Flow & Price Mechanics
Servo-electric actuation displacing hydraulic architectures redraws procurement geography toward Germany and Japan while compressing margin pools for fluid-system suppliers dependent on mineral-oil formulations. This substitution dynamic elevates pricing power for captive beam-source manufacturers and reshapes total-cost-of-ownership calculations for automotive OEMs auditing factory energy consumption.
Pricing Analysis
Volume-discount tiering structures separate CE-certified fiber laser systems from standard-tier punching combinations and economy-grade hydraulic press brakes. Price differentiation rests on electromagnetic compatibility certification under China's GB standards and energy-efficiency ratings for EU machinery directive compliance. Cost compression in mid-range servo-electric press brakes intensifies as German OEMs certify mineral-oil-free architectures. Metal fabrication job shops exhibit highest price sensitivity, while automotive OEMs prioritize lifecycle operational cost over acquisition price.
Supply Chain Analysis
Extended lead times for fiber laser resonators sourced from Germany and Japan constrain cutting system assemblers lacking in-house photonics capability. Beam source manufacturing concentrates in German and Japanese industrial clusters, while final equipment assembly feeds from Chinese and Taiwanese control electronics suppliers. Single-source vulnerability sits with rare-earth-doped fiber suppliers for resonator gain media. Distribution runs through Hamburg and Ningbo-Zhoushan port complexes serving European and Asian manufacturing corridors respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of CNC programmers capable of 5-axis laser nesting optimization constrains equipment utilization rates and creates arbitrage opportunity for training-capable vendors. This capability gap separates high-throughput operations from stranded capital in metal fabrication environments.
For Market Incumbents: Fortify backward integration into beam source production to defend margin pools against emerging Asian challengers with captive photonics capability. Prioritize software licensing revenue streams for nesting optimization and collision-free toolpath generation. Expand service hub capacity in Vietnam's Ho Chi Minh City corridor to capture electronics manufacturing whitespace. For New Entrants and Emerging Players: GB standards fast-track certification for servo-electric press brake architectures opens procurement channels among Yangtze River Delta appliance manufacturers seeking production velocity gains. Target Vietnam's underpenetrated automated panel bending capacity serving smartphone and laptop assembly. Lead with equipment-as-a-service contracting to displace capital purchase resistance among volatile-order-book job shops. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed metal fabrication equipment distributors in Germany and the United States with unconsolidated aftermarket service networks. Five-to-ten year viability favors vendors controlling software-defined forming parameters and real-time defect detection algorithms. Watch for inflection in US Inflation Reduction Act domestic content enforcement redirecting solar inverter enclosure fabrication toward North American suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Beam Source Production | Captive fiber laser resonator supply insulates TRUMPF and Schuler from Japanese photonics bottlenecks. |
| Mineral-Oil-Free Hydraulic Certification | German OEMs meeting EU F-Gas Regulation timelines defend installed base replacement cycles against electrical substitution. |
| Southeast Asian Service Hub Expansion | Ho Chi Minh City proximity reduces response times for Vietnam's electronics contract manufacturing panel bending lines. |
| Equipment-as-a-Service Contracting | Per-hour pricing structures unlock job shop segments with volatile order books and limited capital access. |
| Machine Learning Vision Integration | Real-time defect detection algorithms enable unattended high-mix production in metal fabrication environments. |
Methodological Framework
Desk research of trade flow databases, machinery customs records, and EU machinery directive implementation guidance preceded structured interviews with plant engineers, aftermarket service heads, OEM procurement teams, and maintenance directors across German, Chinese, and North American manufacturing clusters. Primary fieldwork captured equipment specification priorities, replacement cycle timing, and software licensing attachment rates. Secondary validation drew from SEC filings of listed machinery conglomerates, METI industrial efficiency reports, and GB standards certification timelines. Bottom-up demand modeling triangulated against top-down manufacturing investment cycle analysis.
Variance decomposition across product type, end-user vertical, technology architecture, and geographic production cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include equipment category, buyer archetype, actuator technology, and application workflow integration. CAGRs derived from equipment shipment volumes, replacement cycle assumptions, and capacity expansion announcements. Industry-specific forecast inputs incorporated factory energy audit penetration rates and GB standards enforcement timelines.
Underlying assumptions cover sustained automotive electrification platform launches, continued EU F-Gas Regulation phase-down adherence, and stable appliance manufacturing throughput in China's Yangtze River Delta corridor, with deviation risk concentrated in steel price volatility and beam source supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Seafood Processing Equipment Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Food Recycler Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Shrimp Peeling Machine Market
Food Processing Equipment
Pizza Preparation Refrigerator Market
Food Processing Equipment
Food Processing Equipment Market
Food Processing Equipment
Bottled Water Processing Equipment Market
Food Processing Equipment
Deaeration Machine Market
Food Processing Equipment
Optical Sorter Market
Food Processing Equipment
Corn Puff Making Machine Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Residential Food Waste Disposer Market