
 Fruit Yogurt Market | 2026-2036
Fruit Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Yogurt Market Foresight
Single-serve cup-to-multi-pack bundling is repositioning household purchase patterns across developed markets. Danone leverages its refrigerated logistics network to sustain shelf dominance in European retail. Chobani Global Holdings anchors its portfolio in Greek-style fruit blends with higher protein positioning. Nestlé competes through pediatric-oriented formulations that extend its dairy expertise into toddler segments.
Fruit yogurt denotes a fermented dairy product containing live bacterial cultures, fruit preparations, and stabilizers, typically manufactured through controlled incubation at 40–45°C followed by fruit blending and cold-chain distribution. It serves as a convenient protein and probiotic delivery vehicle for daily consumption. Strawberry yogurt and blueberry yogurt occupy the mature volume core where margin compression is most acute, while mango yogurt captures the fastest growth trajectory in tropical and diaspora markets. Cup packaging retains the largest share of retail-facing SKUs, though tube formats gain traction in children's lunchbox occasions.
FDA nutrition labeling requirements and EU F-Gas Regulation on refrigeration emissions shape formulation and cold-chain investment decisions for cross-border suppliers. India's FSSAI fortification guidelines and China's GB standards on dairy imports create divergent compliance thresholds that fragment export strategies. Stakeholders must monitor evolving sugar taxation regimes and refrigeration energy standards to calibrate regional product portfolios.
Market Dynamics
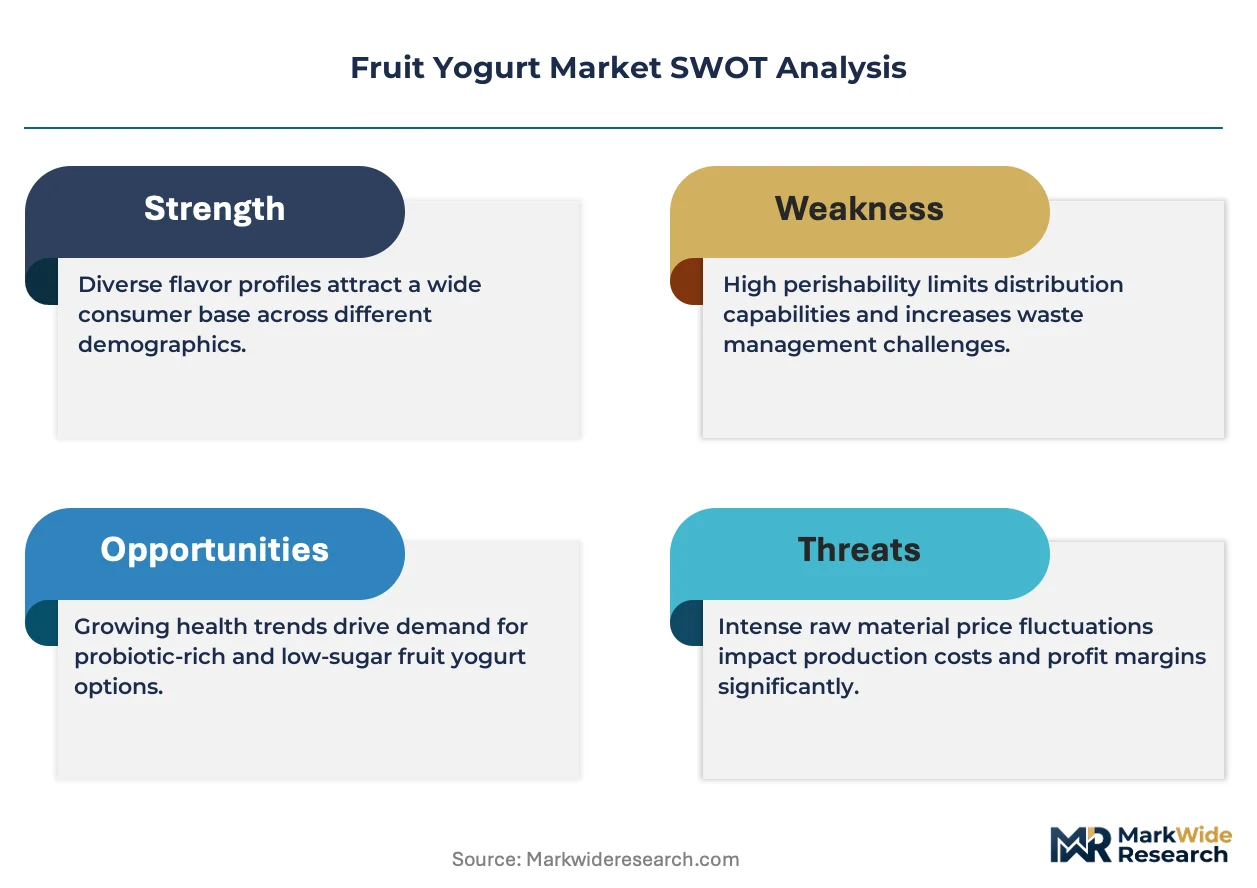
Refrigerated supply chain modernization in emerging economies is redrawing competitive boundaries, as cold-chain infrastructure gaps once excluded mass-market penetration. India's FSSAI fortification guidelines and China's GB standards on dairy imports create divergent compliance thresholds that fragment export strategies and redirect capital toward localized production.
Growth Catalysts
- EU F-Gas Regulation:Emissions caps on hydrofluorocarbon refrigerants are accelerating investment in natural refrigeration systems across European dairy processing facilities.
- Urban India:Modernization of refrigerated logistics networks in Mumbai, Delhi, and Bangalore is unlocking household penetration previously blocked by spoilage risk.
- Clean-label reformulation:Pressure from added-sugar taxation regimes is driving R&D spending toward fruit-sweetened formulations and stabilizer reduction.
Market Restraints
- Milk powder price volatility:Global dairy commodity swings compress margin predictability for manufacturers dependent on reconstituted base stocks.
- Single-origin fruit concentrate sourcing:Reliance on seasonal mango pulp from Maharashtra and Alphonso supply concentration creates input vulnerability.
- Substitution by plant-based alternatives:Oat and coconut yogurt formulations are capturing label-conscious consumers seeking dairy-free probiotic options.
Strategic Opportunities
- Pediatric fortification:India's FSSAI micronutrient guidelines create a compliant pathway for iron and vitamin D enriched toddler formats.
- Tube packaging innovation:Single-serve squeezable formats are penetrating school lunchbox occasions previously dominated by cup SKUs.
- PLI scheme alignment:India's production-linked incentive framework for food processing offers capital subsidy offsets for cold-chain infrastructure buildout.
Industry Challenges
- Live culture viability maintenance:Temperature excursion tolerance in last-mile distribution remains a technical bottleneck for probiotic claim integrity.
- Multi-jurisdiction label compliance:Divergent sugar disclosure rules between FDA nutrition panels and EU front-of-pack traffic light systems inflate packaging complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Yogurt Market |
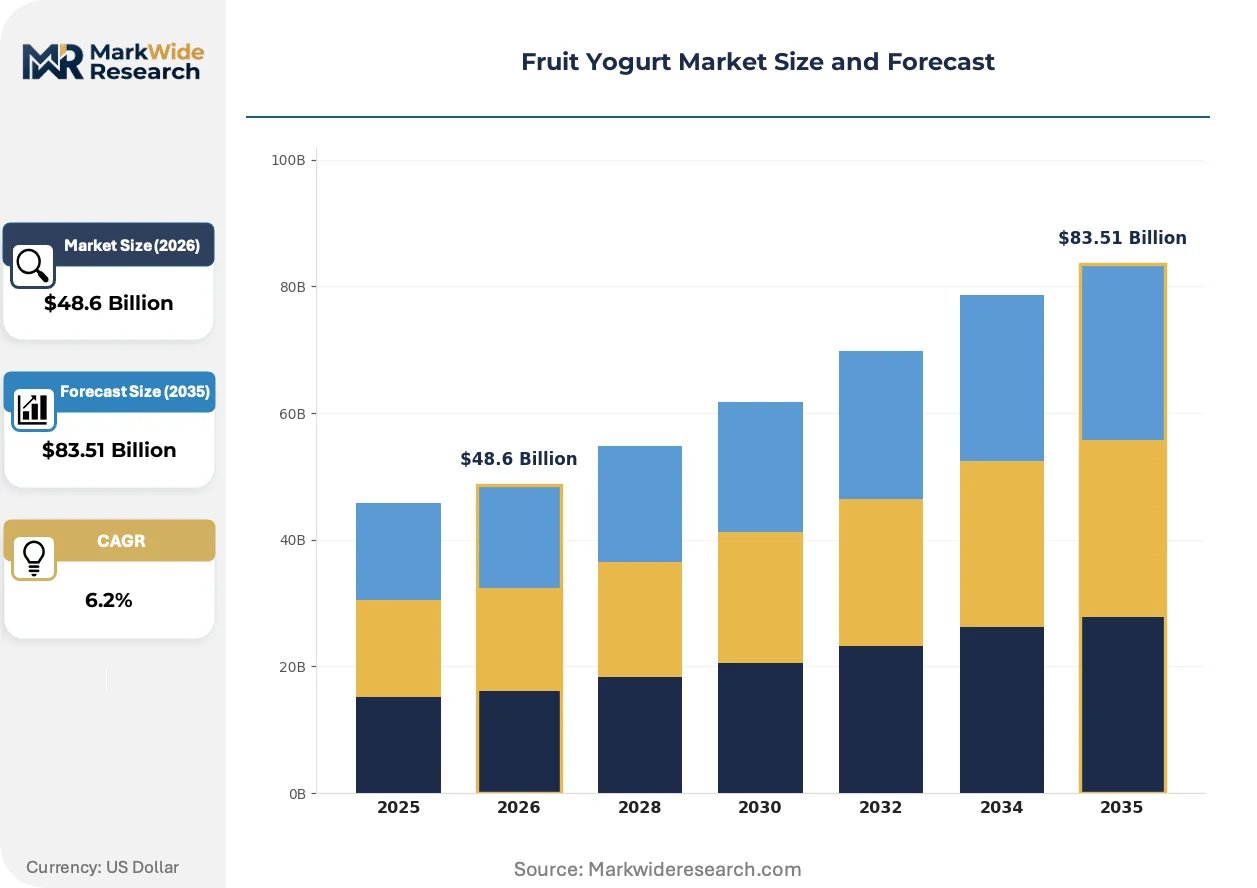
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $83.51 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strawberry Yogurt, Blueberry Yogurt, Mango Yogurt, Peach Yogurt, Cherry Yogurt Packaging Type: Cup, Bottle, Tube, Multi-Pack, Sachet Consumer Age Group: Children, Teenagers, Adults, Seniors, Toddlers Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores, Pharmacies |
| Companies Covered | Danone, General Mills, Chobani Global Holdings, Nestlé, Fage International, Arla Foods, Britannia Industries, FrieslandCampina, Lactalis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Yogurt Market Shifts & Advancements
Formulation science and packaging engineering are converging to extend shelf stability without compromising live culture counts. Manufacturers are rebalancing capital allocation between processing automation and cold-chain redundancy.
Aseptic fruit preparation technology is converging with high-pressure processing to eliminate thermal degradation of volatile flavor compounds. Premium private-label buyers in German and French retail are adopting these systems to compress the quality gap with branded equivalents. This convergence is enabling shorter ingredient lists while maintaining the 28-day refrigerated shelf life that mass retail requires.
The EU Green Deal's Farm to Fork strategy is mandating 25% pesticide reduction targets that cascade into fruit supply contracts. Dairy processors are restructuring procurement relationships toward integrated grower partnerships to secure residue-compliant berry and tropical fruit volumes. Greek-style and skyr formats face the steepest reformulation pressure given their reliance on concentrated fruit preparations.
Household purchasing is fragmenting across channel types as convenience stores and quick-commerce platforms capture impulse yogurt occasions previously consolidated in weekly supermarket trips. Quick-commerce dark stores in São Paulo, Mexico City, and Jakarta are optimizing for 15-minute delivery windows that demand ultra-localized cold storage nodes. This rotation is compressing the relevance of traditional retail-facing multi-pack promotions in urban core markets.
Fruit Yogurt Market Segmentation
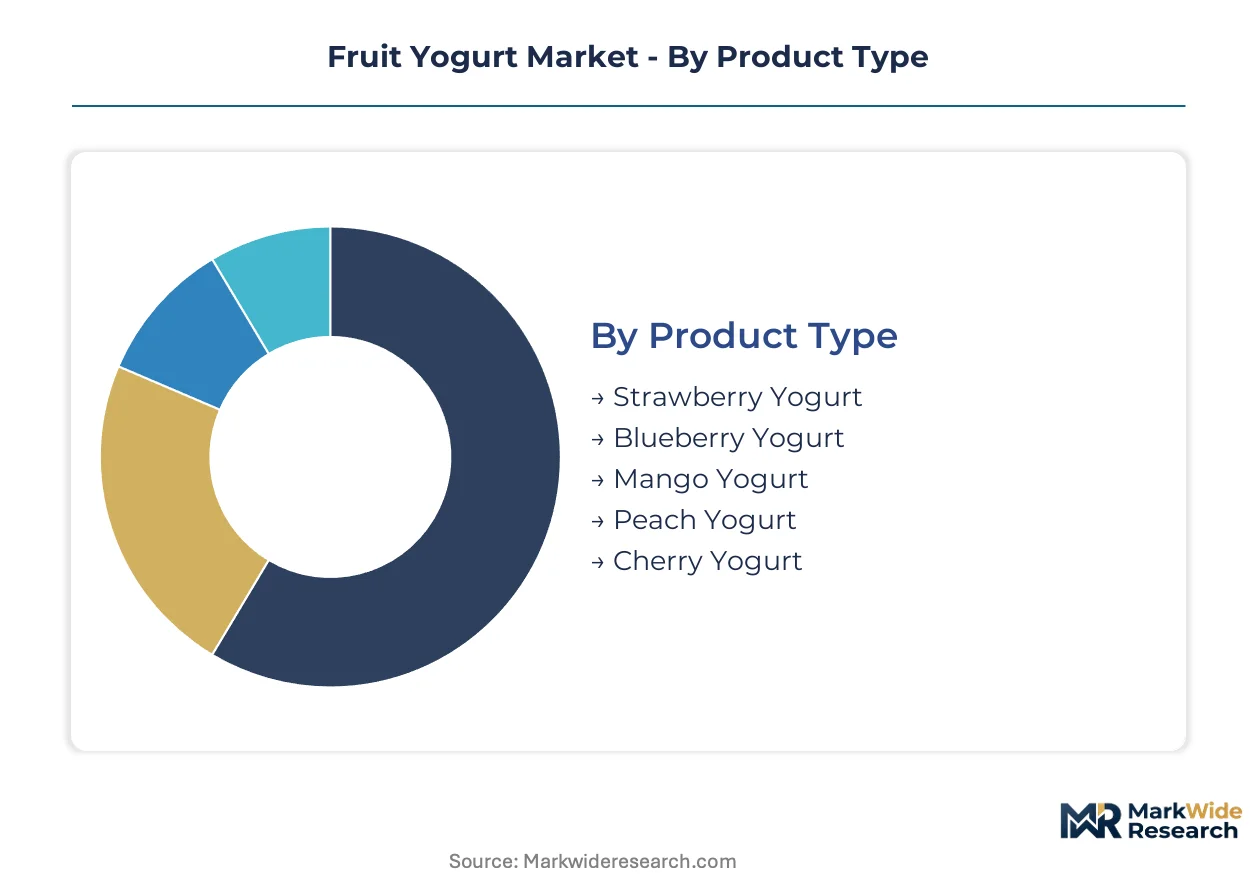
Fruit yogurt segmentation reveals how formulation, packaging, and channel choices align with distinct consumption moments and household purchasing rhythms. Manufacturers calibrate product architecture across these dimensions to capture refrigerated shelf space and repeat purchase loyalty.
Product Type:
Flavor preferences stratify sharply between mature Western markets and tropical growth corridors, with texture and sweetness intensity driving reformulation priorities.
- Strawberry Yogurt:The foundational SKU carries the highest household penetration in North American and European retail, where its mild acidity profile accommodates reduced-sugar reformulations without alienating core buyers. Demand concentrates in multi-pack formats for weekly stock-up trips, though margin pressure intensifies as private-label alternatives narrow the quality perception gap.
- Mango Yogurt:Alphonso and Kesar pulp varieties command premium positioning in Indian urban centers and diaspora communities across the Gulf states and United Kingdom. The segment climbs fastest as refrigerated logistics modernization unlocks chilled distribution in Mumbai, Delhi, and Bangalore previously constrained by spoilage windows.
- Blueberry Yogurt:Antioxidant-linked health claims sustain its premium tier placement in German and French retail, with procurement increasingly tied to EU Green Deal pesticide reduction mandates.
- Peach Yogurt:Southern European markets favor its lower acidity profile, with Italian and Spanish processors leading formulation adaptation for regional palate preferences.
- Cherry Yogurt:Seasonal limited editions dominate its commercial footprint, with Black Forest regional variants sustaining niche premium positioning in German-speaking markets.
Volume sits with strawberry formulations; growth tilts toward mango varieties as tropical supply chains mature.
Packaging Type:
Format selection directly governs consumption occasion access, with single-serve portability commanding R&D investment ahead of household bulk formats.
- Cup:The dominant retail-facing format maintains its position through established filling line infrastructure and clear visibility of fruit preparation layers, though its rigidity limits on-the-go consumption capture. European retailers continue prioritizing cup SKUs for planogram consistency, while Indian modern trade accelerates adoption as cold-chain reliability improves.
- Tube:Squeezable formats penetrate school lunchbox and snacking occasions previously inaccessible to rigid packaging, with French and Japanese manufacturers leading barrier-film innovation to preserve live culture viability through distribution temperature excursions.
- Bottle:Drinkable yogurt variants target teenage and young adult consumption, with Brazilian and Mexican processors expanding PET line capacity for convenience store channel placement.
- Multi-Pack:Bundled pricing sustains household pantry loading behavior in US and UK supermarket channels, though quick-commerce fragmentation erodes its historical dominance in urban core markets.
- Sachet:Powdered and concentrated formats serve price-sensitive rural penetration in Southeast Asian markets where refrigerated last-mile distribution remains economically unviable.
Manufacturing scale concentrates in cup production; format innovation accelerates fastest in tube configurations.
Consumer Age Group:
Nutritional positioning and fortification requirements diverge sharply across life stages, with regulatory compliance thresholds fragmenting formulation strategies.
- Toddlers:Iron and vitamin D enrichment under India's FSSAI guidelines creates a compliant product pathway distinct from standard formulations, with Nestlé and Danone anchoring portfolio development in pediatric dairy expertise.
- Children:Reduced-sugar claims and character licensing drive parental purchase approval, with tube formats capturing lunchbox occasion share from traditional cup offerings.
- Teenagers:Higher protein Greek-style and skyr variants align with sports nutrition positioning, with Chobani's fruit blend portfolio targeting this transition demographic.
- Adults:The broadest addressable market supports clean-label and probiotic claim differentiation, with EU front-of-pack traffic light labeling forcing sugar disclosure transparency.
- Seniors:Digestive health and bone density claims concentrate demand in Japanese and European markets with aging demographic profiles.
Adult segments generate baseline volume; toddler fortification represents the steepest expansion trajectory as regulatory frameworks formalize.
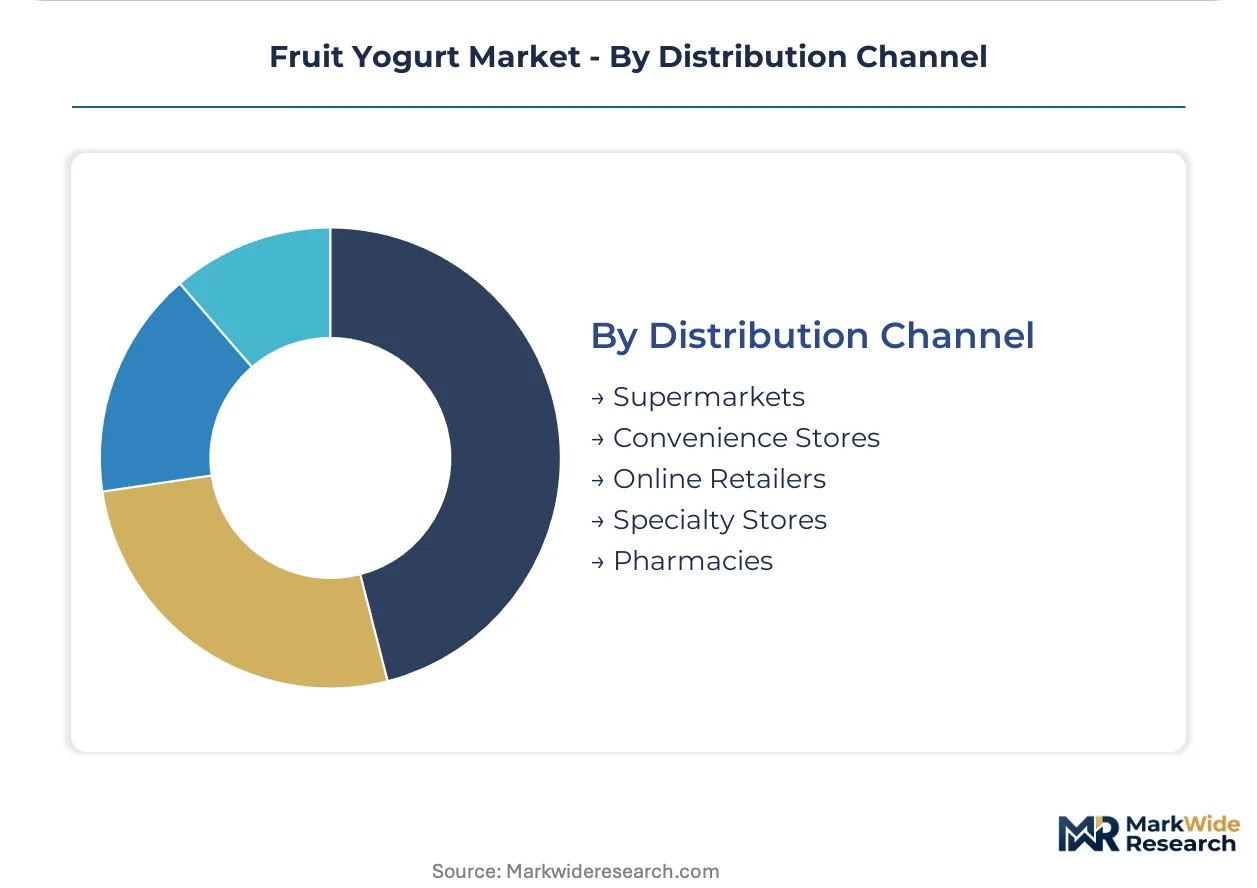
Distribution Channel:
Channel mix determines promotional mechanics and cold-chain investment intensity, with convenience and quick-commerce formats demanding localized inventory positioning.
- Supermarkets:Weekly stock-up behavior sustains multi-pack velocity and promotional calendar dependency, though foot traffic erosion in urban cores compresses relevance.
- Convenience Stores:Impulse-oriented single-serve placement captures immediate consumption demand in Japanese and South Korean urban networks.
- Online Retailers:Subscription models and chilled dark-store networks expand in São Paulo, Mexico City, and Jakarta, optimizing for 15-minute delivery windows.
- Specialty Stores:Organic and artisanal positioning commands premium pricing in French and Italian retail, with shorter supply chains justifying higher unit economics.
- Pharmacies:Probiotic and digestive health claims enable placement alongside wellness categories in German and Swiss markets, with live culture count specifications exceeding standard retail thresholds.
Supermarket channels anchor current volume; quick-commerce infrastructure expands most rapidly in emerging market urban centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in dairy-rich hinterlands while consumption tilts toward urban corridors with reliable cold-chain infrastructure. Refrigerated logistics gaps once excluded mass-market penetration in emerging economies. Regulatory divergence on fortification and sugar disclosure fragments export strategies.
United States
Health-conscious millennials drive multi-pack adoption in suburban weekly stock-up channels. FDA nutrition labeling requirements shape front-of-pack sugar disclosure transparency. Chobani Global Holdings anchors Greek-style production in upstate New York while Danone leverages its refrigerated network for retail shelf dominance.
Germany
Antioxidant-linked blueberry variants sustain premium tier placement in discounter and organic retail. EU F-Gas Regulation on refrigeration emissions accelerates natural refrigerant system investment across dairy processing facilities. Bavarian and North Rhine-Westphalia clusters host reformulation R&D responding to EU Green Deal pesticide reduction mandates.
India
Alphonso and Kesar mango pulp varieties command premium positioning in Mumbai, Delhi, and Bangalore urban centers. FSSAI fortification guidelines on iron and vitamin D create compliant pathways for toddler-oriented formulations. Maharashtra's refrigerated supply chain modernization unlocks household penetration previously blocked by spoilage risk.
China
GB standards on dairy imports establish divergent compliance thresholds that redirect capital toward localized production. Urban middle-class demand concentrates in tier-one cities with expanding cold-chain coverage. Yangtze River Delta processors adapt formulations for reduced-sugar preferences while navigating SAMR labeling requirements.
Brazil
Drinkable yogurt variants in PET bottles target teenage convenience store consumption in São Paulo and Rio de Janeiro. Quick-commerce dark stores optimize for 15-minute delivery windows that demand ultra-localized cold storage nodes. ANVISA dairy regulations shape probiotic claim substantiation requirements for cross-border suppliers.
Fruit Yogurt Market Competitive Landscape
The competitive structure tilts toward multinational dairy conglomerates with captive refrigerated logistics networks. Tiered positioning separates premium Greek-style specialists from mass-market cup-format providers. Three archetypes dominate: diversified nutrition giants with pediatric dairy expertise, regional cooperatives with backward integration into milk supply, and private-label enablers with aseptic processing technology. M&A activity concentrates on cold-chain infrastructure acquisitions and tropical fruit pulp supply consolidation.
Among diversified nutrition conglomerates, Danone, Nestlé, and Chobani Global Holdings exemplify distinct strategic positioning. Danone occupies a position anchored in European refrigerated logistics scale. Nestlé represents pediatric-oriented formulation expertise extending dairy heritage into fortified toddler segments. Chobani Global Holdings exemplifies premium Greek-style positioning with higher-protein fruit blend architecture. These three anchors illustrate how multinational scale, regional specialization, and format innovation define competitive differentiation in fruit yogurt.
| Leading Market Players |
|---|
| Danone |
| General Mills |
| Chobani Global Holdings |
| Nestlé |
| Fage International |
| Arla Foods |
| Britannia Industries |
| FrieslandCampina |
| Lactalis |
| Others |
Supply & Pricing Matrix
Family-owned dairy cooperatives in Bavaria and Normandy anchor mid-tier production, their patient capital enabling long-term fruit supply contracts that insulate pricing from spot-market volatility. Their ownership structure permits below-market pricing during commodity downturns, compressing returns for private-equity-rolled-up competitors dependent on quarterly leverage coverage.
Pricing Analysis
Margin tightening in standard cup formats reflects private-label quality convergence and retailer direct-sourcing programs. Three-tier pricing structure across premium Greek-style, standard fruit-blend, and economy private-label levels segments buyer willingness-to-pay by protein claim intensity and fruit preparation visibility. Cost-down pressure on multi-pack bundles accelerates because quick-commerce fragmentation erodes weekly stock-up velocity. Price sensitivity concentrates in suburban household purchasers, while urban convenience seekers absorb single-serve premiums.
Supply Chain Analysis
Regional distribution centers in Mumbai, São Paulo, and Mexico City govern hub-and-spoke patterns that compress last-mile spoilage windows. Raw material sourcing draws from Maharashtra mango pulp processors, North Rhine-Westphalia dairy cooperatives, and Yangtze River Delta stabilizer manufacturers. Single-origin fruit concentrate vulnerability from Alphonso supply concentration creates input disruption exposure during monsoon variability. Distribution runs through refrigerated dark-store networks in emerging market urban cores alongside traditional retail-facing multi-pack channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fruit yogurt competitive dynamics favor consolidation plays as cold-chain infrastructure investment requirements exceed mid-cap balance sheet capacity. EU F-Gas Regulation compliance costs and refrigerated logistics modernization in India are forcing weaker capitalized processors toward acquisition or exit.
For Market Incumbents: Anticipate plant-based substitution pressure by securing exclusive berry supply partnerships under EU Green Deal pesticide reduction mandates. Anchor defensive positioning through backward integration into Alphonso pulp processing in Maharashtra, locking input cost predictability. Prioritize tube format R&D investment to capture school lunchbox occasions from rigid cup alternatives. For New Entrants and Emerging Players: India's PLI scheme for food processing opens a window for cold-chain infrastructure subsidy capture in Bangalore and Delhi urban corridors. Target toddler fortification segments under FSSAI iron and vitamin D guidelines where incumbent pediatric portfolios retain pricing power. Pursue direct-to-quick-commerce distribution partnerships bypassing traditional retail slotting fee barriers. For Investors and Strategic Acquirers: Maharashtra refrigerated logistics modernization announcements are the leading indicator that Indian market penetration inflection is materializing. Five-to-ten year viability rests on captive cold-chain ownership rather than third-party distribution dependence. Monitor FSSAI fortification guideline enforcement intensity as signal for pediatric segment margin expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Fruit Preparation Technology Adoption | Eliminates thermal degradation, enabling clean-label reformulation for EU added-sugar taxation compliance. |
| Tube Packaging Format Expansion | Captures school lunchbox occasions previously inaccessible to rigid cup configurations in French and Japanese markets. |
| Backward Integration into Mango Pulp Processing | Secures Alphonso supply concentration against monsoon-driven input volatility for Indian urban distribution. |
| Quick-Commerce Dark-Store Network Partnership | Optimizes 15-minute delivery windows in São Paulo and Jakarta, displacing traditional retail multi-pack velocity. |
| Pediatric Fortification Compliance Investment | Aligns with FSSAI iron and vitamin D guidelines, creating differentiated positioning in Indian toddler segments. |
Research Methodology
Trade databases, EU regulatory filings, and Nielsen retail audit data formed the secondary backbone, cross-referenced against primary interviews with dairy processing plant managers, refrigerated logistics operators, and modern trade category buyers. Bottom-up and top-down triangulation validated volume estimates across flavor, packaging, and channel segmentation dimensions.
Bottom-up modeling anchored projections in individual facility capacity and regional cold-chain penetration rates, while top-down constraints drew from aggregate dairy consumption trends and probiotic category growth patterns. Modeled dimensions span flavor type, packaging format, consumer age group, and distribution channel across the analysis window. CAGRs were derived from normalized growth trajectory fitting against historical refrigerated logistics expansion curves and urban household penetration benchmarks.
The model assumes a particular technology adoption path; alternative pathways for aseptic fruit preparation and high-pressure processing would alter the outlook if cost curves shift faster than projected. Forecasts reflect documented assumptions on cold-chain infrastructure buildout timing and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Japan Dairy Market
Dairy Products
Germany Milk Protein Market
Dairy Products
North America Whole Milk Powder Market
Dairy Products
Savory Dairy Products Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Probiotic Yogurt Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
Cream Market
Dairy Products
UHT Milk Market
Dairy Products
Ghee Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Europe Cheese Market
Dairy Products
Dairy Foods Market