
 Low Calorie RTD Beverages Market | 2026-2036
Low Calorie RTD Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie RTD Beverages Market Intelligence
The fortification of beverages with functional ingredients like probiotics and adaptogens is rotating the market toward higher-value product categories. The Coca-Cola Company leverages its extensive distribution network to introduce low-sugar variants of its core brands. PepsiCo Inc. competes through innovation in the functional water and enhanced tea segments. Nestlé S.A. specializes in ready-to-drink coffee and plant-based beverages with reduced sugar content.
Low calorie ready-to-drink (RTD) beverages are commercially prepared drinks, packaged for immediate consumption, that contain minimal or zero sugar and are often formulated with non-nutritive sweeteners. Their primary commercial purpose is to offer consumers convenient hydration and refreshment options that align with health-conscious dietary goals, avoiding the high sugar content of traditional soft drinks. Low-calorie tea and coffee products command a significant share, while sports drinks infused with electrolytes represent the fastest-growing product type. Sales are dominated by supermarkets and convenience stores, though the online retail channel is expanding rapidly due to direct-to-consumer models.
Regulations from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate clear nutritional labeling, including calorie and sugar content. In parallel, sugar taxes implemented in nations like Mexico and the United Kingdom directly influence formulation strategies and consumer purchasing behavior. Future success for manufacturers depends on navigating evolving sweetener safety regulations and adapting to shifting consumer preferences for natural ingredients.
Market Dynamics
The central dynamic shaping the low calorie RTD beverage market is the increasing consumer expectation for products that deliver both health benefits and sensory satisfaction. This pressure forces innovation in natural sweetener formulation and functional ingredient integration to overcome historical taste and texture trade-offs.
Growth Catalysts
- Sugar Taxation Policies:Government-led sugar taxes, such as those implemented in the United Kingdom and Mexico, create a direct financial incentive for manufacturers to reformulate legacy high-sugar beverages and prioritize the development of low-calorie alternatives.
- Demand for Functionality:Health-conscious millennial and Gen Z consumers are seeking beverages with added functional benefits, such as probiotics for gut health or adaptogens for stress relief, driving growth in higher-value product segments.
- Sweetener Technology Advancement:Innovations in the blending and formulation of natural, non-nutritive sweeteners like stevia and monk fruit extract are improving taste profiles, reducing off-notes, and enabling broader product development without sugar.
Market Restraints
- Natural Ingredient Price Volatility:The cost and availability of key natural ingredients, particularly monk fruit and certain adaptogens sourced from specific regions, are subject to significant fluctuation, impacting production costs and margin stability.
- Sensory Profile Challenges:Achieving a sugar-like taste and mouthfeel with zero-calorie sweeteners remains a significant technical hurdle, with lingering consumer perceptions of off-tastes hindering adoption for some product types.
- Complex Health Claim Regulations:Navigating the stringent and divergent regulations for health and nutrient content claims set by bodies like the FDA in the US and EFSA in Europe can create costly delays in product launches.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity for expansion into markets across Southeast Asia and Latin America, where rising disposable incomes and nascent wellness trends create new demand for convenient, healthy beverage options.
- Niche Functional Formulations:Developing targeted beverages for specific use-cases, such as cognitive enhancers for the e-sports community or sleep-support drinks, allows brands to capture value in specialized, high-margin segments.
- Direct-to-Consumer Channels:Leveraging online retail and subscription models enables brands to bypass traditional retail gatekeepers, build direct customer relationships, and gather valuable data on consumer preferences to accelerate innovation cycles.
Industry Challenges
- Global Supply Chain Consistency:Ensuring a consistent and high-quality supply of sensitive functional ingredients like live probiotics and botanicals across a global manufacturing footprint presents a significant logistical and quality control challenge.
- Fragmented Labeling Requirements:Manufacturers face the operational complexity of complying with a patchwork of national and regional front-of-pack nutritional labeling schemes, requiring different packaging and formulations for various markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie RTD Beverages Market |
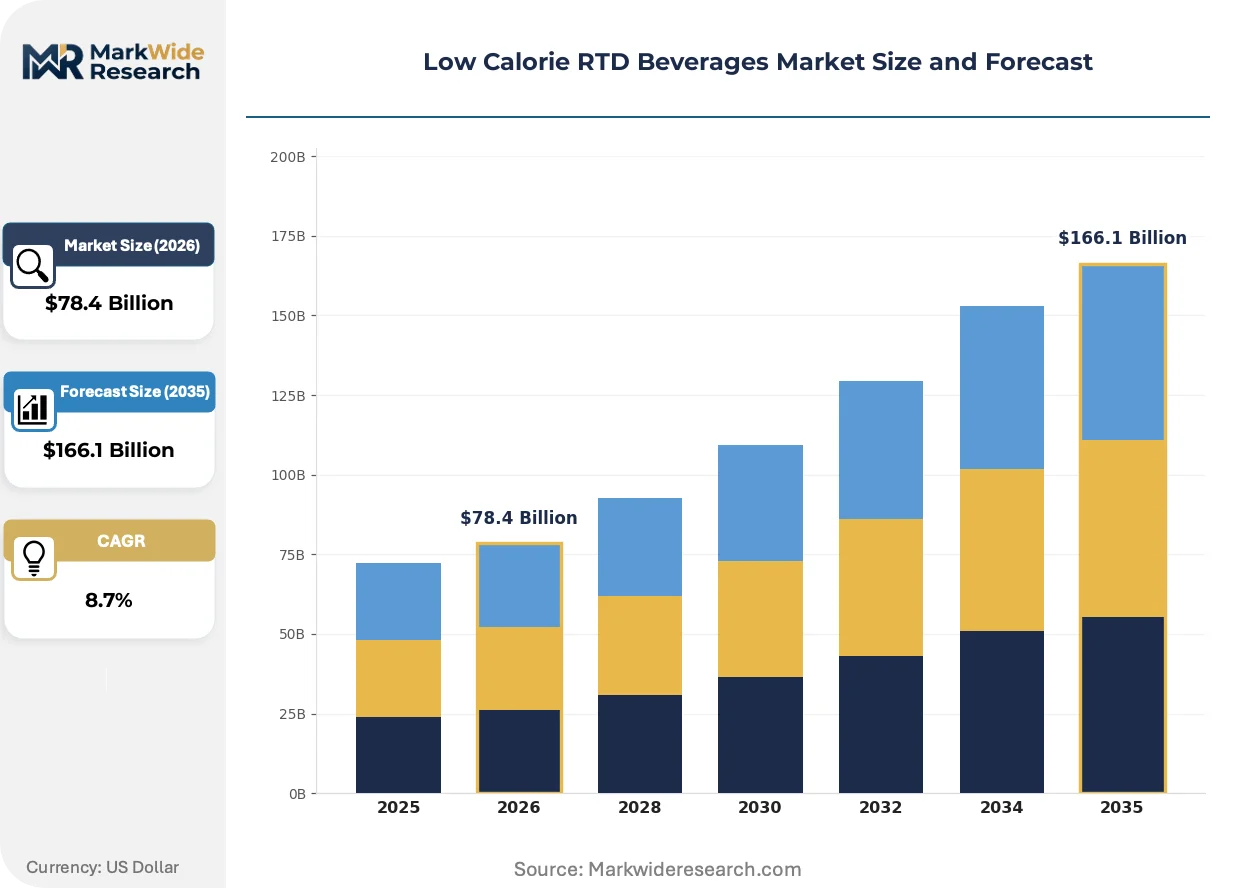
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $166.1 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea, Coffee, Juice, Sports Drink Sales Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Packaging Type: Bottles, Cans, Tetra Packs, Pouches Flavor Profile: Fruit Blend, Herbal, Chocolate, Vanilla |
| Companies Covered | The Coca-Cola Company, PepsiCo Inc., Nestlé S.A., Danone S.A., Red Bull GmbH, Monster Beverage Corporation, Keurig Dr Pepper Inc., Asahi Breweries Ltd., Unilever N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie RTD Beverages Market Strategic Shifts & Innovations
Product development is pivoting from a singular focus on calorie reduction toward a holistic approach that integrates functional wellness. This evolution is driven by advances in ingredient science that enable sophisticated formulations which meet complex consumer demands for health, taste, and clean labels.
Advanced sweetener systems that blend multiple natural sources like stevia, monk fruit, and allulose provide a more authentic sugar-like taste profile. Beverage formulators across segments are rapidly adopting these systems to appeal to mainstream consumers. This technology is displacing first-generation, single-ingredient natural sweeteners that were often criticized for prominent bitter or licorice-like aftertastes, thereby expanding the addressable market.
Regulatory frameworks from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) are tightening the requirements for making specific health claims on beverage labels. This forces manufacturers to invest in scientific substantiation for any functional benefits advertised, such as improved focus or gut health. The enhanced water and functional tea segments are most affected, now allocating greater resources to clinical studies to validate marketing claims.
A notable shift in consumer behavior involves a move from impulse, single-unit purchases toward planned, recurring buys via online channels. This pattern disrupts the long-held dominance of supermarkets and convenience stores as the primary points of sale for RTD beverages. The trend is most visible in major metropolitan areas of the United States and Germany, where direct-to-consumer subscription models are gaining significant market share.
Low Calorie RTD Beverages Market Segmentation
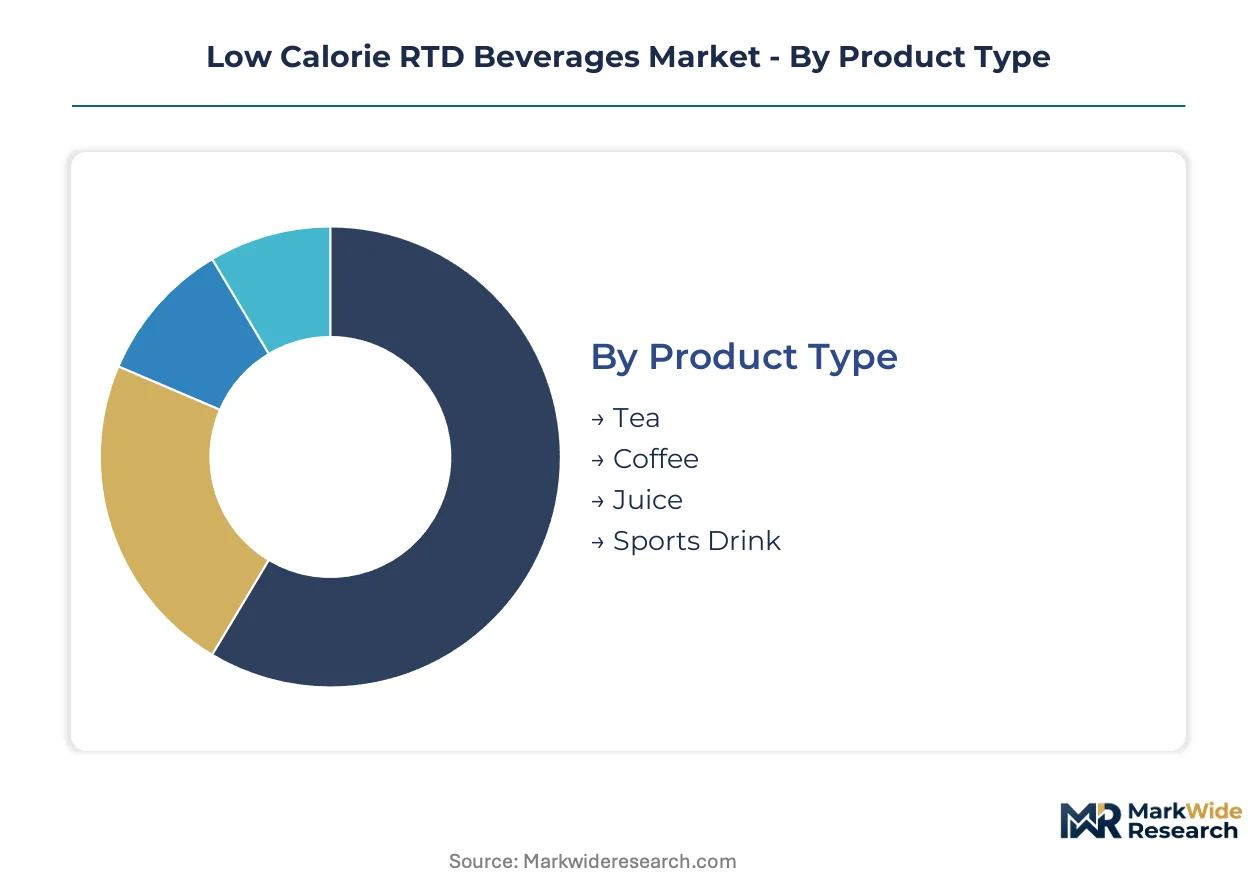
Segmentation analysis provides a granular understanding of the Low Calorie RTD Beverages Market, revealing distinct consumer preferences and commercial pathways. This detailed breakdown helps manufacturers tailor product development, optimize distribution strategies, and identify high-potential growth areas within the diverse beverage landscape.
Product Type:
The low-calorie RTD beverage market faces significant substitution pressure from traditional, sugar-laden counterparts, driving innovation in healthier alternatives across various product categories.
- Sports Drink:These beverages are formulated with electrolytes and minimal or no sugar, targeting active consumers for hydration and recovery. Demand concentrates among fitness-conscious demographics in major metropolitan areas, where wellness trends are prominent.
- Tea:Low-calorie tea products offer natural ingredients and often incorporate functional benefits like antioxidants, appealing to health-conscious consumers. Demand for these beverages is strong in regions with established tea cultures and a growing interest in natural wellness.
- Coffee:Reduced-sugar coffee options provide convenience and a caffeine boost without excessive calories.
- Juice:Low-calorie juice variants offer fruit flavor profiles with non-nutritive sweeteners, catering to consumers seeking healthier refreshment.
Tea retains volume leadership; Sports Drink holds the steepest expansion curve.
Sales Channel:
Volume concentration across sales channels defines access to the low-calorie RTD consumer base, dictating reach and purchasing convenience.
- Supermarkets:These large retail formats provide broad product assortments and competitive pricing, serving as the primary purchase point for most consumers. Demand is driven by routine grocery shopping and bulk purchases across diverse demographics.
- Online Retail:This channel facilitates direct-to-consumer models and subscription services, offering convenience and personalized shopping experiences. Demand is rapidly expanding among tech-savvy consumers in urban centers like the United States and Germany.
- Convenience Stores:These outlets cater to impulse purchases and immediate consumption needs due to their widespread accessibility.
- Specialty Stores:Niche retailers focus on premium, organic, or specific functional beverage offerings, attracting discerning consumers.
Online retail is gaining share rapidly, while supermarkets maintain broad market penetration.
Packaging Type:
Packaging type directly influences product portability and shelf life, catering to diverse consumption occasions and consumer lifestyles.
- Bottles:Plastic and glass bottles offer resealability and portion control, making them ideal for on-the-go consumption and individual servings. Demand is high for single-serve formats in active and urban lifestyles.
- Cans:Aluminum cans provide excellent chilling efficiency and recyclability, often used for carbonated or sparkling low-calorie beverages. Demand for these sleek, single-serve containers is strong in social and casual settings.
- Tetra Packs:Aseptic Tetra Pak packaging ensures extended shelf life for sensitive products without refrigeration.
- Pouches:Flexible pouches offer lightweight and portable solutions, particularly for specific niche products or smaller serving sizes.
Bottles and cans dominate immediate consumption, with sustainable packaging innovations driving future shifts.
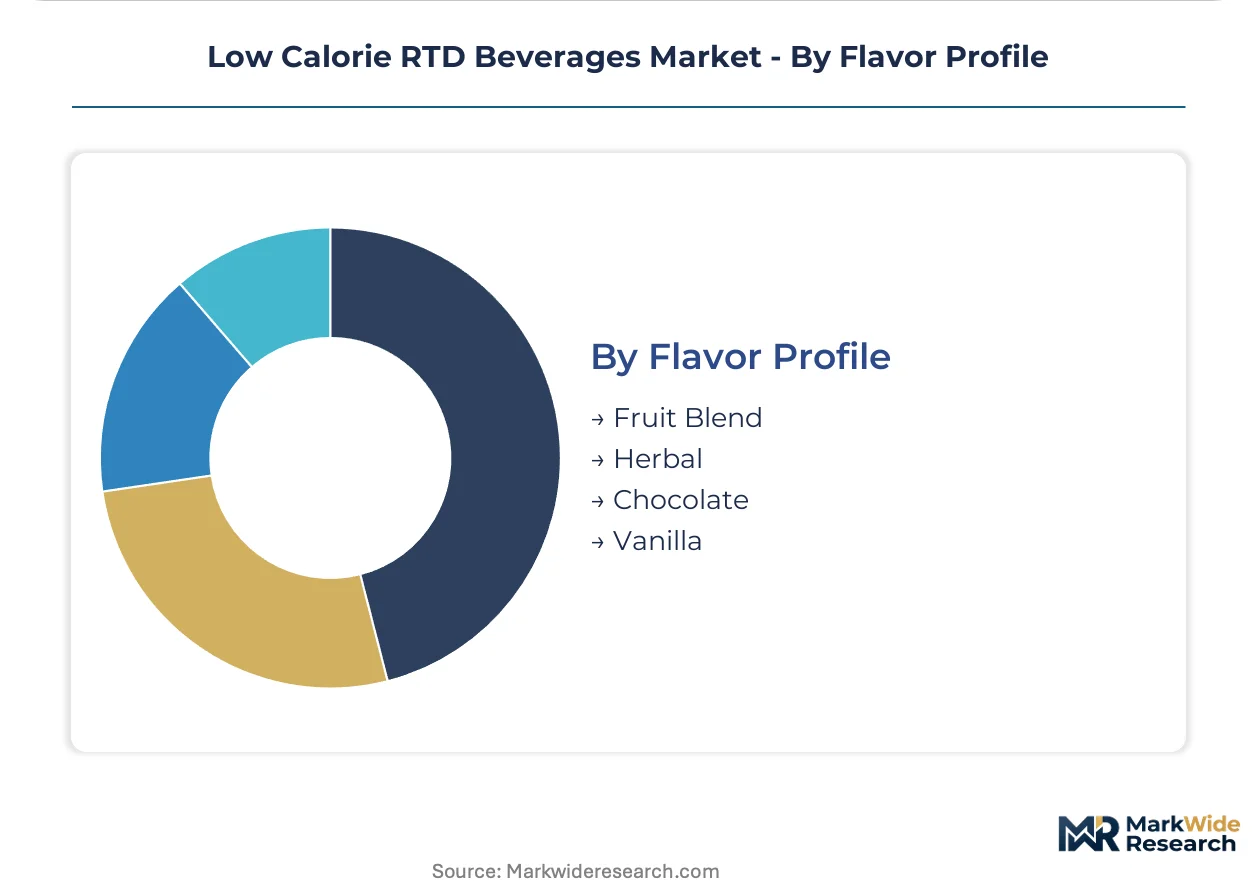
Flavor Profile:
Consumer preference for specific flavor profiles shapes product development and brand differentiation, influencing adoption and repeat purchases.
- Fruit Blend:These flavors combine various fruit essences, offering a broadly appealing and refreshing taste profile without high sugar content. Demand comes from consumers seeking familiar and palatable low-calorie options.
- Herbal:Beverages with herbal flavor profiles often incorporate botanicals and adaptogens, appealing to consumers seeking functional benefits and natural ingredients. Demand is rising among wellness-focused demographics exploring new taste experiences.
- Chocolate:Low-calorie chocolate-flavored beverages provide an indulgent option with reduced sugar, often in coffee or protein drinks.
- Vanilla:Classic vanilla flavors offer a comforting and versatile base for various low-calorie RTD formulations, including coffee and dairy-free options.
Fruit blend flavors retain widespread appeal, while herbal infusions are expanding most quickly due to wellness trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global low calorie RTD beverages market sees varied import-export dynamics, with established markets like the United States and Germany driving innovation, while emerging economies in Southeast Asia and Latin America represent significant consumption growth opportunities. This balance necessitates localized product development and distribution strategies for manufacturers.
United States
Demand for low-calorie RTD beverages in the United States stems from pervasive health and wellness trends, particularly among millennial and Gen Z consumers seeking functional benefits. The U.S. Food and Drug Administration (FDA) mandates clear nutritional labeling, influencing formulation transparency. Major metropolitan areas like New York City and Los Angeles serve as innovation hubs, where new functional beverage concepts are first tested and scaled.
Germany
German consumers exhibit strong demand for clean-label, naturally sweetened low-calorie drinks, aligning with a broader European preference for organic products. The European Food Safety Authority (EFSA) sets stringent standards for health claims and ingredient safety, shaping market entry. Munich and Berlin are key urban centers where wellness-focused startups and established beverage companies introduce new plant-based and reduced-sugar offerings.
United Kingdom
The United Kingdom's market for low-calorie RTD beverages is significantly influenced by the Soft Drinks Industry Levy, commonly known as the sugar tax, which incentivizes reformulation. Consumers prioritize convenience and a wide array of flavor options in their low-sugar choices. London remains a central hub for beverage innovation, with numerous brands focusing on functional teas and enhanced waters to meet evolving preferences.
Mexico
Mexico's low-calorie RTD market experiences robust growth due to government-imposed sugar taxes and increasing public health campaigns targeting obesity. This regulatory environment directly pushes manufacturers to offer reduced-sugar alternatives. Mexico City and Guadalajara are major consumption centers, where local and international brands compete to capture demand for healthier refreshment options.
China
China presents a rapidly expanding market for low-calorie RTD beverages, driven by rising disposable incomes and a growing awareness of health and dietary concerns among urban populations. Chinese regulators are increasingly scrutinizing food and beverage safety and labeling, impacting product development. Shanghai and Beijing lead in consumer adoption, with a strong preference for innovative fruit-flavored and functional low-sugar drinks.
Low Calorie RTD Beverages Market Key Industry Players
Listed leaders compete with private specialists across distribution scale and product innovation within the low calorie RTD beverages market. The market exhibits a tiered structure, with a few global conglomerates dominating volume alongside numerous niche players focusing on specific functional segments. Strategic partnerships and portfolio diversification represent dominant competitive moves, allowing companies to expand their reach and product offerings.
At the scale-driven end, The Coca-Cola Company, a global beverage corporation, leverages its extensive network to introduce low-sugar variants of its core brands. PepsiCo Inc., another multinational food and beverage giant, competes through innovation in the functional water and enhanced tea segments. Nestlé S.A., a Swiss multinational food and drink processing conglomerate, occupies a position specializing in ready-to-drink coffee and plant-based beverages with reduced sugar content.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| PepsiCo Inc. |
| Nestlé S.A. |
| Danone S.A. |
| Red Bull GmbH |
| Monster Beverage Corporation |
| Keurig Dr Pepper Inc. |
| Asahi Breweries Ltd. |
| Unilever N.V. |
| Others |
Cost & Logistics Intelligence
U.S. Food and Drug Administration (FDA) nutritional labeling mandates gate both ingredient qualification and price differentiation for low-calorie RTD beverages. This regulatory oversight influences sourcing decisions and consumer value perception across the market.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing for bulk ingredients, influencing the broader market. Price differentiation stems from the inclusion of premium natural sweeteners like monk fruit and certified organic functional ingredients. Pricing pressure intensifies due to the volatile cost of specialized botanicals. Consumers purchasing through online subscription models exhibit lower price sensitivity than those making impulse buys in convenience stores.
Supply Chain Analysis
Inventory strategies blend just-in-time for perishable functional ingredients and strategic stockpiling for volatile natural sweeteners. Geographic supply concentrates for monk fruit in China and for adaptogens in specific Southeast Asian regions, creating raw material dependencies on these specialized inputs. A key structural risk involves global supply chain consistency for sensitive live probiotics. Distribution runs through established supermarket networks and rapidly expanding direct-to-consumer online channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
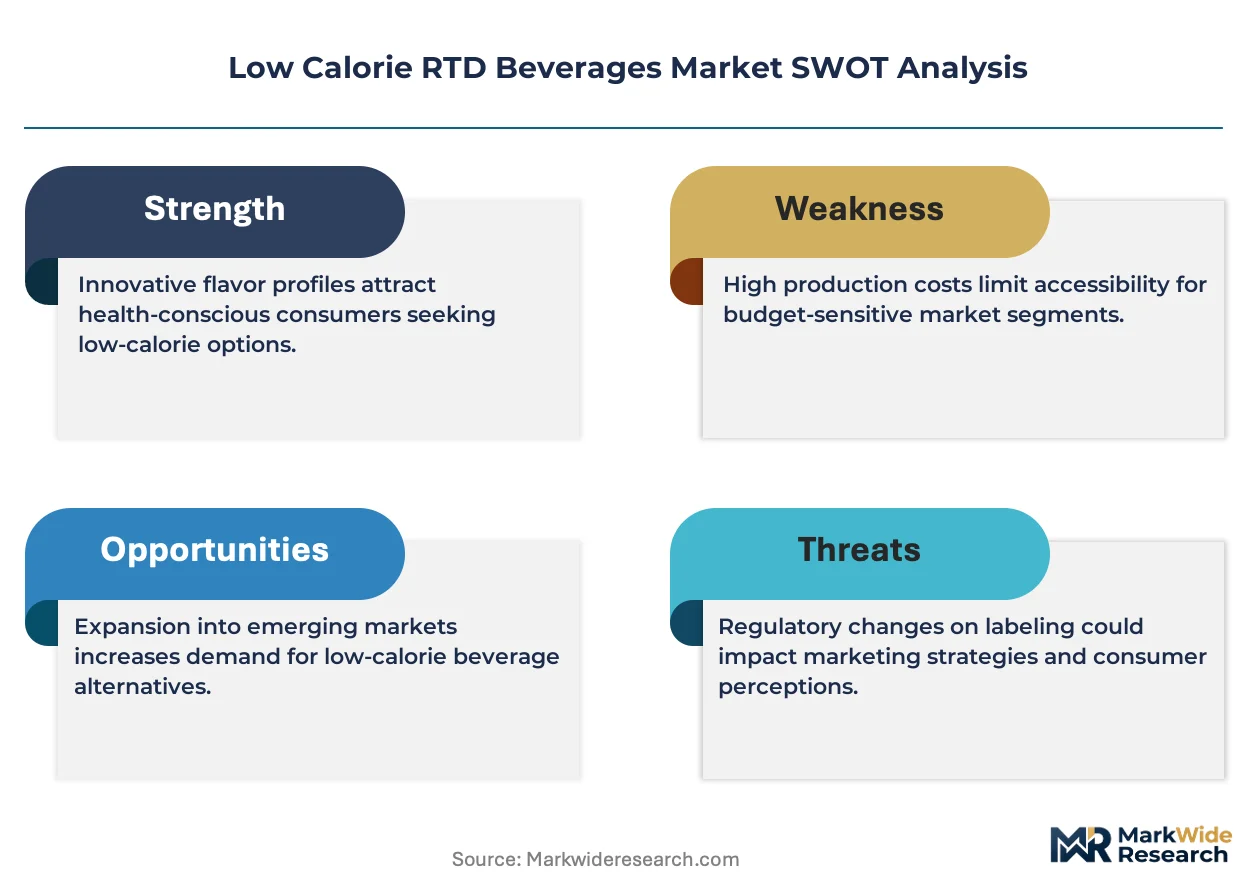
Advanced formulation science, particularly in natural sweetener blending, represents a critical capability scarcity in the low-calorie RTD beverages market. This specialized skill is essential for achieving sensory satisfaction without compromising health benefits.
For Market Incumbents:Secure proprietary natural sweetener blends through focused R&D investment to counter emerging niche brands. Diversify extensively into higher-value functional segments, leveraging global distribution networks to mitigate the threat of shifting consumer preferences for natural ingredients. Invest in advanced manufacturing capabilities for sensitive functional ingredients like probiotics.
For New Entrants and Emerging Players:Lack of personalized functional beverage options creates a fertile ground for new entrants. Target niche functional formulations such as cognitive enhancers for the e-sports community or sleep-support drinks. The urban, tech-savvy Gen Z demographic in major metropolitan areas represents the most penetrable segment. Direct-to-consumer subscription models offer an effective go-to-market angle.
For Investors and Strategic Acquirers:Stricter health claim regulations from the FDA and EFSA reshape the acquisition landscape, favoring scientifically validated brands. Long-term viability hinges on brands that can credibly substantiate functional benefits for a health-conscious consumer base. Acquisition targets should focus on specialized functional beverage brands with proprietary ingredient sourcing or advanced sweetener technology. The signal to watch is successful clinical validation of advertised health claims.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Sweetener R&D | Develops superior taste profiles without sugar, expanding the addressable market for low-calorie RTD beverages. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail gatekeepers and builds direct customer relationships, gathering valuable consumer data. |
| Functional Ingredient Sourcing Partnerships | Ensures consistent and high-quality supply of botanicals and probiotics, mitigating supply chain risks. |
| Clinical Validation of Health Claims | Provides scientific substantiation for functional benefits, meeting stringent regulatory requirements from the FDA and EFSA. |
| Niche Product Line Diversification | Captures value in specialized, high-margin segments like cognitive enhancers or sleep-support drinks for specific consumer groups. |
Research Approach
Two parallel data streams informed the analysis: primary stakeholder interviews and extensive secondary research. Interviews with beverage formulators, retail category managers, ingredient suppliers, and regulatory affairs specialists provided qualitative insights. Secondary validation drew from company annual reports, government health agency publications, and industry association reports. A robust bottom-up and top-down triangulation process ensured data accuracy.
The quantitative forecast model projects market dynamics across the analysis window. Segmentation dimensions included product type, sales channel, packaging type, flavor profile, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected consumer behavior shifts. Key industry-specific inputs included sweetener technology adoption rates and sugar tax implementation schedules.
Underlying assumptions cover persistent consumer wellness trends and stable regulatory frameworks, with deviation risk concentrated in unforeseen ingredient supply disruptions. Forecasts reflect these assumptions, though rapid shifts in sweetener safety perceptions present a significant risk. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Latin America Sports and Energy Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Commercial Sparkling Water Dispenser Market
Beverages
Electrolyte Mixes Market
Beverages
Japan Ready-To-Drink (RTD) Coffee Market
Beverages
Packaged Natural Mineral Water Market
Beverages
Cactus Water Market
Beverages
Global Beverage Emulsion Market
Beverages
Fruit Juices and Nectars Market
Beverages
Packaged Turmeric-Based Beverage Market
Beverages
Orange Juice Market
Beverages
Caffeinated Beverage Market
Beverages
United States Smoothie Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
Europe Yerba Mate Market
Beverages
Superfood Infused Beverages Market