
 Global Specialty Cheese Market | 2026-2036
Global Specialty Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Cheese Market Outlook
The gap between premium artisan wheels and mass-market blocks is restructuring how producers allocate aging capacity and milk sourcing contracts. Saputo Inc. leverages its North American plant network to control commodity cheddar volume. Lactalis Group anchors European distribution through Protected Designation of Origin holdings in France and Italy. Emmi Group specializes in Swiss-origin hard cheeses, competing on AOP-certified aging protocols.
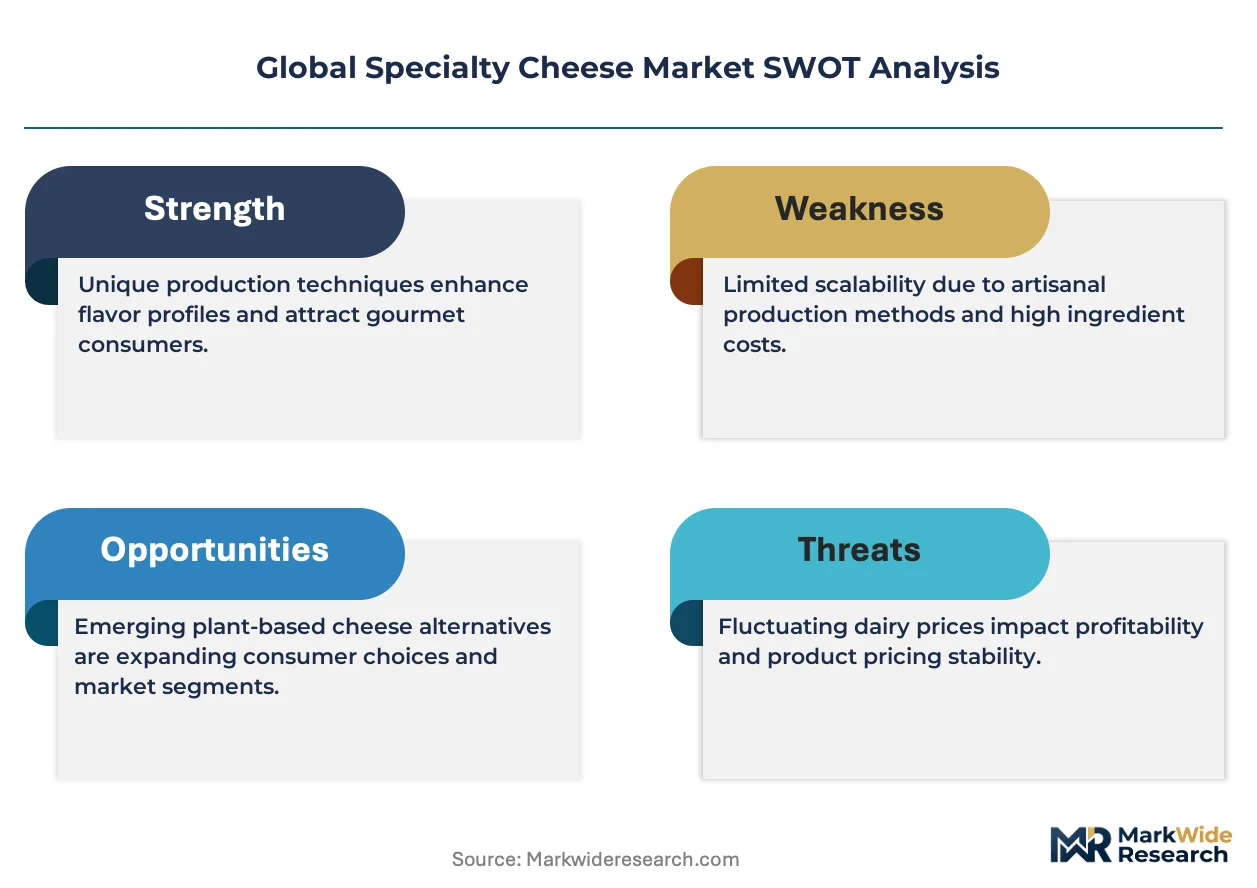
Specialty cheese denotes varieties distinguished by milk type, aging duration, geographic origin, or microbial culture composition, typically requiring controlled humidity between 85-95% and temperatures of 8-15°C during affinage. The primary commercial purpose centers on flavor differentiation commanding price premiums over standard processed cheese in retail and foodservice channels. Cow-milk cheddar occupies the largest volume pool globally, while goat-milk segments generate higher per-unit margins due to constrained supply and niche positioning. Foodservice distribution channels are expanding fastest as restaurant chains incorporate regional cheese boards and melting applications into standardized menus.
FDA dairy plant inspection requirements, EU hygiene package regulations, and CODEX Alimentarius microbiological criteria collectively shape raw-milk cheese legality, interstate commerce eligibility, and export market access. These frameworks force producers to maintain dual compliance tracks for domestic sale versus cross-border shipment. Stakeholders must monitor evolving pathogen threshold debates and digital traceability mandates that will determine which aging facilities retain operational licenses.
Market Dynamics
EU hygiene package revisions and CODEX Alimentarius microbiological criteria are compressing raw-milk cheese production capacity while simultaneously bifurcating the market between licensed artisan facilities and commodity processors unable to meet dual compliance tracks.
Growth Catalysts
- Foodservice channel expansion:Premium restaurant chains in the United States and France are incorporating regional cheese boards into standardized menus, creating pull-through demand for aged farmstead varieties with controlled humidity protocols.
- Protected Designation of Origin holdings:AOP-certified aging protocols in Switzerland and Italy command price premiums in retail channels, incentivizing producers to maintain traditional affinage methods despite higher compliance costs.
- Goat-milk supply constraints:Constrained herd sizes in France and Spain generate higher per-unit margins, attracting capital toward niche positioning and specialized microbial culture development.
Market Restraints
- Pathogen threshold volatility:FDA dairy plant inspection requirements and evolving Listeria monocytogenes standards create regulatory friction that blocks interstate commerce for small-batch raw-milk producers lacking HACCP infrastructure.
- Milk sourcing contract concentration:Saputo Inc. and Lactalis Group control commodity cheddar volume through captive North American and European dairy networks, limiting independent affineur access to consistent fluid milk supplies.
- Aging facility capex intensity:Climate-controlled affinage cellars requiring 85-95% humidity maintenance and 8-15°C temperature precision demand substantial capital outlay that excludes new market entrants.
Strategic Opportunities
- Digital traceability mandates:EU Green Deal farm-to-fork transparency requirements and ISO 22000 certification convergence create first-mover advantage for producers investing in blockchain-enabled batch tracking systems.
- Plant-based hybrid positioning:Precision fermentation technologies combined with traditional affinage expertise open white space in flexitarian retail segments seeking familiar texture profiles without animal-derived inputs.
- Direct-to-consumer channel innovation:Subscription-based cheese club models bypass conventional foodservice distribution markups, capturing margin in urban clusters across Germany, the Netherlands, and Japan.
Industry Challenges
- Affineur skill scarcity:Master cheesemaker apprenticeship programs in France and Switzerland face demographic collapse as aging practitioners retire without sufficient knowledge transfer to successor generations.
- Dual compliance timeline compression:Producers must simultaneously satisfy domestic FDA requirements and export-market EFSA microbiological criteria, stretching quality assurance teams across incompatible documentation frameworks.
- Legacy ERP integration friction:Small farmstead operations struggle to embed digital traceability modules into existing inventory management systems without disrupting seasonal production cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Cheese Market |
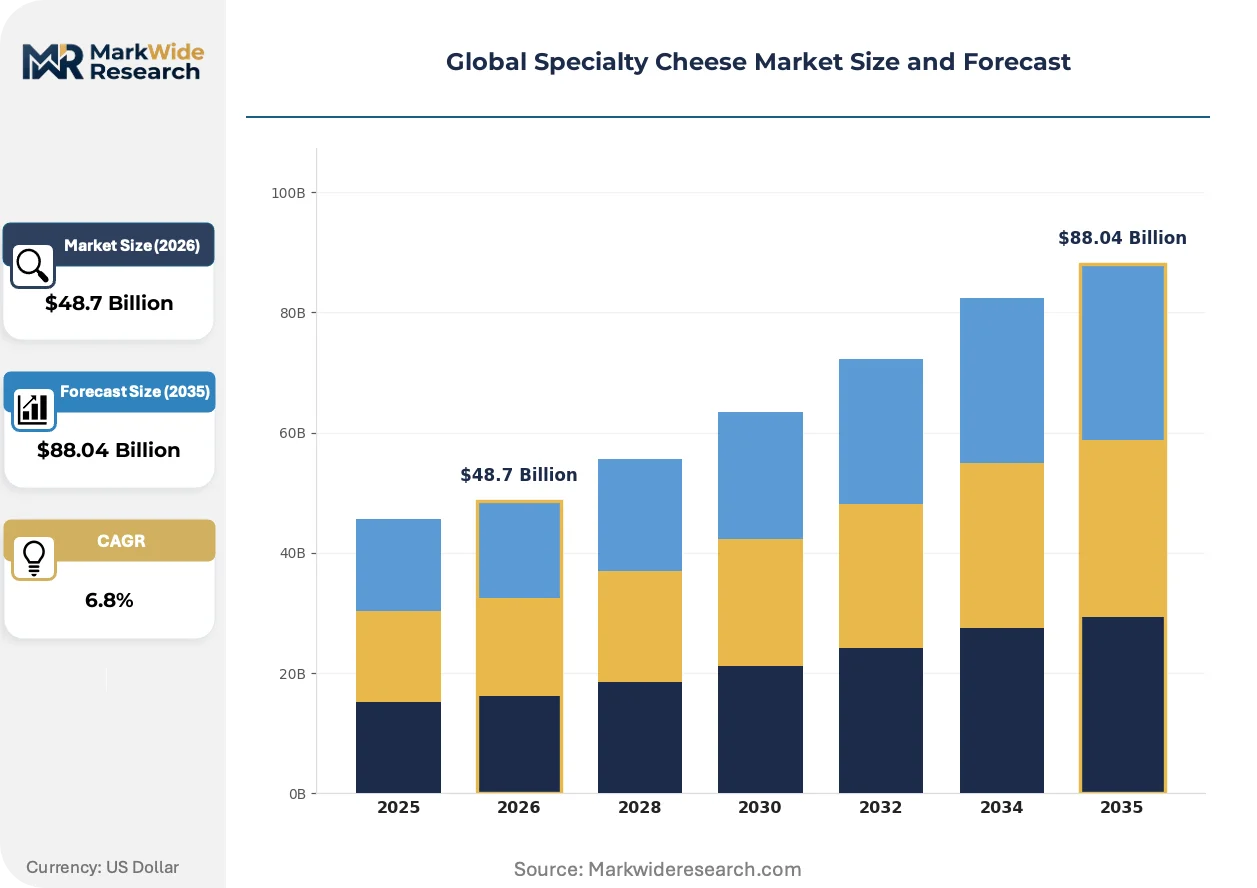
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Blue, Gouda, Brie Milk Source: Cow, Goat, Sheep, Buffalo Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Foodservice Flavor Profile: Spicy, Savory, Sweet, Nutty |
| Companies Covered | Saputo Inc., Kraft Heinz, Lactalis Group, Emmi Group, Savencia, Arla Foods, FrieslandCampina, Sargento Foods Inc., Fonterra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Cheese Market Strategic Shifts
Controlled-environment agriculture technologies and precision monitoring systems are penetrating traditional affinage operations, compressing the expertise gap between artisan methods and scalable production while regulatory transparency mandates force infrastructure reinvestment across the value chain.
Smart sensor arrays embedded within aging cellars now track real-time humidity, temperature, and microbial colony development. Foodservice distributors and premium retail buyers in France and Italy are adopting these systems to validate AOP-certified protocols. The technology is absorbing quality assurance functions previously performed by master affineurs, enabling volume producers to mimic artisan flavor profiles.
CODEX Alimentarius standards for raw-milk cheese are tightening microbiological criteria for Salmonella and Shiga toxin-producing E. coli. This regulatory shift forces producers to segregate domestic and export production lines or invest in pathogen intervention technologies. Small-scale farmstead operations in the United States face the steepest compliance burden, with many opting to abandon export licensing entirely.
Buyer concentration among consolidated foodservice distributors is compressing supplier margins and extending payment terms. Independent affineurs in Spain and Portugal are responding by forming cooperative direct-sales networks that bypass wholesale channels entirely. This disintermediation is most visible in urban gastronomy clusters where chef-owned restaurants prioritize provenance documentation over distributor convenience.
Global Specialty Cheese Market Segmentation
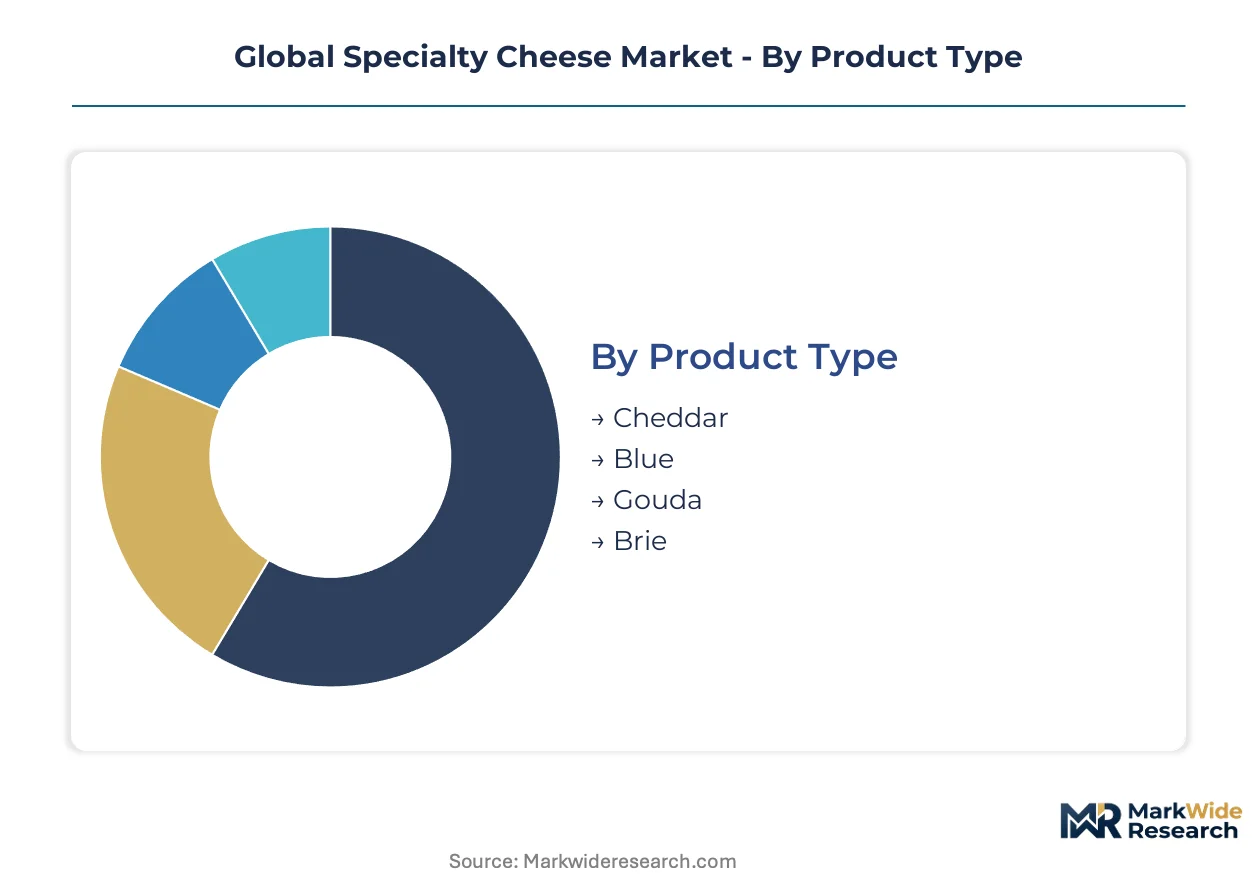
Specialty cheese producers configure aging protocols and microbial culture selection around distinct product specifications, milk chemistry variations, and channel-specific handling requirements. Segmentation clarity determines where capital flows for affinage infrastructure and which regulatory compliance tracks dominate investment priorities.
Product Type:
Affinage duration and humidity specifications differentiate cheese categories by protein structure breakdown rates and surface mold development requirements.
- Cheddar:Requires 6-24 months aging in controlled 12-15°C environments with 85-90% humidity to develop crystalline texture and sharp flavor compounds. Foodservice distributors in the United States absorb the largest volume for melting applications in chain restaurant standardized menus.
- Blue:Penicillium roqueforti inoculation demands piercing protocols and 90-95% humidity to enable internal veining. French and Italian affineurs command premium positioning through AOP-certified Roquefort and Gorgonzola production methods.
- Gouda:Dutch-origin washed-curd technique produces dense, sliceable wheels suitable for extended aging. Retail channels in Germany and the Netherlands favor younger varieties for everyday consumption.
- Brie:Surface-ripened soft cheese with 30-60 day affinage requiring precise Penicillium camemberti management. Direct-to-consumer subscription models in Japan target urban clusters seeking provenance documentation.
Mature deployment sits with Cheddar. Newer deployment is concentrated in Blue varieties.
Milk Source:
Protein composition and fat globule size drive curd formation behavior and final texture outcomes across animal species.
- Cow:Standardized casein ratios enable consistent industrial-scale production. Lactalis Group and Saputo Inc. control captive supply networks across France, Italy, and North America.
- Goat:Smaller fat molecules and distinct caprylic acid profile create tangy, crumbly textures. Constrained herd sizes in France and Spain generate higher per-unit margins and niche positioning premiums.
- Sheep:Higher solid content produces dense, buttery wheels with extended shelf stability. Greek and Spanish producers dominate Feta and Manchego AOP categories.
- Buffalo:Elevated butterfat concentration yields mozzarella di bufala with distinctive elasticity. Italian Campania region anchors traditional production with strict DOP territorial limits.
Volume concentration centers on Cow milk. Margin expansion is climbing the fastest in Goat milk segments.
Distribution Channel:
Cold chain integrity requirements and buyer concentration patterns shape channel economics and producer margin capture.
- Supermarkets:Consolidated retail buyers in France and the United States demand ISO 22000 certification and extended payment terms. Private label penetration compresses branded positioning opportunities.
- Online Retail:Temperature-controlled logistics enable direct producer-to-consumer relationships bypassing wholesale markups. German and Dutch urban clusters show strongest subscription adoption.
- Specialty Stores:Knowledgeable affineur staff and cut-to-order service justify price premiums for aged farmstead varieties. Independent retailers in Spain and Portugal form cooperative networks to bypass distributor concentration.
- Foodservice:Premium restaurant chains incorporate regional cheese boards and melting applications into standardized menus. This channel is expanding most quickly as procurement shifts toward provenance documentation.
Established infrastructure dominates Supermarkets. Emerging infrastructure investment concentrates in Online Retail.
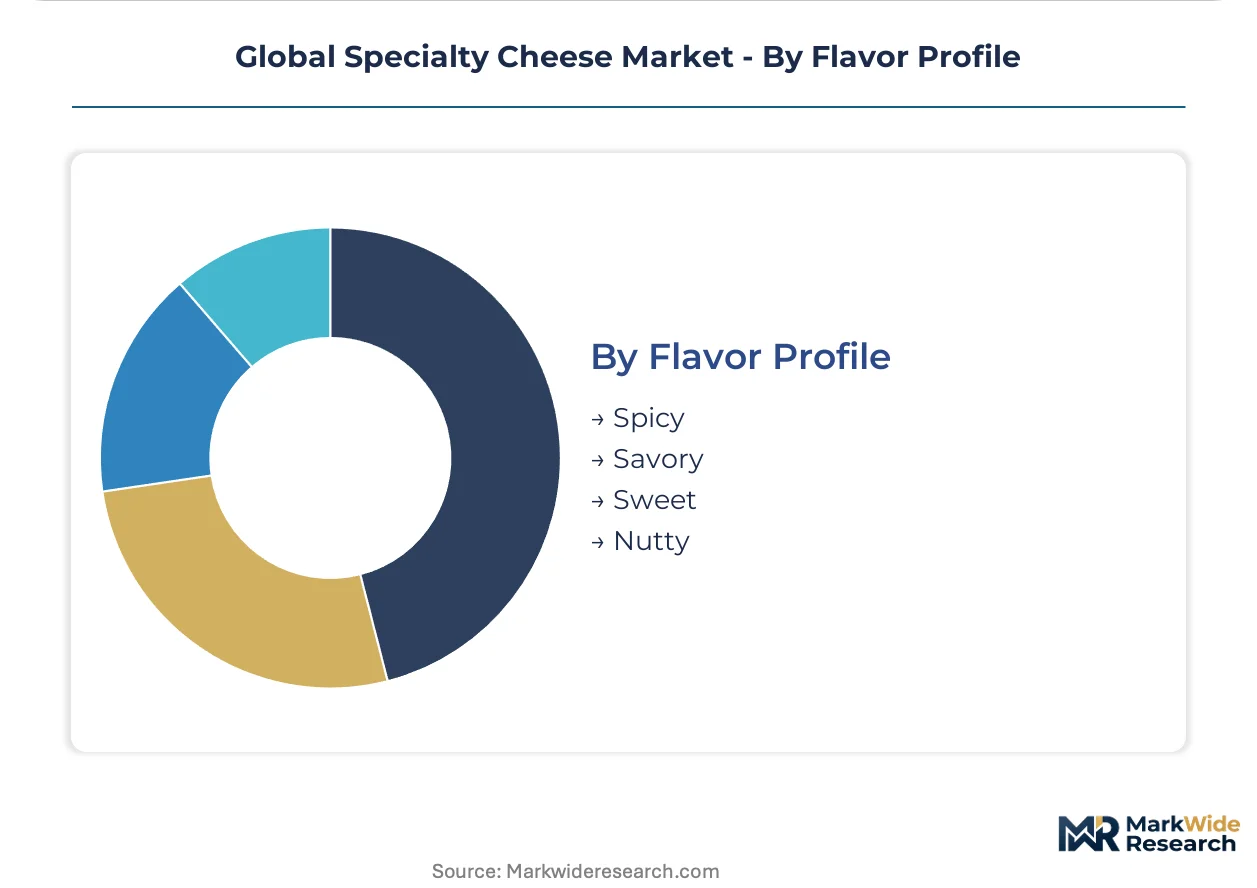
Flavor Profile:
Microbial culture composition and affinage environment sculpt volatile compound development determining sensory categorization.
- Spicy:Pepper-inclusion or aggressive lipase activity creates heat-forward profiles. Limited commercial scale due to narrow demographic appeal.
- Savory:Umami compound concentration through extended proteolysis aligns with foodservice melting applications. Cheddar and aged Gouda variants dominate this space.
- Sweet:Lactose retention and fruity ester development characterize younger, softer varieties. Retail positioning targets dessert and breakfast occasions.
- Nutty:Maillard reaction products and methyl ketone formation during extended aging produce hazelnut and almond notes. Swiss-origin hard cheeses command premium positioning through AOP-certified protocols.
Commercial maturity sits with Savory profiles. Innovation investment flows toward Nutty flavor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors the highest-value specialty cheese consumption cluster globally, with Île-de-France gastronomy corridors absorbing premium AOP-certified wheels through direct affineur relationships and consolidated foodservice procurement.
United States
Wisconsin and Vermont farmstead producers drive artisan volume expansion, while California's Central Valley supplies fluid milk for specialty cheddar aging programs. FDA dairy plant inspection requirements and evolving Listeria monocytogenes standards create regulatory friction that blocks interstate commerce for small-batch raw-milk producers lacking HACCP infrastructure. Brooklyn and San Francisco gastronomy clusters bypass distributor concentration through chef-producer direct contracts.
France
Roquefort-sur-Soulzon and Comté aging caves in the Jura Mountains maintain AOP-certified affinage protocols that command retail price premiums. EU hygiene package revisions tighten pathogen controls for raw-milk production, compressing unlicensed farmstead capacity. Lyon and Marseille foodservice channels incorporate regional cheese boards into standardized restaurant menus, pulling through aged farmstead varieties.
Italy
Emilia-Romagna's Parmigiano-Reggiano consortium enforces strict DOP territorial limits on aging and milk sourcing. CODEX Alimentarius microbiological criteria for Salmonella and Shiga toxin-producing E. coli force export-oriented producers to segregate domestic and international production lines. Milan and Rome retail channels favor younger Grana Padano for everyday consumption while premium positioning concentrates in aged Pecorino Toscano.
Switzerland
Emmental and Gruyère AOP-certified aging protocols in the Bernese Mittelland generate nutty flavor profiles through extended affinage. Swissmedic coordinates with EFSA on dairy pathogen thresholds, maintaining dual compliance tracks for EU export eligibility. Zurich and Geneva direct-to-consumer subscription models capture margin by bypassing wholesale distributor markups.
Spain
Castilla-La Mancha Manchego producers dominate sheep-milk AOP categories through controlled herd management and seasonal milking protocols. Spanish national food safety agency AESAN enforces microbiological criteria that align with EU hygiene package standards. Barcelona and Madrid independent affineurs form cooperative direct-sales networks that bypass consolidated foodservice distributor channels entirely.
Global Specialty Cheese Market Competitive Environment
Premium-margin players sit above commodity-margin players across affinage certification tiers, with AOP-certified aging protocols commanding price premiums that commodity cheddar processors cannot replicate. The market structure bifurcates between licensed artisan facilities with controlled humidity infrastructure and volume producers leveraging captive dairy networks. Three archetypes dominate: heritage affineurs with generational expertise, diversified dairy conglomerates with backward integration into fluid milk supply, and niche specialists exploiting goat-milk supply constraints. Consolidation pressure drives M&A activity among European PDO holdings, while North American players expand aging cellar capacity to capture foodservice channel growth.
Among diversified dairy conglomerates, Saputo Inc. and Lactalis Group exemplify scale-driven positioning through captive North American and European milk sourcing networks. Emmi Group occupies a specialist position within Swiss-origin hard cheese segments, representing heritage affineur archetypes that compete on AOP-certified aging protocols rather than volume scale. These three companies illustrate the competitive tension between commodity-margin cheddar production and premium-margin specialty positioning across divergent capital allocation strategies.
| Leading Market Players |
|---|
| Saputo Inc. |
| Kraft Heinz |
| Lactalis Group |
| Emmi Group |
| Savencia |
| Arla Foods |
| FrieslandCampina |
| Sargento Foods Inc. |
| Fonterra |
| Others |
Value Chain & Pricing Dynamics
Class III milk futures on the Chicago Mercantile Exchange cascade through specialty cheese supply chains into three distinct pricing tiers, with AOP-certified wheels commanding premiums that commodity cheddar processors cannot replicate. Fluid milk contract concentration in France, Wisconsin, and Lombardy shapes margin capture across aging facility tiers.
Pricing Analysis
AOP-certified aging protocols anchor value-based pricing, with affinage duration and microbial culture documentation driving price differentiation between heritage affineurs and volume producers. Certification grade and geographic origin command premiums in foodservice procurement, while private label penetration in French and United States retail channels compresses branded positioning. Cost compression in younger Gouda and Brie segments is intensifying because consolidated supermarket buyers extend payment terms. Price-sensitive mass-market retail segments absorb the tightest margins, while least-sensitive premium restaurant chains prioritize provenance documentation over per-kilogram cost.
Supply Chain Analysis
Dual-sourcing requirements from European foodservice distributors mandate multi-supplier qualification across French, Italian, and Swiss affineurs to mitigate single-source vulnerability. Raw material dependencies center on fluid milk contracts, Penicillium roqueforti cultures, and humidity-controlled cellar infrastructure. Supply chain risk concentrates in tariff exposure for United States farmstead producers seeking EU market access. Distribution runs through consolidated foodservice networks in Paris, New York, and Milan, with direct-to-consumer channels emerging in German and Dutch urban clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU hygiene package revisions and CODEX Alimentarius pathogen thresholds force sub-scale farmstead operations toward exit or acquisition.
For Market Incumbents: To counter affineur skill scarcity and demographic collapse in French and Swiss master cheesemaker programs, Saputo Inc. and Lactalis Group should deepen backward integration into captive fluid milk networks while acquiring distressed PDO holdings in Castilla-La Mancha and Emilia-Romagna. Certification investment in ISO 22000 and blockchain-enabled batch tracking systems will defend positioning against digital traceability mandates. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for goat-milk specialists and plant-based hybrid producers seeking to bypass consolidated foodservice distributor markups. Target German and Dutch urban clusters with temperature-controlled logistics partnerships, leveraging white space in flexitarian retail segments seeking familiar texture profiles without animal-derived inputs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap heritage affineurs with AOP-certified aging protocols in France and Switzerland, where regulatory compliance costs have compressed unlicensed capacity. Long-term viability hinges on 5-10 year positioning within premium foodservice channels as restaurant chains standardize regional cheese boards. Watch for inflection in FDA-EFSA microbiological criteria harmonization debates as the signal triggering accelerated M&A among export-oriented producers.| Strategic Initiative | Industry Significance |
|---|---|
| AOP Certification Investment | Secures price premiums in French and Italian retail channels through protected designation protocols. |
| Direct-to-Consumer Channel Launch | Bypasses consolidated foodservice markups in German and Dutch urban subscription clusters. |
| Digital Traceability Integration | Aligns with EU Green Deal farm-to-fork transparency requirements and ISO 22000 convergence. |
| Backward Integration into Fluid Milk | Locks in consistent supply against Lactalis and Saputo captive network concentration. |
| Plant-Based Hybrid Development | Captures flexitarian demand through precision fermentation combined with traditional affinage expertise. |
Study Parameters
USDA National Agricultural Statistics Service dairy price reports, EU Farm Accountancy Data Network filings, and CODEX Alimentarius microbiological standards formed the secondary backbone. Primary interviews with master affineurs, foodservice procurement directors at premium restaurant chains, dairy plant quality assurance managers, and cooperative network organizers in Spain and Portugal combined with customs records and AOP consortium production disclosures. Bottom-up facility capacity modeling and top-down consumption elasticity analysis enabled triangulation across data sources.
Historical trendline analysis of affinage facility investment cycles, milk contract pricing volatility, and foodservice channel penetration established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product type by aging duration, milk source by protein composition, distribution channel by cold chain requirements, and flavor profile by microbial culture composition. CAGRs derived from elasticity-adjusted volume projections incorporating pathogen regulatory threshold scenarios and digital traceability adoption curves.
The model holds under stable EU hygiene package enforcement and FDA inspection continuity; deviation in raw-milk cheese legality rulings or Listeria monocytogenes standard harmonization would shift volume projections materially. Forecasts reflect assumptions regarding aging facility capex cycles and foodservice procurement consolidation trajectories. A model refresh is warranted upon material change in CODEX Alimentarius microbiological criteria adoption timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United Kingdom Dairy Market
Dairy Products
Africa Yogurt Market
Dairy Products
Japan Dairy Market
Dairy Products
North America Casein Market
Dairy Products
Japan Casein Market
Dairy Products
Sour Cream Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Donkey Milk Market
Dairy Products
Dairy Carton Market
Dairy Products
Filled Cheese Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
Kuwait Dairy Products Market
Dairy Products
Probiotic Cheese Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Global Dairy Market
Dairy Products
Canada Casein and Caseinate Market