
 Mascarpone Cheese Market | 2026-2036
Mascarpone Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Mascarpone Cheese Market Analysis
Bakery applications is restructuring demand profiles across the Mascarpone Cheese Market as artisanal dessert adoption accelerates in Western Europe and North America. Fonterra Co-operative Group Limited leverages its integrated dairy supply chain to secure cream inputs across Oceania and Asian export corridors. BelGioioso Cheese Inc. anchors its position through Wisconsin-based production calibrated to Italian-origin recipes. Granarolo S.p.A. competes from its Emilia-Romagna heartland, sustaining PDO-adjacent quality signaling for foodservice buyers.
Mascarpone cheese is a high-fat fresh cream cheese containing approximately 60-75% milk fat, produced through the acidification of heavy cream using citric or tartaric acid rather than rennet, yielding a spreadable texture critical for tiramisu, cheesecake, and sauce applications. Plain mascarpone dominates volume throughput due to its formulation versatility across sweet and savory recipes, while organic variants capture expanding shelf space in European supermarkets as EFSA-aligned clean-label requirements harden. The foodservice distribution channel generates premium margin pools as restaurants and bakeries prioritize consistent fat-content specifications for recipe stability.
EU food safety frameworks including EFSA standards and PDO labeling requirements shape product standards and market access for imported cream cheese derivatives. The US FDA enforces pasteurization and pathogen controls that determine facility eligibility for American distribution. Stakeholders must monitor evolving dairy fat classification debates within Codex Alimentarius committees that could recalibrate tariff schedules and cross-border ingredient sourcing protocols.
Market Dynamics
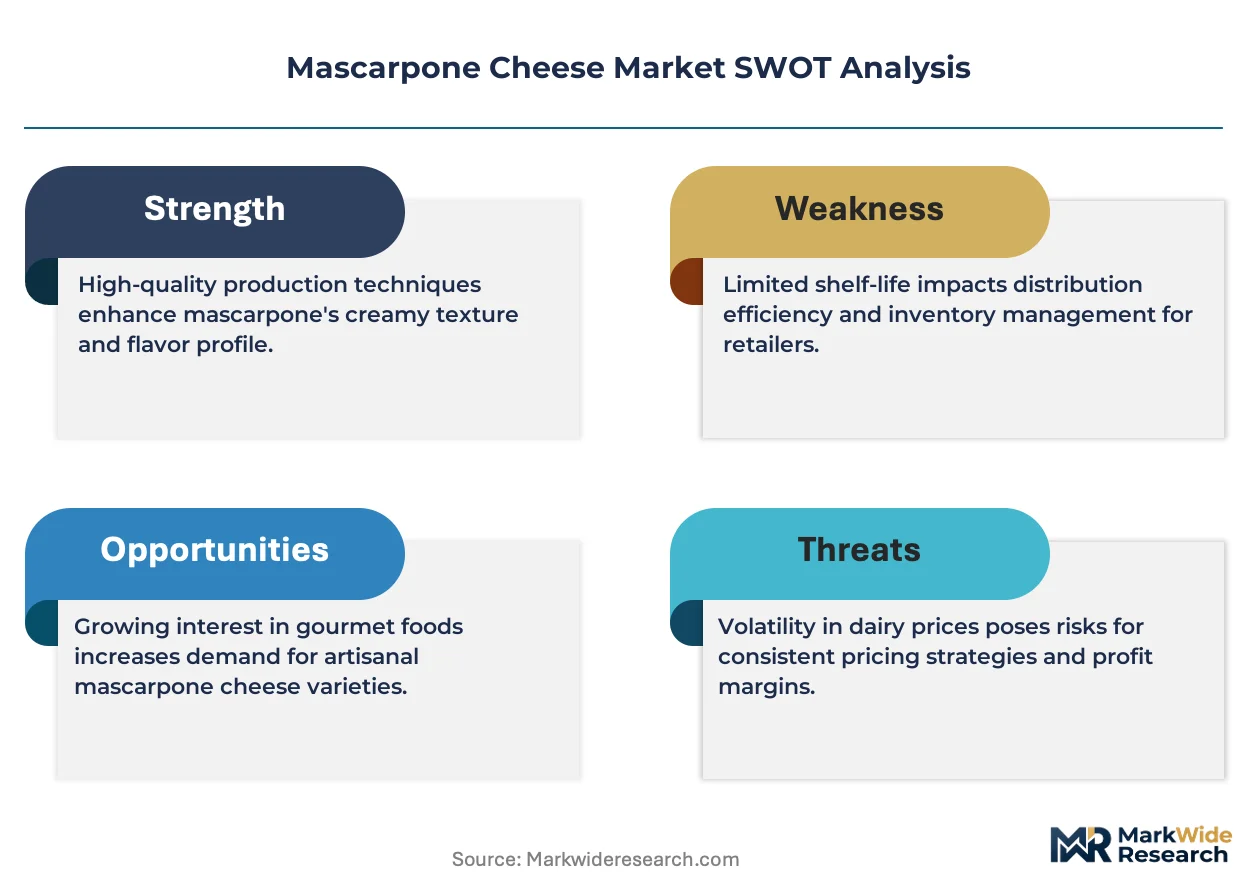
Bakery demand is restructuring supply priorities as artisanal dessert adoption forces cream cheese suppliers to recalibrate fat-content specifications and cold-chain logistics for temperature-sensitive fresh products.
Growth Catalysts
- EFSA-aligned clean-label mandates:European supermarkets are expanding shelf space for organic mascarpone variants as additive disclosure requirements harden across EU member states.
- Foodservice channel premiumization:Restaurants and bakeries in Italy, France, and the United States are locking in consistent fat-content specifications for recipe stability, generating margin pools above retail.
- Artisanal dessert proliferation:Tiramisu and modern cheesecake applications are pulling heavy cream volumes toward acid-coagulated fresh cheese production in Emilia-Romagna and Wisconsin clusters.
Market Restraints
- Cream input cost volatility:Global dairy fat prices fluctuate with feed grain markets and seasonal milk production cycles, compressing processor margins unpredictably.
- Supply concentration in Italian PDO zones:Traditional production gravity in Lombardy and Emilia-Romagna creates geographic vulnerability to regional climate shocks and logistics disruptions.
- Rennet-free process limitations:Acid-coagulation chemistry restricts yield efficiency compared to enzymatic cheese production, capping scale economies for mass-market penetration.
Strategic Opportunities
- Clean-label retail expansion:German and French supermarket chains are carving dedicated fixture space for additive-free fresh cream cheeses with transparent sourcing credentials.
- Asian foodservice penetration:Japanese and South Korean bakery chains are importing Italian-origin mascarpone for fusion dessert applications, bypassing domestic fresh cheese infrastructure gaps.
- US FDA pasteurization alignment:Wisconsin-based producers meeting federal pathogen controls can access American foodservice distribution with Italian-calibrated recipes.
Industry Challenges
- Cold-chain integrity requirements:Fresh cream cheese demands unbroken temperature control from production through foodservice delivery, raising logistics complexity and spoilage risk.
- PDO-adjacent certification timelines:Producers outside protected designation zones face extended quality-auditing processes to signal equivalent standards to European buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mascarpone Cheese Market |
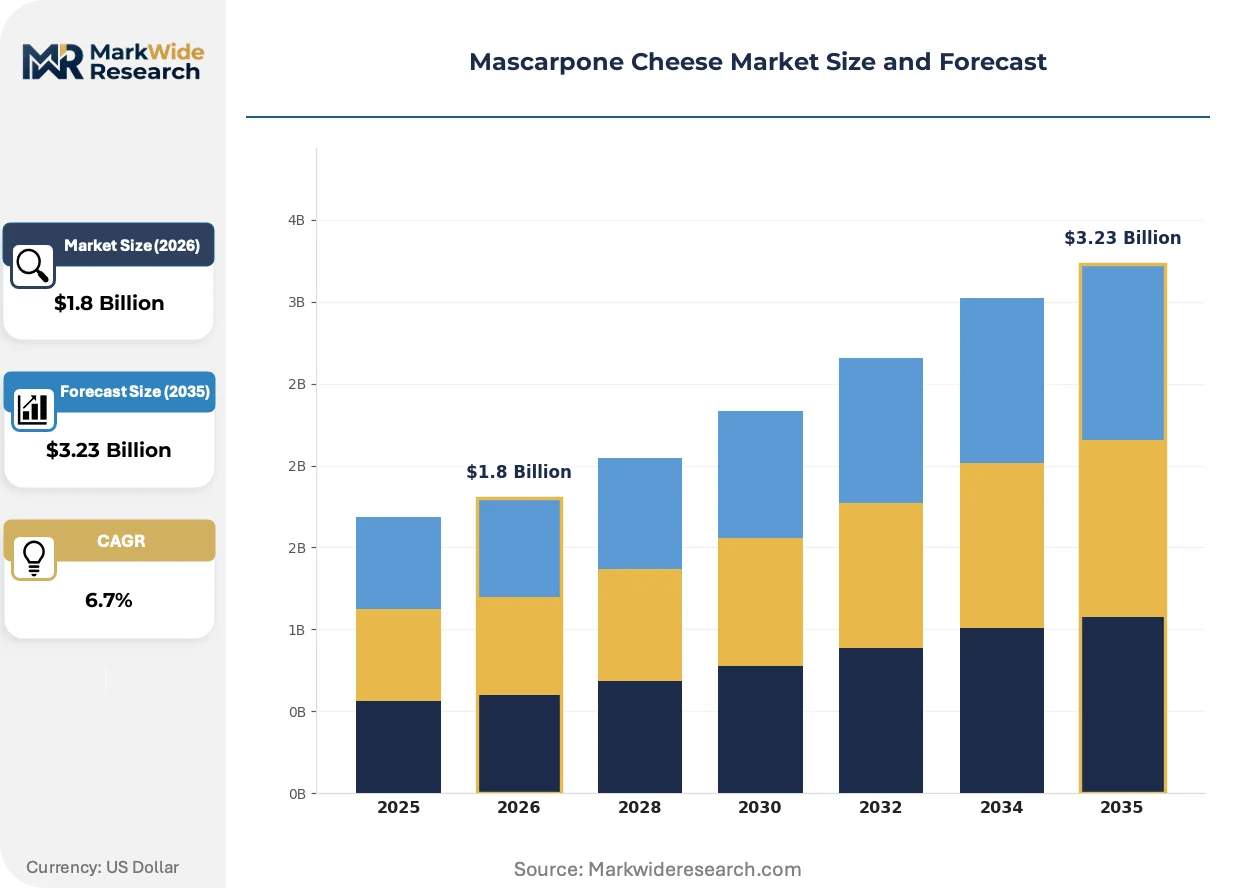
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Organic, Conventional Packaging Type: Tubs, Pouches, Containers, Cartons Distribution Channel: Supermarkets, Specialty Stores, Online, Foodservice End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Fonterra Co-operative Group Limited, Emilio Mauri S.p.A., Granarolo S.p.A., Meadow Foods Ltd., Newlat Food SpA, Arla Foods, BelGioioso Cheese Inc., Quality Cheese Inc., Ferraro Dairy Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mascarpone Cheese Market Emerging Trajectories
Fresh cheese production is absorbing precision fermentation and clean-label formulation advances as suppliers compete on fat-content consistency and additive transparency rather than commodity scale.
Precision fermentation for dairy protein is converging with traditional cream acidification as biotechnology firms develop animal-free fat and protein inputs that replicate mascarpone's 60-75% milk fat texture. Specialty dessert manufacturers in California and the Netherlands are piloting these inputs for vegan tiramisu applications. The technology is converging with conventional supply chains by forcing established processors to defend their Italian-origin authenticity signaling against lab-cultured alternatives.
EFSA's evolving stance on novel food ingredients and clean-label enforcement is tightening additive disclosure requirements for fresh dairy derivatives across EU member states. Processors must now document acidification agents and cream sourcing with granular traceability to maintain retail listings. German and French supermarket buyers are demanding batch-level certification documentation, shifting procurement power toward suppliers with integrated quality management systems.
Foodservice buyers are consolidating supplier relationships around single-source cream cheese contracts with locked fat-content specifications and guaranteed cold-chain integrity. Independent bakeries in Milan, Paris, and New York are displacing spot-market purchasing with annual volume agreements that include technical support and recipe calibration services. This consolidation is most visible in premium dessert segments where consistency failures carry immediate reputational costs.
Mascarpone Cheese Market Segmentation
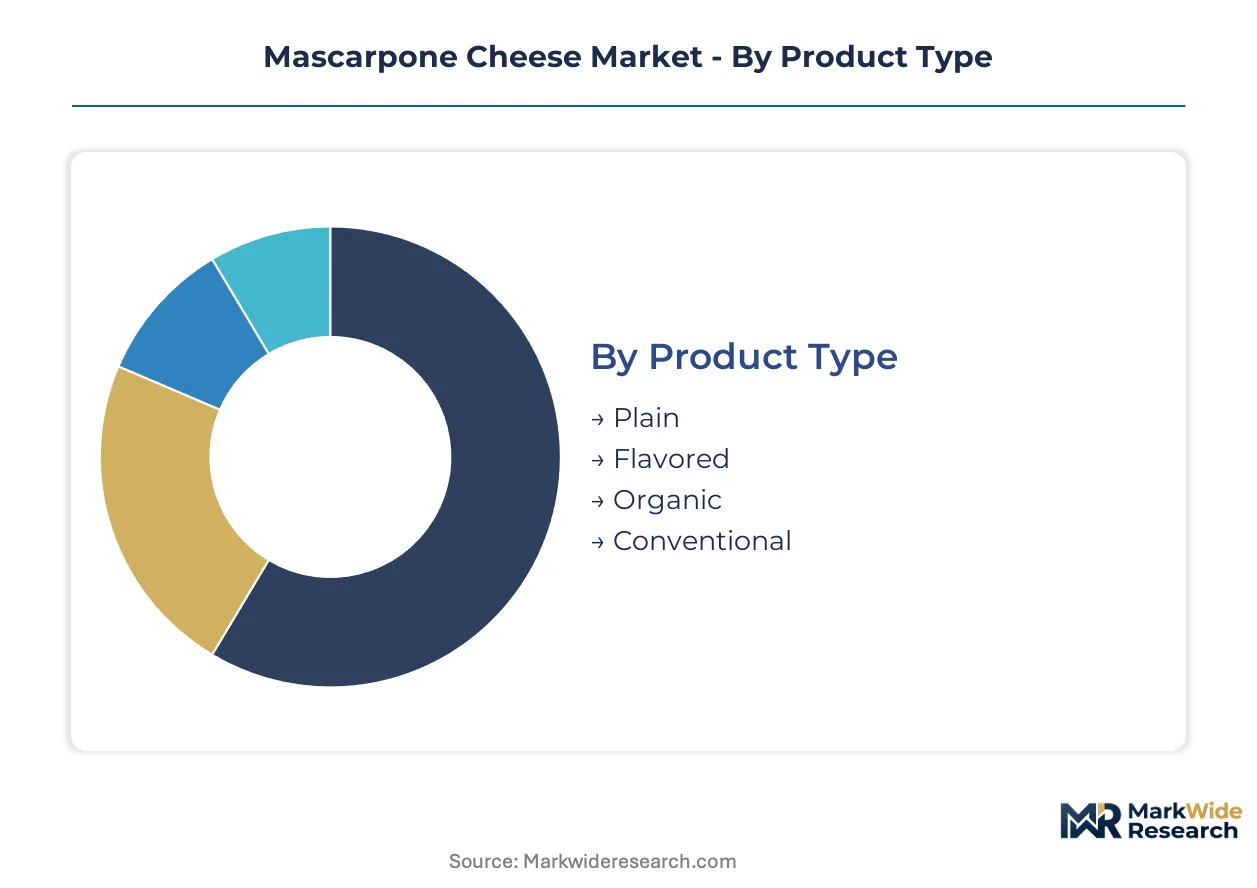
Mascarpone cheese segmentation reveals how capital requirements, shelf-life constraints, and regulatory compliance reshape competitive entry barriers across production formats. Suppliers must align facility investments with specific segment demands for fat-content precision and cold-chain integrity.
Product Type:
Capital intensity peaks in organic certification infrastructure, where dedicated production lines and traceability systems demand seven-figure facility upgrades before market entry.
- Plain:Standard 60-75% milk fat formulations dominate volume throughput across tiramisu and cheesecake applications. Italian PDO-adjacent producers in Lombardy anchor supply for European foodservice buyers demanding batch-level consistency.
- Organic:EFSA-aligned clean-label mandates drive German and French supermarket expansion. Producers must document acidification agents and cream sourcing with granular traceability, raising compliance costs substantially.
- Flavored:Vanilla and citrus variants target premium retail shelves in North American specialty grocers. Limited production runs constrain scale economies.
- Conventional:Non-certified formulations serve price-sensitive food manufacturers in industrial bakery applications. Wisconsin-based processors compete on pasteurization alignment with US FDA pathogen controls.
Most installed capacity flows through Plain. Expansion is steepest in Organic.
Packaging Type:
Packaging selection directly determines shelf-life extension capabilities and logistics cost structures for temperature-sensitive fresh cheese.
- Tubs:Polypropylene containers with modified atmosphere sealing dominate retail distribution. Italian exporters prioritize tub formats for trans-Atlantic cold-chain integrity to US East Coast ports.
- Pouches:Flexible film reduces shipping cube and refrigeration load for foodservice bulk users. Japanese bakery chains import pouch formats for fusion dessert production.
- Containers:Rigid plastic with resealable lids targets household repeat-purchase segments in French hypermarkets.
- Cartons:Paperboard with polyethylene lining serves sustainability-positioned European retailers under EU Green Deal packaging directives.
Tub formats command the highest unit margins. Pouch adoption is climbing fastest among foodservice distributors.
Distribution Channel:
Channel selection dictates margin capture, with foodservice contracts locking in annual volumes versus spot-market retail exposure.
- Foodservice:Single-source contracts with locked fat-content specifications generate premium pools above retail. Milan and Paris bakeries displace spot purchasing for guaranteed cold-chain integrity.
- Supermarkets:German chains like Edeka and REWE carve dedicated fixture space for additive-free variants with transparent sourcing credentials.
- Specialty Stores:Italian delicatessens and cheese mongers in New York and London emphasize PDO-adjacent provenance signaling.
- Online:Direct-to-consumer platforms aggregate artisanal producers for temperature-controlled last-mile delivery in dense European urban corridors.
Foodservice channels concentrate procurement power. Online distribution is expanding most quickly in premium household segments.
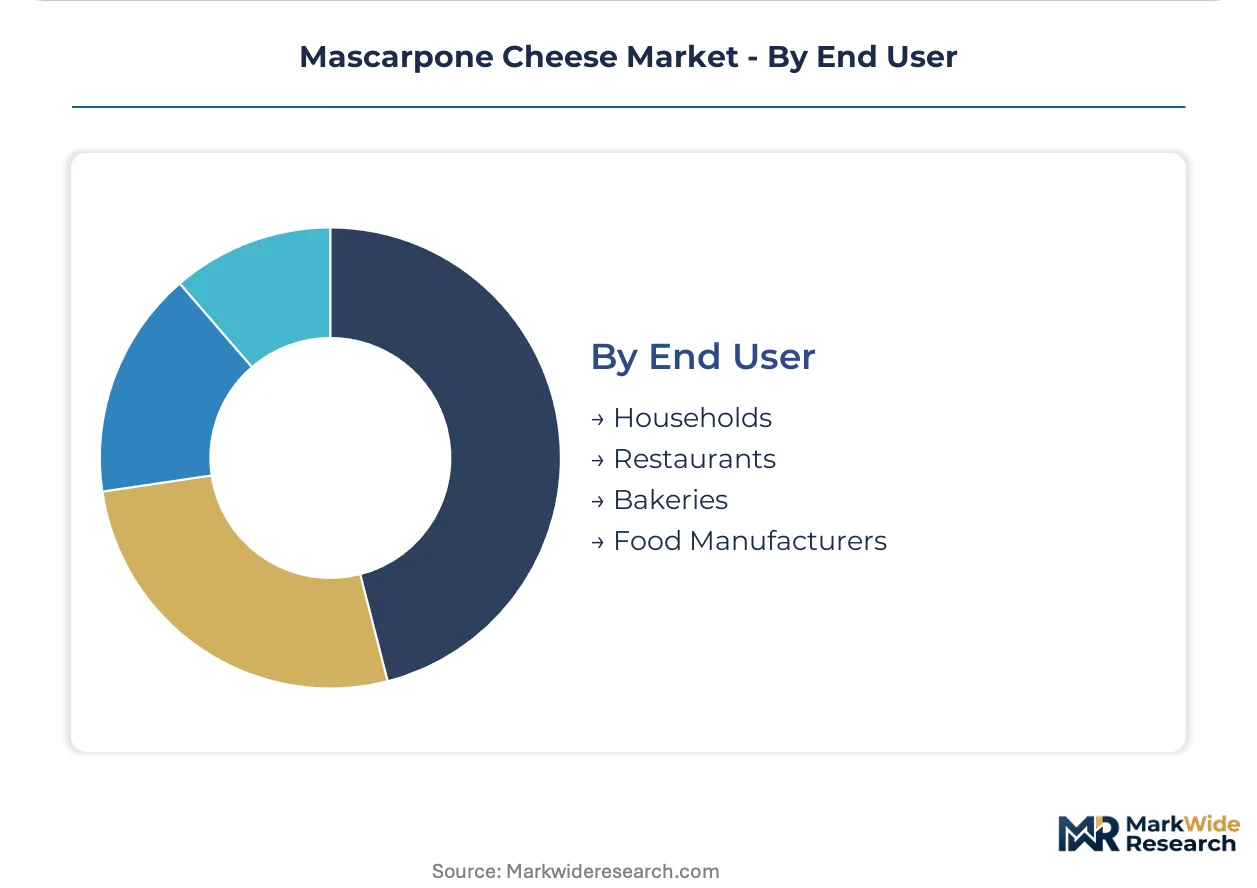
End User:
End-use segmentation separates recipe-calibration requirements from commodity ingredient purchasing patterns.
- Restaurants:Fine-dining establishments in Italy and France prioritize consistent fat-content specifications for sauce stability and dessert presentation.
- Bakeries:Artisanal dessert proliferation across Western Europe pulls heavy cream volumes toward acid-coagulated production with technical support contracts.
- Households:Retail purchasers favor smaller formats with extended refrigerated shelf life for home tiramisu preparation.
- Food Manufacturers:Industrial users in cheesecake and prepared dessert production source bulk conventional formats with pasteurization documentation for FDA compliance.
Restaurants anchor premium pricing. Bakeries are gaining share fastest as artisanal dessert adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting fresh cream cheese production toward jurisdictions with streamlined dairy safety certifications and lower cold-chain compliance costs. Italian-origin producers face margin pressure from Wisconsin-based competitors meeting US FDA pasteurization standards with equivalent fat-content specifications.
Italy
Artisanal dessert demand in Milan and Rome sustains premium pricing for PDO-adjacent production from Lombardy and Emilia-Romagna clusters. EFSA clean-label mandates tighten additive disclosure requirements for acid-coagulated fresh cheeses entering German and French retail channels. Traditional producers in the Po Valley maintain supply influence through batch-level consistency protocols calibrated for tiramisu applications.
United States
Wisconsin-based processors capture foodservice share by aligning acidification recipes with FDA pathogen controls and guaranteed cold-chain specifications. The USDA dairy grading program shapes procurement standards for industrial bakery users sourcing bulk conventional formats. Greater Milwaukee production clusters supply East Coast ports with Italian-calibrated formulations for restaurant and bakery contracts.
Germany
Edeka and REWE supermarket chains drive organic variant expansion through dedicated fixture space for additive-free fresh cream cheeses with transparent sourcing credentials. EU Green Deal packaging directives accelerate carton format adoption for sustainability-positioned retail segments. Bavarian dairy processors are investing in traceability systems to document acidification agents for EFSA-aligned compliance.
Japan
Fusion dessert proliferation in Tokyo and Osaka bakery chains pulls imported Italian-origin mascarpone through specialized cold-chain logistics for temperature-sensitive fresh products. The Ministry of Health, Labour and Welfare enforces dairy import standards that favor established European suppliers with documented production histories. Kanto region distributors are consolidating supplier relationships around single-source contracts with locked fat-content specifications.
France
Parisian fine-dining establishments prioritize consistent fat-content specifications for sauce stability, generating premium margin pools above retail supermarket channels. ANSM food safety frameworks align with EFSA standards for clean-label enforcement across hypermarket distribution. Île-de-France foodservice buyers are displacing spot-market purchasing with annual volume agreements that include technical support and recipe calibration services.
Mascarpone Cheese Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with Italian-origin producers commanding premium positioning in European foodservice while Wisconsin-based fabricators capture scale efficiencies in North American retail. The vendor base organizes around three strategic archetypes: PDO-adjacent heritage specialists, integrated dairy cooperatives with captive cream supply, and regional contract manufacturers serving private-label supermarket programs. Dominant competitive moves include backward integration into heavy cream sourcing and geographic expansion through cold-chain partnerships with third-party logistics providers.
Among integrated dairy cooperatives, Fonterra Co-operative Group Limited and Arla Foods exemplify the archetype of operators leveraging captive milk supply to secure cream inputs across export corridors. Italian heritage specialists Granarolo S.p.A. and BelGioioso Cheese Inc. occupy positions defined by Emilia-Romagna and Wisconsin production clusters respectively, each calibrated to Italian-origin recipe standards with regional regulatory alignment. These named entities represent the competitive tension between authentic provenance signaling and pasteurization-compliant scale production.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Emilio Mauri S.p.A. |
| Granarolo S.p.A. |
| Meadow Foods Ltd. |
| Newlat Food SpA |
| Arla Foods |
| BelGioioso Cheese Inc. |
| Quality Cheese Inc. |
| Ferraro Dairy Foods |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Lombardy and Emilia-Romagna anchor production clusters, translating heritage authenticity into pricing power while constraining supply scalability through artisanal batch protocols. Their ownership structure limits external financing for cold-chain expansion, forcing selective channel prioritization that concentrates premium pricing in foodservice contracts.
Pricing Analysis
Distributor margin layers separate Italian-origin PDO-adjacent producers from Wisconsin-based competitors, with three-tier pricing structure across premium, standard, and economy levels. Premium tiers command fat-content precision guarantees and batch-level traceability documentation for Milan and Paris fine-dining establishments. Price erosion runs through conventional formats as industrial bakery buyers consolidate volume purchasing power. Foodservice channels exhibit lowest price sensitivity due to recipe stability requirements, while retail supermarkets drive hardest bargain on organic variants.
Supply Chain Analysis
Reverse-logistics constraints are minimal for fresh cream cheese given perishable shelf life, though temperature excursions trigger immediate disposal rather than refurbishment. Heavy cream inputs draw from Lombardy, Wisconsin, and Bavarian dairy clusters, with citric acid and tartaric acid acidification agents sourced from German and Chinese chemical processors. Single-source vulnerability concentrates in Italian PDO zones exposed to regional climate shocks. Distribution runs through cold-chain partnerships with third-party logistics providers serving East Coast US ports and Japanese Kanto region bakery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mascarpone cheese has entered late-cycle quality dominance as artisanal dessert specifications harden fat-content tolerances and eliminate commodity substitution. Tiramisu and modern cheesecake applications now demand batch-level consistency that rewards provenance signaling over volume scale.
For Market Incumbents: Hedge precision fermentation disruption by fortifying Italian-origin authenticity credentials through granular traceability systems and PDO-adjacent quality auditing. Backward integration into heavy cream sourcing secures input cost stability against dairy fat volatility. Channel control through single-source foodservice contracts with locked specifications protects margin pools above retail spot markets. For New Entrants and Emerging Players: Foodservice distributors represent the most accessible entry vector for Wisconsin-based producers meeting FDA pasteurization standards with Italian-calibrated recipes. White-space concentrates in Asian bakery chains importing through specialized cold-chain logistics for fusion dessert applications. German supermarket chains carving dedicated fixture space for additive-free variants offer secondary penetration opportunity through transparent sourcing credentialing. For Investors and Strategic Acquirers: Valuations sit cheapest among regional contract manufacturers serving private-label supermarket programs with pasteurization-compliant scale production. Five-to-ten year viability hinges on clean-label enforcement trajectory across EU member states and biotechnology firm progress in animal-free fat replication. Monitor EFSA novel food ingredient rulings and precision fermentation pilot scale-up announcements as inflection indicators for conventional supply chain displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heavy Cream Supply | Fonterra and Arla Foods secure captive cream inputs across Oceania and European export corridors. |
| PDO-Adjacent Quality Certification Investment | Granarolo S.p.A. sustains batch-level consistency protocols for Milan foodservice buyer retention. |
| Cold-Chain Partnership Expansion | BelGioioso Cheese Inc. accesses US East Coast ports through third-party logistics provider alliances. |
| Clean-Label Formulation Development | Organic variants capture German Edeka and REWE shelf space under EFSA-aligned disclosure mandates. |
| Asian Foodservice Distribution Agreement | Japanese bakery chains import Italian-origin product through Kanto region single-source contracts. |
Methodological Framework
Bottom-up bakery and restaurant demand modeling reconciled against top-down cream input supply tracking forms the analytical core. Primary interviews with dairy procurement managers at Italian food manufacturers, Wisconsin-based production facility directors, German supermarket category buyers, and Japanese cold-chain logistics operators combined with secondary validation from FDA pasteurization documentation, EFSA clean-label enforcement records, EU Green Deal packaging directive filings, and customs trade data for fresh cheese derivatives.
Historical trendline analysis of acid-coagulated fresh cheese production volumes and fat-content specification premiums informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type certification tier, packaging format shelf-life extension capability, distribution channel margin structure, and end-use recipe calibration requirement. CAGRs derived from volume-weighted average of segment growth trajectories, with dairy fat price volatility and artisanal dessert adoption curves as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to precision fermentation technology maturation and EFSA novel food ingredient classification decisions. Forecasts reflect documented assumptions on clean-label enforcement trajectory, cold-chain infrastructure investment rates, and biotechnology firm partnership announcements with conventional processors. Practitioners should monitor Codex Alimentarius dairy fat classification debates and precision fermentation pilot production scale-up for early signals of supply chain structure revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Yogurt and Probiotic Drink Market
Dairy Products
Sheep Milk Market
Dairy Products
Blue Cheese Market
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Middle East and Africa Whey Protein Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Dairy Blends Market
Dairy Products
Asia-Pacific Milk Protein Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
North America Yogurt Market
Dairy Products
Butter and Margarine Market
Dairy Products
Sweet Whey Market
Dairy Products
North America Dairy Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Paneer Market