
 Cultured Dairy Blends Market | 2026-2036
Cultured Dairy Blends Market Size, Share, and Industry Trends Forecast 2026-2036
Cultured Dairy Blends Market Outlook
Ingredient functionality premiums is reconfiguring margin distribution across the cultured dairy value chain. Danone leverages its fermentation science depth to sustain European market positioning. Chobani LLC anchors North American yogurt blend innovation through controlled dairy sourcing. Fonterra Co-operative Group competes on milk solids supply security for industrial blend formulations.
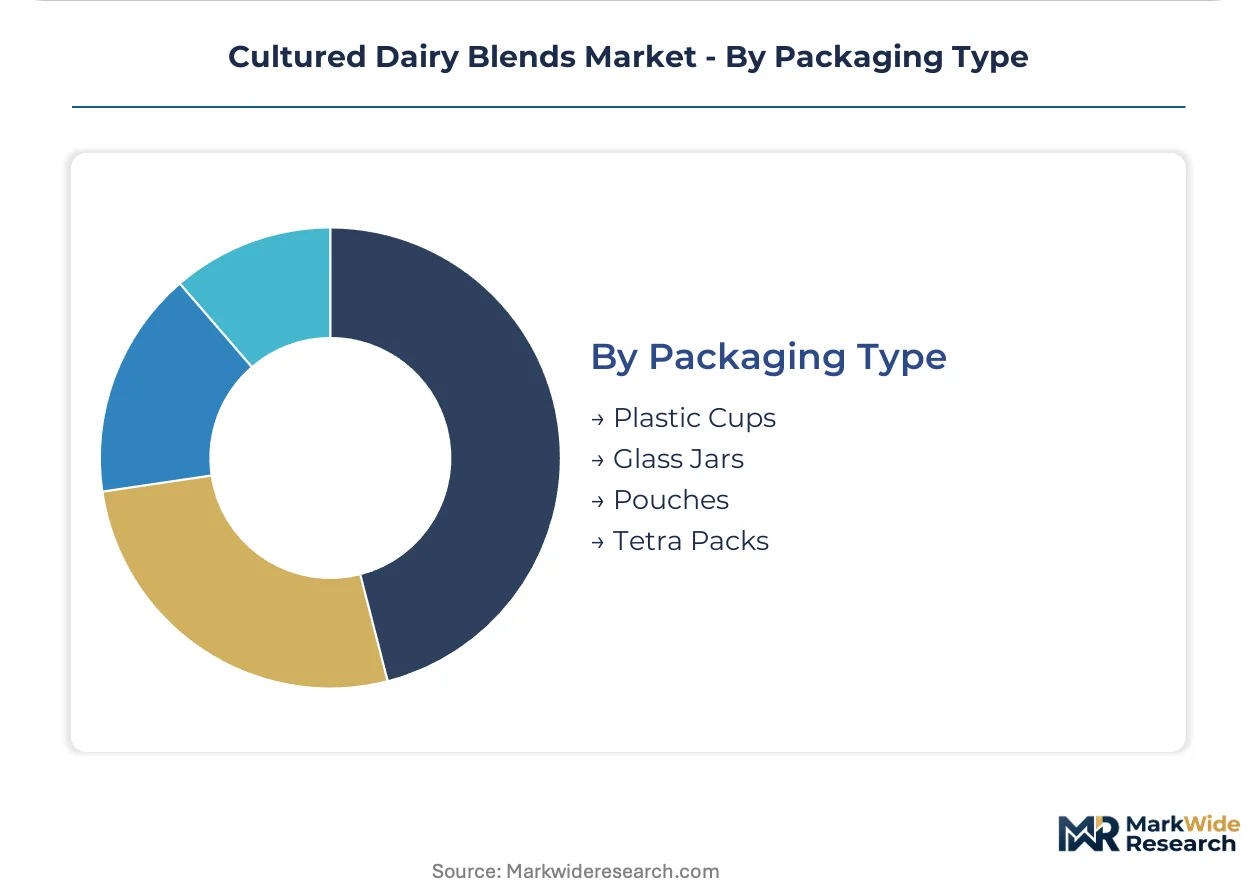
Cultured dairy blends combine fermented milk substrates with functional cultures, stabilizers, and flavor systems to achieve defined pH ranges, typically between 4.0 and 4.6, with live culture counts exceeding specified thresholds for probiotic claims. These products serve commercial food manufacturing and direct consumption channels requiring consistent texture, shelf stability, and nutritional labeling compliance. The yogurt segment dominates volume throughput across retail and food processing channels, while kefir applications in beverages represent the fastest-growing position driven by functional health positioning. Plastic cups retain the largest packaging share though pouches gain traction in snack-oriented formats where portability commands price premiums.
FDA standards for Grade A dairy products, EFSA health claim substantiation protocols, and FSSAI licensing requirements for fermented milk products collectively shape formulation thresholds and cross-border market access conditions. Compliance with dual carbon goals in China and EU Green Deal sustainability metrics is redirecting capital toward lower-emission fermentation infrastructure and recyclable packaging transitions. Stakeholders must monitor evolving live culture count thresholds and carbon intensity disclosure mandates as these parameters increasingly determine competitive shelf access and procurement contract eligibility.
Market Dynamics
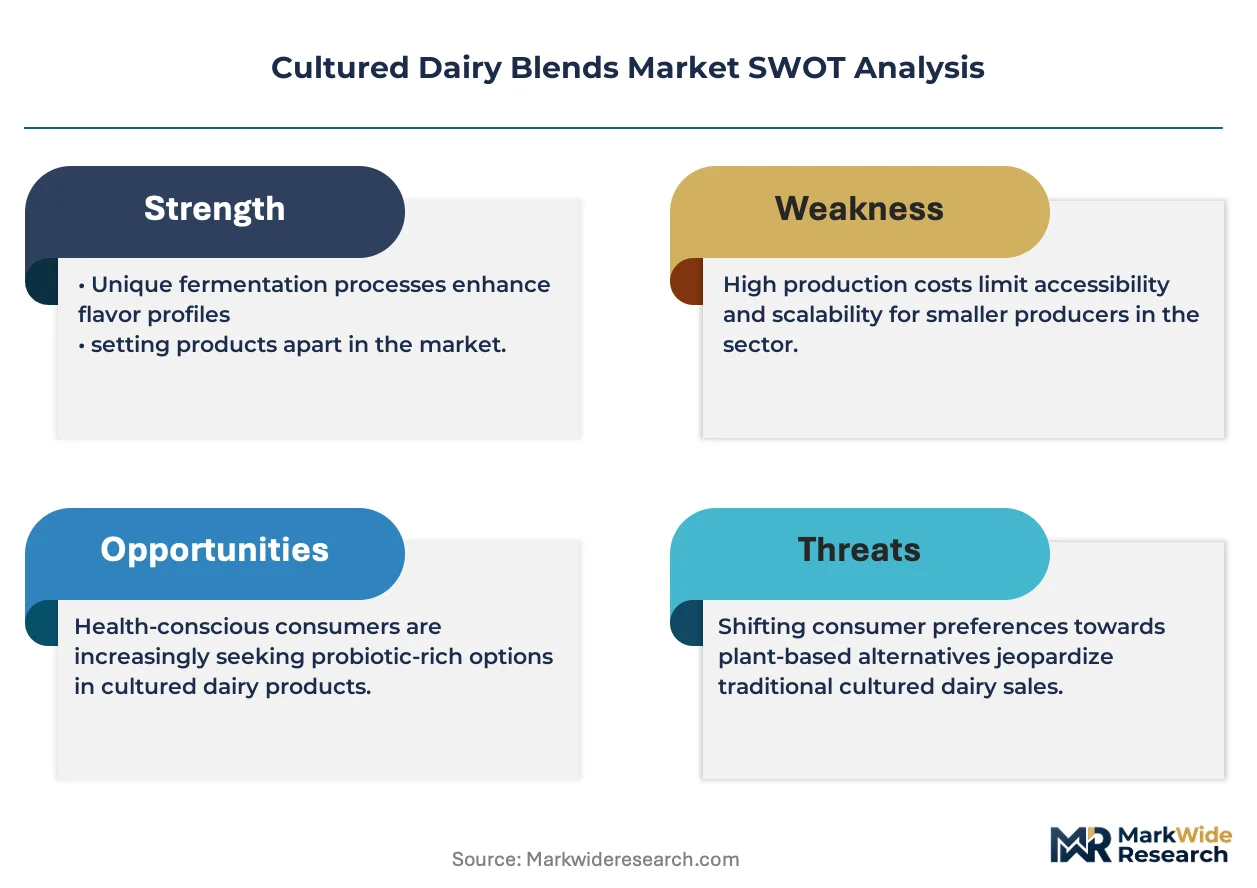
Fermentation infrastructure consolidation and clean-label reformulation mandates are compressing margin structures across the cultured dairy value chain, forcing operators to choose between capital-intensive facility upgrades or private-label commoditization.
Growth Catalysts
- EFSA Health Claim Substantiation:Validated probiotic positioning unlocks premium shelf placement in European retail channels and commands price multiples over standard yogurt formulations.
- Kefir Beverage Applications:Functional drink formats attract health-conscious consumers seeking portable gut-health solutions beyond traditional spoonable yogurt.
- Food Service Menu Integration:Commercial kitchens in the United States, Germany, and Japan are expanding probiotic-rich cultured products into sauces, dressings, and dessert applications.
Market Restraints
- Milk Solids Supply Concentration:New Zealand and EU dairy cooperatives control critical protein and fat inputs, exposing blend manufacturers to weather-driven volatility and export quota restrictions.
- Live Culture Count Thresholds:FDA Grade A standards and FSSAI licensing requirements impose strict minimums that disqualify formulations with compromised fermentation consistency.
- Plant-Based Fermentation Substitutes:Oat and coconut yogurt alternatives capture lactose-intolerant and vegan households, eroding addressable market for dairy-based cultured products.
Strategic Opportunities
- Japan's Functional Foods Channel:FOSHU (Foods for Specified Health Uses) approval pathways enable premium positioning for clinically substantiated probiotic strains in aging demographics.
- Pouch Packaging Innovation:Flexible single-serve formats penetrate snacking occasions where plastic cups fail, unlocking convenience-store and on-premise vending placements.
- EU Green Deal Carbon Metrics:Lower-emission fermentation infrastructure qualifies for green procurement contracts and sustainability-linked financing instruments.
Industry Challenges
- Fermentation Science Talent Scarcity:Industrial microbiologists with strain optimization expertise command compensation premiums that strain mid-tier operator budgets.
- Dual Certification Timelines:Simultaneous FDA and EFSA compliance for cross-border products extends development cycles and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cultured Dairy Blends Market |
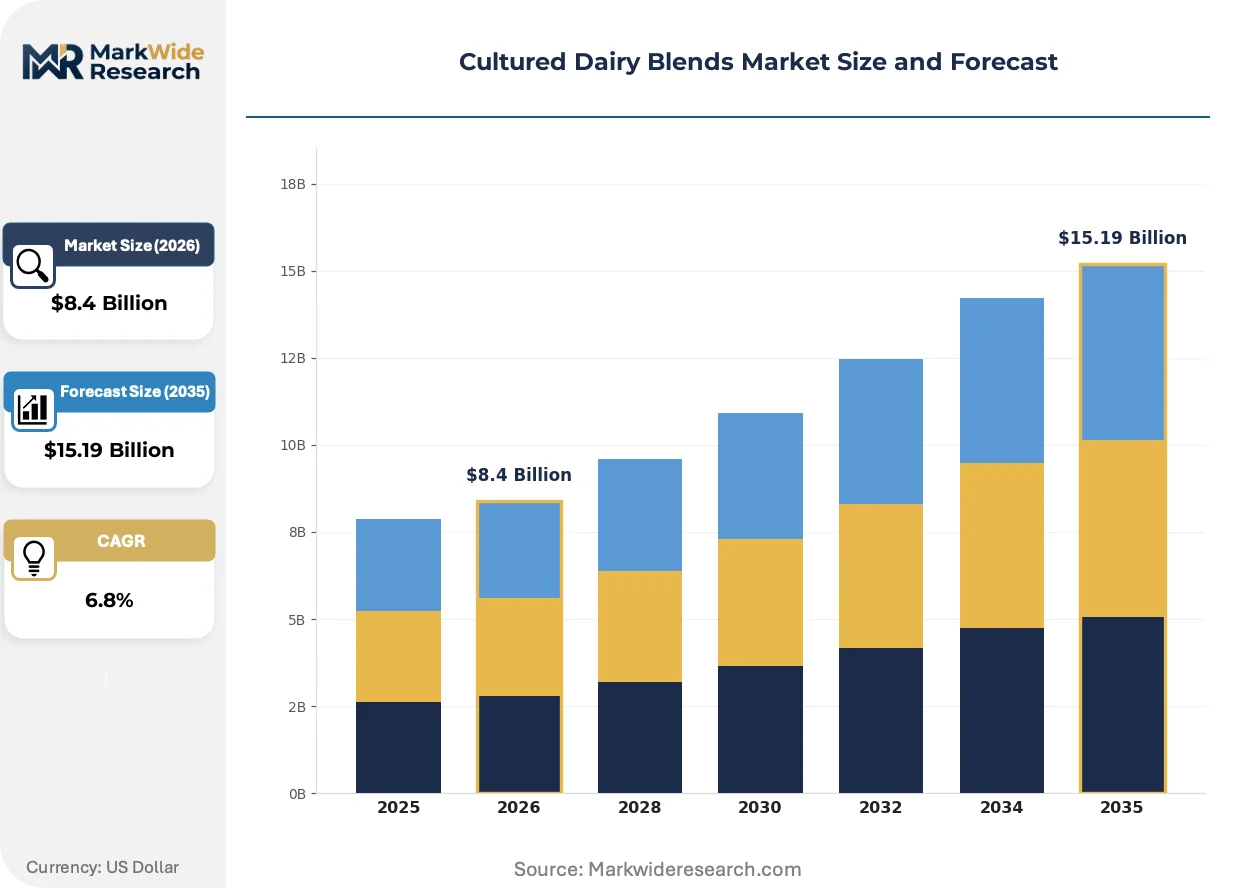
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yogurt, Kefir, Sour Cream, Cream Cheese Application: Desserts, Snacks, Beverages, Sauces End User: Residential, Food Service, Food Processing, Retail Packaging Type: Plastic Cups, Glass Jars, Pouches, Tetra Packs |
| Companies Covered | Nestle, Lactalis, Chobani LLC, Danone, Fonterra Co-operative Group, Arla Foods, Royal FrieslandCampina, Yakult Honsha Co., Ltd., Agropur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cultured Dairy Blends Market Strategic Shifts
Precision fermentation and culture banking technologies are rewriting strain development economics, while regulatory disclosure requirements and channel fragmentation are forcing simultaneous adaptation across multiple operational fronts.
High-throughput screening platforms for probiotic strain selection are collapsing the traditional 18-24 month development timeline for new cultured dairy formulations. Mid-sized blend manufacturers in the United States and Germany are adopting these tools to match Danone's historical fermentation depth without captive research infrastructure. The compression is enabling faster response to emerging health positioning claims and reducing first-mover advantage duration for established players.
EFSA's evolving health claim substantiation protocols are tightening evidentiary standards for gut microbiome benefits, forcing reformulation investments toward clinically validated strain combinations. Industrial blend suppliers serving European retail channels must now commission human intervention studies to maintain shelf access. The policy shift most impacts commodity yogurt producers lacking R&D scale to absorb compliance costs.
Direct-to-subscription models for functional dairy products are bypassing traditional retail slotting fee structures that favor multinational volume commitments. Niche operators in Japan and Germany are building recurring revenue through personalized strain-matching services based on consumer microbiome testing. The channel innovation concentrates in urban clusters where premium positioning and delivery logistics achieve viable unit economics.
Cultured Dairy Blends Market Segmentation
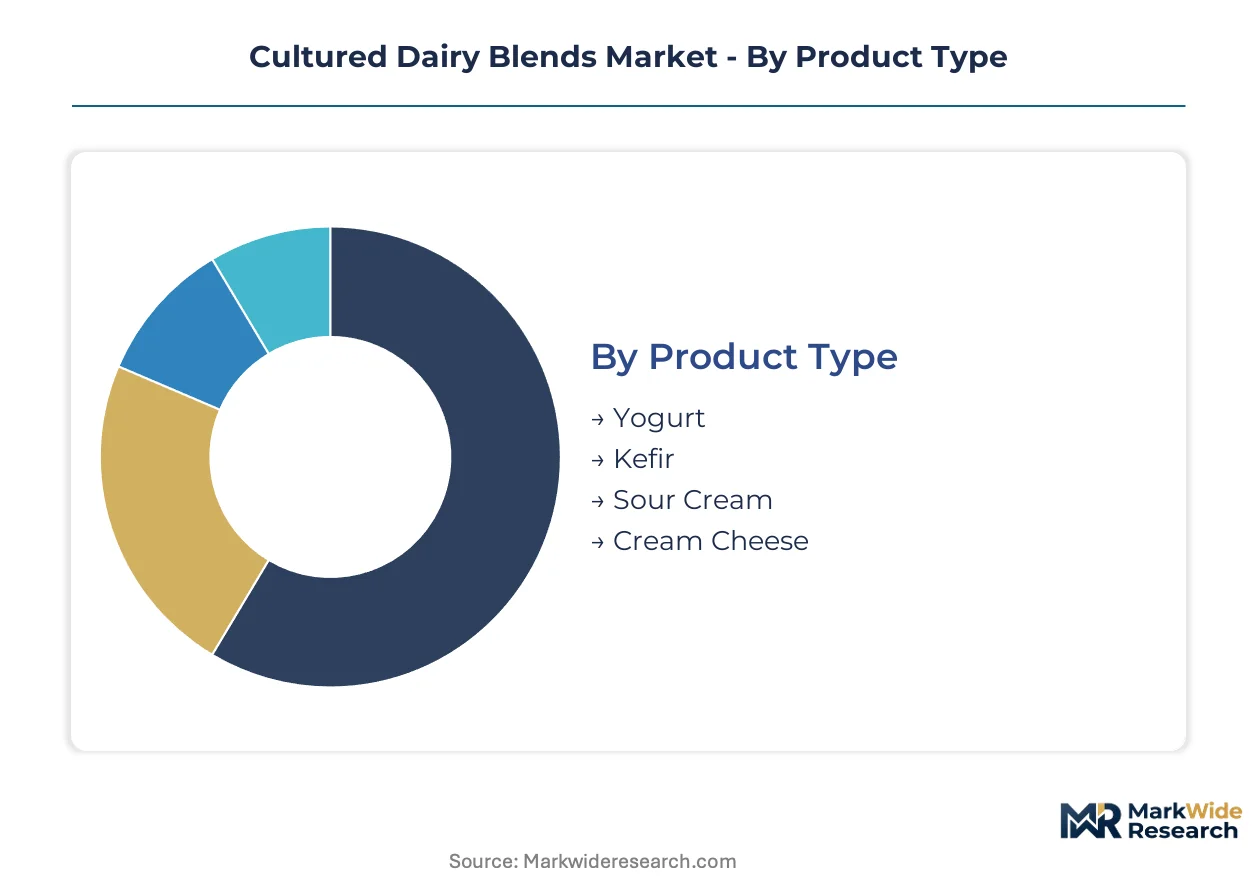
Cultured dairy blends serve heterogeneous demand pools requiring precise technical alignment between fermentation specifications and channel requirements. Product formulation, application context, and packaging format each impose distinct constraints on pH stability, live culture viability, and shelf-life performance.
Product Type:
Cost tier differentiation separates commodity-positioned formats from clinically substantiated functional premiums.
- Yogurt:Spoonable fermented milk products with standardized pH ranges between 4.0 and 4.6 and live culture counts meeting FDA Grade A thresholds. Demand concentrates in United States retail channels where clean-label positioning commands shelf space against private-label alternatives.
- Kefir:Pourable fermented beverages incorporating multiple yeast and bacterial strains, delivering higher probiotic diversity than standard yogurt. Applications in Germany and Japan are expanding fastest as functional drink formats capture health-conscious consumers seeking portable gut-health solutions.
- Sour Cream:High-fat cultured cream products serving food processing and food service channels requiring stable emulsion performance under thermal stress.
- Cream Cheese:Fresh cheese-cultured hybrid products with extended fermentation cycles, dominating bagel and bakery applications in North American food service.
Yogurt commands the established base. The steepest expansion runs through kefir.
Application:
Application context determines formulation priorities around viscosity, acid stability, and flavor masking requirements.
- Desserts:Cultured dairy bases requiring precise gelation control and sugar tolerance to maintain texture through freeze-thaw cycles. United States and Japanese retail channels prioritize indulgent positioning with probiotic health claims.
- Beverages:Drinkable formats demanding suspension stability for insoluble fibers and flavor systems without compromising mouthfeel. German and Japanese markets show strongest momentum as on-the-go consumption patterns displace traditional spoonable occasions.
- Snacks:Portion-controlled formats emphasizing portability and extended ambient stability for convenience retail placement.
- Sauces:Industrial formulations requiring heat stability and emulsion integrity under commercial kitchen conditions.
Desserts anchor volume throughput. Beverage applications are climbing the fastest.
End User:
Customer type segmentation reflects divergent procurement specifications between household purchasing and commercial scale operations.
- Residential:Direct-to-consumer sales through retail channels with emphasis on family-sized formats and recognizable probiotic strain branding. United States supermarkets and Japanese convenience stores concentrate volume.
- Food Service:Commercial kitchen procurement requiring bulk packaging, consistent batch performance, and technical support for menu integration. Demand clusters in United States fast-casual chains and German institutional catering.
- Food Processing:Industrial ingredient buyers sourcing standardized cultured bases for downstream manufacturing with strict specification compliance and supply security requirements.
- Retail:Branded and private-label finished goods distribution through grocery, convenience, and specialty channels with slotting fee structures favoring volume commitments.
Food service and retail split the commercial base. Residential direct-to-subscription models are gaining share fastest.
Packaging Type:
Format selection trades off shelf visibility, portability, and sustainability compliance against unit economics and filling line compatibility.
- Plastic Cups:Thermoformed polystyrene or polypropylene containers retaining dominant retail share through established filling infrastructure and consumer familiarity. United States and German markets face mounting pressure under EU Green Deal and state-level plastic reduction mandates.
- Pouches:Flexible single-serve formats with reduced material intensity and enhanced portability for snacking occasions. Japanese convenience stores and United States grab-and-go channels are expanding placements fastest.
- Glass Jars:Premium-positioned formats supporting artisanal branding and reuse programs, concentrated in European specialty retail and direct-to-consumer channels.
- Tetra Packs:Aseptic carton formats enabling ambient distribution and extended shelf life for beverage applications in emerging market retail.
Plastic cups retain volume leadership. Pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States favors spoonable yogurt formats for breakfast occasions. Germany and Japan prioritize pourable kefir beverages for functional health positioning. These demand-mix differentials shape local formulation requirements and channel strategies.
United States
Retail yogurt demand concentrates in family-sized formats with clean-label positioning. FDA Grade A standards enforce minimum live culture counts for probiotic claims. California and New York dairy corridors host fermentation facilities supplying national retail chains.
Germany
Kefir beverage consumption exceeds yogurt penetration in urban centers seeking portable gut-health solutions. EFSA health claim substantiation protocols require clinical validation for premium shelf placement. Bavaria and North Rhine-Westphalia cluster industrial blend manufacturing for European distribution.
Japan
Aging demographics drive FOSHU-approved functional dairy positioning with clinically substantiated strains. METI and PMDA frameworks govern health claim approvals and fermentation facility licensing. Tokyo-Osaka corridor convenience stores lead pouch-format adoption for on-the-go consumption.
China
Middle-class expansion sustains demand for ambient-stable yogurt beverages in tier-one cities. SAMR and dual carbon goals redirect capital toward lower-emission fermentation infrastructure. Yangtze River Delta dairy processors invest in recyclable packaging transitions to meet procurement contract eligibility.
India
Traditional dahi consumption provides foundation for branded cultured product expansion in urban markets. FSSAI licensing requirements for fermented milk products impose strict quality thresholds. Maharashtra and Gujarat dairy cooperatives supply milk solids for industrial blend formulations.
Cultured Dairy Blends Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. Fermentation science depth and strain banking infrastructure define premium positioning, while commodity volume throughput rewards efficient milk solids procurement and filling-line scale. Three archetypes populate the competitive map: multinational dairy conglomerates with captive R&D infrastructure, regional cooperatives controlling upstream milk supply, and specialized probiotic houses with clinical validation capabilities. Dominant competitive moves include backward integration into milk solids supply and portfolio diversification into plant-based fermentation alternatives.
Within the multinational conglomerate tier, Nestle and Danone occupy positions defined by global distribution reach and fermentation science depth. Lactalis represents scale-driven dairy processing with cooperative-aligned milk sourcing. Among specialized operators, Yakult Honsha Co., Ltd. exemplifies the clinical-validation archetype through strain-specific health positioning. Chobani LLC anchors North American innovation through controlled dairy sourcing and clean-label formulation focus.
| Leading Market Players |
|---|
| Nestle |
| Lactalis |
| Chobani LLC |
| Danone |
| Fonterra Co-operative Group |
| Arla Foods |
| Royal FrieslandCampina |
| Yakult Honsha Co., Ltd. |
| Agropur |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion feeds directly into cultured dairy blend cost structures, amplifying margin pressure for operators dependent on Chinese milk solids imports while enabling New Zealand and EU cooperatives to command premium contract terms for protein and fat inputs.
Pricing Analysis
Long-term offtake agreements dominate industrial procurement between blend manufacturers and dairy cooperatives, insulating volume buyers from spot volatility in milk solids markets. Three-tier pricing structure across premium, standard, and economy levels reflects live culture count thresholds and EFSA health claim validation status. Cost compression in commodity yogurt tiers is intensifying because private-label retailers are consolidating supplier bases. Food service buyers exhibit highest price sensitivity due to thin menu margins, while FOSHU-approved functional positioning commands lowest elasticity in Japanese retail channels.
Supply Chain Analysis
Upstream feedstock availability concentrates in New Zealand, the European Union, and India, where dairy cooperatives control critical protein powder and cream inputs. Industrial blend formulations draw from skim milk solids, milk fat, and specialized starter cultures as primary material inputs. Single-source vulnerability runs through New Zealand's Fonterra-controlled export quotas, which expose blend manufacturers to weather-driven supply disruptions. Distribution runs through temperature-controlled logistics networks serving food processing facilities and retail distribution centers, with ambient-stable beverage formats enabling broader geographic reach through conventional trucking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across the cultured dairy blends landscape as direct-to-subscription models and personalized microbiome services splinter historically consolidated retail channels, creating viable entry points for specialized operators.
For Market Incumbents: Entrench fermentation science capabilities through captive strain banking infrastructure and backward integration into controlled dairy sourcing. Plant-based fermentation substitutes threaten traditional dairy-based volume, making EFSA health claim substantiation investment the critical defensive lever for European shelf access. For New Entrants and Emerging Players: Build out pouch-format snacking portfolios targeting Japanese convenience stores and United States grab-and-go channels where portability commands price premiums. Kefir beverage applications in Germany and Japan represent the most penetrable white-space, with personalized strain-matching subscriptions offering differentiated go-to-market positioning. For Investors and Strategic Acquirers: Clinical-validation specialists with FOSHU-approved strain portfolios and human intervention study archives offer acquisition exposure to Japan's aging-demographic functional foods channel. Monitor EFSA evidentiary standard tightening as the inflection indicator for R&D scale becoming a binding competitive constraint.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Infrastructure | Captive culture collections reduce dependency on external microbiology suppliers and accelerate formulation cycles. |
| EFSA Health Claim Investment | Clinical validation unlocks premium shelf placement and defends against private-label commoditization in European retail. |
| Pouch Packaging Scale-Up | Flexible format adoption penetrates snacking occasions beyond traditional spoonable yogurt consumption patterns. |
| Backward Dairy Integration | Controlled milk solids sourcing insulates margin from New Zealand export quota volatility and weather shocks. |
| Direct-to-Subscription Launch | Recurring revenue models bypass slotting fee structures that favor multinational volume commitments in retail. |
Study Parameters
Operator-level perspectives from fermentation facility managers, dairy cooperative procurement leads, retail category buyers, food service technical directors, and regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through FDA Grade A compliance databases, EFSA health claim registers, FSSAI licensing records, and trade flow data from New Zealand and EU dairy export statistics. Bottom-up volume modeling across production facilities triangulated against top-down demand aggregation from retail channel audits.
Scenario-bracketing framed the analytical approach, with growth projections tested against alternative regulatory tightening trajectories and milk solids supply disruption events across the analysis window. Segmentation dimensions modeled include product type, application context, packaging format, end-user channel, and geographic regulatory cluster. CAGRs derived from historical volume trajectories adjusted for live culture count threshold changes and clean-label reformulation investment cycles. Strain development timelines and EFSA substantiation study costs served as industry-specific forecast inputs.
Practitioners should monitor EFSA evidentiary standard evolution, New Zealand drought frequency, and dual carbon goal enforcement intensity for early signals requiring forecast revision. Cross-checking against Nielsen retail audit data and dairy cooperative export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Non-Dairy Yogurt Market
Dairy Alternatives
United States Dairy Alternatives Market
Dairy Alternatives
A2 Lactose-free Milk Market
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
South Korea Dairy Alternatives Market