
 Oil Storage Sales Market | 2026-2036
Oil Storage Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Storage Sales Market Insights
Aftermarket service revenue is rewriting profit pools across the Oil Storage Sales landscape. Koninklijke Vopak NV leverages its global terminal network to capture recurring maintenance contracts. Kinder Morgan Inc. anchors North American midstream storage with pipeline-integrated tank farms. Buckeye Partners L.P. competes through specialized refined-product terminals along coastal demand corridors.
Oil storage sales encompass the engineering, fabrication, and installation of containment systems for crude oil, refined products, and petrochemical intermediates, with above-ground tanks typically fabricated from carbon steel plate per API 650 standards and rated for atmospheric pressure operation. These structures serve the fundamental purpose of balancing supply chain timing mismatches between production, transport, and consumption. Above Ground Tanks dominate installed capacity due to lower capital intensity and inspection accessibility, while Floating Roof Tanks command premium pricing for volatile crude grades where vapor loss control determines regulatory compliance. Underground Caverns sustain strategic petroleum reserve programs but face extended permitting cycles that constrain near-term deployment.
EPA enforces Spill Prevention, Control, and Countermeasure rules that mandate secondary containment and integrity testing for above-ground storage exceeding threshold volumes. API 653 and API 650 standards govern tank design, fabrication, and in-service inspection protocols that manufacturers must embed to qualify for commercial contracts. OSHA workplace safety requirements and state-level fire codes add jurisdictional layering that shapes regional vendor qualification. Stakeholders must weigh capex cycles against evolving carbon accounting pressures that could reclassify certain storage configurations as stranded assets.
Market Dynamics
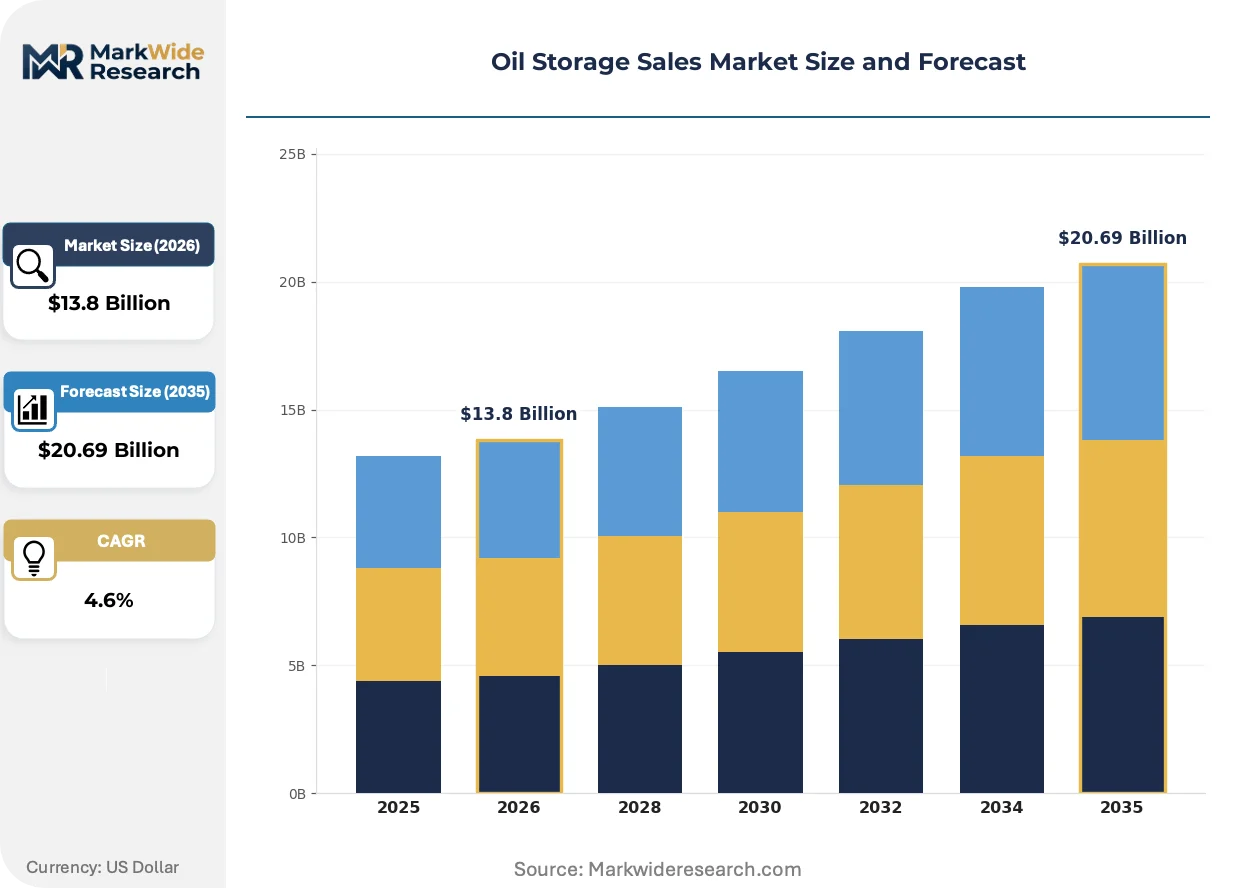
Refinery operators in Asia-Pacific are accelerating capacity additions while EPA spill prevention rules and API 653 inspection standards tighten compliance costs across the installed base. This tension between demand expansion and regulatory burden defines current market trajectory.
Growth Catalysts
- China's Coastal Import Dependency:Crude import concentration in Shandong, Zhejiang, and Guangdong provinces drives terminal construction along deepwater berths. State planners prioritize storage buffer capacity against supply disruption.
- API 650 Standardization:Uniform fabrication protocols reduce engineering redundancy and accelerate tank farm commissioning timelines. Engineering firms embed these specifications into turnkey contracts.
- Floating Roof Adoption:Volatile crude grades from Permian and Bakken formations require vapor recovery systems. Terminal operators specify internal floating roof designs to minimize product loss.
Market Restraints
- Carbon Steel Plate Volatility:Raw material input costs fluctuate with scrap metal and iron ore pricing. Fabricators face margin compression when fixed-price contracts encounter spot market spikes.
- Extended Permitting Cycles:Underground cavern projects for strategic petroleum reserves face multi-year environmental review timelines. Salt dome construction in the US Gulf Coast stalls near-term deployment.
- Secondary Containment Mandates:EPA SPCC rules impose additional civil works and liner system costs. Above-ground tank farms require bund walls and leak detection infrastructure.
Strategic Opportunities
- India's Strategic Reserve Expansion:Padur, Mangalore, and Visakhapatnam caverns offer contract opportunities for engineering-procurement-construction consortia. ISPRL tenders target foreign technology partners.
- Hydrogen Storage Retrofit:Existing crude terminals adapt tankage and piping for ammonia and liquid hydrogen handling. Blending infrastructure repurposes carbon steel assets for energy transition feedstocks.
- Digital Twin Integration:IoT sensor networks and predictive analytics converge with traditional integrity management. API 653 inspection intervals extend through real-time corrosion monitoring.
Industry Challenges
- Welding Inspector Certification:API 653 and ASME Section IX qualification requirements constrain qualified technician supply. Turnaround schedules slip when certified crews are unavailable.
- Legacy Tank Integration:Pre-2000 carbon steel structures require seismic retrofit and bottom replacement. Revamp projects compete with greenfield construction for fabrication yard capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Storage Sales Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $20.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Above Ground Tanks, Underground Caverns, Floating Roof Tanks, Spherical Tanks Technology: Fixed Roof, Internal Floating Roof, External Floating Roof, Vapor Recovery Application: Refinery, Distribution, Transport, End-user Supply End User: Oil Companies, Independent Operators, Contractors, Government Agencies |
| Companies Covered | Koninklijke Vopak NV, Oiltanking GmbH, Vitol Tank Terminals International BV, Buckeye Partners L.P., Kinder Morgan Inc., CST Industries Inc., Shawcor Ltd., Energy Transfer LP, Synalloy Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Storage Sales Market Trends and Innovations
Digitalization and materials science are compressing inspection cycles while regulatory frameworks force vapor emission controls. These shifts favor technology-enabled service providers over pure equipment vendors.
Composite tank liners and advanced coating systems are collapsing traditional maintenance intervals for internal corrosion protection. Refinery operators in the US Gulf Coast specify epoxy and polyurethane linings that extend service life beyond standard recoating cycles. This materials transition reduces out-of-service time during turnaround windows.
EPA SPCC amendments tighten secondary containment and integrity testing thresholds for above-ground storage. Terminal operators must install continuous leak detection and submit certified professional engineer documentation. Midstream companies in Texas and Louisiana absorb civil engineering costs to maintain operating permits.
Buyer consolidation among supermajors and national oil companies concentrates procurement leverage. Integrated operators now bundle storage construction with long-term operating contracts, displacing standalone tank sales. China's Sinopec and CNPC favor engineering-procurement-construction arrangements over equipment-only purchases.
Oil Storage Sales Market Segmentation
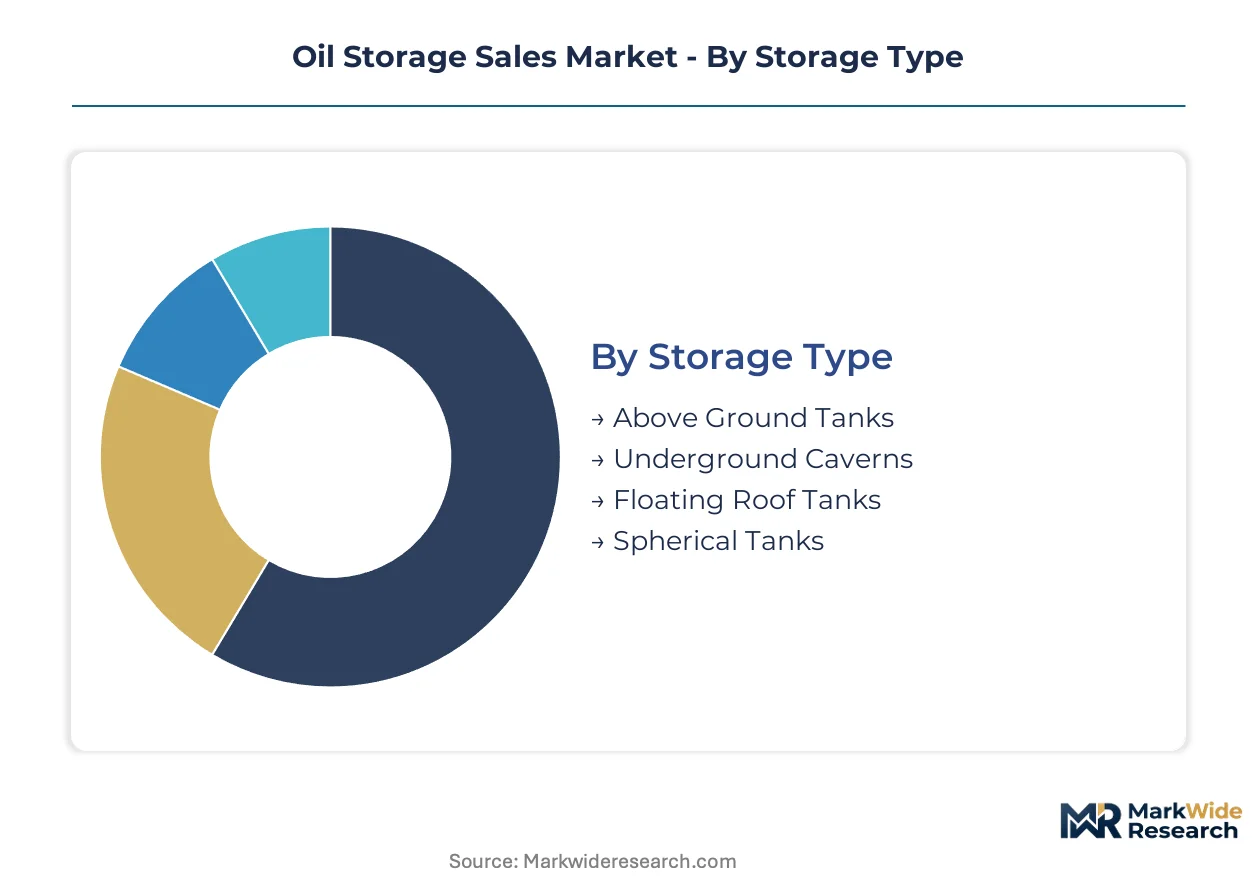
Storage configuration determines capital intensity, inspection protocols, and regulatory exposure for terminal operators. Segment boundaries reflect trade-offs between vapor loss control, seismic resilience, and permitting timelines that shape procurement decisions across crude and refined product handling.
Storage Type:
Cost tier stratification separates atmospheric pressure designs from high-specification containment systems requiring specialized civil works and geological screening.
- Above Ground Tanks:Carbon steel plate structures fabricated to API 650 standards dominate commercial installations due to lower capital intensity and accessible inspection geometry. Refinery operators in Shandong and Guangdong provinces specify these for coastal crude receipt terminals where rapid deployment outweighs land use constraints.
- Underground Caverns:Salt dome and hard rock excavations serve strategic petroleum reserve programs with minimal surface footprint and natural temperature stability. India's ISPRL tenders at Padur and Mangalore attract foreign engineering consortia despite multi-year environmental clearances that compress near-term deployment.
- Floating Roof Tanks:Internal and external floating deck designs cut volatile organic compound emissions from light crude and gasoline storage. Permian Basin terminal operators specify these for Bakken and Eagle Ford feedstocks where vapor recovery mandates tighten.
- Spherical Tanks:Pressure-rated vessels handle liquefied petroleum gas and petrochemical intermediates requiring higher design margins. South Korean refiners deploy these at Daesan and Yeosu complexes for propylene and butane containment.
Above Ground Tanks holds installed capacity. Floating Roof Tanks is rotating up the share rankings.
Technology:
Application-specific vapor management requirements drive technology selection between fixed containment and dynamic roof systems.
- Fixed Roof:Welded steel structures with permanent covers suit non-volatile products like fuel oil and residual streams where vapor pressure remains below regulatory thresholds. Chinese independent refiners in Zhejiang province favor these for heavy crude storage buffers.
- Internal Floating Roof:Pontoon decks suspended within fixed roof shells combine weather protection with emission control. Singapore terminal operators specify these for gasoline and naphtha handling where MEE air quality standards apply.
- External Floating Roof:Open-top designs with peripheral seals expose decks to weather but maximize volume efficiency for large crude tanks. Rotterdam storage clusters use these for Urals and Brent blending operations.
- Vapor Recovery:Vapor collection and compression systems capture tank breathing losses for reinjection or destruction. EPA SPCC amendments in Texas and Louisiana mandate these additions for existing above-ground capacity.
Fixed Roof holds installed capacity. Internal Floating Roof is rotating up the share rankings.
Application:
Customer type concentration varies by supply chain position from production aggregation through final delivery.
- Refinery:On-site tankage balances crude receipt against processing unit throughput with dedicated feedstock segregation. Reliance Industries at Jamnagar operates one of the largest integrated refinery storage complexes globally.
- Distribution:Midstream terminals buffer pipeline batching and marine loading schedules with multi-product segregation. Kinder Morgan's Houston Ship Channel facilities exemplify pipeline-integrated distribution storage.
- Transport:Rail, truck, and barge loading terminals require rapid turnaround tankage with metering and custody transfer infrastructure. Bakken crude rail terminals in North Dakota deploy modular above-ground systems for unit train dispatch.
- End-user Supply:Industrial and utility fuel oil storage serves power generation and manufacturing with just-in-time delivery contracts. Cement producers in Guangdong province maintain dedicated heavy fuel oil tanks for kiln operations.
Refinery holds installed capacity. Distribution is rotating up the share rankings.
End User:
Volume scale and contracting sophistication separate integrated operators from fragmented service providers.
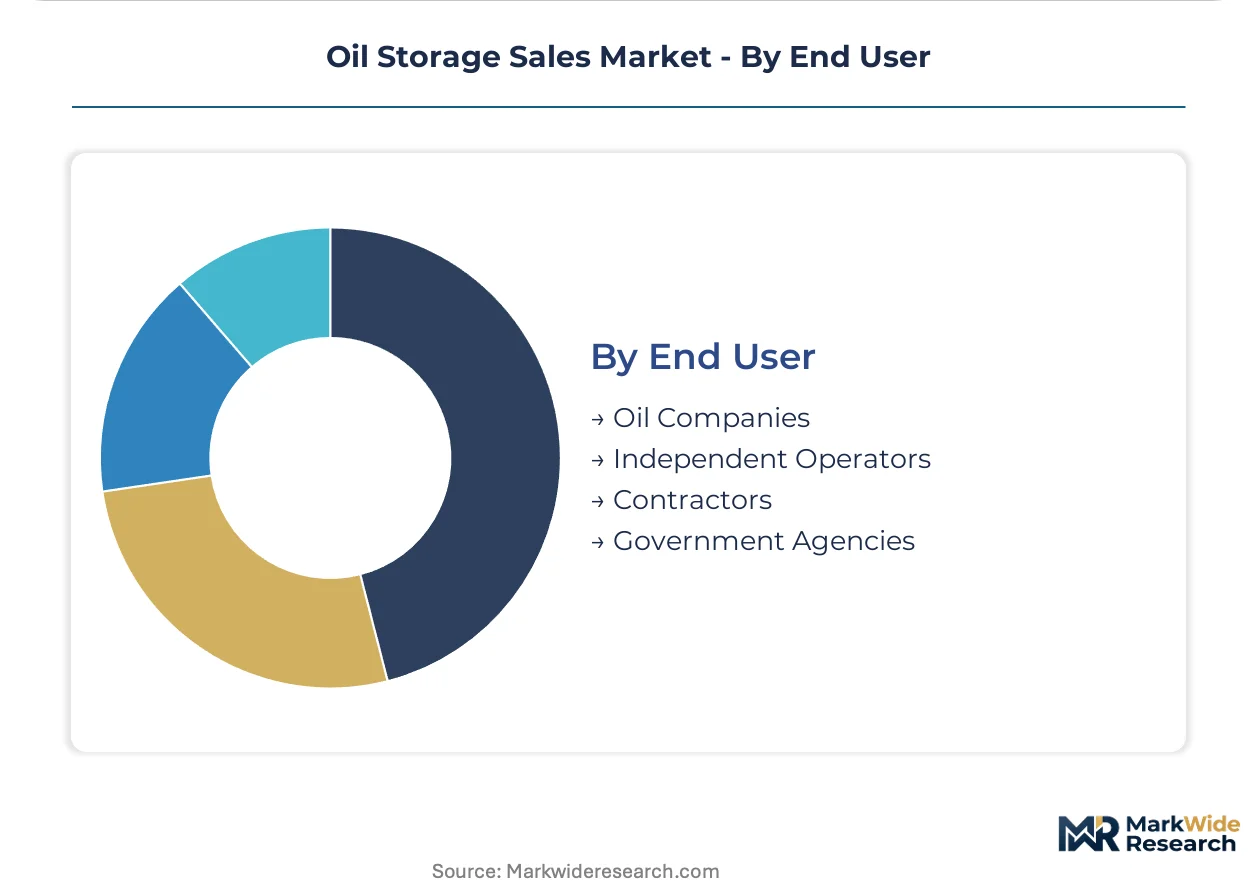
- Oil Companies:Supermajors and national oil companies bundle storage construction with long-term operating contracts, favoring engineering-procurement-construction arrangements over equipment-only purchases. Sinopec and CNPC procurement frameworks in China illustrate this consolidation.
- Independent Operators:Midstream specialists and terminal developers compete on location access and tariff structures without upstream integration. Vopak's global network captures recurring maintenance contracts through terminal operating agreements.
- Contractors:Engineering-procurement-construction firms source tankage as subcontracted scope within larger facility builds. McDermott and Saipem procurement specifications drive API 650 compliance across fabrication yards.
- Government Agencies:Strategic reserve authorities and military fuel commands specify hardened storage with extended design lives and security protocols. India's ISPRL and the US Department of Energy maintain distinct procurement standards from commercial operators.
Oil Companies holds installed capacity. Independent Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in import-dependent coastal markets absorb premium pricing for rapid deployment, while domestic production basins squeeze fabricators on standardized tank specifications. State reserve programs in South Asia and the Middle East prioritize security over cost, creating insulated demand pockets.
United States
Gulf Coast refiners and Permian Basin midstream operators drive above-ground tank orders for crude export terminals. EPA SPCC rules mandate secondary containment upgrades at existing facilities. Houston Ship Channel clusters concentrate fabrication demand for pipeline-integrated storage farms serving Nederland and Corpus Christi loadings.
China
Shandong and Zhejiang province independents expand coastal receipt capacity for Saudi and Russian crude imports. MEE air quality standards tighten vapor recovery requirements at gasoline terminals. Zhoushan and Qingdao port zones anchor the largest greenfield tank farm construction programs globally.
India
ISPRL strategic reserve expansion at Padur and Mangalore caverns attracts foreign engineering consortia. CEA petroleum storage guidelines mandate 90-day import cover buffers. Visakhapatnam and Kochi terminals balance refinery feedstock scheduling against monsoon-disrupted maritime arrivals.
Saudi Arabia
Ras Tanura and Yanbu mega-refineries sustain continuous tankage replacement cycles for aging carbon steel infrastructure. The country's national oil company procurement frameworks favor long-term EPC partnerships over equipment-only purchases. Jubail Industrial City clusters process unit-integrated storage for petrochemical export streams.
Singapore
Jurong Island storage terminals pivot from fuel oil to cleaner product handling amid IMO 2020 marine fuel shifts. The country's national environmental agency enforces stringent VOC emission controls on gasoline and naphtha tanks. Tuas megaport development relocates legacy tank farms, triggering replacement construction.
Oil Storage Sales Market Competitive Landscape
Capability concentration sits with specialized terminal operators holding proprietary integrity management protocols; scale advantage sits with pipeline-integrated midstream giants commanding captive throughput volumes. The market structures around three tiers: global terminal networks capturing recurring service contracts, regional fabricators competing on API 650 compliance velocity, and EPC integrators bundling construction with long-term operations. Dominant competitive moves include hydrogen storage retrofit partnerships and digital twin technology licensing to extend inspection intervals.
Among Dutch-incorporated terminal specialists, Koninklijke Vopak NV exemplifies the service-contract archetype through its global berth network. Kinder Morgan Inc. and Buckeye Partners L.P. occupy positions on the pipeline-integrated vector, anchoring North American midstream storage with contiguous tank farm and transport infrastructure. These three represent contrasting scale-versus-specialization positioning without overlapping customer segments.
| Leading Market Players |
|---|
| Koninklijke Vopak NV |
| Oiltanking GmbH |
| Vitol Tank Terminals International BV |
| Buckeye Partners L.P. |
| Kinder Morgan Inc. |
| CST Industries Inc. |
| Shawcor Ltd. |
| Energy Transfer LP |
| Synalloy Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Shandong tank fabrication yards compresses spot pricing for API 650 standard tanks while simultaneously pressuring fabricators to absorb carbon steel plate volatility. This utilization-driven margin squeeze reshapes supplier consolidation patterns and forces buyers toward bundled engineering-procurement-construction contracts that transfer input risk.
Pricing Analysis
Aftermarket service contracts anchor lifetime value capture for terminal operators seeking to extend tank integrity intervals beyond standard API 653 cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and inspection automation depth. Cost compression in economy-tier carbon steel fabrication intensifies because Shandong independents compete on volume throughput. National oil companies exhibit lowest price sensitivity due to strategic buffer mandates, while independent refiners in Zhejiang province negotiate aggressively on turnkey delivery timelines.
Supply Chain Analysis
Export-control restrictions on advanced welding automation and digital twin software constrain technology transfer to certain strategic reserve programs. Carbon steel plate supply concentrates in China, South Korea, and Japan, with specialty coatings and composite liners sourcing from Germany and the Netherlands. Raw material feeds draw from iron ore pelletizing in Australia and scrap metal recovery in the US Gulf Coast. Single-source vulnerability sits with API-certified welding inspector labor pools concentrated in Texas and Louisiana. Distribution runs through EPC integrators bundling fabrication with long-term terminal operating agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen storage retrofit capability threatens to displace traditional crude tank vendors unable to adapt carbon steel assets for ammonia and liquid hydrogen containment. Incumbents must defend against this substitution arc through materials science investment and energy transition partnerships.
For Market Incumbents: Build regulatory compliance moats around API 653 inspection automation and predictive corrosion monitoring. Acquire certified welding crews in the US Gulf Coast to lock turnaround capacity. Partner with hydrogen technology licensors to repurpose existing tankage for energy transition feedstocks before pure-play competitors capture retrofit demand.
For New Entrants and Emerging Players: Establish a beachhead in India's strategic petroleum reserve cavern construction where ISPRL tenders favor foreign engineering consortia. Target Padur and Mangalore expansion phases where environmental clearance bottlenecks deter incumbent fast-followers. Lead with digital twin integration capabilities that extend inspection intervals and reduce out-of-service windows.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among terminal operators with proprietary integrity management protocols and long-term operating contracts. Terminal networks with hydrogen storage retrofit capabilities and coastal access in import-dependent markets present durable cash flow profiles. Watch for inflection when national oil companies begin bundling hydrogen storage mandates into existing crude terminal procurement frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Storage Retrofit | Repurposes carbon steel tankage for ammonia and liquid hydrogen handling as energy transition feedstocks. |
| Digital Twin Integration | Extends API 653 inspection intervals through real-time corrosion monitoring and predictive analytics. |
| Strategic Reserve Cavern Construction | Captures multi-year engineering-procurement-construction contracts in India's ISPRL expansion program. |
| API 653 Automation Investment | Locks certified welding inspector capacity in Texas and Louisiana turnaround markets. |
| Coastal Terminal Network Expansion | Secures deepwater berth access in China's Shandong and Zhejiang import corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across terminal engineering, fabrication procurement, and integrity management functions. Primary interviews captured perspectives from refinery storage planners at Sinopec and CNPC, EPC contractors specifying API 650 compliance, and terminal operators managing corrosion programs. Secondary validation drew from EPA SPCC rulemaking dockets, API standards documentation, customs data on carbon steel plate trade flows, and FERC filings for midstream storage projects. Bottom-up tank deployment tallies were triangulated against top-down refinery capacity expansion announcements.
Calibration against historical capacity commissioning timelines and regulatory compliance cost trajectories anchored the analytical framework. Segmentation dimensions modeled include storage configuration, vapor management technology, application type, and end-user contracting sophistication. CAGRs were derived from regression analysis of capital expenditure cycles and import dependency ratios. Forecast inputs incorporated carbon steel price volatility indices and environmental permitting duration trends.
Stress conditions across raw material cost spikes, extended environmental clearance timelines, and hydrogen storage substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and energy transition pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Base Oil Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Crude Oil Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Petcoke Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Malaysia Refined Petroleum Products Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Naphtha Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Paraffin Oil Market