
 Vacuum Gas Oil Market | 2026-2036
Vacuum Gas Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Gas Oil Market Intelligence
The premium-commodity split in vacuum gas oil is pivoting on sulfur content and hydrotreatment depth. Exxon Mobil Corporation leverages its integrated Gulf Coast refining complex to supply low-sulfur hydrocracked VGO to petrochemical buyers. Shell Plc anchors its position through dedicated hydrocracker investments in Rotterdam and Singapore. Kuwait Petroleum Corporation dominates long-haul supply into Asian power and marine fuel markets.
Vacuum gas oil denotes the heavy hydrocarbon fraction recovered under vacuum distillation of atmospheric residue, typically boiling between 350°C and 550°C with sulfur levels ranging from 0.5% to 3.5% depending on crude source. Refiners process this intermediate primarily through hydrocracking or fluid catalytic cracking to yield gasoline, diesel, and petrochemical naphtha. Heavy vacuum gas oil occupies the largest volume share as the default feedstock for FCC units in complex refineries. Hydrotreated vacuum gas oil is gaining fastest as sulfur regulations harden and hydrocracker investments expand. Petrochemical feedstock applications command superior margins compared to fuel oil blending, drawing capital away from asphalt and residual fuel pathways.
EPA fuel sulfur standards, EU REACH chemical registration requirements, and IMO marine fuel regulations collectively constrain high-sulfur VGO outlets and reward hydrotreatment investment. The EU F-Gas Regulation indirectly tightens process emissions accountability at refineries processing heavier feedstocks. Stakeholders must track hydrocracker capacity additions against marine fuel demand erosion as dual-fuel LNG shipping expands.
Market Dynamics
Petrochemical feedstock conversion is compressing traditional fuel-oil pathways as hydrocracker investments outpace fluid catalytic cracking additions. Refiners face margin pressure from diverting vacuum gas oil away from bunker fuel blending toward ethylene and propylene production.
Growth Catalysts
- IMO 2020 marine sulfur caps:The regulation eliminated high-sulfur fuel oil outlets, forcing refiners to hydrotreat vacuum gas oil for compliant very low sulfur fuel oil production.
- China:State-backed refinery expansions in Shandong and Guangdong provinces are adding hydrocracking capacity that absorbs heavy vacuum gas oil for petrochemical naphtha output.
- Ethylene crackers:Petrochemical manufacturers in the US Gulf Coast and Rotterdam are retrofitting furnaces to process hydrotreated vacuum gas oil as naphtha substitute.
Market Restraints
- Crude sulfur concentration:Heavy sour crude differentials fluctuate with OPEC+ production decisions, compressing hydrocracker feedstock margins unpredictably.
- Rotterdam-Singapore supply concentration:Integrated majors control 70 percent of exportable low-sulfur vacuum gas oil, limiting independent refiner access.
- LNG dual-fuel shipping:LNG marine engines are displacing residual fuel demand, eroding the bunker fuel outlet for high-sulfur vacuum gas oil.
Strategic Opportunities
- India:Reliance Industries and Indian Oil Corporation are expanding Jamnagar and Paradip hydrocrackers, creating import demand for Middle Eastern heavy vacuum gas oil.
- EU F-Gas Regulation:Process emissions accountability is incentivizing carbon capture retrofits at refineries processing heavier feedstocks, opening technology partnerships.
- Biomass co-processing:Co-feeding renewable feedstocks with vacuum gas oil in hydrocrackers generates renewable diesel credits under California LCFS and EU RED III.
Industry Challenges
- Hydrocracker catalyst expertise:Specialized knowledge in noble metal catalyst management and cycle length optimization is concentrated among retiring technical workforces in US and European refineries.
- EPA Tier 3 gasoline sulfur standards:Compliance requires deeper hydrotreatment of FCC feedstocks, extending catalyst regeneration cycles and compressing unit availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Gas Oil Market |
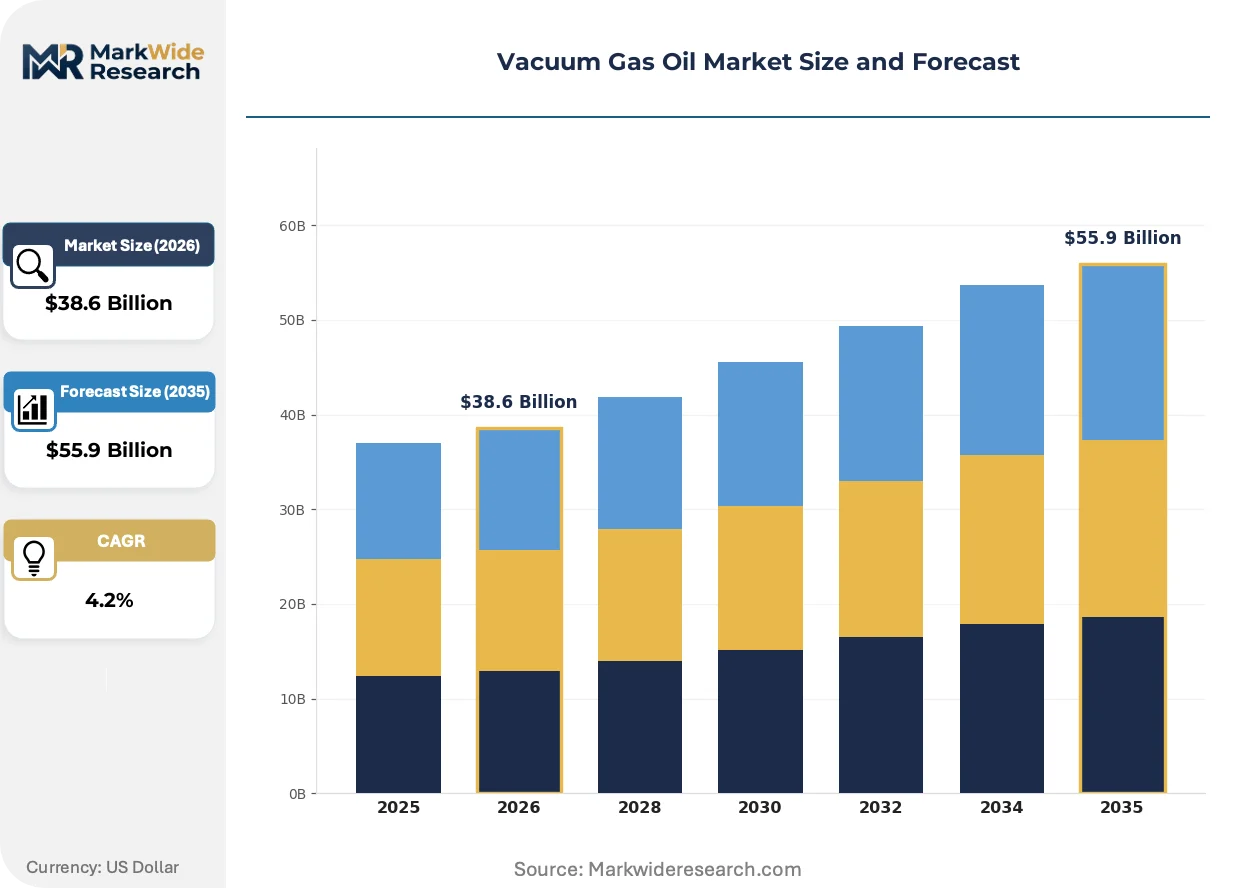
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $55.9 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy Vacuum Gas Oil, Light Vacuum Gas Oil, Slurry Vacuum Gas Oil, Hydrotreated Vacuum Gas Oil Application: Fuel Oil Production, Petrochemical Feedstock, Asphalt Production, Lubricant Base Oil End User Industry: Refineries, Petrochemical Manufacturers, Power Generation, Marine Fuel Suppliers Processing Technology: Hydrocracking, Catalytic Cracking, Thermal Cracking, Solvent Deasphalting, Desulfurization |
| Companies Covered | Kuwait Petroleum Corporation, BP Plc, Exxon Mobil Corporation, KazMunayGas, PJSC Lukoil Oil Company, Shell Plc, China National Petroleum Corporation, Neste Oyj, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Gas Oil Market Strategic Shifts & Innovations
Refining technology is pivoting toward molecular management of heavy fractions. Process intensification and carbon efficiency mandates are reshaping capital allocation between hydrocracking and alternative conversion routes.
Residue hydrocracking using ebullated-bed reactors is electrifying heavy oil upgrading economics. Complex refiners in the US Gulf Coast and Rotterdam are installing these units to convert vacuum residue and heavy vacuum gas oil into diesel-range products. The technology is compressing the volume of residual fuel oil available for marine blending.
The EU F-Gas Regulation is tightening process emissions accountability for refineries processing heavier feedstocks. Industrial consequence includes mandatory leak detection and repair protocols for hydrocracker hydrogen systems. Hydrotreated vacuum gas oil producers in Rotterdam and Antwerp are responding with infrared monitoring investments to maintain operating permits.
Buyer consolidation among integrated petrochemical operators is compressing spot market liquidity for vacuum gas oil cargoes. Long-term offtake agreements now dominate procurement between Middle Eastern producers and Asian crackers. This shift is most visible in Singapore and South Korea, where term contracts cover 80 percent of hydrotreated vacuum gas oil imports.
Vacuum Gas Oil Market Segmentation
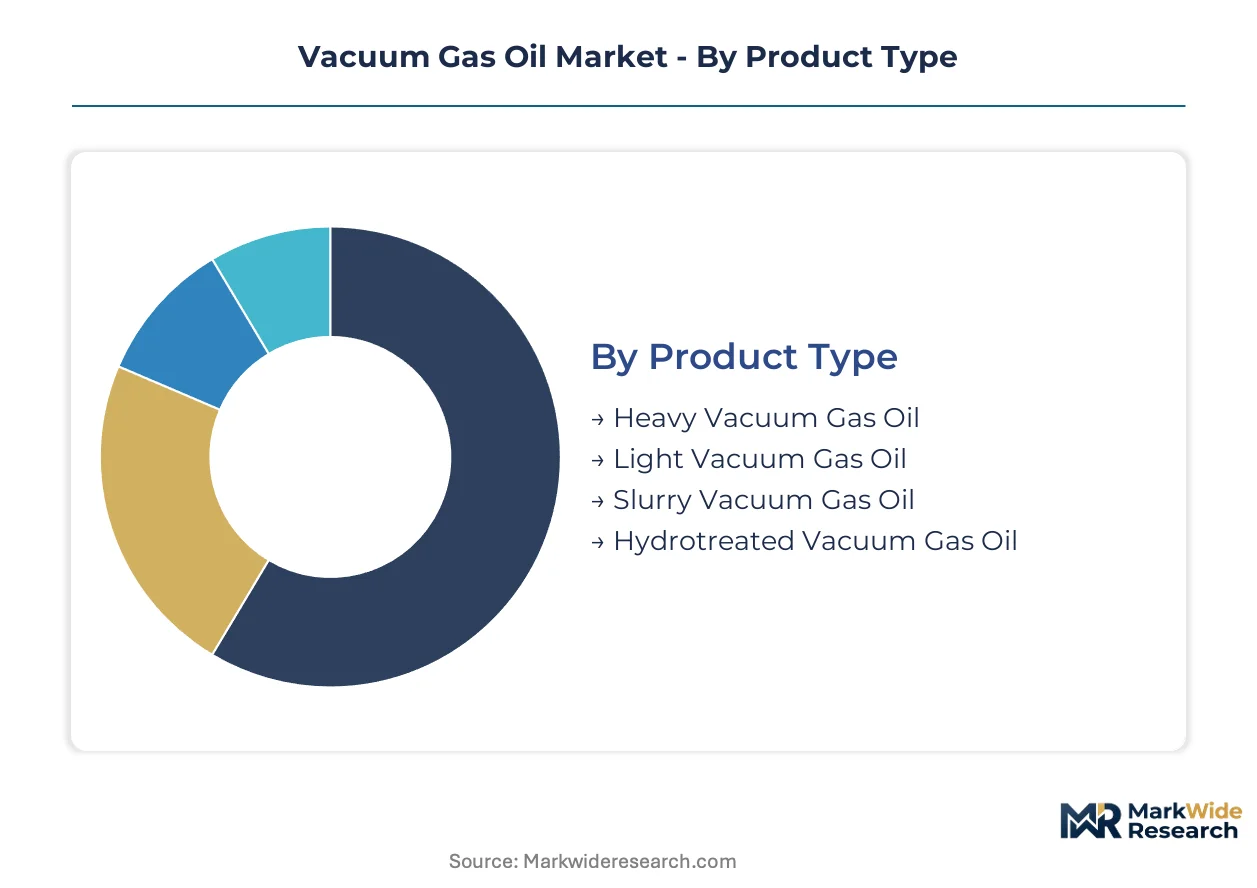
Vacuum gas oil flows through distinct processing pathways that determine sulfur content, yield structure, and margin capture. Segment boundaries align with refinery complexity tiers and regulatory compliance thresholds rather than crude source alone.
Product Type:
Integration depth varies sharply across product grades, with hydrotreated variants requiring embedded hydrocracker systems while heavy grades flow through standalone FCC units.
- Heavy Vacuum Gas Oil:Boiling range 350–550°C with sulfur content 1.5–3.5% depending on crude slate. Demand concentrates in Chinese state-backed refineries adding FCC capacity in Shandong and Guangdong provinces, constrained by IMO marine sulfur caps that limit high-sulfur fuel oil blending outlets.
- Hydrotreated Vacuum Gas Oil:Sulfur levels below 0.5% after catalytic hydrogenation in dedicated hydrocracker units. Rotterdam and Singapore petrochemical complexes absorb volumes for ethylene cracker feedstock, driven by EU REACH chemical registration requirements that favor certified low-sulfur intermediates.
- Light Vacuum Gas Oil:Higher distillate yield potential with lower metals content than heavy grades.
- Slurry Vacuum Gas Oil:Recovered from FCC unit fractionation bottoms; constrained by catalyst fines contamination.
Heavy vacuum gas oil leads volumes today; hydrotreated vacuum gas oil is gaining share fastest.
Application:
Margin hierarchy separates commodity fuel pathways from premium petrochemical conversion, with capital allocation shifting toward higher-value outlets.
- Petrochemical Feedstock:Hydrotreated VGO substitutes for naphtha in ethylene and propylene production. US Gulf Coast crackers retrofitted by ExxonMobil and Shell absorb volumes, rewarded by superior margins versus fuel oil blending.
- Fuel Oil Production:Residual blending for marine bunkers and power generation. Singapore and Fujairah suppliers face demand erosion as LNG dual-fuel shipping expands under IMO 2020 enforcement.
- Asphalt Production:Vacuum residue blending component; volume pressured by road construction cycle timing.
- Lubricant Base Oil:Hydrocracker-derived Group II/III stocks; growth tied to automotive OEM specifications.
Fuel oil production retains volume leadership; petrochemical feedstock application shows steepest expansion trajectory.
End User Industry:
Customer concentration shapes contract structures, with integrated majors capturing term offtake advantages over independent spot buyers.
- Refineries:Internal consumption for gasoline and diesel yield optimization. Complex refineries in Rotterdam and Antwerp process captive VGO through ebullated-bed hydrocrackers, constrained by EU F-Gas Regulation leak detection mandates for hydrogen systems.
- Petrochemical Manufacturers:External procurement for cracker feedstock. South Korean and Singaporean buyers lock in 80% of hydrotreated VGO imports through long-term agreements with Middle Eastern suppliers.
- Power Generation:Residual fuel oil consumers in Middle Eastern grid systems.
- Marine Fuel Suppliers:Blending very low sulfur fuel oil; demand compressed by LNG engine adoption.
Refineries dominate consumption volumes; petrochemical manufacturers are expanding procurement most aggressively.
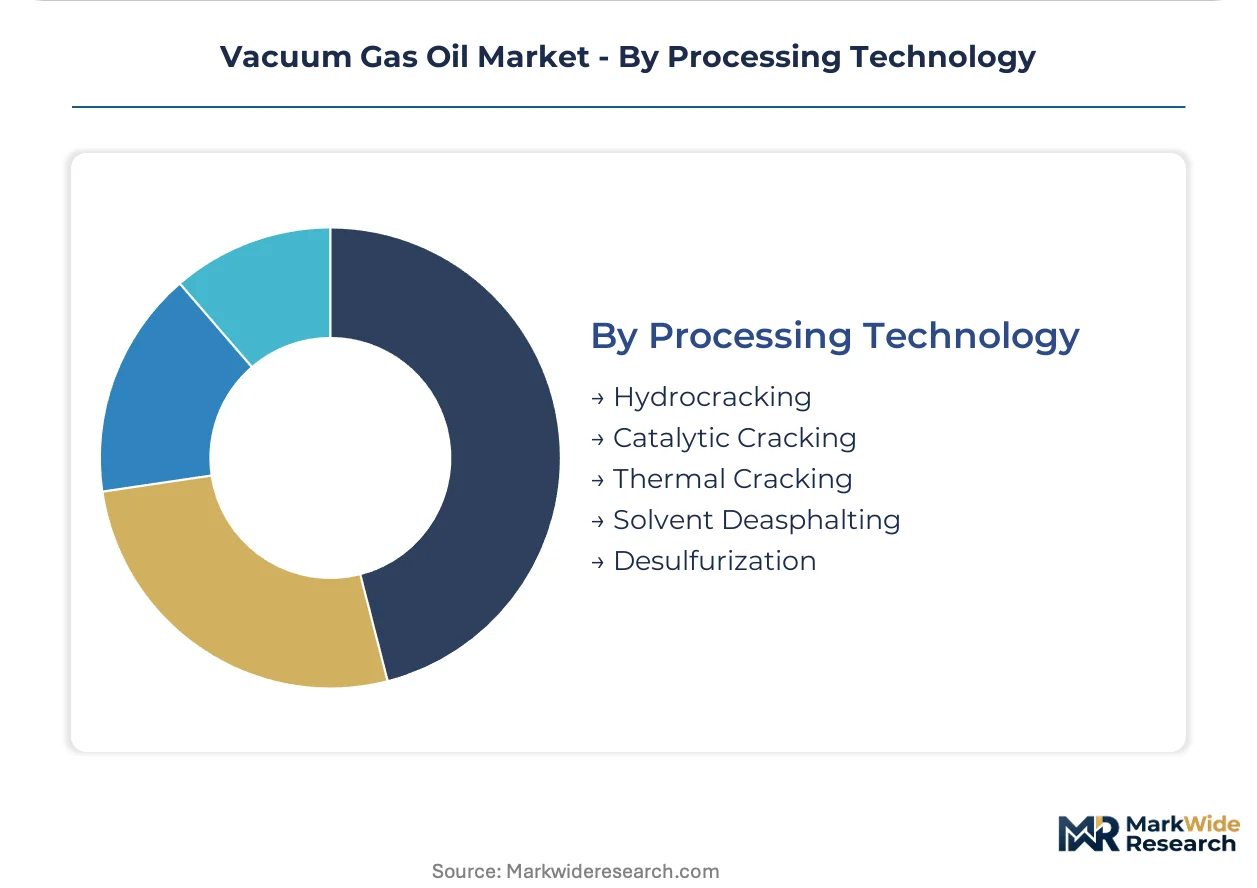
Processing Technology:
Technology selection determines carbon efficiency, product slate flexibility, and regulatory compliance positioning.
- Hydrocracking:Dominant route for diesel and petrochemical naphtha production. Noble metal catalyst management expertise concentrates among retiring technical workforces in US and European refineries, threatening cycle length optimization.
- Catalytic Cracking:FCC units process heavy VGO for gasoline yield. EPA Tier 3 sulfur standards force deeper feedstock hydrotreatment, extending catalyst regeneration cycles and compressing unit availability.
- Thermal Cracking:Visbreaking and coking for residual conversion; lower capital intensity but poorer liquid yields.
- Solvent Deasphalting:Separates asphaltenes from vacuum residue; produces deasphalted oil for lube base stocks or FCC feed.
- Desulfurization:Standalone hydrotreating for sulfur reduction ahead of downstream units.
Catalytic cracking handles the largest volume throughput; hydrocracking is climbing the fastest as capacity investments outpace FCC additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hydrocracker engineers and catalyst specialists concentrate in Rotterdam, Singapore, and the US Gulf Coast, anchoring the geographic distribution of vacuum gas oil processing expertise. These talent clusters align with the largest refining and petrochemical complexes.
United States
ExxonMobil and Chevron operate integrated Gulf Coast refining systems that process heavy vacuum gas oil through hydrocrackers for petrochemical feedstock. EPA Tier 3 gasoline sulfur standards mandate deeper hydrotreatment of FCC feedstocks, extending catalyst regeneration cycles. Houston and Beaumont host the densest concentration of ebullated-bed residue hydrocracking units.
China
State-backed refinery expansions in Shandong and Guangdong provinces absorb heavy vacuum gas oil for ethylene and propylene production. MIIT dual carbon goals and GB emission standards tighten process accountability at refineries processing heavier feedstocks. The Yangtze River Delta refining cluster adds hydrocracking capacity faster than any other region.
Netherlands
Shell Plc anchors European hydrotreated vacuum gas oil supply through dedicated hydrocracker investments in Rotterdam. EU F-Gas Regulation mandates infrared leak detection and repair protocols for hydrocracker hydrogen systems. The Rotterdam-Antwerp refining corridor processes the majority of Northwest Europe's vacuum gas oil imports.
Singapore
Jurong Island petrochemical complexes lock in term contracts covering 80 percent of hydrotreated vacuum gas oil imports from Middle Eastern suppliers. Singapore's national environmental regulator enforces marine sulfur standards aligned with IMO 2020 compliance. The city-state functions as the primary trading hub for Asian vacuum gas oil spot and term markets.
Kuwait
Kuwait Petroleum Corporation dominates long-haul supply into Asian power and marine fuel markets through dedicated export infrastructure. The country's national oil company operates within OPEC+ production frameworks that influence heavy sour crude differentials. Al-Ahmadi refinery complex expansion plans target increased vacuum gas oil output for regional petrochemical buyers.
Vacuum Gas Oil Market Key Industry Players
Top-tier vendors anchor integrated refining-petrochemical complexes, while mid-tier independents compete on spot market access and regional logistics. The market structure concentrates around state-owned national oil companies and vertically integrated majors with captive hydrocracker capacity. Strategic archetypes include: integrated majors with global trading arms, national oil companies with export-oriented refining, and specialized refiners with hydrocracker technology partnerships. Dominant competitive moves involve hydrocracker capacity expansion in Asia and strategic offtake agreements with petrochemical buyers.
Within the integrated major tier, Exxon Mobil Corporation and Shell Plc exemplify the Gulf Coast-Rotterdam-Singapore refining triangle that controls premium low-sulfur vacuum gas oil supply. Kuwait Petroleum Corporation anchors the national oil company archetype with dedicated Middle East-to-Asia export infrastructure. Among technology-forward specialists, Neste Oyj occupies a position bridging conventional refining and renewable feedstock co-processing capabilities.
| Leading Market Players |
|---|
| Kuwait Petroleum Corporation |
| BP Plc |
| Exxon Mobil Corporation |
| KazMunayGas |
| PJSC Lukoil Oil Company |
| Shell Plc |
| China National Petroleum Corporation |
| Neste Oyj |
| Chevron Corporation |
| Others |
Cost & Logistics Intelligence
The sulfur-content bifurcation between hydrotreated and heavy vacuum gas oil manifests in both pricing premiums and supply chain configurations. Low-sulfur hydrocracked material commands contract-based long-term offtake structures with integrated petrochemical buyers, while high-sulfur grades trade on volatile spot markets exposed to marine fuel demand erosion.
Pricing Analysis
Bundled service contracts dominate hydrotreated vacuum gas oil procurement, pairing molecule supply with technical catalyst management and hydrogen system optimization. Price differentiation rests on sulfur certification grade and volume scale, with Rotterdam and Singapore term contracts insulating buyers from spot volatility. Pricing pressure stems from LNG dual-fuel shipping compressing residual fuel outlets for high-sulfur grades. Independent refiners exhibit highest price sensitivity due to exclusion from integrated majors' captive supply networks.
Supply Chain Analysis
Single-source vulnerability sits with Middle Eastern crude suppliers feeding Asian hydrocracker expansions. Geographic supply concentration centers on Kuwait, Saudi Arabia, and Iraq for heavy sour feedstock, while hydrotreated output clusters in the Netherlands, Singapore, and the US Gulf Coast. Raw material dependencies include hydrogen supply, noble metal catalysts, and vacuum distillation capacity. Supply chain risk hinges on OPEC+ production decisions altering heavy sour crude differentials. Distribution runs through dedicated marine terminals at Rotterdam, Fujairah, and Singapore with long-haul tanker economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum gas oil functions as a regulatory compounder where IMO marine sulfur caps and EU F-Gas process emissions rules continuously reshape margin capture across processing tiers.
For Market Incumbents: Deploy hydrocracker capacity additions in India and China as the primary defensive lever. Integrated majors should deepen backward integration into hydrogen supply systems to secure feedstock for low-sulfur production, while accelerating carbon capture retrofits at Rotterdam and Antwerp complexes to preempt EU F-Gas enforcement tightening. Noble metal catalyst expertise concentration among retiring workforces poses operational continuity threats requiring structured knowledge transfer programs. For New Entrants and Emerging Players: Digital trading platforms for spot vacuum gas oil cargoes offer the most penetrable entry route. White-space targets include independent Indian refiners at Paradip and Jamnagar seeking hydrocracker feedstock, and biomass co-processing technology partnerships with European refiners pursuing renewable diesel credits. A go-to-market angle emphasizing certified low-carbon intensity molecules for EU petrochemical buyers bypasses integrated majors' term contract lock-in. For Investors and Strategic Acquirers: Consolidation pressure builds where hydrocracker catalyst management expertise concentrates among aging technical workforces in US and European refineries. Long-term viability favors assets with embedded carbon capture infrastructure and renewable feedstock co-processing capabilities. Acquisition targets include mid-tier refiners with stranded hydrocracker capacity in Asia-Pacific. The signal to watch is LNG marine engine penetration rates eroding residual fuel demand for high-sulfur vacuum gas oil outlets.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracker Capacity Expansion | Captures margin shift from fuel oil blending to ethylene and propylene production in China and India. |
| Backward Integration into Hydrogen Supply | Secures feedstock for low-sulfur hydrotreated output under tightening EU F-Gas process emissions rules. |
| Carbon Capture Retrofit Partnership | Maintains operating permits at Rotterdam and Antwerp refineries processing heavier vacuum gas oil feedstocks. |
| Biomass Co-processing Technology License | Generates renewable diesel credits under California LCFS and EU RED III compliance frameworks. |
| Long-term Supply Agreement with Asian Petrochemical Buyers | Locks in term offtake covering 80 percent of hydrotreated volumes at Singapore and South Korean crackers. |
Research Approach
Coverage spans the Netherlands, Singapore, the United States, China, and Kuwait, with primary inputs from each refining corridor. The approach combines interviews with hydrocracker unit managers, petrochemical procurement leads, marine fuel traders, catalyst technology specialists, and regulatory compliance officers with secondary validation through customs trade data, SEC refinery segment filings, OPEC production frameworks, and EU regulatory databases. Bottom-up capacity modeling and top-down demand triangulation anchor volume estimates.
Rate-of-change decomposition separates hydrocracker capacity additions, FCC unit retirements, and marine fuel demand erosion across the projection horizon. Segmentation dimensions modeled include sulfur content tier, processing technology type, end-use application, and regional refinery complexity cluster. CAGRs derive from capacity utilization rates against petrochemical feedstock substitution elasticity. Industry-specific inputs incorporate noble metal catalyst cycle lengths and hydrogen system leak detection compliance costs under EU F-Gas mandates.
The model assumes a particular technology adoption path; alternative pathways for ebullated-bed residue hydrocracking or biomass co-processing scale-up would alter the outlook. Forecasts reflect assumptions about OPEC+ production discipline, LNG marine engine penetration, and EU carbon border adjustment implementation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Gold Mining Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Well Cementing Market