
 India White Oil Market | 2026-2036
India White Oil Market Size, Share, and Industry Trends Forecast 2026-2036
India White Oil Market Foresight
The Bureau of Indian Standards (BIS) revision of IS 335 for liquid paraffin is pivoting domestic refiners toward higher viscosity index grades and lower sulfur residues. Indian Oil Corporation Ltd leverages its Panipat and Vadodara refining complexes to sustain captive feedstock advantages for white oil distillation. Gandhar Oil Refinery (India) Ltd anchors its position through specialized hydrofinishing capabilities tailored to cosmetic and pharmaceutical off-take. Savita Oil Technologies Ltd competes on technical service depth, embedding formulation support teams directly with Mumbai-based personal care manufacturers.
White oil denotes a highly refined, colorless, odorless, and tasteless mineral oil produced through severe hydrotreating or acid-clay treatment of distillate fractions, achieving UV absorbance specifications critical for skin-contact and ingestion applications. Its primary commercial purpose spans cosmetic emollients, pharmaceutical laxatives and ointment bases, food machinery lubricants, and polymer processing aids where regulatory purity thresholds exclude conventional lubricant stocks. Mineral oil retains the dominant share of product type revenue given entrenched supply chains and cost structures, though synthetic oil variants command premium positioning in pharmaceutical aerosol and high-temperature food equipment segments where oxidative stability requirements exceed paraffinic feedstock limits. The cosmetics application segment channels the steepest volume growth as Indian beauty and personal care brands reformulate toward "clean label" positioning that relies on NF/USP-grade white petrolatum for barrier and emollient claims.
BIS grading protocols, CDSCO drug substance monographs, and FSSAI food-grade lubricant notifications collectively determine market access thresholds and product differentiation possibilities for domestic and imported white oils. Compliance costs escalate disproportionately for smaller blenders lacking in-house analytical infrastructure for polycyclic aromatic hydrocarbon and heavy metal certification. Stakeholders must monitor the convergence of BIS standards with REACH-aligned impurity limits, as European export eligibility increasingly shapes investment priorities for Indian refiners serving multinational pharmaceutical and cosmetics accounts.
Market Dynamics
CDSCO's tightening pharmaceutical-grade purity benchmarks are forcing domestic refiners to upgrade hydrofinishing infrastructure, compressing margins for mid-scale blenders while rewarding integrated producers with captive hydrogen supply.
Growth Catalysts
- Pharmaceutical-grade demand:CDSCO monograph revisions for liquid paraffin laxatives and ointment bases are pulling technical-grade refiners toward USP/NF certification investments.
- FSSAI food lubricant mandates:Institutional bakery and confectionery procurement now requires documented food-grade white oil compliance, locking out uncertified suppliers from institutional channels.
- Gujarat refining corridor concentration:Pipeline-connected hydrogen and sulfur recovery infrastructure at Vadodara and Jamnagar clusters enables cost-competitive hydrofinishing at scale.
Market Restraints
- Base oil feedstock volatility:Paraffinic distillate availability fluctuates with Indian Oil Corporation's transport fuel priority scheduling, creating white oil production scheduling uncertainty.
- Import dependency for specialty grades:High-viscosity cosmetic and pharmaceutical aerosol grades rely on Korean and Singaporean supply, exposing blenders to freight and currency risk.
- PAH analytical infrastructure gaps:Polycyclic aromatic hydrocarbon certification to BIS 335 limits requires capital-intensive UV fluorescence equipment unavailable to regional blenders.
Strategic Opportunities
- Maharashtra personal care manufacturing:Mumbai-Thane cosmetic formulation clusters lack embedded technical service support, creating openings for white oil suppliers with in-house formulation laboratories.
- PLI scheme alignment:Pharmaceutical active ingredient production incentives under the Production Linked Incentive scheme expand domestic API output, lifting excipient-grade white oil offtake.
- Synthetic-naphthenic hybrid development:Convergence of Group III base oil hydrocracking with gas-to-liquids Fischer-Tropsch wax addresses high-temperature food equipment oxidative stability gaps.
Industry Challenges
- Hydrofinishing catalyst expertise scarcity:Sulfur and nitrogen guard bed management requires specialized process engineering talent concentrated at Reliance and Indian Oil Corporation facilities.
- Multi-registrar certification timelines:Simultaneous BIS, CDSCO drug master file, and FSSAI food-grade lubricant approvals extend product launch cycles by 18-24 months.
- Legacy batch blending system integration:Automated in-line blending investments face retrofit complexity at family-owned regional refineries operating acid-clay treatment trains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India White Oil Market |
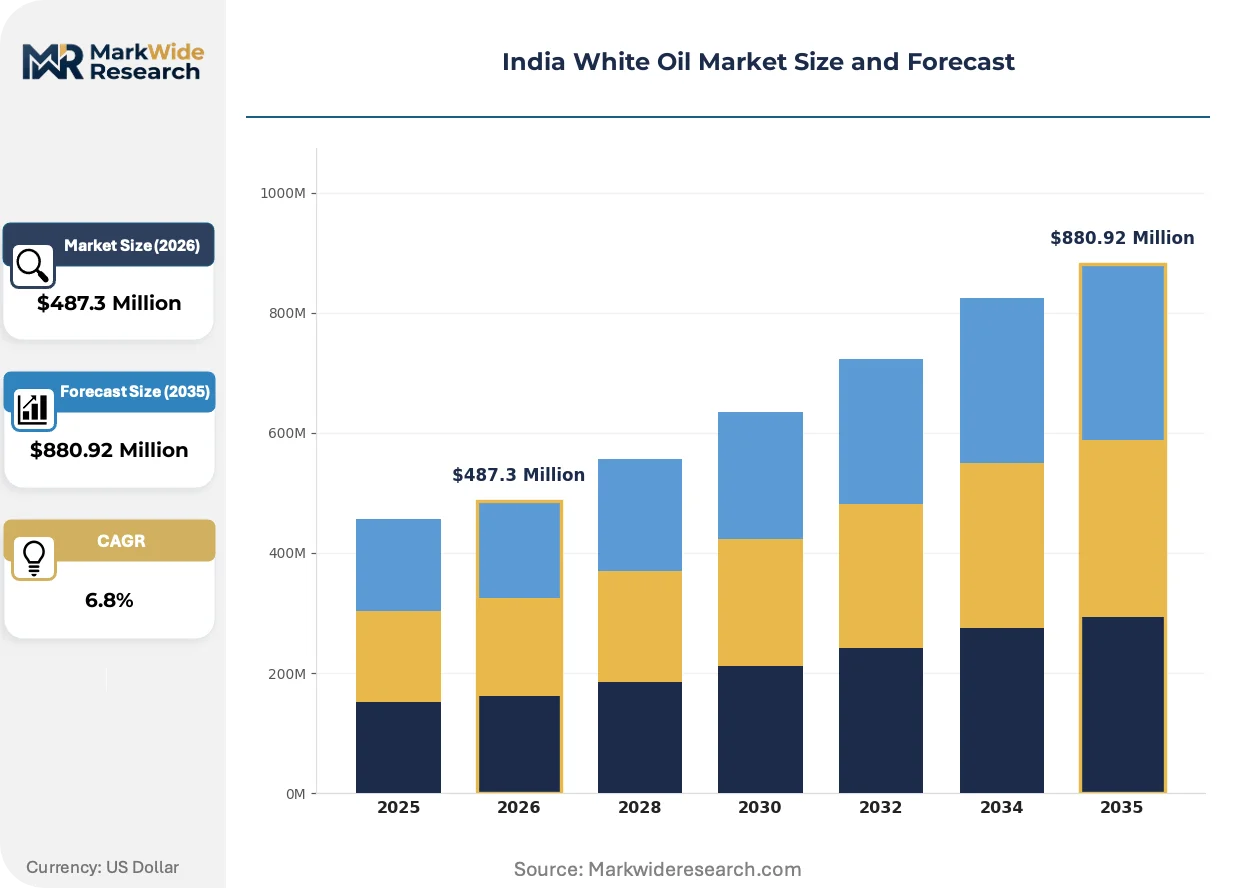
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, White Petrolatum, Paraffin Oil Application: Cosmetics, Pharmaceuticals, Food Industry, Industrial Lubricants End User: Beauty & Personal Care, Food Processing, Healthcare, Manufacturing Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Indian Oil Corporation Ltd, Raj Petro Specialities Pvt. Ltd, Gandhar Oil Refinery (India) Ltd, Columbia Petro Chem Pvt. Ltd, ExxonMobil Corp, Savita Oil Technologies Ltd, Bharat Petroleum Corporation Limited, Shell plc, Apar Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India White Oil Market Shifts & Advancements
Hydroprocessing technology advancement and regulatory convergence are compressing the technical gap between pharmaceutical, cosmetic, and food-grade specifications, forcing suppliers to pursue multi-certification rather than single-segment specialization.
Membrane separation technology is integrating into white oil finishing trains as a sulfur and aromatic polishing step downstream of hydrotreaters. Gandhar Oil Refinery and Savita Oil Technologies are piloting ceramic membrane modules at Gujarat facilities to reduce clay filtration waste volumes. This integration is enabling simultaneous compliance with BIS 335, USP, and REACH-aligned PAH limits without separate processing lines.
FSSAI's 2023 food-grade lubricant notification is mandating H1 registration for all machinery oils with incidental food contact, extending beyond prior voluntary NSF certification. Bakery and dairy equipment manufacturers now require documented H1 white oil supply chains, disqualifying technical-grade suppliers from original equipment specification. Maharashtra and Karnataka food processing clusters are experiencing the fastest compliance transition, with institutional buyers rejecting non-H1 documentation.
Personal care brands are consolidating supplier relationships around technical service depth rather than transactional commodity supply. Mumbai-based cosmetic manufacturers now expect embedded formulation support for emulsion stability testing and regulatory dossier preparation. This reconfiguration favors white oil suppliers with captive laboratory infrastructure over trading intermediaries, compressing distributor margins in the western India supply corridor.
India White Oil Market Segmentation
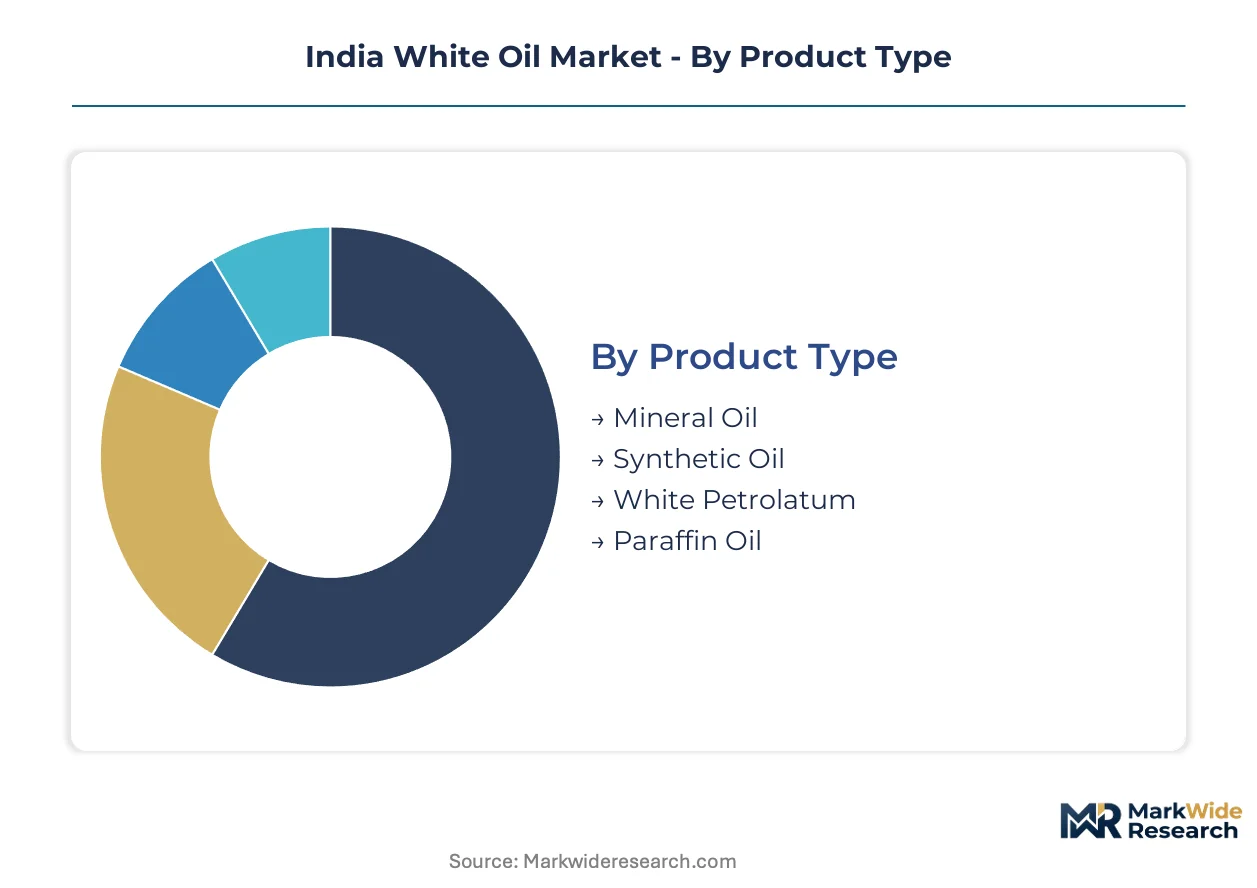
White oil segmentation in India reflects divergent certification burdens across product grades and end-use channels. Each segment demands distinct BIS, CDSCO, or FSSAI compliance pathways that shape supplier economics and customer procurement patterns.
Product Type:
Mineral oil and synthetic variants carry fundamentally different certification loads — paraffinic mineral oils require BIS 335 alignment plus CDSCO drug master files for pharmaceutical use, while synthetic grades face additional REACH-aligned PAH scrutiny for cosmetic aerosol applications.
- Mineral Oil:Refined paraffinic distillate processed through severe hydrotreating or acid-clay treatment to achieve colorless, odorless, tasteless specifications with UV absorbance limits critical for skin-contact applications. Demand concentrates in Gujarat's pharmaceutical formulation corridor, where CDSCO monograph compliance for liquid paraffin laxatives and ointment bases pulls technical-grade refiners toward USP/NF certification investments.
- Synthetic Oil:Group III hydrocracked or gas-to-liquids Fischer-Tropsch derived fluids delivering superior oxidative stability for high-temperature food equipment and pharmaceutical aerosol propellants. Maharashtra cosmetic manufacturers command premium positioning for these grades, though Korean and Singaporean import dependency exposes blenders to freight and currency volatility.
- White Petrolatum:Semi-solid hydrocarbon mixture meeting NF/USP purity thresholds for barrier and emollient claims in clean-label personal care formulations.
- Paraffin Oil:Lower viscosity liquid paraffin grades serving industrial polymer processing and textile lubrication with reduced regulatory burden.
Leading the category by volume: Mineral Oil. Growing fastest: Synthetic Oil.
Application:
Application segments separate by margin structure — pharmaceutical and cosmetic channels reward certification depth with pricing power, while industrial lubricants compete on volume throughput with thinner compliance requirements.
- Cosmetics:Steepest volume expansion as Indian beauty brands reformulate toward clean-label positioning reliant on NF/USP-grade white petrolatum for barrier claims. Mumbai-Thane formulation clusters now expect embedded technical service support for emulsion stability testing, favoring suppliers with captive laboratory infrastructure over trading intermediaries.
- Pharmaceuticals:CDSCO monograph revisions for liquid paraffin laxatives and ointment bases are compressing margins for mid-scale blenders lacking hydrofinishing upgrades while rewarding integrated producers with captive hydrogen supply at Panipat and Vadodara refining complexes.
- Food Industry:FSSAI's H1 registration mandate for machinery oils with incidental food contact now disqualifies technical-grade suppliers from original equipment specifications in Maharashtra and Karnataka dairy and bakery equipment channels.
- Industrial Lubricants:Polymer processing aids and textile lubrication applications where regulatory purity thresholds exclude conventional lubricant stocks but permit lower certification grades.
Dominating application revenue: Cosmetics. Expanding most quickly: Pharmaceuticals.
End User:
End-user concentration maps to India's manufacturing geography — western states anchor personal care and pharmaceutical demand, while food processing pulls toward southern and western agricultural belts.
- Beauty & Personal Care:Mumbai-based cosmetic manufacturers consolidate supplier relationships around formulation support depth rather than transactional commodity supply, compressing distributor margins in the western India supply corridor.
- Food Processing:Institutional bakery and confectionery procurement now requires documented H1 white oil compliance, locking out uncertified suppliers from Maharashtra and Karnataka institutional channels.
- Healthcare:Hospital and clinic procurement of pharmaceutical-grade liquid paraffin for laxative and topical applications tied to CDSCO drug substance monographs.
- Manufacturing:Polymer, textile, and general industrial lubrication buyers prioritizing cost over certification tier.
Largest end-user segment by volume: Beauty & Personal Care. Gaining share fastest: Food Processing.
Distribution Channel:
Channel economics fragment by customer scale — bulk institutional buyers route through direct distributor relationships, while smaller cosmetic formulators increasingly access certified grades via specialty chemical platforms.
- Online Retail:Specialty chemical marketplaces serving small-batch cosmetic formulators and regional pharmaceutical compounders with documented BIS and FSSAI certification trails.
- Supermarkets:Limited consumer-facing white oil SKUs, primarily cosmetic-grade mineral oil for direct retail purchase.
- Specialty Stores:Chemical supply houses in Mumbai, Ahmedabad, and Hyderabad serving institutional buyers with technical service bundling.
- Distributors:Dominant channel for bulk pharmaceutical and food-grade procurement, with relationships anchored at Gandhar Oil Refinery and Savita Oil Technologies for western India coverage.
Primary volume channel: Distributors. Climbing the fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vadodara anchors India's white oil production capacity through pipeline-connected hydrogen infrastructure at the Gujarat refining corridor. The state's chemical manufacturing belt concentrates hydrofinishing operations serving pharmaceutical and cosmetic formulation demand. Four sub-regional clusters shape domestic supply geography and procurement patterns.
Gujarat
Pharmaceutical-grade liquid paraffin demand from Ahmedabad and Vadodara formulation plants drives technical-grade refinery upgrades. BIS 335 revision compliance costs concentrate investment at Jamnagar and Vadodara hydrofinishing complexes. The Dahej-PCPIR chemical zone hosts membrane separation pilots reducing clay filtration waste volumes for multi-certification output.
Maharashtra
Mumbai-Thane cosmetic manufacturing clusters pull NF/USP-grade white petrolatum for clean-label personal care reformulation. FSSAI H1 registration mandates now govern dairy and bakery equipment procurement across Pune and Nashik food processing belts. Specialty chemical distributors in Navi Mumbai embed formulation support teams with beauty brand technical departments.
Karnataka
Bengaluru pharmaceutical excipient demand expands under PLI scheme API production incentives. FSSAI food-grade lubricant notifications reshape dairy equipment supply chains in the Mysuru-Mandya milk processing corridor. Regional blenders face PAH analytical infrastructure gaps blocking BIS 335 certification for institutional bakery procurement.
Tamil Nadu
Chennai-based personal care exporters require REACH-aligned impurity documentation for European cosmetic accounts. CDSCO drug master file timelines extend product launch cycles for Coimbatore pharmaceutical compounders. The Sriperumbudur automotive belt generates polymer processing aid demand with reduced certification burden.
Haryana
Manesar-Gurugram industrial lubricant distributors serve Delhi-NCR pharmaceutical packaging machinery maintenance. FSSAI H1 compliance gaps exclude uncertified suppliers from Faridabad dairy equipment channels. Regional refiners rely on Panipat complex feedstock scheduling subject to transport fuel priority interruptions.
India White Oil Market Competitive Landscape
The competitive structure tilts toward integrated refiners with captive hydrogen supply and hydrofinishing infrastructure. Mid-scale blenders lacking in-house PAH analytical capabilities face margin compression from multi-registrar certification timelines. Three archetypes dominate: state-owned refining complexes with feedstock advantages, specialized hydrofinishing independents, and technical service-oriented formulation partners. Capacity expansion and backward integration into base oil distillation represent the primary competitive vectors.
Among integrated refining complexes, Indian Oil Corporation Ltd and Bharat Petroleum Corporation Limited anchor the feedstock-controlled tier through Panipat and Vadodara operations. Gandhar Oil Refinery (India) Ltd exemplifies the specialized hydrofinishing archetype with Gujarat corridor concentration. Savita Oil Technologies Ltd occupies the technical service depth position, embedding formulation support with Maharashtra personal care manufacturers. These three patterns illustrate how certification infrastructure and geographic proximity to demand clusters determine competitive positioning.
| Leading Market Players |
|---|
| Indian Oil Corporation Ltd |
| Raj Petro Specialities Pvt. Ltd |
| Gandhar Oil Refinery (India) Ltd |
| Columbia Petro Chem Pvt. Ltd |
| ExxonMobil Corp |
| Savita Oil Technologies Ltd |
| Bharat Petroleum Corporation Limited |
| Shell plc |
| Apar Industries |
| Others |
Supply & Pricing Matrix
Hydrofinishing catalyst specialists concentrated at Panipat and Vadodara complexes command wage premiums that compress margins for mid-scale blenders, widening spreads between USP-certified pharmaceutical grades and technical-grade industrial oils.
Pricing Analysis
Certification-grade anchoring determines value capture, with CDSCO drug master file holders extracting premiums for liquid paraffin laxatives while uncertified suppliers compete on volume in polymer processing aids. Price differentiation hinges on BIS 335 compliance tier and captive hydrogen infrastructure ownership, not brand recognition alone. Cost compression in technical-grade segments is intensifying because regional blenders lack UV fluorescence equipment for PAH certification. Pharmaceutical formulators show least price sensitivity given regulatory substitution barriers, while industrial lubricant buyers prioritize cost over certification tier.
Supply Chain Analysis
Freight cost exposure runs through Korean and Singaporean import corridors for high-viscosity cosmetic and pharmaceutical aerosol grades, exposing domestic blenders to currency volatility. Supply concentrates in India's Gujarat refining corridor, with secondary sourcing from South Korea and Singapore for specialty grades. Feedstock dependencies center on paraffinic distillate from Indian Oil Corporation's transport fuel scheduling, Group III base oils, and Fischer-Tropsch wax for oxidative stability applications. Single-source vulnerability to Indian Oil Corporation's priority scheduling creates production uncertainty. Distribution runs through specialty chemical distributors in Mumbai, Ahmedabad, and Hyderabad serving institutional buyers with technical service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained: hydrofinishing catalyst expertise scarcity at integrated refineries props pricing for certified grades while locking out regional blenders from pharmaceutical and food-grade channels.
For Market Incumbents: Deepen captive hydrogen supply advantages at Panipat and Vadodara through sulfur recovery infrastructure expansion, defending against mid-scale blender margin compression from multi-registrar certification timelines. Prioritize membrane separation pilot scale-up at Dahej-PCPIR to reduce clay filtration waste and enable simultaneous BIS 335, USP, and REACH-aligned output without separate processing trains. For New Entrants and Emerging Players: The premium-to-economy tier gap in Maharashtra cosmetic formulation support offers white-space entry, as Mumbai-Thane clusters lack embedded technical service from trading intermediaries. Target institutional bakery procurement in Karnataka and Maharashtra where FSSAI H1 registration mandates disqualify uncertified suppliers; lead with documented compliance trails and formulation laboratory partnerships rather than commodity supply. For Investors and Strategic Acquirers: Re-rating potential sits with specialized hydrofinishing independents given CDSCO monograph convergence with REACH-aligned impurity limits expanding addressable market for multi-certified output. Long-term viability hinges on backward integration into base oil distillation and geographic proximity to western India demand clusters. Watch for PLI scheme API production incentive disbursement velocity as inflection indicator for excipient-grade white oil offtake acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Distillation | Captive paraffinic feedstock supply at Panipat insulates against Indian Oil Corporation scheduling volatility. |
| Membrane Separation Technology Scale-Up | Ceramic module deployment at Gujarat facilities enables simultaneous BIS 335, USP, and REACH compliance. |
| Multi-Registrar Certification Investment | Simultaneous BIS, CDSCO drug master file, and FSSAI approvals unlock pharmaceutical and food-grade pricing tiers. |
| Embedded Technical Service Expansion | Formulation support teams in Mumbai-Thane clusters capture clean-label personal care reformulation demand. |
| PLI Scheme Alignment for API Excipient Supply | Domestic active ingredient production incentives lift certified liquid paraffin offtake from pharmaceutical compounders. |
Research Methodology
Independent corroboration across hydrofinishing plant managers, procurement leads at Mumbai-based cosmetic manufacturers, CDSCO regulatory affairs specialists, and FSSAI compliance officers underwrites the qualitative findings. Secondary validation draws from BIS standard revision notices, CDSCO drug substance monographs, FSSAI food-grade lubricant notifications, and customs trade data for white oil imports. Bottom-up demand modeling from end-use consumption patterns triangulates against top-down refinery capacity assessments across the analysis window.
Rate-of-change decomposition separates volume drivers by grade tier, end-use industry, and regional production hub throughout the projection horizon. CAGRs derive from segmented demand elasticity modeling against hydrofinishing capacity expansion timelines. Forecast inputs include PLI scheme API production incentive trajectories, BIS-REACH regulatory convergence assumptions, and membrane separation technology adoption curves at Gujarat refining complexes.
Inputs from CDSCO regulatory filings and FSSAI notification databases were available through the study window; gaps in real-time refinery utilization rates introduce uncertainty bands around near-term supply projections. Stakeholders should weight assumptions against their own operating context and feedstock scheduling priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Balanos Oil Market
Petroleum Products
Tar Oil Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market