
 Gasoline-Naphtha-Crude-MTBE Market | 2026-2036
Gasoline-Naphtha-Crude-MTBE Market Size, Share, and Industry Trends Forecast 2026-2036
Gasoline-Naphtha-Crude-MTBE Market Foresight
The gap between premium low-sulfur gasoline blends and commodity-grade refinery output is expanding across Asian trading hubs. Sinopec Group leverages its integrated refining-petrochemical complexes to dominate premium gasoline supply in East China. Saudi Aramco anchors global crude flows through long-term offtake agreements with Asian refiners. Exxon Mobil differentiates via proprietary resid-upgrading technology that yields higher naphtha cuts from heavy sour barrels.
Gasoline-Naphtha-Crude-MTBE encompasses hydrocarbon streams spanning crude oil extraction through refined fuel and oxygenate production, with gasoline typically carrying Reid vapor pressure specifications between 9.0 and 15.0 psi depending on season and region. These materials serve primarily as combustion fuels, chemical precursors, and octane boosters across transportation and manufacturing value chains. Crude oil and gasoline together occupy the largest value share within the product type dimension, reflecting entrenched demand from the transportation sector end user category. Petrochemical feedstock applications within the naphtha segment are capturing margin expansion as ethylene cracker operators in Asia prioritize light feedstock flexibility.
China's MEE enforces sulfur caps and dual carbon emissions targets that constrain high-sulfur crude processing while favoring low-carbon intensity MTBE blending. The EPA in the United States maintains Tier 3 gasoline sulfur standards at 10 parts per million, shaping import demand for compliant blending components. India's BIS mandates Bharat Stage VI fuel specifications that drive refinery upgrade investments and naphtha quality differentiation. Stakeholders must monitor how carbon border adjustments and marine fuel sulfur regulations redirect crude grade preferences and MTBE trade flows between Atlantic and Pacific basins.
Market Dynamics
Refinery upgrade cycles across Asia-Pacific are compressing as sulfur specifications tighten and dual carbon mandates force capital reallocation toward resid-upgrading and hydrogen production units.
Growth Catalysts
- India's Bharat Stage VI mandate:Refinery investments in hydrocracking and hydrotreating capacity expand demand for low-sulfur naphtha streams as petrochemical feedstock.
- Ethylene cracker flexibility:Asian petrochemical operators are prioritizing light feedstock capability that favors naphtha over heavier alternatives.
- Marine fuel sulfur regulations:IMO 2020 residual fuel sulfur caps redirect high-sulfur fuel oil toward coking units, increasing gasoline and naphtha yields.
Market Restraints
- Crude grade concentration:Middle Eastern sour crude supply concentration exposes Asian refiners to term pricing volatility and geopolitical disruption risk.
- Carbon intensity accounting:China's dual carbon goals impose lifecycle emissions tracking that penalizes high-carbon MTBE production pathways.
- Electrification substitution:Battery electric vehicle penetration in Chinese coastal provinces compresses gasoline demand growth trajectories.
Strategic Opportunities
- Vietnam refining expansion:Nghi Son and Long Son complexes under construction create import substitution potential for regional naphtha and gasoline traders.
- Bio-MTBE pathways:Renewable feedstock integration into oxygenate production qualifies for carbon credits under EU Renewable Energy Directive frameworks.
- Digital trading platforms:Singapore-based commodity exchanges are enabling direct refiner-to-retailer gasoline contracting that disintermediates traditional wholesale layers.
Industry Challenges
- Hydroprocessing catalyst supply:Specialized cobalt-molybdenum and nickel-molybdenum catalyst procurement faces 18-24 month lead times from German and Japanese suppliers.
- Cross-border carbon accounting:Refiners struggle to document Scope 3 emissions across blended gasoline and MTBE supply chains for EU Carbon Border Adjustment Mechanism compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gasoline-Naphtha-Crude-MTBE Market |
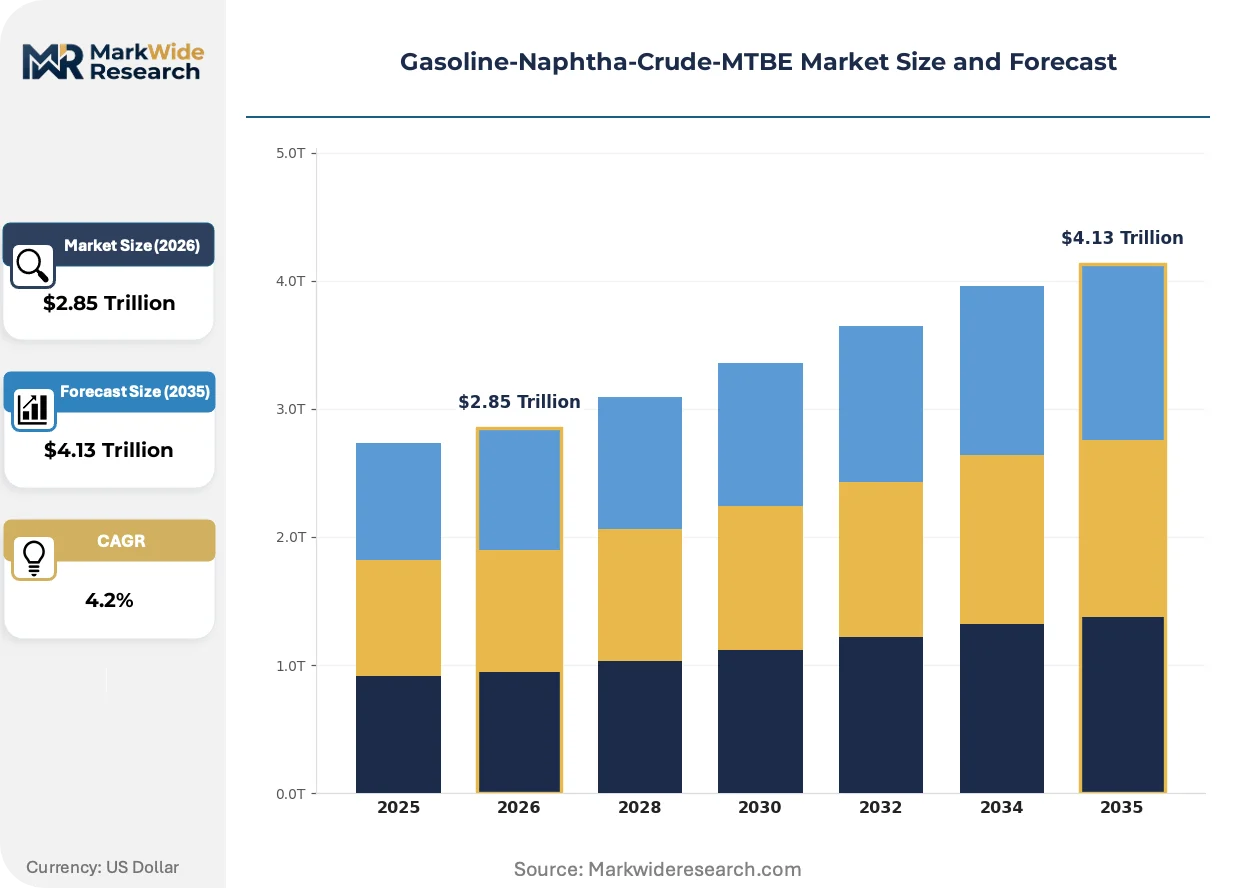
| Market Size in 2026 | $2.85 Trillion |
| Market Size in 2035 | $4.13 Trillion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Naphtha, Crude Oil, MTBE, Liquefied Petroleum Gas Application: Fuel Blending, Solvent Use, Petrochemical Feedstock, Octane Enhancer, Industrial Cleaning End User: Refineries, Chemical Manufacturers, Fuel Distributors, Industrial Plants, Transportation Sector Distribution Channel: Wholesale Suppliers, Direct Sales, Exporters, Energy Traders, Retail Fuel Stations |
| Companies Covered | China Petrochemical Corp. (Sinopec Group), LyondellBasell Industries, PetroChina Company Ltd., SABIC, Exxon Mobil Corporation, Saudi Arabian Oil Co., Enterprise Products Partners L.P., Evonik Industries, BP PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gasoline-Naphtha-Crude-MTBE Market Shifts & Advancements
Process intensification and molecular management technologies are redefining refinery economics, enabling heavier crude processing with lighter product slates while regulatory pressure accelerates low-carbon fuel pathway development.
Advanced process control systems integrating real-time crude assay data with reactor optimization algorithms are automating cut-point decisions in atmospheric and vacuum distillation units. Korean and Japanese refiners are deploying these systems to maximize naphtha yields from discounted heavy sour barrels. The technology is automating quality giveaway reduction that previously required manual laboratory intervention and shift-based operator judgment.
China's MEE enforcement of carbon intensity benchmarks for transportation fuels is forcing independent teapot refiners to document MTBE production emissions or face production quota restrictions. The regulation compresses margins for coal-to-olefins-based MTBE while favoring natural gas liquids pathways. Shandong province refiners are responding by retrofitting carbon capture units onto existing etherification plants.
Spot market procurement of gasoline blending components is displacing term offtake contracts among Japanese and South Korean trading houses. Buyers are aggregating demand through Singapore-based price benchmarks rather than direct refinery relationships. This behavioral shift concentrates price discovery liquidity in Platts Singapore assessments while fragmenting supply chain visibility for end-users.
Gasoline-Naphtha-Crude-MTBE Market Segmentation
Segmentation in hydrocarbon markets determines contract structures, logistics requirements, and margin capture potential across refining and petrochemical value chains. Product specifications, application intensity, and channel control create divergent profitability profiles that shape strategic positioning.
Product Type:
Supply concentration varies sharply across hydrocarbon streams, with integrated majors dominating crude procurement while independent refiners compete in finished products.
- Gasoline:Finished motor gasoline carries Reid vapor pressure specifications between 9.0 and 15.0 psi depending on season and region. Transportation sector buyers in India and Vietnam are scaling purchases as regional refining capacity climbs and sulfur specifications tighten under BIS Bharat Stage VI mandates.
- Crude Oil:Unprocessed petroleum ranging from light sweet to heavy sour grades with API gravity from 10° to 45°. Saudi Aramco anchors term supply flows to Asian refiners, though grade concentration exposes buyers to pricing volatility and geopolitical disruption risk.
- Naphtha:Light hydrocarbon fraction boiling between 30°C and 200°C serving as primary ethylene cracker feedstock. Petrochemical operators in South Korea and Japan prioritize light feedstock flexibility that favors naphtha over heavier alternatives.
- MTBE:Methyl tertiary-butyl ether functions as oxygenate additive raising octane ratings while reducing exhaust emissions. China's MEE carbon intensity benchmarks penalize coal-to-olefins production pathways while favoring natural gas liquids routes.
- Liquefied Petroleum Gas:Propane-butane mixture separated from natural gas processing or refinery streams. Residential and industrial heating demand in rural China and India absorbs regional supply.
Crude oil and gasoline together absorb the bulk of installed capacity; MTBE is expanding most quickly as low-carbon fuel pathways gain regulatory preference.
Application:
Application intensity maps directly to margin volatility, with fuel blending exhibiting price-sensitive spot market dynamics while petrochemical feedstock contracts favor term stability.
- Fuel Blending:Gasoline and MTBE combined to meet octane and emissions specifications. EPA Tier 3 sulfur standards at 10 parts per million shape US import demand for compliant blending components.
- Petrochemical Feedstock:Naphtha cracked to produce ethylene, propylene, and aromatics for plastics and synthetic rubber. Ethylene cracker flexibility investments across Asia favor light feedstock capability.
- Octane Enhancer:MTBE and alternative oxygenates raise gasoline antiknock properties. China's dual carbon goals constrain high-carbon production pathways while bio-MTBE qualifies for EU Renewable Energy Directive credits.
- Solvent Use:Naphtha fractions employed in paints, coatings, and adhesives manufacturing. Industrial solvent demand tracks construction and automotive production cycles.
- Industrial Cleaning:Degreasing and metal cleaning applications utilizing aliphatic hydrocarbon fractions. Manufacturing sector consumption correlates with machinery maintenance schedules.
Fuel blending commands the largest volume share; petrochemical feedstock is climbing the fastest as Asia cracks capacity expansion accelerates.
End User:
Customer scale and integration level determine procurement power, with integrated refiners commanding supply security while distributors compete on logistics flexibility.
- Refineries:Complex processing units converting crude into transportation fuels and chemical precursors. Upgrade cycles across Asia-Pacific compress as sulfur specifications tighten and dual carbon mandates force capital reallocation.
- Chemical Manufacturers:Ethylene crackers and aromatics complexes consuming naphtha and LPG feedstocks. Indian petrochemical consumption from naphtha crackers is accelerating as domestic polymer demand expands.
- Transportation Sector:Fleet operators and retail consumers purchasing finished gasoline and diesel. Battery electric vehicle penetration in Chinese coastal provinces compresses gasoline demand growth trajectories.
- Fuel Distributors:Wholesale and retail intermediaries managing storage, logistics, and last-mile delivery. Singapore-based commodity exchanges enable direct refiner-to-retailer contracting that disintermediates traditional wholesale layers.
- Industrial Plants:Manufacturing facilities consuming fuel oil, LPG, and solvent fractions for process heat and cleaning. Process heat demand tracks industrial production indices.
Refineries absorb the bulk of installed capacity; chemical manufacturers are gaining share fastest as petrochemical integration deepens.
Distribution Channel:
Channel control determines working capital requirements and price discovery exposure, with term contracts favoring supply security while spot trading captures arbitrage opportunities.
- Wholesale Suppliers:Large-volume intermediaries aggregating refinery output for redistribution to retailers and industrial buyers. Sinopec Group leverages integrated refining-petrochemical complexes to dominate premium gasoline supply in East China.
- Energy Traders:Merchants exploiting geographic and temporal arbitrage across Atlantic and Pacific basins. Spot market procurement is displacing term offtake contracts among Japanese and South Korean trading houses.
- Direct Sales:Refiner-to-end-user contracting bypassing intermediaries for large industrial and utility customers. Long-term offtake agreements with Saudi Aramco anchor crude supply security for Asian refiners.
- Exporters:International merchants managing cross-border flows and customs clearance. Marine fuel sulfur regulations redirect high-sulfur fuel oil toward coking units, increasing gasoline and naphtha yields for export.
- Retail Fuel Stations:Final distribution points for finished gasoline and diesel to transportation consumers. Digital payment integration and loyalty programs increasingly differentiate retail networks.
Wholesale suppliers command the bulk of volume flows; energy traders are expanding most quickly as spot market liquidity concentrates in Platts Singapore assessments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Jurong Island refining-petrochemical cluster anchors Asia-Pacific hydrocarbon processing, with integrated complexes converting Middle Eastern crude into gasoline, naphtha, and MTBE for regional distribution.
China
Shandong province teapot refiners are retrofitting carbon capture onto etherification plants as MEE carbon intensity benchmarks penalize coal-to-olefins MTBE pathways. The dual carbon goals constrain high-sulfur crude processing while favoring natural gas liquids routes. Zhejiang's Zhoushan green petrochemical base is expanding resid-upgrading capacity to maximize naphtha yields from discounted heavy sour barrels.
India
Jamnagar's Reliance Industries complex processes over one million barrels daily, driving naphtha cracker feedstock demand as domestic polymer consumption accelerates. BIS Bharat Stage VI mandates force refinery investments in hydrocracking and hydrotreating capacity. Gujarat's Dahej PCPIR zone attracts ethylene cracker expansions prioritizing light feedstock flexibility.
South Korea
Ulsan's refining-petrochemical corridor deploys advanced process control systems integrating real-time crude assay data with reactor optimization algorithms. MFDS-aligned environmental standards shape fuel quality specifications for export markets. Yeosu National Industrial Complex operators maximize naphtha yields through molecular management technologies.
Japan
Chiba Prefecture refiners are shifting from term offtake contracts toward spot market procurement of gasoline blending components through Singapore-based price benchmarks. METI energy security policies maintain strategic petroleum reserves while allowing trading house flexibility. Kashima coastal industrial zone facilities automate cut-point decisions in atmospheric distillation units.
Saudi Arabia
Jubail Industrial City's SABIC complexes anchor global petrochemical feedstock supply through integrated crude-to-chemicals configurations. SFDA environmental standards align with EU export requirements for low-sulfur products. Ras Tanura terminal infrastructure supports term crude flows to Asian refiners under long-term offtake agreements.
Gasoline-Naphtha-Crude-MTBE Market Competitive Landscape
Capital-heavy integrated refiners compete with asset-light trading houses across hydrocarbon value chains. The vendor base concentrates around national oil companies and multinational majors with captive crude supplies, while independent refiners and commodity traders fragment finished product distribution. Three archetypes dominate: state-backed integrated majors controlling upstream-through-downstream value chains, multinational energy corporations licensing proprietary upgrading technologies, and regional trading specialists exploiting arbitrage across Atlantic and Pacific basins. Capacity expansion and strategic partnerships represent the dominant competitive vectors as sulfur specifications tighten and carbon accounting requirements proliferate.
Among state-backed integrated majors, China Petrochemical Corp. (Sinopec Group) and PetroChina Company Ltd. occupy positions exemplifying domestic market dominance through refining-petrochemical complex control. Saudi Arabian Oil Co. anchors term crude supply security for Asian buyers through long-term offtake structures. These entities represent the capital-intensive archetype where upstream crude access determines downstream product market positioning.
| Leading Market Players |
|---|
| China Petrochemical Corp. (Sinopec Group) |
| LyondellBasell Industries |
| PetroChina Company Ltd. |
| SABIC |
| Exxon Mobil Corporation |
| Saudi Arabian Oil Co. |
| Enterprise Products Partners L.P. |
| Evonik Industries |
| BP PLC |
| Others |
Supply & Pricing Matrix
The bifurcation between low-sulfur premium gasoline blends and high-sulfur commodity refinery output manifests in divergent pricing power and logistics configurations across Asian trading hubs. Sinopec Group commands premium margins in East China through integrated refining-petrochemical complexes, while independent teapot refiners in Shandong province compete on spot naphtha arbitrage with compressed logistics flexibility.
Pricing Analysis
Yield-linked pricing anchors value capture for resid-upgrading investments that maximize naphtha cuts from heavy sour barrels. Three-tier pricing structure across premium low-sulfur gasoline, standard Bharat Stage VI-compliant blends, and economy high-sulfur residual fuel reflects quality grade and certification level differentiation. Pricing pressure stems from carbon intensity accounting under China's MEE dual carbon mandates that penalize coal-to-olefins MTBE pathways. Chemical manufacturers exhibit highest price sensitivity due to feedstock flexibility options, while transportation sector buyers locked into sulfur specifications show lowest elasticity.
Supply Chain Analysis
IMO 2020 marine fuel sulfur certification gates access to premium product channels and coking unit feedstock redirection. Supply concentrates in Saudi Arabia, China, and India as primary crude processing and refined product sourcing nodes. Raw material dependencies center on Middle Eastern sour crude grades, specialized cobalt-molybdenum hydroprocessing catalysts from German and Japanese suppliers, and natural gas liquids for low-carbon MTBE pathways. Single-source catalyst procurement vulnerability creates 18-24 month lead time exposure. Distribution runs through Singapore-based commodity exchanges concentrating price discovery liquidity in Platts Singapore assessments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refinery upgrade cycle compression creates supply-constrained conditions that prop pricing for resid-upgrading and hydrogen production capacity. Hydroprocessing catalyst scarcity and carbon capture retrofit requirements limit near-term supply response.
For Market Incumbents: Hedge sulfur specification tightening by accelerating hydrotreating capacity additions in India and Vietnam before Bharat Stage VI enforcement peaks. Secure long-term offtake structures with Saudi Aramco to anchor crude supply security against geopolitical disruption risk. Backward integration into carbon capture technology licensing protects margin position as MEE dual carbon benchmarks tighten. For New Entrants and Emerging Players: EU Renewable Energy Directive carbon credit frameworks in Europe open a window for bio-MTBE pathway development using renewable feedstock integration. Target Vietnam's Nghi Son and Long Son refining complexes under construction for import substitution partnerships in naphtha and gasoline trading. Direct refiner-to-retailer digital platform contracting disintermediates traditional wholesale layers as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with integrated refining-petrochemical operators given ethylene cracker flexibility investments accelerating across Asia-Pacific. Long-term viability favors asset-light trading specialists exploiting Atlantic-Pacific arbitrage with working capital efficiency. Watch battery electric vehicle penetration rates in Chinese coastal provinces as the inflection signal for gasoline demand trajectory revision.| Strategic Initiative | Industry Significance |
|---|---|
| Resid-Upgrading Capacity Expansion | Zhejiang's Zhoushan green petrochemical base maximizes naphtha yields from discounted heavy sour barrels. |
| Carbon Capture Retrofit Program | Shandong province teapot refiners document MTBE production emissions for MEE quota compliance. |
| Long-term Crude Supply Agreement | Saudi Aramco anchors term flows to Asian refiners through Ras Tanura terminal infrastructure. |
| Digital Trading Platform Integration | Singapore-based exchanges enable direct refiner-to-retailer gasoline contracting that fragments wholesale layers. |
| Bio-MTBE Pathway Development | Renewable feedstock integration qualifies for EU Renewable Energy Directive carbon credit frameworks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with refinery operations managers, petrochemical procurement leads, energy trading desk heads, and hydroprocessing catalyst technical directors combined with secondary validation from EPA Tier 3 compliance databases, BIS Bharat Stage VI certification records, and IMO 2020 marine fuel sulfur enforcement reports. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume and value estimates across the analysis window.
Granularity-level modeling disaggregated projections by product type, application intensity, end-user integration level, and distribution channel control across the projection horizon. CAGRs derived from weighted average of historical trajectory analysis and scenario-adjusted forward assumptions. Crude grade preference shifts under carbon border adjustment mechanisms and marine fuel sulfur regulations served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for resid-upgrading and hydrogen production; alternative pathways for molecular management automation would alter the outlook. Forecasts reflect assumptions around refinery upgrade cycle timing, catalyst supply availability, and carbon intensity benchmark enforcement. A model refresh is warranted upon material change in battery electric vehicle penetration rates or MEE dual carbon quota allocation mechanisms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Naphtha Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Oil Shale Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Africa Refined Petroleum Products Market