
 Malaysia Refined Petroleum Products Market | 2026-2036
Malaysia Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Refined Petroleum Products Market Foresight
Project finance structures tied to refinery upgrades and storage terminal leases is reshaping competitive entry in Malaysia's downstream petroleum sector. Petroliam Nasional Berhad anchors the national supply chain through integrated upstream-to-retail operations. Hengyuan Refining Company Berhad leverages its Port Dickson complex capacity to compete on middle distillate output. Shell PLC differentiates through premium retail network positioning across Peninsular Malaysia.
Refined petroleum products encompass hydrocarbon fuels produced through atmospheric and vacuum distillation, catalytic cracking, and hydrotreating of crude oil, yielding fractions with specific boiling ranges and sulfur content thresholds for combustion engines and industrial burners. Gasoline and diesel together dominate product type volume, with diesel gaining structural share from industrial logistics and power generation applications. Jet fuel represents the fastest-growing product type segment, driven by aviation end-user recovery and expansion at Kuala Lumpur International Airport's cargo and passenger hubs.
The Malaysian Department of Environment enforces Clean Air Regulations that limit sulfur content in automotive diesel, while the Energy Commission oversees fuel quality standards under the Electricity Supply Act. The Ministry of International Trade and Industry coordinates B20 biodiesel blending mandates that reshape refinery product slates and import dependency calculations. Stakeholders must monitor feedstock cost volatility against biofuel policy trajectories to calibrate capital deployment across cracking and hydrotreater investments.
Market Dynamics
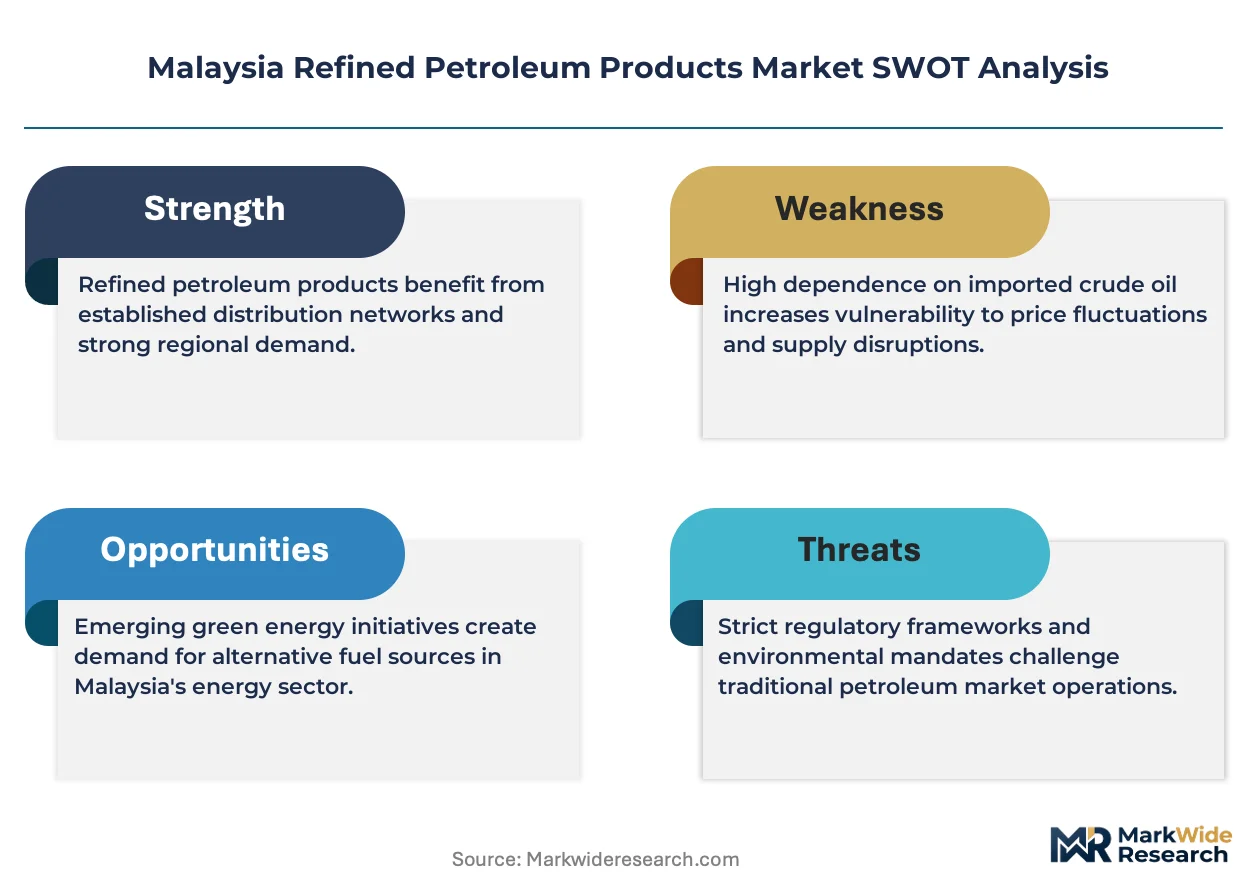
Malaysia's refined petroleum sector operates under the tension between Petronas's integrated supply dominance and the Malaysian Palm Oil Board's escalating biodiesel mandates that are systematically redirecting refinery output slates away from conventional distillates.
Growth Catalysts
- Jet fuel demand recovery:Kuala Lumpur International Airport's cargo and passenger expansion is accelerating middle distillate consumption from aviation end-users. This structural demand pull concentrates in the Klang Valley corridor where refining complexes anchor distribution.
- B20 biodiesel mandate progression:The Ministry of International Trade and Industry's blending requirements are creating dedicated offtake channels for palm oil methyl ester, securing refinery utilization through mandated product slate diversification.
- Automotive sector gasoline requirements:Petronas's downstream investments are expanding supply infrastructure to serve Peninsular Malaysia's vehicle fleet, with retail network density reinforcing volume capture.
Market Restraints
- Crude feedstock cost volatility:Malaysian refiners remain exposed to Middle Eastern crude benchmark fluctuations, compressing crack spreads during periods of elevated input costs.
- Refinery capacity concentration:National supply security depends disproportionately on the Port Dickson complex and Klang Valley facilities, creating geographic vulnerability to operational disruptions.
- Import dependency for specialty fractions:Domestic hydrotreating limitations necessitate gasoline component imports, constraining full product slate independence.
Strategic Opportunities
- Sarawak and Sabah distribution expansion:East Malaysian states present underdeveloped retail infrastructure where independent terminal operators can establish coastal storage and bunkering positions.
- Marine gasoil bunkering growth:Port Klang's vessel traffic is creating demand for low-sulfur marine fuels that domestic refiners can capture through hydrotreater investments.
- Renewable diesel co-processing:Existing fluid catalytic cracking units can be retrofitted for vegetable oil feedstock integration, aligning with the Malaysian Palm Oil Board's biofuel trajectory.
Industry Challenges
- Hydrotreater catalyst replacement cycles:Sulfur reduction requirements under the Department of Environment's Clean Air Regulations demand frequent catalyst changeouts, disrupting continuous operations.
- Blending infrastructure reconfiguration:Biodiesel mandate escalation requires tank farm modifications and additive injection systems that strain legacy terminal designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Refined Petroleum Products Market |
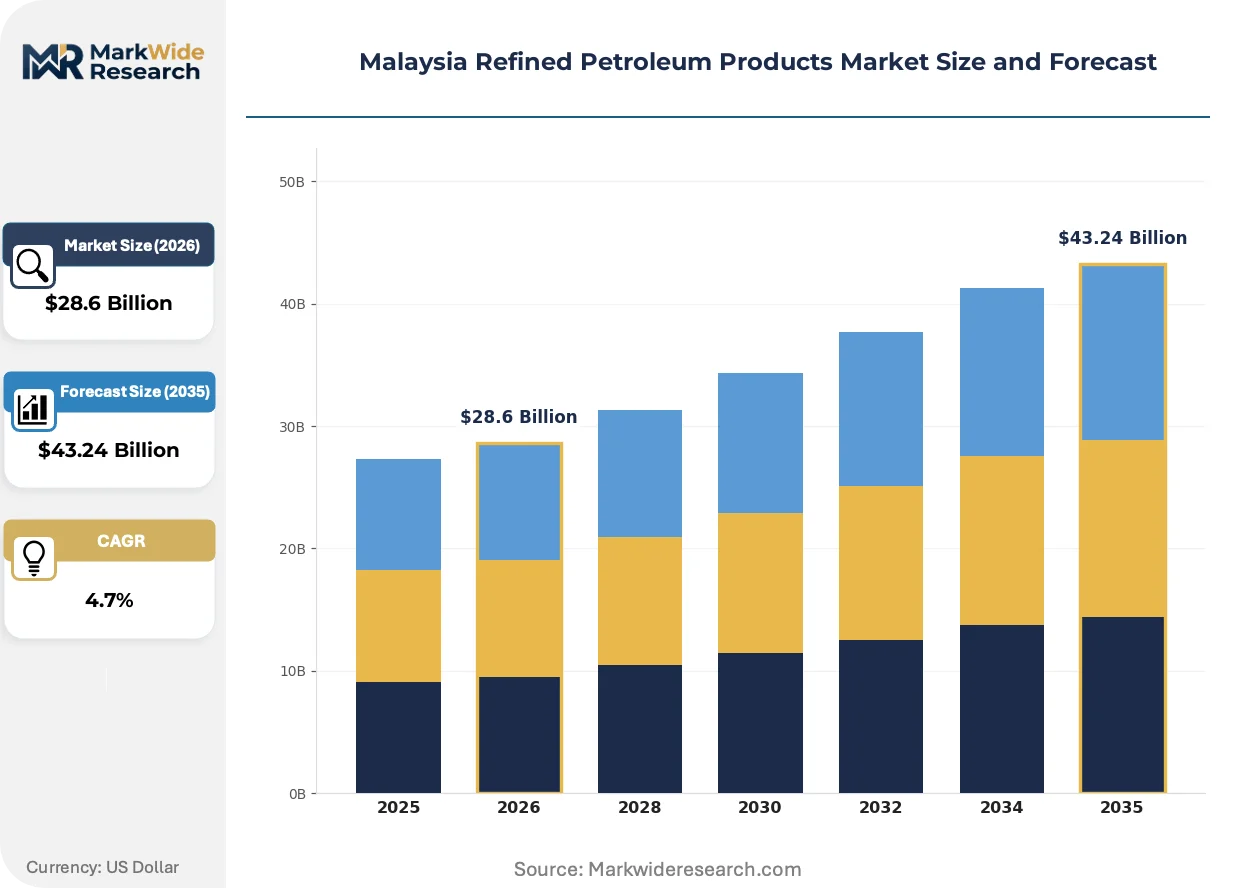
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene Distribution Channel: Retail, Wholesale, Direct Supply, Online Sales Application: Transportation, Industrial, Power Generation, Residential End User: Automotive, Aviation, Shipping, Manufacturing |
| Companies Covered | Petron Malaysia Refining & Marketing Bhd, FIVE Petroleum Malaysia Sdn Bhd, Petroliam Nasional Berhad, Gas Malaysia Berhad, Petroleum Sarawak Berhad, Chevron Corporation, Hengyuan Refining Company Berhad, EcoCeres, Shell PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Refined Petroleum Products Market Shifts & Advancements
Refining technology and product specifications in Malaysia are pivoting toward lower-carbon intensity outputs, with regulatory pressure and feedstock economics jointly forcing capital redeployment across cracking and treating assets.
Residue upgrading technology is migrating from conventional coking configurations toward ebullated-bed hydrocracking systems that maximize middle distillate yields from heavy sour crude slates. Port Dickson complex operators are evaluating reactor additions to capture aviation and marine gasoil premiums. This shift is compressing the economic viability of standalone visbreaking units that produce high-sulfur fuel oil.
The Department of Environment enforces sulfur content limits in automotive diesel under Clean Air Regulations that align with Euro 5 equivalent specifications. Refiners must operate hydrotreaters at higher severity to achieve 10 ppm sulfur thresholds, increasing hydrogen consumption and catalyst replacement frequency. The automotive diesel segment bears the steepest compliance cost burden, with product differentiation now tied to sulfur certification rather than cetane index alone.
Fleet operators in Peninsular Malaysia are consolidating fuel procurement through direct refinery offtake agreements that bypass traditional distributor markups. Large logistics and plantation companies with captive vehicle fleets now negotiate volume contracts with Hengyuan and Petronas Marketing, compressing margins for independent petrol station dealers. This concentration is most visible in the Klang Valley industrial belt where centralized fleet management dominates diesel consumption patterns.
Malaysia Refined Petroleum Products Market Segmentation
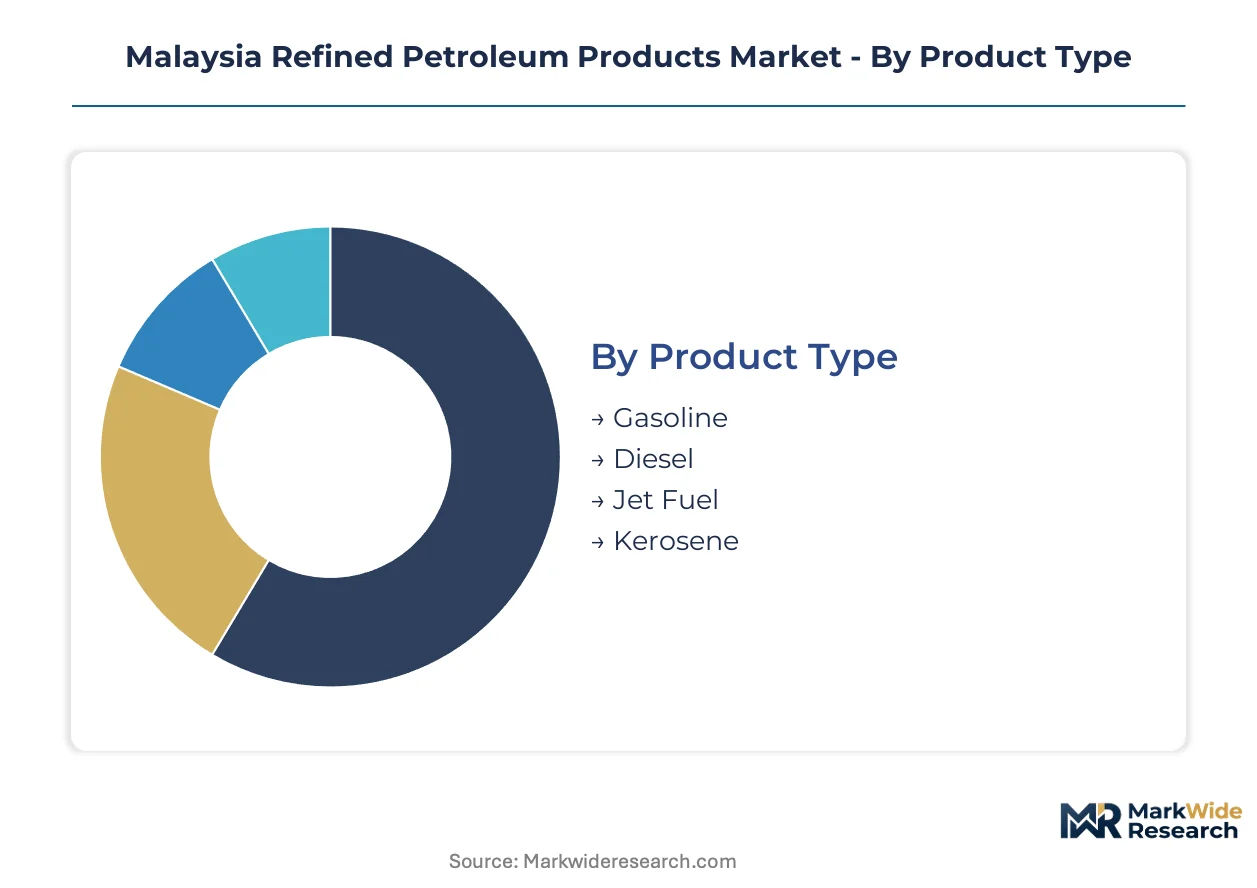
Segmentation in Malaysia's refined petroleum sector reveals how regulatory mandates and infrastructure constraints reshape product slates and channel economics. Each dimension exposes different pressure points from biodiesel blending requirements to fleet procurement consolidation.
Product Type:
Mature distillates anchor refinery output while emerging specifications force capital redeployment across hydrotreating assets.
- Gasoline:Light hydrocarbon fractions with Reid vapor pressure specifications for spark-ignition engines. Demand concentrates in Peninsular Malaysia's Klang Valley corridor where Petronas retail networks capture automotive sector volume. The Department of Environment's sulfur limits under Clean Air Regulations force continuous hydrotreater investment.
- Diesel:Middle distillate with cetane index and sulfur content thresholds for compression-ignition engines. Industrial logistics fleets in the Klang Valley industrial belt now procure through direct refinery offtake agreements, bypassing traditional distributor channels. B20 biodiesel mandates from the Ministry of International Trade and Industry systematically redirect refinery output slates.
- Jet Fuel:Kerosene-range fraction with freeze point and smoke point specifications for aviation turbine engines.
- Kerosene:Illuminating oil with flash point requirements for wick-fed burners and industrial heating applications.
Diesel handles the majority of throughput; jet fuel is expanding most quickly on share.
Distribution Channel:
Channel economics split between capital-intensive infrastructure plays and relationship-based volume contracting.
- Retail:Branded petrol station networks with tank farm and forecourt infrastructure. Peninsular Malaysia's dealer-operated sites face margin compression from fleet operator consolidation into direct supply agreements.
- Wholesale:Terminal-to-terminal transfers and distributor markups for independent petrol dealers.
- Direct Supply:Refinery-to-fleet contracts that bypass traditional distributor economics. Large plantation and logistics companies with captive vehicle fleets negotiate volume agreements with Hengyuan and Petronas Marketing.
- Online Sales:Digital procurement platforms for commercial fuel ordering and delivery scheduling.
Direct supply is gaining share fastest as fleet operators consolidate procurement; retail maintains the widest geographic footprint.
Application:
End-use diversification exposes refiners to diverging demand elasticities across mobility and stationary combustion.
- Transportation:Fuel combustion in road vehicles, rail locomotives, and marine vessels. Kuala Lumpur International Airport's cargo and passenger expansion accelerates middle distillate consumption from aviation end-users in the Klang Valley corridor.
- Industrial:Process heat and motive power for manufacturing operations. Diesel-fed generators provide backup power for factories in Peninsular Malaysia's industrial belts where grid reliability varies.
- Power Generation:Fuel oil and diesel combustion in reciprocating engines and turbines for electricity production.
- Residential:Kerosene and LPG for cooking and heating in domestic households.
Transportation commands the largest volume share; industrial applications show the steepest expansion trajectory.
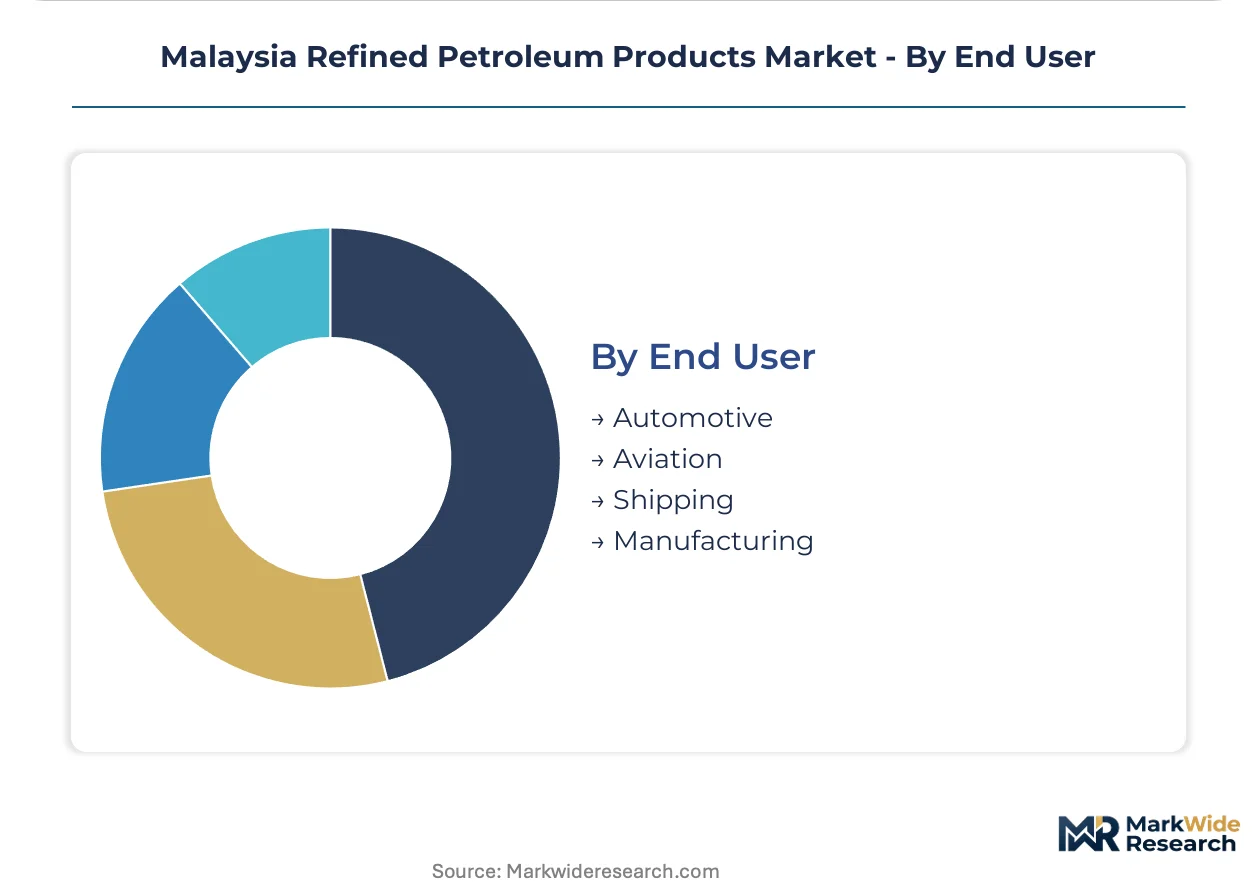
End User:
Customer concentration patterns determine pricing leverage and contract structure across the value chain.
- Automotive:Passenger vehicles and commercial trucks consuming gasoline and diesel. Fleet operators in Peninsular Malaysia negotiate direct refinery contracts, compressing margins for independent petrol station dealers.
- Aviation:Airlines and cargo operators requiring jet fuel at Kuala Lumpur International Airport. This segment climbs fastest on volume as airport expansion drives middle distillate demand.
- Shipping:Vessel operators requiring marine gasoil and low-sulfur bunkers at Port Klang.
- Manufacturing:Industrial facilities using diesel for captive power generation and process heat.
Automotive absorbs the greatest product volume; aviation is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Malaysian Palm Oil Board's escalating biodiesel mandates are redrawing refinery output slates across Southeast Asia. National energy policies now prioritize palm oil methyl ester integration over conventional distillate expansion. Refining capacity concentrates in coastal corridors where marine bunkering and aviation demand intersect.
Peninsular Malaysia
The Klang Valley corridor hosts Petronas refining complexes that anchor national fuel distribution. The Department of Environment enforces Clean Air Regulations limiting sulfur content in automotive diesel. Kuala Lumpur International Airport's cargo expansion accelerates jet fuel consumption from aviation end-users concentrated in this industrial belt.
Sarawak
East Malaysian coastal terminals present underdeveloped retail infrastructure for independent storage operators. Petroleum Sarawak Berhad coordinates state-level petroleum resource management and downstream distribution. Bintulu's industrial port cluster creates demand for marine gasoil bunkering that domestic refiners can capture through coastal supply positions.
Sabah
Kota Kinabalu's vessel traffic generates requirements for low-sulfur marine fuels at regional shipping hubs. The Ministry of International Trade and Industry's B20 mandate progression affects refinery product slate calculations for East Malaysian facilities. Sandakan's palm oil processing belt creates localized biodiesel feedstock availability for blending operations.
Port Dickson Complex Zone
Hengyuan Refining Company Berhad leverages atmospheric and vacuum distillation capacity to compete on middle distillate output. The Energy Commission oversees fuel quality standards under the Electricity Supply Act across this refining concentration. Industrial logistics fleets in the surrounding Negeri Sembilan corridor negotiate direct refinery offtake agreements bypassing traditional distributor markups.
Johor Bahru-Singapore Corridor
Cross-border marine bunkering demand at Port of Tanjung Pelepas competes with Singapore's established low-sulfur fuel oil hub. Shell PLC differentiates through premium retail network positioning across southern Peninsular Malaysia. The Iskandar Malaysia economic zone's manufacturing concentration drives diesel-fed generator demand for backup power where grid reliability varies.
Malaysia Refined Petroleum Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Malaysia's downstream petroleum sector. Petronas anchors national supply security through integrated upstream-to-retail operations while independent refiners capture margin in specific distillate segments. Two archetypes dominate: state-linked integrated majors with terminal infrastructure control, and independent processors with cracking unit specialization. Competitive moves concentrate on storage terminal lease negotiations and hydrotreater capacity additions for sulfur compliance.
Within the state-linked integrated tier, Petroliam Nasional Berhad and Petroleum Sarawak Berhad exemplify channel-controlling positioning through captive distribution networks. Hengyuan Refining Company Berhad occupies the independent processor archetype, leveraging Port Dickson complex capacity for middle distillate competition. Shell PLC and Chevron Corporation represent multinational retail specialists with premium positioning across Peninsular Malaysia forecourts. These three groupings illustrate how regulatory mandates and infrastructure access shape competitive boundaries.
| Leading Market Players |
|---|
| Petron Malaysia Refining & Marketing Bhd |
| FIVE Petroleum Malaysia Sdn Bhd |
| Petroliam Nasional Berhad |
| Gas Malaysia Berhad |
| Petroleum Sarawak Berhad |
| Chevron Corporation |
| Hengyuan Refining Company Berhad |
| EcoCeres |
| Shell PLC |
| Others |
Supply & Pricing Matrix
Undercapacity at East Malaysian coastal terminals is tightening supplier negotiating leverage while compressing delivered-cost premiums for buyers in Sarawak and Sabah. This utilization gap simultaneously rewards inventory positioning in Peninsular Malaysia and penalizes distant procurement, creating a bifurcated pricing posture across the archipelago.
Pricing Analysis
Sulfur certification level creates the primary spread between Euro 5-compliant automotive diesel and high-sulfur fuel oil residuals. Contract-based long-term offtake agreements dominate, with volume scale and direct refinery access driving differentiation between fleet operators and independent dealers. Price compression runs through retail channels as Petronas Marketing and Hengyuan negotiate direct supply contracts with plantation and logistics companies. Fleet operators with captive vehicle pools exhibit lowest price sensitivity; independent petrol station dealers face acute margin pressure from bypassed distributor economics.
Supply Chain Analysis
Extended payment terms from Petronas Marketing to terminal operators are stabilizing working capital across the Klang Valley distribution corridor. Crude feedstock draws from Middle Eastern benchmarks, with Malaysian refiners tethered to Dubai-Oman pricing for input cost calculation. Hydrotreater catalyst replacement cycles and B20 biodiesel blending infrastructure create single-source vulnerability for specialty additive suppliers. Distribution runs through coastal storage terminals at Port Dickson and Port Klang, with barge-fed secondary distribution to East Malaysian states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Malaysia's refined petroleum sector presents a defensive-moat story anchored in regulatory entrenchment: biodiesel mandate progression and sulfur compliance requirements create structural barriers that favor incumbents with existing hydrotreater investments and terminal infrastructure control.
For Market Incumbents: Entrench position through captive hydrogen supply integration at Port Dickson and Klang Valley complexes, neutralizing feedstock cost volatility that compresses crack spreads. Expand storage terminal lease negotiations in Sarawak and Sabah before independent operators capture coastal bunkering positions. Priority lever rests on hydrotreater capacity additions that secure Euro 5 diesel certification ahead of Department of Environment enforcement tightening.
For New Entrants and Emerging Players: East Malaysian coastal terminals present the most penetrable geography, where Petroleum Sarawak Berhad's distribution coordination leaves gaps for independent storage and marine gasoil bunkering. Target Bintulu's industrial port cluster and Kota Kinabalu's vessel traffic for low-sulfur marine fuel supply positions. Go-to-market angle: renewable diesel co-processing retrofits that align with Malaysian Palm Oil Board biofuel trajectories while leveraging existing fluid catalytic cracking unit infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hydrotreating and hydrogen production assets as sulfur specifications tighten. Long-term viability favors processors with backward integration into crude supply or forward integration into fleet direct-supply contracts. Acquisition target archetype: independent refiners with stranded visbreaking capacity that can be repurposed for residue upgrading to middle distillates. Signal to watch: Petronas downstream investment announcements indicating capacity expansion or retail network densification.
| Strategic Initiative | Industry Significance |
|---|---|
| Residue Upgrading Capacity Addition | Ebullated-bed hydrocracking retrofits capture aviation and marine gasoil premiums at Port Dickson. |
| Renewable Diesel Co-Processing | Vegetable oil feedstock integration aligns refinery output with Malaysian Palm Oil Board mandate progression. |
| East Malaysia Distribution Expansion | Coastal storage positions in Bintulu and Kota Kinabalu secure marine bunkering growth from Port Klang spillover. |
| Hydrotreater Catalyst Supply Agreement | Long-term additive procurement stabilizes compliance costs under Department of Environment sulfur regulations. |
| Direct Fleet Supply Contracting | Refinery-to-logistics company agreements bypass distributor markups and cement volume capture in Klang Valley industrial belt. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery operations managers, Petronas Marketing distribution executives, fleet procurement directors at plantation companies, terminal lease negotiators, and Malaysian Palm Oil Board policy specialists. Secondary validation drew from Energy Commission fuel quality filings, Department of Environment Clean Air Regulation enforcement records, customs import data for gasoline components, and Petroliam Nasional Berhad annual downstream disclosures. Bottom-up volume modeling across product types and top-down macroeconomic calibration were triangulated to secure analytical coherence.
Calibration against historical crack spreads and biodiesel blending cost curves anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, distribution channel, application, and end-user concentration patterns. CAGRs were derived from elasticity-adjusted demand curves incorporating aviation recovery trajectories at Kuala Lumpur International Airport and B20 mandate implementation schedules. Industry-specific inputs encompassed palm oil methyl ester price volatility and marine gasoil sulfur specification shifts at Port Klang.
Macroeconomic conditions sit as an overlay; deviation in Middle Eastern crude benchmarks, ringgit-dollar exchange rates, or Malaysian Palm Oil Board mandate acceleration would shift the trajectory. Forecasts reflect documented assumptions about refinery utilization rates and infrastructure investment timelines. Regulatory enforcement intensity, feedstock cost dislocation, or technological substitution in renewable diesel processing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Oil Shale Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Petcoke Market
Petroleum Products
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market
Petroleum Products
Oil Refining Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Marine Minerals Market
Petroleum Products
South Africa Petroleum Market