
 Longitudinal Submerged-Arc Welded (LSAW) Pipes Market | 2026-2036
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market Analytics
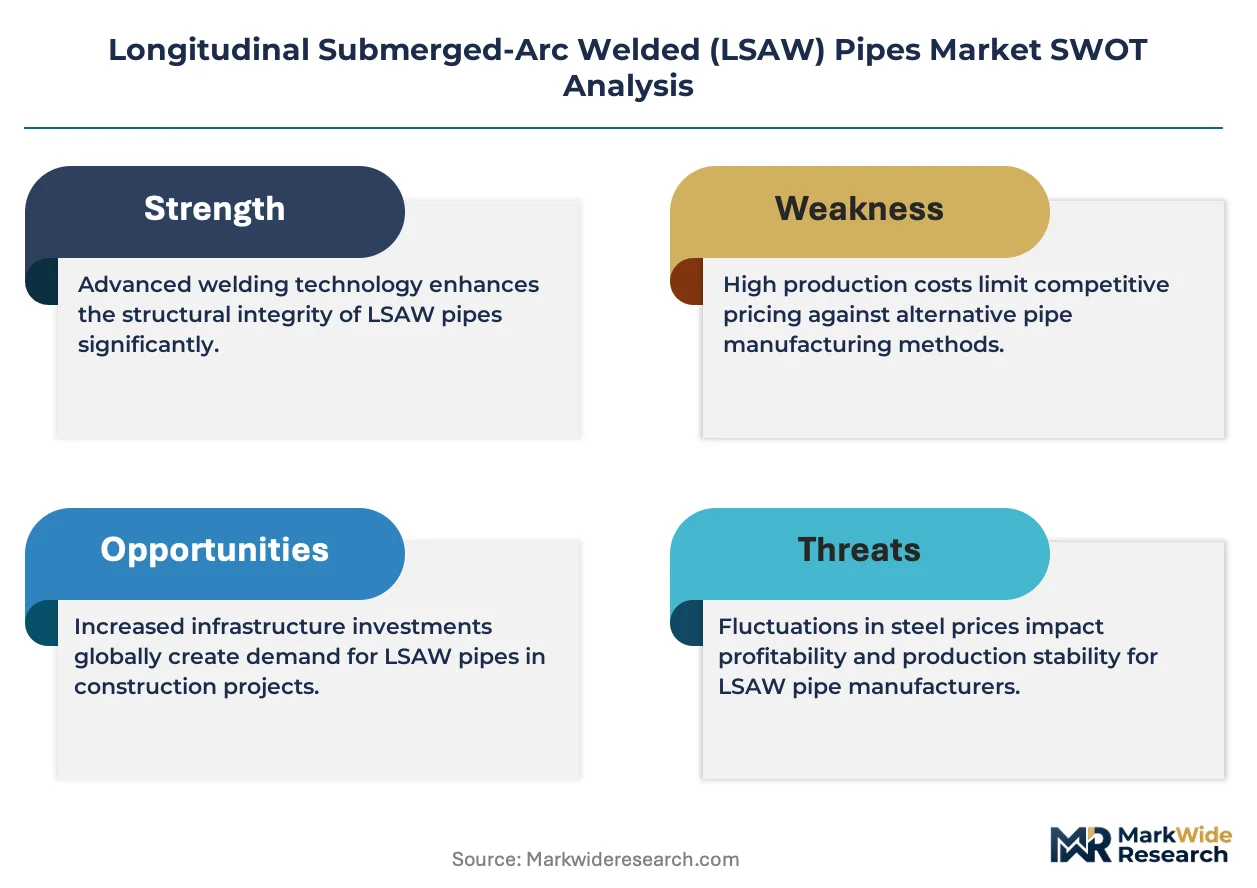
The capability gap between integrated steel-pipe producers and regional fabricators is rotating competitive advantage toward firms with captive plate mills and in-house coating facilities. EUROPIPE GmbH leverages its German manufacturing base to sustain long-term supply contracts for North Sea offshore pipelines. JFE Steel Corporation anchors its position through advanced metallurgy capabilities that differentiate its high-strength grades for sour-service environments. Welspun Group competes on scale, operating one of the world's largest LSAW pipe facilities on India's west coast.
Longitudinal Submerged-Arc Welded pipes are manufactured from steel plates formed into cylindrical shapes and welded along the longitudinal seam using submerged-arc welding, typically producing diameters from 16 to 64 inches with wall thicknesses up to 40 millimeters for high-pressure fluid transmission. Their primary purpose lies in transporting hydrocarbons, water, and industrial fluids over long distances under extreme pressure and temperature conditions. Large-diameter segments dominate volume due to trunk pipeline replacement cycles in mature markets, while coated LSAW commands premium positioning as operators prioritize corrosion resistance for subsea and Arctic deployments. The offshore application dimension is gaining structural prominence as floating production systems and deepwater tiebacks multiply.
API 5L standards enforced by the American Petroleum Institute govern chemical composition and mechanical testing for North American pipeline projects, while ISO 3183 harmonizes international specifications for line pipe steel grades. The EU's F-Gas Regulation and national methane reduction targets are indirectly steering European operators toward leak-resistant welded systems with enhanced joint integrity. Stakeholders must monitor evolving carbon-border adjustments and domestic content requirements as procurement criteria increasingly embed emissions accounting alongside traditional cost and performance metrics.
Market Dynamics
The LSAW pipes market is tightening around metallurgical capability gaps as API 5L and ISO 3183 standards harden traceability mandates for sour-service grades. Integrated producers with captive plate mills capture procurement contracts that regional fabricators cannot fulfill.
Growth Catalysts
- API 5L Certification Expansion:North American pipeline operators now require enhanced Charpy V-notch testing for Arctic deployments, pulling demand toward certified high-strength grades.
- India:The Petroleum and Natural Gas Regulatory Board is accelerating trunk pipeline approvals for cross-country natural gas grids, concentrating procurement in domestic facilities.
- Subsea Coating Advancement:Three-layer polyethylene and fusion-bonded epoxy systems are extending asset life in deepwater tiebacks, creating premium positioning for coated LSAW segments.
Market Restraints
- Steel Plate Concentration:High-grade sour-service plate supply concentrates among integrated mills in China, Japan, and Germany, exposing project timelines to single-source risk.
- Spiral-Weld Substitution:Spiral submerged-arc welded pipes retain cost advantage in low-pressure water transmission, compressing LSAW volume in non-hydrocarbon applications.
- F-Gas Regulatory Friction:The EU's fluorinated gas phase-down is complicating coating facility permits in European manufacturing zones, extending project lead times.
Strategic Opportunities
- Hydrogen Infrastructure:Germany's SINTEG funding clusters and the EU Hydrogen Backbone initiative are creating dedicated procurement channels for hydrogen-rated LSAW grades.
- Carbon-Adjusted Procurement:Buyers are embedding Scope 3 emissions accounting into tender criteria, rewarding mills with electric-arc furnace plate supply and in-house coating.
- Middle East Localization:Saudi Arabia's National Industrial Development Center is incentivizing domestic pipe fabrication for Red Sea offshore projects, opening greenfield supply relationships.
Industry Challenges
- Welding Inspector Scarcity:Qualified ASNT Level III ultrasonic testing technicians are in short supply across North American and European fabrication yards, bottlenecking certification throughput.
- Legacy Mill Retrofit Costs:Converting plate rolling capacity to API 5L PSL2 sour-service specifications requires furnace control upgrades that strain mid-tier producer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Longitudinal Submerged-Arc Welded (LSAW) Pipes Market |
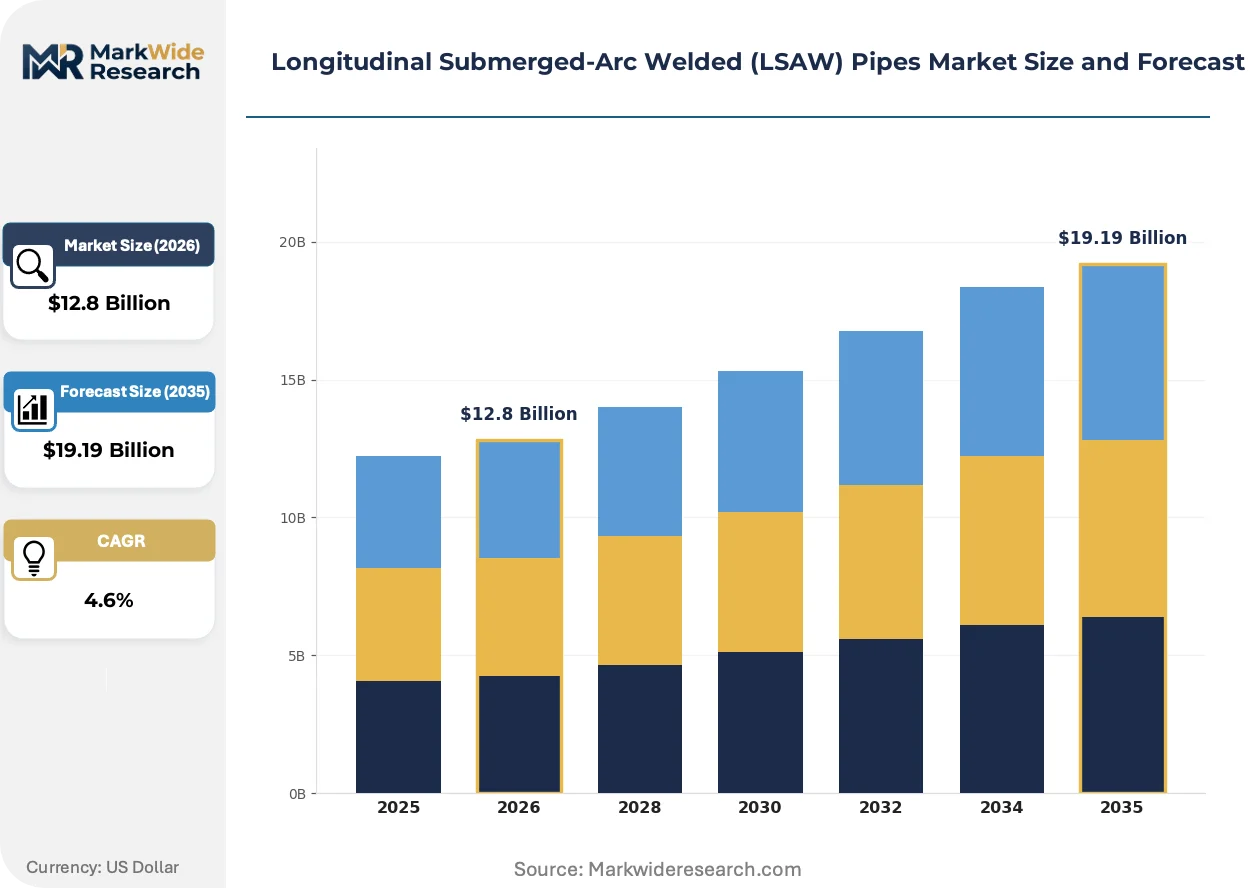
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard LSAW, High-Strength LSAW, Coated LSAW, Special LSAW End User: Oil & Gas, Water Supply, Construction, Industrial Diameter: Small Diameter, Medium Diameter, Large Diameter, Extra-Large Diameter Application: Pipeline, Structural, Marine, Offshore |
| Companies Covered | Jindal Saw, EUROPIPE GmbH, JFE Steel Corporation, Tenaris S.A., Nippon Steel Corporation, Welspun Group, EEW Group, TMK, ArcelorMittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market Evolving Landscape
Digital thread technologies and advanced non-destructive testing are compressing defect detection timelines while hardening material traceability. These shifts are restructuring competitive advantage around data infrastructure rather than scale alone.
Thermomechanically controlled processing is supplanting normalized rolling for high-strength line pipe grades. Offshore operators in the North Sea and Gulf of Mexico are specifying TMCP plates for reduced carbon equivalent and improved weldability. This metallurgical shift is enabling thinner wall designs that cut tonnage requirements per kilometer of trunk line.
The EU's F-Gas Regulation and national methane reduction frameworks are tightening leak-rate specifications for pipeline joints. German and Dutch transmission system operators are revising procurement criteria to mandate enhanced ultrasonic testing of seam welds. This regulatory pressure is compressing market share for second-tier fabricators lacking automated inspection infrastructure.
Integrated service contracts are displacing discrete pipe-and-coating purchasing across major trunk line projects. EPC firms in India and the United States are bundling LSAW supply with welding, field joint coating, and integrity management into single-source agreements. This procurement consolidation is most visible in cross-border transmission projects where schedule risk transfer outweighs unit cost optimization.
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market Segmentation
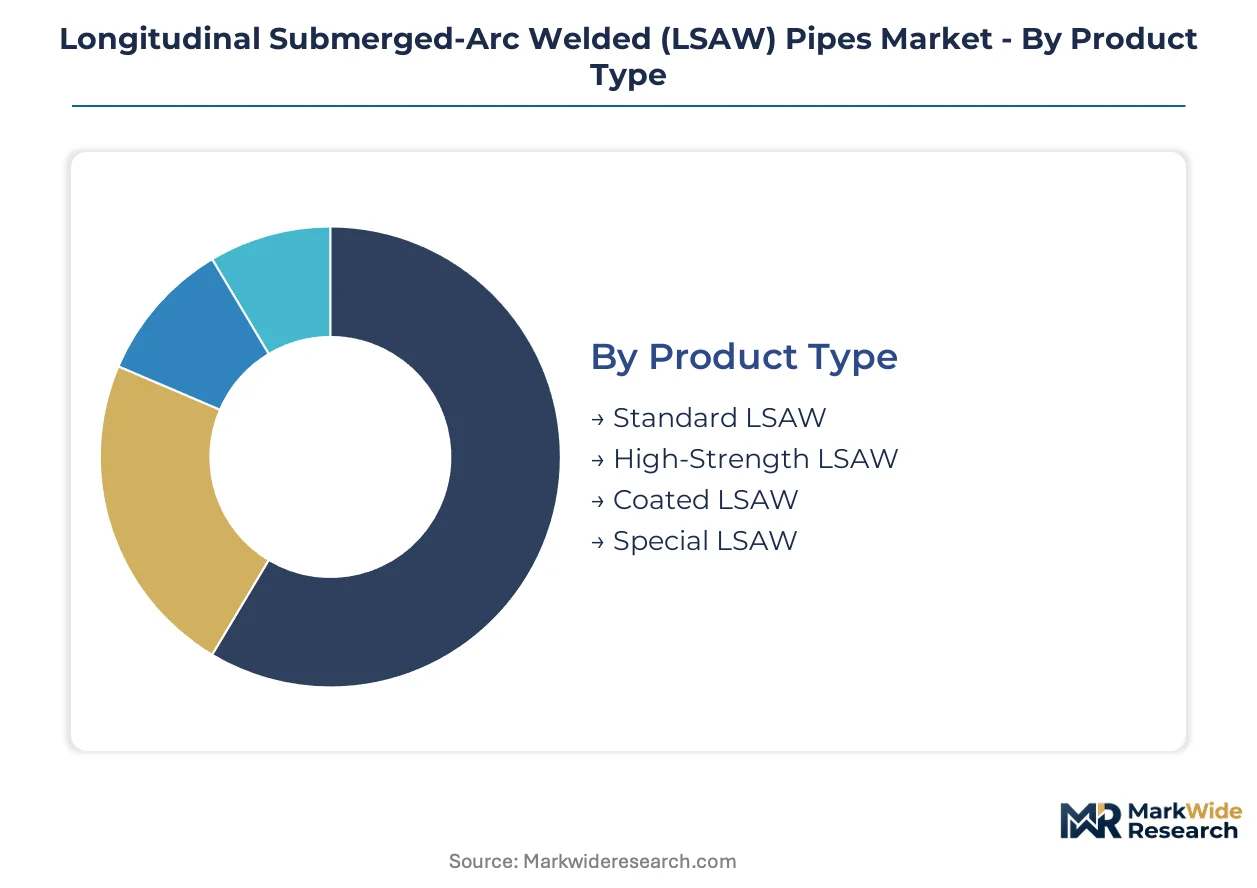
LSAW pipe procurement splits sharply between domestic infrastructure mandates and export-driven hydrocarbon projects. Segmentation reveals how certification requirements and coating specifications reshape competitive positioning across product tiers.
Product Type:
Standard grades dominate domestic water transmission in India and China, while high-strength and coated variants concentrate in North Sea and Gulf of Mexico export contracts.
- Standard LSAW:Manufactured to API 5L PSL1 specifications with yield strengths of 245-450 MPa. Municipal water authorities in India and China's provincial pipeline networks specify these grades for non-sour service environments where cost minimization overrides metallurgical complexity.
- High-Strength LSAW:API 5L X70-X80 grades with thermomechanically controlled processing deliver reduced carbon equivalent for Arctic deployments. Norwegian and Alaskan trunk line operators now mandate these specifications for permafrost and subsea tiebacks where weight reduction cuts installation tonnage.
- Coated LSAW:Three-layer polyethylene and fusion-bonded epoxy systems extend asset life in corrosive soils.
- Special LSAW:Sour-service grades with HIC-resistant metallurgy for hydrogen sulfide environments.
Standard LSAW holds the largest share; momentum sits with Coated LSAW.
End User:
Cost tiers separate commodity procurement from premium-grade contracting, with oil and gas operators paying metallurgical premiums unavailable to municipal water utilities.
- Oil & Gas:Transmission system operators in Germany, the Netherlands, and the United States specify enhanced ultrasonic testing and full-body inspection. Sour-service grades for hydrogen sulfide environments command 15-25% price premiums over standard API 5L PSL1 material.
- Water Supply:Municipal procurement in India and China's provincial networks prioritizes unit cost over alloy complexity. Spiral-weld substitution pressure is most acute in this tier where pressure ratings remain below 50 bar.
- Construction:Piling and structural applications in Saudi Arabia's Red Sea developments and UAE infrastructure corridors.
- Industrial:Chemical process and power generation feedwater systems in Japan and South Korea.
Oil & Gas commands the highest value per ton; Water Supply delivers the steepest expansion trajectory in developing economies.
Diameter:
Volume concentrates in large-diameter trunk line replacement cycles, while extra-large segments remain captive to integrated mills with specialized plate rolling capacity.
- Large Diameter:42-64 inch specifications for cross-border natural gas transmission. The Petroleum and Natural Gas Regulatory Board's accelerated trunk pipeline approvals in India concentrate demand at 48-56 inch diameters for the national gas grid.
- Extra-Large Diameter:Above 64 inches requiring dedicated plate mills with 5-meter width rolling capacity. Only Japanese, German, and Chinese integrated producers maintain qualified supply for North Sea offshore pipelines and Middle East petrochemical corridors.
- Medium Diameter:24-40 inch range for gathering systems and distribution laterals.
- Small Diameter:16-24 inch segments facing spiral-weld displacement in non-critical applications.
Large Diameter dominates current procurement volumes; Extra-Large Diameter is climbing the fastest on offshore project proliferation.
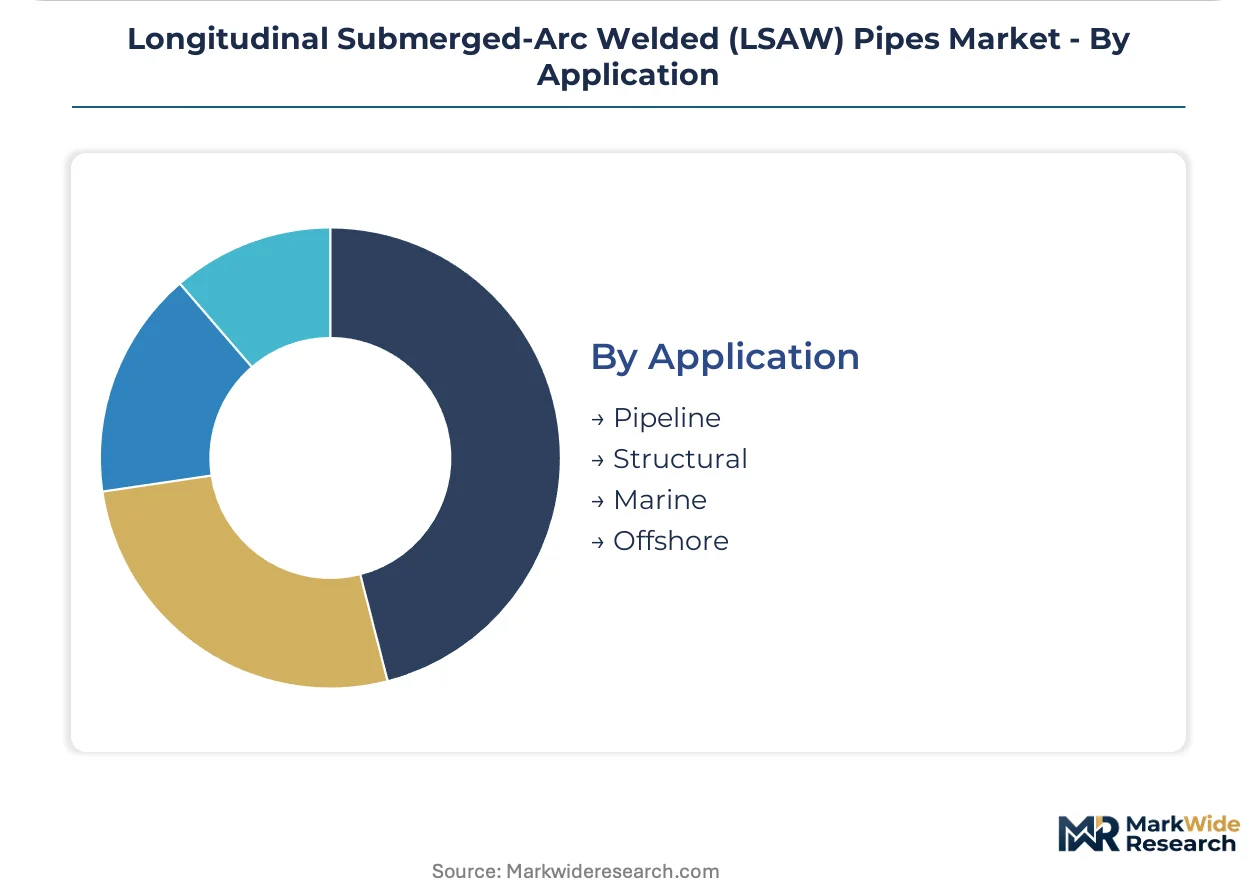
Application:
Customer type separates specification intensity, with offshore operators demanding full-service bundles unavailable to structural fabricators.
- Pipeline:Hydrocarbon and water transmission requiring longitudinal seam integrity over thousands of kilometers. German transmission system operators under EU methane reduction frameworks now mandate enhanced joint testing that disqualifies second-tier fabricators.
- Offshore:Deepwater tiebacks and floating production systems specifying TMCP plates for fatigue resistance. Gulf of Mexico and Brazilian pre-salt developments drive coated segment premiums for corrosion protection in splash zones.
- Structural:Building frameworks and bridge piling with lower pressure ratings.
- Marine:Port infrastructure and coastal protection requiring cathodic compatibility.
Pipeline application holds the largest share; momentum sits with Offshore as deepwater project sanctions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for sour-service grades concentrates in German and Japanese integrated mills, while Indian and Chinese fabricators compete on standard-grade volume tenders where metallurgical premiums collapse.
China
Domestic pipeline network expansion and Belt and Road export contracts drive plate mill utilization in Hebei and Jiangsu provinces. GB standards and MIIT industrial policy mandate domestic content thresholds for critical infrastructure. The Yangtze River Delta cluster hosts plate-to-pipe integrated facilities serving Southeast Asian offshore projects.
India
The Petroleum and Natural Gas Regulatory Board's accelerated trunk pipeline approvals concentrate 48-56 inch diameter demand along the west coast. BIS certification requirements and PLI scheme incentives favor domestic fabrication over imports. Gujarat's Dahej and Hazira industrial corridors host the country's largest LSAW pipe complexes.
United States
FERC interstate certificate approvals and Permian Basin takeaway constraints sustain large-diameter procurement from Gulf Coast plate suppliers. API 5L PSL2 Charpy testing mandates harden qualification barriers for imported pipe. Texas and Louisiana fabrication yards anchor North American supply for cross-border Mexican and Canadian tie-ins.
Germany
EU F-Gas Regulation coating facility constraints and methane reduction frameworks tighten joint integrity specifications for North Sea offshore pipelines. ECHA chemical compliance and national hydrogen backbone funding redirect plate mill output toward hydrogen-rated grades. The Ruhr industrial region maintains specialized sour-service plate capacity unavailable in Southern European mills.
Saudi Arabia
Red Sea offshore project sanctions and petrochemical corridor expansion concentrate extra-large diameter procurement in domestic fabrication zones. The National Industrial Development Center's localization incentives require joint venture structures for foreign pipe suppliers. The Eastern Province's Jubail industrial city hosts integrated plate-to-pipe facilities serving Gulf Cooperation Council transmission networks.
Longitudinal Submerged-Arc Welded (LSAW) Pipes Market Competitive Landscape
Concentration sits with integrated steel-pipe producers possessing captive plate mills and in-house coating infrastructure. The vendor base stratifies across three tiers: global integrated mills commanding sour-service premiums, regional scale fabricators competing on standard-grade volume, and project-specific specialists serving niche offshore applications. Two dominant competitive moves define current positioning: backward integration into high-grade plate supply and bundling of pipe supply with field joint coating and integrity management services.
Among German integrated producers, EUROPIPE GmbH exemplifies the captive-mill archetype through its Ruhr-based manufacturing complex. JFE Steel Corporation represents Japanese metallurgical specialization for high-strength sour-service environments. Welspun Group anchors the scale-driven tier with its west Indian coastal facility serving domestic trunk line and Middle East export contracts.
| Leading Market Players |
|---|
| Jindal Saw |
| EUROPIPE GmbH |
| JFE Steel Corporation |
| Tenaris S.A. |
| Nippon Steel Corporation |
| Welspun Group |
| EEW Group |
| TMK |
| ArcelorMittal |
| Others |
Value Network & Pricing Analysis
API 5L PSL2 certification gates both supply qualification and price differentiation, restricting sour-service grade production to integrated mills with captive plate capacity while allowing certified producers to command metallurgical premiums over standard-grade fabricators.
Pricing Analysis
Configured-to-order pricing for sour-service grades with HIC-resistant metallurgy commands 15-25% premiums over standard API 5L PSL1 material. Three-tier pricing structure across premium, standard, and economy levels separates coated offshore segments from municipal water transmission and structural piling applications. Cost compression in standard grades is intensifying because spiral-weld substitution erodes LSAW volume in low-pressure water transmission. Municipal water utilities in India and China exhibit highest price sensitivity, while North Sea offshore operators prioritize joint integrity over unit cost.
Supply Chain Analysis
Extended lead times for high-grade sour-service plate concentrate inventory risk among integrated producers in China, Japan, and Germany. Steel plate supply draws from blast furnace and electric-arc furnace routes, with thermomechanically controlled processing capacity tethered to specialized rolling mills. Single-source vulnerability concentrates in extra-large diameter segments above 64 inches, where only Japanese, German, and Chinese integrated mills maintain qualified supply. Distribution runs through EPC contractors bundling pipe supply with field joint coating and integrity management services for cross-border trunk line projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LSAW pipes market sits in a cyclical recovery phase as trunk pipeline replacement cycles in mature markets and offshore project sanctions drive procurement volume.
For Market Incumbents: Shield market position by deepening backward integration into high-grade plate supply and investing in automated ultrasonic testing infrastructure that satisfies German and Dutch transmission system operator mandates. Spiral-weld substitution in non-critical water transmission represents the primary volume threat, while API 5L PSL2 certification barriers protect sour-service margins. For New Entrants and Emerging Players: Field joint coating and integrity management bundling represents a service-layer gap where incumbents under-serve, creating white-space for specialized contractors to capture procurement consolidation in Indian and U.S. cross-border transmission projects. Hydrogen-rated LSAW grades for Germany's SINTEG funding clusters offer the most penetrable segment, with go-to-market traction through EPC partnership structures rather than direct mill competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across extra-large diameter segments as furnace control upgrades and coating facility investments strain mid-tier producer balance sheets. Five-to-ten year viability favors integrated mills with electric-arc furnace plate supply and in-house coating infrastructure. Watch German ECHA chemical compliance and EU carbon-border adjustment implementation as inflection indicators for procurement criteria embedding emissions accounting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plate Supply | Captive steel plate mills eliminate single-source dependency for sour-service grades in German and Japanese facilities. |
| Automated Ultrasonic Testing Deployment | Enhanced seam weld inspection satisfies EU methane reduction frameworks and disqualifies second-tier fabricators. |
| Hydrogen-Rated Grade Development | API 5L compliant sour-service metallurgy positions mills for Germany's SINTEG and EU Hydrogen Backbone procurement. |
| Integrated Service Contract Bundling | Pipe supply combined with field joint coating captures EPC consolidation in Indian and U.S. cross-border projects. |
| Electric-Arc Furnace Plate Conversion | Scope 3 emissions reduction aligns with carbon-adjusted tender criteria from European transmission system operators. |
Research Methodology
Initial hypotheses were tested against primary input from pipeline procurement managers at transmission system operators, EPC contract engineers, plate mill metallurgists, and coating facility technical directors, and refined through secondary validation against API certification databases, FERC interstate certificate filings, customs trade records, and national pipeline regulator approval logs. Bottom-up volume estimates from fabrication yard capacity utilization were triangulated against top-down demand projections from trunk line project sanction databases.
Variance decomposition across product type, diameter class, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by certification tier and coating specification intensity. Forecast inputs incorporated plate mill capacity expansion announcements, national pipeline network development plans from India's Petroleum and Natural Gas Regulatory Board, and EU F-Gas Regulation coating facility constraint timelines.
Forecasts assume regulatory continuity in API 5L and ISO 3183 certification regimes; material policy shifts in methane reduction frameworks or carbon-border adjustment mechanisms would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Ultra Low Sulphur Fuel Oil (ULSFO) Market
Petroleum Products
Tar Oil Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Refined Petroleum Products Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Market