
 Global Petroleum Pitch Market | 2026-2036
Global Petroleum Pitch Market Size, Share, and Industry Trends Forecast 2026-2036
Global Petroleum Pitch Market Foresight
The divergence between premium carbon fiber-grade pitch and commodity electrode binder pitch is shifting procurement standards across the value chain. Himadri Speciality Chemical Ltd. leverages integrated coal tar distillation to control feedstock quality for anode applications. Resonac Holdings Corporation anchors its position through advanced mesophase pitch technology for aerospace carbon fiber precursors. Rain Carbon Inc. competes via global refinery partnerships that secure heavy residue streams across multiple continents.
Petroleum pitch is a heavy aromatic residue derived from catalytic cracking and thermal processing of petroleum feedstocks, characterized by softening points between 100°C and 200°C and a carbon yield exceeding 50 percent for high-performance grades. Its primary industrial purpose centers on serving as a precursor for carbon fiber production and as a binder matrix in graphite electrodes for electric arc furnaces. Refined pitch commands premium positioning in battery anode applications where low impurity thresholds determine performance. Carbonized pitch dominates volume flows into steel manufacturing electrodes, though margin pools are thinning amid feedstock cost volatility. Soft pitch sustains steady demand within roofing and waterproofing segments where formulation flexibility outweighs carbon yield requirements.
The US EPA regulates polycyclic aromatic hydrocarbon emissions from pitch coking operations, while REACH in Europe imposes strict registration requirements on imported coal tar and petroleum-derived pitch products. China's MEE enforces dual carbon targets that restrict high-sulfur residue processing, reshaping regional supply availability. Japan's METI maintains JIS standards for carbon fiber precursor quality that filter market access for lower-grade imports. Stakeholders must monitor evolving battery-grade certification protocols as automotive OEMs tighten anode material traceability requirements.
Market Dynamics
The battery anode supply chain is compressing qualification timelines for carbonized pitch precursors as automotive OEMs enforce traceability mandates from mine to cell, forcing feedstock processors to upgrade impurity detection protocols and secure dual-source distillation capacity.
Growth Catalysts
- MIIT Dual Carbon Goals:China's tightening feedstock qualification rules for electrode-grade materials are filtering out high-sulfur residue processors and redirecting procurement toward certified low-impurity streams.
- Carbon Fiber Clusters:Demand concentration in Jiangsu Province is pulling specialized mesophase pitch production toward coastal China, creating localized supply ecosystems that reduce logistics costs for aerospace precursor manufacturers.
- Electric Arc Furnace Expansion:Steel decarbonization mandates across multiple jurisdictions are sustaining electrode binder pitch consumption even as blast furnace capacity contracts.
Market Restraints
- Heavy Residue Cost Volatility:Refinery throughput fluctuations and crude slate shifts create input price instability that compresses margin pools for commodity-grade pitch processors.
- Supply Concentration Risk:Distillation capacity clusters in China's coal tar belt and US Gulf Coast refineries create geographic chokepoints vulnerable to regional environmental enforcement actions.
- Polycyclic Aromatic Hydrocarbon Emissions Controls:US EPA coking operation regulations impose capital-intensive abatement requirements that disadvantage smaller batch processors.
Strategic Opportunities
- Battery Anode Certification Gap:Automotive OEM material traceability requirements have outpaced standardized testing protocols, creating first-mover advantage for processors who establish JIS-compliant precursor quality systems.
- Refinery Partnership Models:Long-term offtake agreements with catalytic cracking operators in the Middle East and North America are securing heavy residue streams outside traditional trading channels.
- Roofing Formulation Flexibility:Soft pitch segments in waterproofing applications remain undersupplied by specialized processors, allowing margin recovery through formulation customization services.
Industry Challenges
- Mesophase Pitch Talent Scarcity:The specialized knowledge required for controlled carbonization and optical texture optimization resides with a limited cohort of researchers, constraining capacity expansion timelines.
- Dual-Grade Certification Complexity:Processors serving both aerospace carbon fiber and battery anode markets must maintain parallel quality systems under divergent JIS and emerging automotive protocols.
- Legacy Distillation Asset Retrofit Costs:Converting coal tar distillation trains to handle petroleum-derived feedstocks requires furnace modifications and emission control upgrades that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Petroleum Pitch Market |
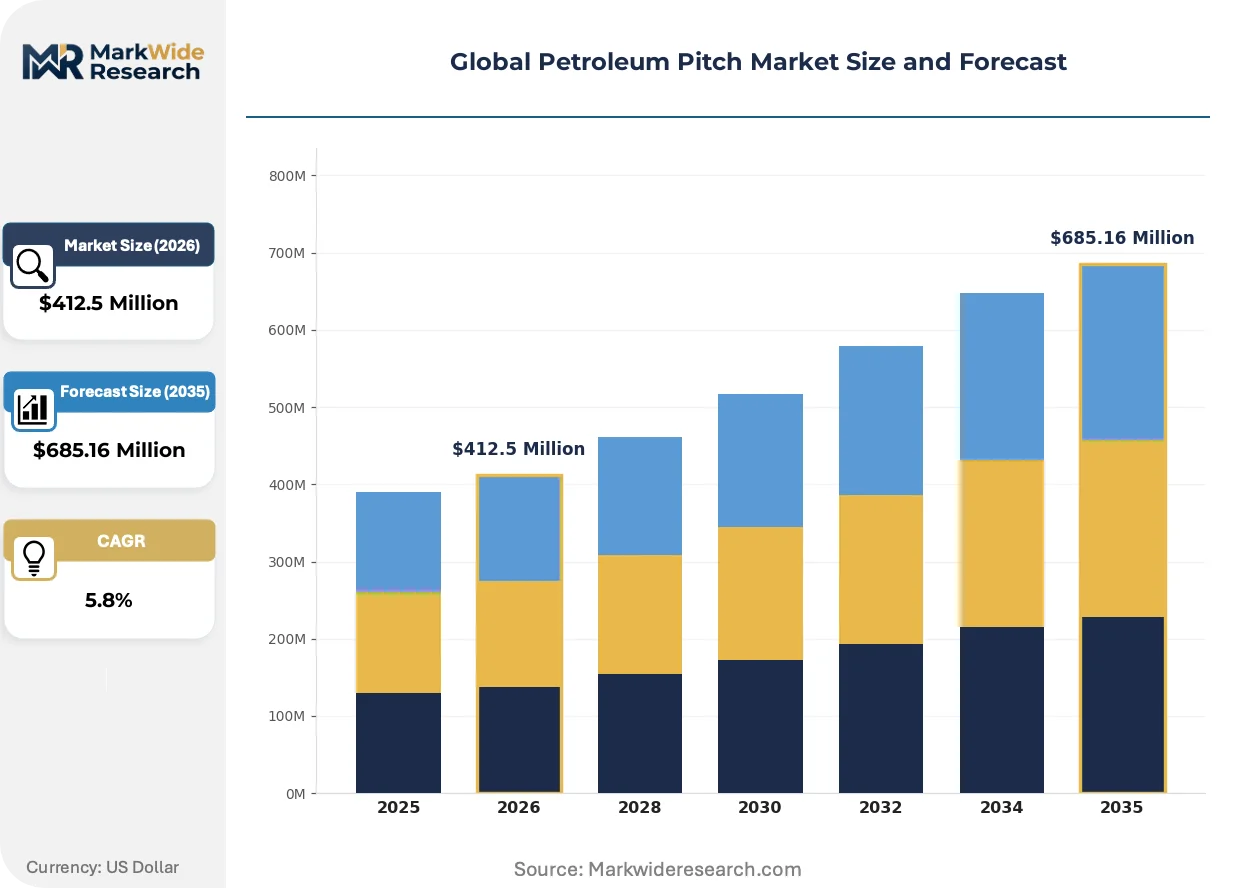
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Pitch, Unrefined Pitch, Carbonized Pitch, Soft Pitch, Hard Pitch Application: Carbon Fibers, Electrodes, Battery Anodes, Roofing Materials, Waterproofing Agents Feedstock Source: Coal Tar, Petroleum Residue, Byproduct Tar, Pyrolysis Oil, Heavy Fuel Oil End User Industry: Steel Manufacturing, Aluminum Production, Battery Manufacturing, Construction, Chemical Processing |
| Companies Covered | Himadri Speciality Chemical Ltd., Resonac Holdings Corporation, Rain Carbon Inc., JFE Chemical Corporation, C-Chem Carbon Materials Co., Mitsubishi Chemical Group, Nippon Steel Corporation, Solvay AG, Koppers Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Petroleum Pitch Market Shifts & Advancements
Process intensification and digital quality assurance are compressing the gap between laboratory-scale mesophase development and commercial precursor production, while regulatory fragmentation across battery supply chains is forcing parallel certification investments.
Solvent extraction-based mesophase pitch refining is absorbing the limitations of traditional thermal polymerization methods by enabling lower-temperature processing with tighter molecular weight control. Battery anode manufacturers in South Korea and Japan are adopting this technology ahead of European counterparts, drawn by its compatibility with silicon-carbon composite anode architectures. The shift is absorbing market share from conventional thermal routes and compressing the premium commanded by legacy aerospace-grade suppliers.
REACH registration requirements for imported coal tar and petroleum-derived pitch products are tightening substance documentation obligations for non-EU processors seeking European market access. The regulation's industrial consequence is a bifurcation between integrated producers with in-house analytics capabilities and traders dependent on third-party testing. Carbon fiber precursor segments are most affected, with several Asian suppliers accelerating EU-authorised representative appointments to maintain supply continuity.
Automotive OEMs are unbundling material certification from volume procurement contracts, creating standalone qualification fees that alter supplier selection economics. Tier-1 anode manufacturers are responding by consolidating qualified precursor sources rather than diversifying across marginal suppliers, concentrating procurement leverage with established mesophase pitch processors. This pattern is most visible in German and Japanese battery supply chains, where OEM traceability mandates have compressed supplier onboarding timelines from years to months.
Global Petroleum Pitch Market Segmentation
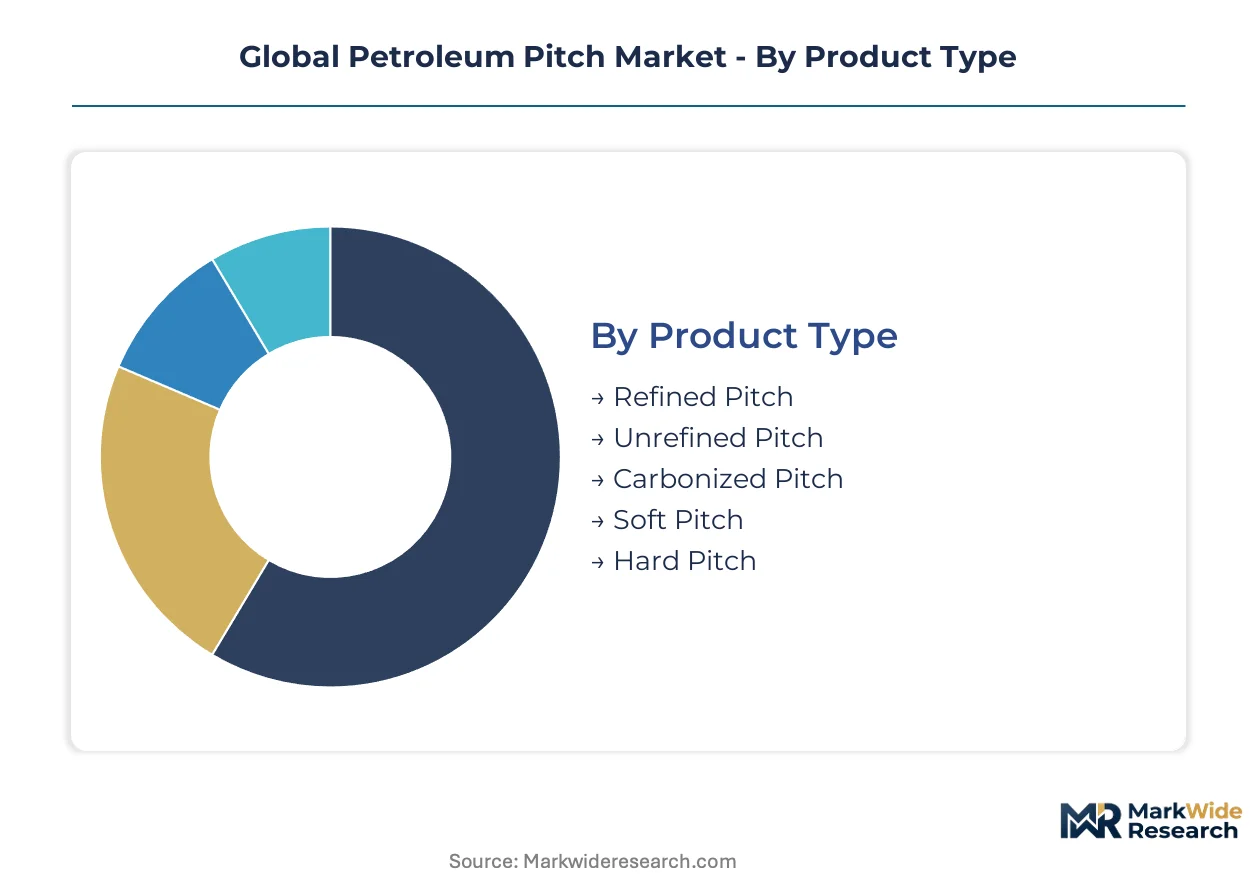
Segmentation in petroleum pitch markets tracks divergent certification burdens across battery anode, aerospace carbon fiber, and steel electrode applications. Each segment carries distinct impurity thresholds and traceability mandates that reshape procurement economics.
Product Type:
Certification burdens vary sharply: carbonized pitch for battery anodes faces automotive OEM traceability protocols, while soft pitch for roofing navigates simpler formulation standards.
- Refined Pitch:Ultra-low sulfur and ash content below 0.1 percent enables qualification for lithium-ion anode precursors. Demand concentrates in South Korean battery supply chains where cathode manufacturers enforce dual-source distillation requirements. Automotive material traceability mandates from German and Japanese OEMs are compressing supplier onboarding timelines.
- Carbonized Pitch:High carbon yield exceeding 55 percent supports graphite electrode binder applications in electric arc furnace steelmaking. Jiangsu Province carbon fiber clusters pull specialized production toward coastal China, creating localized supply ecosystems that reduce logistics costs for aerospace precursor manufacturers. China's MIIT dual carbon goals filter out high-sulfur residue processors.
- Unrefined Pitch:Raw distillation output with minimal post-processing serves lower-specification roofing and waterproofing markets.
- Soft Pitch:Lower softening points between 100°C and 140°C prioritize formulation flexibility over carbon yield in construction applications.
- Hard Pitch:Elevated softening points above 180°C suit carbonization-intensive processes requiring dimensional stability.
Refined pitch sits at the top of the volume ranking, with carbonized pitch climbing the fastest.
Application:
Cost tiers separate premium aerospace precursors from commodity electrode binders, with battery anodes commanding intermediate pricing based on purity premiums.
- Carbon Fibers:Mesophase pitch precursors require optical texture optimization and controlled carbonization expertise. Japan's METI JIS standards filter market access for lower-grade imports, concentrating qualified supply with established aerospace processors. Solvent extraction refining is absorbing share from thermal polymerization routes.
- Battery Anodes:Silicon-carbon composite architectures demand low-impurity carbonized pitch with documented feedstock provenance. South Korean and Japanese manufacturers lead adoption of solvent extraction technology ahead of European counterparts. OEM unbundling of certification from procurement contracts alters supplier selection economics.
- Electrodes:Graphite electrode binders sustain steady consumption through steel decarbonization mandates across multiple jurisdictions.
- Roofing Materials:Soft pitch formulations prioritize cost efficiency and weathering resistance over carbon yield metrics.
- Waterproofing Agents:Bitumen-compatible pitch derivatives serve infrastructure durability requirements with minimal processing overhead.
Electrode applications dominate current volume flows, with battery anodes expanding most quickly.
Feedstock Source:
Supply concentration clusters create geographic chokepoints, with petroleum residue streams concentrated in US Gulf Coast refineries and China's coal tar belt.
- Petroleum Residue:Catalytic cracking heavy streams from Middle Eastern and North American refineries anchor global supply. Long-term offtake agreements outside traditional trading channels secure stream continuity for integrated processors. Crude slate shifts create input price instability that compresses margin pools.
- Coal Tar:High aromaticity supports premium carbon fiber precursor production with established distillation infrastructure in China's industrial heartland. Legacy asset retrofit costs strain mid-cap balance sheets converting trains to handle petroleum-derived alternatives. REACH registration requirements tighten substance documentation obligations for European market access.
- Byproduct Tar:Steel coking operations generate regionally concentrated supply tied to blast furnace economics.
- Pyrolysis Oil:Emerging circular feedstock from waste tire and plastic thermal decomposition offers sustainability positioning.
- Heavy Fuel Oil:Residual marine and power generation streams provide cost-competitive inputs for lower-specification applications.
Petroleum residue leads absolute volume, with pyrolysis oil gaining share fastest.
End User Industry:
Customer maturity separates steel manufacturing's established procurement protocols from battery manufacturing's evolving qualification frameworks.
- Battery Manufacturing:Automotive OEM traceability mandates from mine to cell force feedstock processors to upgrade impurity detection protocols. Tier-1 anode manufacturers consolidate qualified precursor sources rather than diversifying across marginal suppliers. German and Japanese supply chains show compressed supplier onboarding timelines.
- Steel Manufacturing:Electric arc furnace expansion sustains electrode binder pitch consumption even as blast furnace capacity contracts. US EPA polycyclic aromatic hydrocarbon emissions controls impose capital-intensive abatement requirements. Environmental enforcement actions create vulnerability at geographic chokepoints.
- Aluminum Production:Smelter anode binders require moderate purity pitch with consistent volatile matter content.
- Construction:Roofing and waterproofing segments remain undersupplied by specialized processors, allowing margin recovery through formulation customization services.
- Chemical Processing:Carbon black and specialty chemical feedstocks absorb lower-grade pitch with flexible specification tolerances.
Steel manufacturing holds the volume lead, with battery manufacturing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized carbonization engineers and mesophase researchers concentrate in Japan's Kansai corridor and Germany's Ruhr industrial belt, anchoring global precursor quality standards. Their expertise filters market access through certification protocols that reshape regional supply flows.
China
Jiangsu Province carbon fiber clusters pull specialized mesophase pitch production toward coastal manufacturing zones. MIIT dual carbon goals tighten feedstock qualification rules for electrode-grade materials, filtering out high-sulfur residue processors. Xuzhou and Nantong industrial parks host integrated distillation-to-precursor operations serving battery anode supply chains.
Japan
METI JIS standards for carbon fiber precursor quality concentrate qualified supply with established aerospace processors. Osaka-based research institutes anchor mesophase pitch optical texture optimization expertise. Nagoya industrial corridors host precursor qualification laboratories serving tier-1 anode manufacturers.
United States
US Gulf Coast refineries concentrate petroleum residue distillation capacity vulnerable to EPA polycyclic aromatic hydrocarbon enforcement actions. Houston and Beaumont processing clusters secure heavy catalytic cracking streams through long-term offtake agreements. Texas-Louisiana corridor infrastructure supports both electrode binder and specialty precursor production.
Germany
REACH registration requirements tighten substance documentation obligations for imported pitch products seeking European market access. Ruhr Valley chemical processing heritage anchors carbon material research capabilities. Leverkusen and Marl industrial sites host integrated analytics laboratories serving dual aerospace and battery certification protocols.
South Korea
Battery anode manufacturers in Gyeonggi Province lead adoption of solvent extraction refining technology ahead of European counterparts. Domestic cathode producers enforce dual-source distillation requirements on precursor suppliers. Incheon and Pyeongtaek industrial zones concentrate silicon-carbon composite anode development clusters.
Global Petroleum Pitch Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across petroleum pitch value chains, with integrated refiners controlling feedstock access while specialized processors capture premium certification margins. The vendor base separates into three strategic archetypes: coal tar heritage operators with legacy distillation assets, petroleum refinery affiliates securing residue streams, and technology licensors monetizing mesophase process patents. Consolidation pressure intensifies as automotive OEM traceability mandates compress supplier onboarding timelines. Dominant competitive moves include backward integration into catalytic cracking operations and parallel certification investments under divergent JIS and emerging battery-grade protocols.
Within the integrated refinery-affiliate tier, Rain Carbon Inc. exemplifies global heavy residue sourcing through multi-continent partnerships, while Himadri Speciality Chemical Ltd. occupies a position representing coal tar heritage operators leveraging in-house distillation control. Resonac Holdings Corporation anchors the technology-specialist vector through advanced mesophase pitch process positioning. These three entities collectively illustrate how feedstock security, certification depth, and optical texture expertise separate viable competitors from marginal suppliers in tightening qualification environments.
| Leading Market Players |
|---|
| Himadri Speciality Chemical Ltd. |
| Resonac Holdings Corporation |
| Rain Carbon Inc. |
| JFE Chemical Corporation |
| C-Chem Carbon Materials Co. |
| Mitsubishi Chemical Group |
| Nippon Steel Corporation |
| Solvay AG |
| Koppers Inc. |
| Others |
Supply & Pricing Matrix
Automotive OEM traceability mandates from German and Japanese manufacturers are compressing supplier onboarding timelines, forcing feedstock processors to absorb dual-certification costs that stratify pricing across JIS-compliant and emerging battery-grade tiers.
Pricing Analysis
Unbundled certification fees now separate from volume procurement contracts dominate supplier selection economics, with automotive OEMs charging standalone qualification costs that favor established mesophase pitch processors over marginal entrants. Price differentiation hinges on optical texture grade and REACH registration completeness, with premium aerospace precursors commanding substantial premiums over commodity electrode binders. Cost compression in carbonized pitch runs through heavy residue cost volatility at US Gulf Coast refineries. Roofing and waterproofing segments exhibit highest price sensitivity due to formulation flexibility requirements, while battery anode manufacturers show lowest sensitivity given purity threshold non-negotiability.
Supply Chain Analysis
Qualification gating through JIS standards and emerging automotive protocols concentrates qualified supply with established Japanese and South Korean processors, filtering market access for lower-grade imports. Geographic supply concentration clusters in China's Jiangsu Province, Japan's Kansai corridor, and the US Gulf Coast refinery belt. Raw material dependencies draw from catalytic cracking heavy streams, coal tar distillation outputs, and emerging pyrolysis oil feedstocks. Single-source vulnerability at geographic chokepoints creates structural risk from regional environmental enforcement actions. Distribution runs through long-term offtake agreements with tier-1 anode manufacturers and aerospace precursor specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as electric arc furnace steel decarbonization mandates and battery anode procurement expansion create durable demand foundations across multiple industrial verticals.
For Market Incumbents: Hedge against mesophase pitch talent scarcity by securing exclusive research partnerships with Osaka-based optical texture optimization institutes and Nagoya precursor qualification laboratories. Defend margin position through backward integration into catalytic cracking operations in the Middle East and North America, securing heavy residue streams outside volatile trading channels. Prioritize parallel certification investments under divergent JIS and emerging automotive protocols to maintain qualification breadth. For New Entrants and Emerging Players: Underserved roofing and waterproofing segments offer penetrable white-space where formulation customization services command margin recovery opportunities absent from saturated aerospace precursor competition. Target soft pitch applications in construction markets where specification flexibility outweighs carbon yield requirements and incumbent processors underinvest. Pursue go-to-market angles emphasizing solvent extraction technology compatibility with silicon-carbon composite anode architectures to differentiate from legacy thermal polymerization routes. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-specialist processors possessing advanced mesophase pitch patents and established JIS-compliant quality systems, positioned to capture certification-premium expansion as automotive traceability mandates tighten. Long-term viability over a multi-year horizon favors acquisition targets with dual-grade certification capability spanning aerospace carbon fiber and battery anode markets. Monitor inflection signals through OEM unbundling of material certification from procurement contracts, which accelerates supplier consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalytic Cracking | Secures heavy residue streams from Middle Eastern and North American refineries outside traditional trading channels. |
| Dual-Certification Quality System Investment | Enables parallel JIS aerospace and emerging automotive battery-grade protocol compliance. |
| Solvent Extraction Technology Licensing | Absorbs market share from thermal polymerization routes in South Korean and Japanese anode supply chains. |
| Long-Term Offtake Agreement with Tier-1 Anode Manufacturers | Consolidates procurement leverage with German and Japanese battery OEM traceability mandates. |
| EU-Authorised Representative Appointment | Maintains REACH-registered supply continuity for carbon fiber precursor segments seeking European market access. |
Research Methodology
Multiple input streams — primary interviews with carbon fiber procurement leads, battery anode manufacturing executives, and petroleum refinery operations managers; secondary validation through customs trade data, SEC filings from integrated processors, and MIIT regulatory disclosures; plus technical literature on mesophase pitch optical texture optimization — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against expert panel assessments of qualification timeline compression and feedstock cost volatility impacts. Segmentation dimensions modeled include product grade tier, end-use industry application, feedstock source origin, and regional production hub concentration. CAGRs were derived through iterative convergence of demand-side procurement expansion scenarios and supply-side distillation capacity constraints. Industry-specific forecast inputs incorporated electric arc furnace steel production trajectories and automotive OEM material traceability mandate adoption curves.
Underlying measurement precision varies by segment; refined pitch and carbonized pitch carry tighter precision than unrefined and soft pitch categories given more standardized certification protocols. Forecasts reflect assumptions regarding MIIT dual carbon goal enforcement continuity and EPA polycyclic aromatic hydrocarbon regulation stability. A model refresh is warranted upon material change in automotive OEM unbundling of certification from procurement contracts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Balanos Oil Market
Petroleum Products
Pale Oil Market
Petroleum Products
South Africa Petroleum Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Southeast Asia Refined Petroleum Products Market
Petroleum Products
India White Oil Market
Petroleum Products
Floating Roof Tank Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Petcoke Market
Petroleum Products
Base Oil Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Oil Refining Market