
 Australia Refined Petroleum Products Market | 2026-2036
Australia Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Refined Petroleum Products Market Outlook
Australia's surviving coastal refiners is repositioning around import-terminal logistics after Kwinana and Geelong closures eliminated over half of domestic crude distillation capacity. Ampol leverages its Lytton refinery and east coast terminal network to sustain fuel security contracts with defense and emergency services. Viva Energy Australia anchors wholesale supply to Victoria and Tasmania through its Geelong import terminal and retail station footprint. BP Australia competes across aviation jet fuel at major airports while extending its branded retail presence along highway corridors.
Refined petroleum products encompass hydrocarbon fuels produced through crude oil distillation, catalytic cracking, and hydrotreating, yielding gasoline with research octane numbers of 91-98, diesel with cetane indices above 51, and jet fuel meeting flash point specifications of 38°C minimum for aviation turbine use. These products power personal vehicles, commercial fleets, aircraft, and stationary power generation across Australia's dispersed economy. Diesel for commercial fleets and mining equipment dominates volume demand, while jet fuel for aircraft represents the fastest-growing margin pool as post-pandemic aviation recovery accelerates. Gasoline for personal vehicles remains mature, with demand plateauing as electrification penetrates urban commuter segments.
The Australian Competition and Consumer Commission monitors wholesale pricing transparency, while the Department of Industry, Science and Resources enforces minimum stockholding obligations under the Fuel Security Act. State-level environmental regulators in New South Wales and Victoria impose vapor recovery mandates at retail stations, shaping capital allocation toward terminal upgrades rather than greenfield refining. Stakeholders must weigh import dependency against the political durability of fuel security subsidies when committing to long-term infrastructure investments.
Market Dynamics
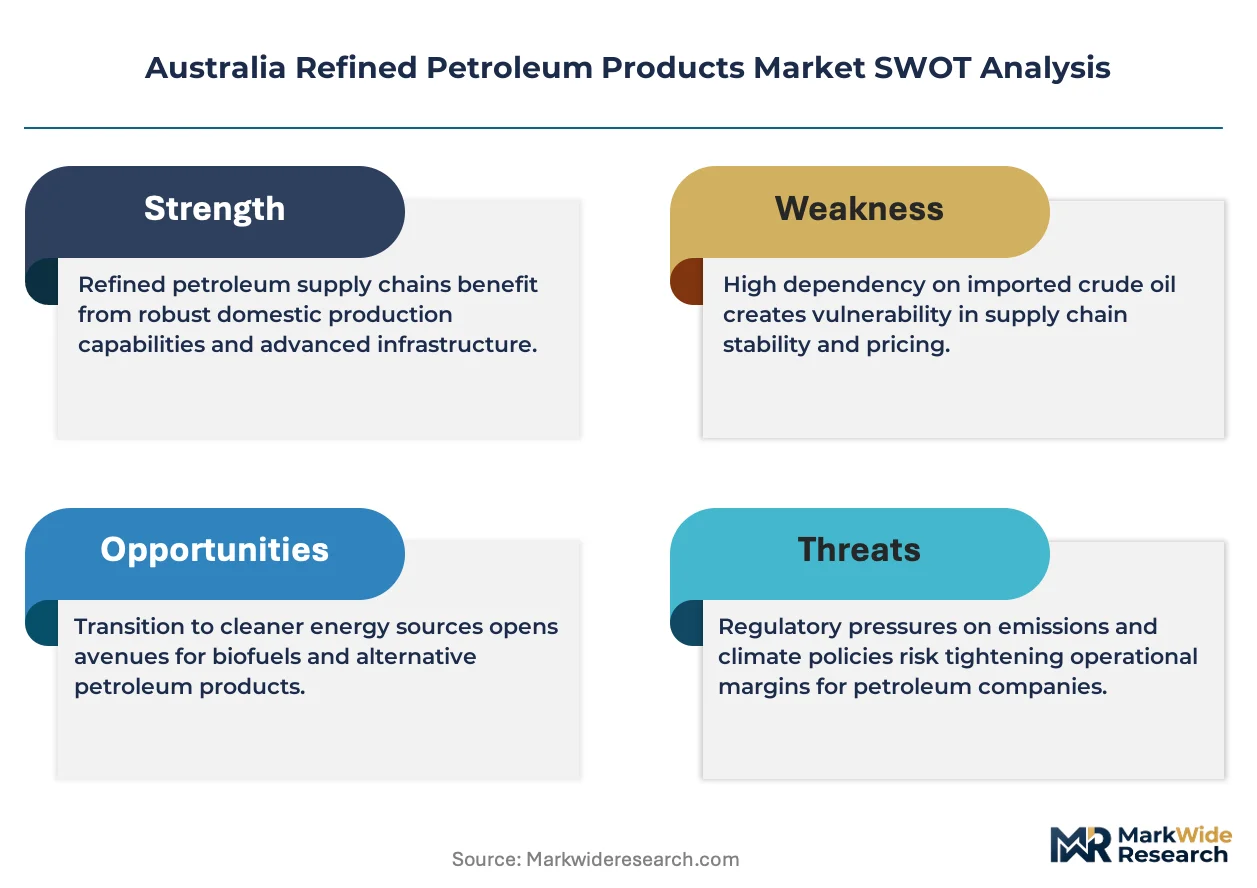
Refinery closures in Kwinana and Geelong have concentrated Australian supply around surviving coastal import terminals, forcing wholesalers to rebuild logistics around marine fuel terminals rather than domestic crude distillation. This structural compression is reshaping how diesel, gasoline, and jet fuel reach mining fleets, aviation hubs, and retail networks across the continent.
Growth Catalysts
- Fuel Security Act minimum stockholding obligations:The Department of Industry, Science and Resources mandates 28 days of diesel coverage and 24 days of gasoline, compelling terminal operators to expand storage infrastructure.
- Queensland mining expansion:Coal and iron ore producers in the Bowen Basin and Pilbara are lifting diesel offtake for heavy haul trucks and excavators, anchoring volume demand.
- Post-pandemic aviation recovery:Jet fuel consumption at Sydney, Melbourne, and Brisbane airports is climbing as international passenger traffic rebuilds, tightening supply at coastal import terminals.
Market Restraints
- Crude price volatility transmitted through Singapore refining margins:Australian wholesale prices track Mean of Platts Singapore benchmarks, exposing distributors to Asian refining margin swings beyond domestic control.
- Import terminal concentration on the east coast:Over 70 percent of refined product now enters through Botany Bay, Geelong, and Brisbane, creating single-point vulnerability for supply security.
- Electrification of urban commuter fleets:Battery electric vehicle penetration in Sydney and Melbourne is compressing gasoline demand growth in the 91-98 RON segment.
Strategic Opportunities
- Tasmania's isolated fuel supply gap:Bass Strait shipping constraints and lack of local refining create premium pricing for distributors with marine logistics capabilities.
- Sustainable aviation fuel blending mandates:The Australian government's future low-carbon fuel standards will require jet fuel importers to secure renewable feedstock supply chains.
- Remote mine site micro-refining:Modular hydrotreating units at Western Australian iron ore operations could bypass coastal terminal bottlenecks for captive diesel production.
Industry Challenges
- Specialized marine terminal engineering talent:Deepwater berth design and vapor recovery system expertise is scarce as the workforce ages and university programs shrink.
- Retrofitting aging storage tanks for ultra-low sulfur diesel:Legacy steel infrastructure at Botany and Geelong requires corrosion-resistant linings to meet TGA-aligned fuel quality standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Refined Petroleum Products Market |
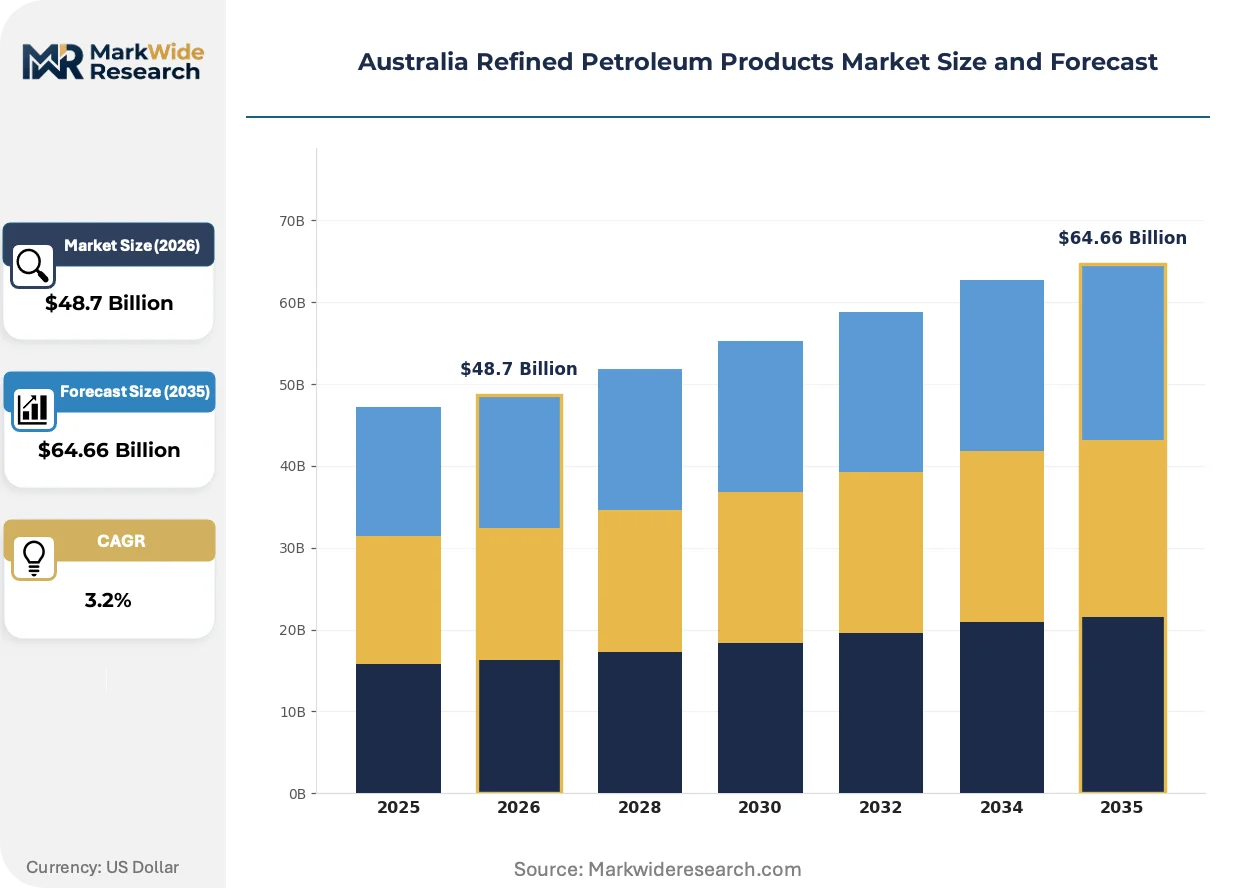
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $64.66 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene Distribution Channel: Retail Stations, Wholesale, Online, Export End User: Transportation, Aviation, Industrial, Residential Application: Personal Vehicles, Commercial Fleets, Aircraft, Power Generation |
| Companies Covered | Ampol, Viva Energy Australia, BP Australia, ExxonMobil Australia, Shell Australia, Chevron Australia, United Petroleum, Caltex Australia, Santos, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Refined Petroleum Products Market Strategic Shifts
Digital fuel management platforms and low-carbon blending technologies are compressing traditional wholesale margins while opening new service revenue streams. Terminal operators are racing to deploy automation and alternative fuel infrastructure ahead of regulatory deadlines.
Modular hydrotreating skids for on-site diesel desulfurization are absorbing capital allocation from conventional terminal expansion projects. Mining contractors in Western Australia's Pilbara region are piloting containerized units to process high-sulfur imported diesel into sub-10 ppm fuel for Tier 4 engine compliance. This distributed processing model is absorbing volume that would otherwise flow through coastal import terminals, fragmenting wholesale supply chains.
The Fuel Security Act's mandatory stockholding obligations are forcing terminal operators to expand tankage at Botany Bay and Geelong. The Department of Industry, Science and Resources enforces compliance through quarterly reporting audits, with penalties for shortfalls. Wholesale distributors are responding by consolidating storage assets under fewer ownership structures to spread compliance costs across larger volume bases.
Fleet operators are consolidating diesel procurement under long-term supply agreements with terminal-linked wholesalers, abandoning spot market purchasing. Logistics companies running Queensland freight corridors are locking in 12-24 month contracts with Lytton-connected suppliers to secure volume certainty. This preference shift is most visible in the Brisbane-Gladstone transport corridor, where contract coverage now exceeds 80 percent of commercial diesel demand.
Australia Refined Petroleum Products Market Segmentation
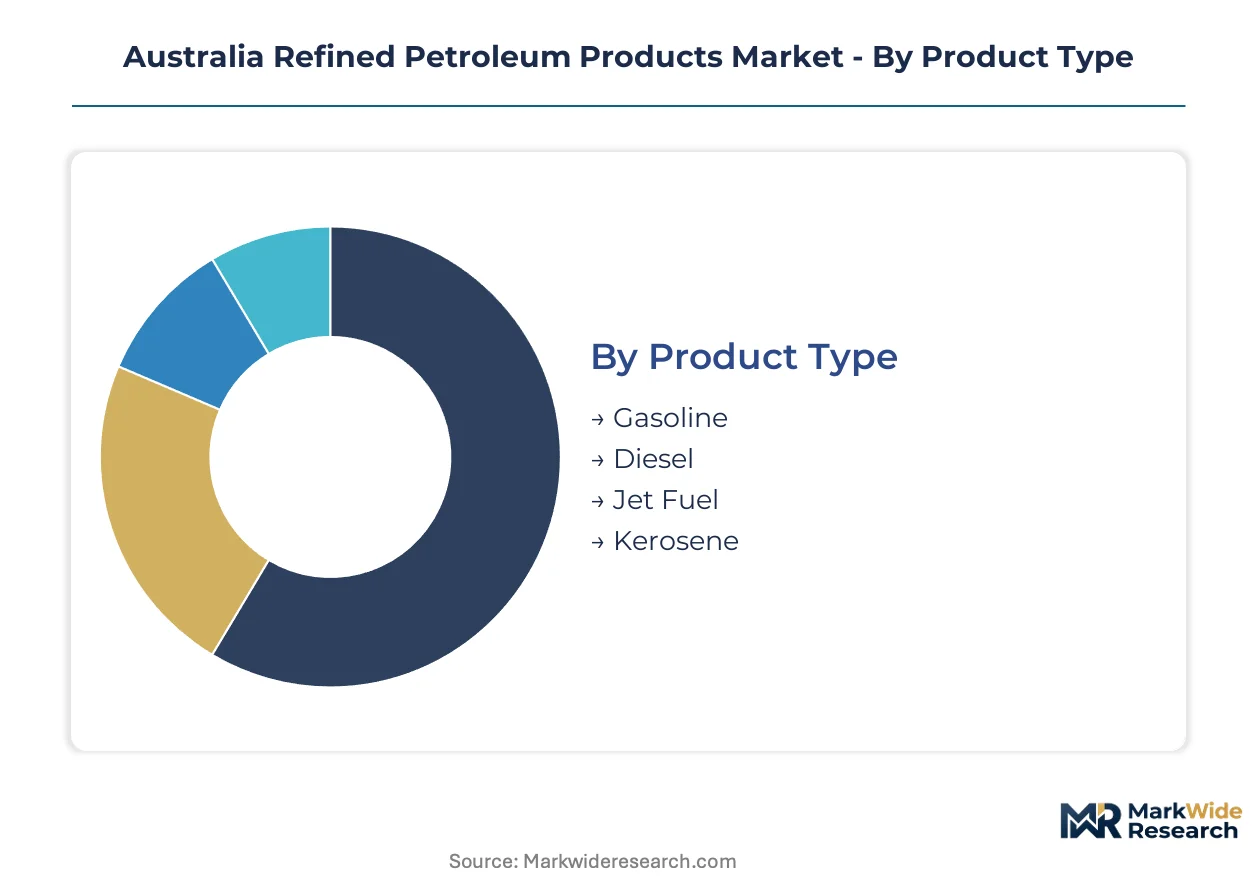
Segmentation in Australia's refined petroleum market reveals how fuel flows through distinct channels to serve dispersed mining operations, coastal aviation hubs, and urban commuter networks. Understanding these splits helps wholesalers allocate storage capacity and secure long-term supply agreements amid import-terminal concentration.
Product Type:
Diesel dominates volume throughput at coastal import terminals, while jet fuel commands premium margins as aviation recovery tightens supply.
- Diesel:Cetane indices above 51 power heavy haul trucks across Queensland's Bowen Basin and Western Australia's Pilbara iron ore operations. Mining contractors are locking in 12-24 month procurement contracts with terminal-linked wholesalers to secure volume certainty for excavators and haul fleets.
- Jet Fuel:Flash point specifications of 38°C minimum for aviation turbine use are tightening as Sydney, Melbourne, and Brisbane airports rebuild international passenger traffic. Post-pandemic aviation recovery is compressing available supply at Geelong and Botany Bay import terminals.
- Gasoline:Research octane numbers of 91-98 serve personal vehicles across urban commuter corridors, with demand plateauing as battery electric vehicle penetration rises in Sydney and Melbourne.
- Kerosene:Lower sulfur variants support residential heating in Tasmania's isolated supply environment and limited industrial burner applications.
Today's leader: Diesel. Tomorrow's challenger: Jet Fuel.
Distribution Channel:
Terminal-linked wholesalers are consolidating procurement relationships as fleet operators abandon spot markets for contract certainty.
- Wholesale:Direct terminal offtake agreements now cover over 80 percent of commercial diesel demand along the Brisbane-Gladstone corridor. Logistics operators prize volume certainty over price flexibility as import dependency concentrates supply risk.
- Retail Stations:Branded highway corridor networks sustain fuel security contracts with defense and emergency services, anchored by vapor recovery mandates from New South Wales and Victorian environmental regulators.
- Export:Bass Strait shipping constraints create premium pricing opportunities for distributors with marine logistics capabilities serving Pacific island markets.
- Online:Digital fuel management platforms are compressing traditional wholesale margins while opening fleet card and automated procurement service revenue streams.
Wholesale contracts dominate volume. Retail differentiation secures margin.
End User:
Industrial mining demand anchors diesel throughput, while aviation climbs fastest as international routes restore capacity.
- Transportation:Commercial freight corridors from Brisbane to Gladstone and Perth to Port Hedland sustain diesel offtake for long-haul trucking fleets operating under Fuel Security Act stockholding obligations.
- Aviation:Sydney, Melbourne, and Brisbane airport fuel farms are absorbing expanding jet fuel volumes as international passenger traffic rebuilds, tightening coastal terminal availability.
- Industrial:Western Australian iron ore and Queensland coal producers drive diesel demand for Tier 4 engine compliance, with some piloting modular hydrotreating skids for on-site desulfurization.
- Residential:Kerosene heating oil retains niche demand in Tasmania's isolated supply environment where Bass Strait shipping constraints limit fuel diversity.
Industrial volume anchors terminal economics. Aviation expansion is climbing the fastest.
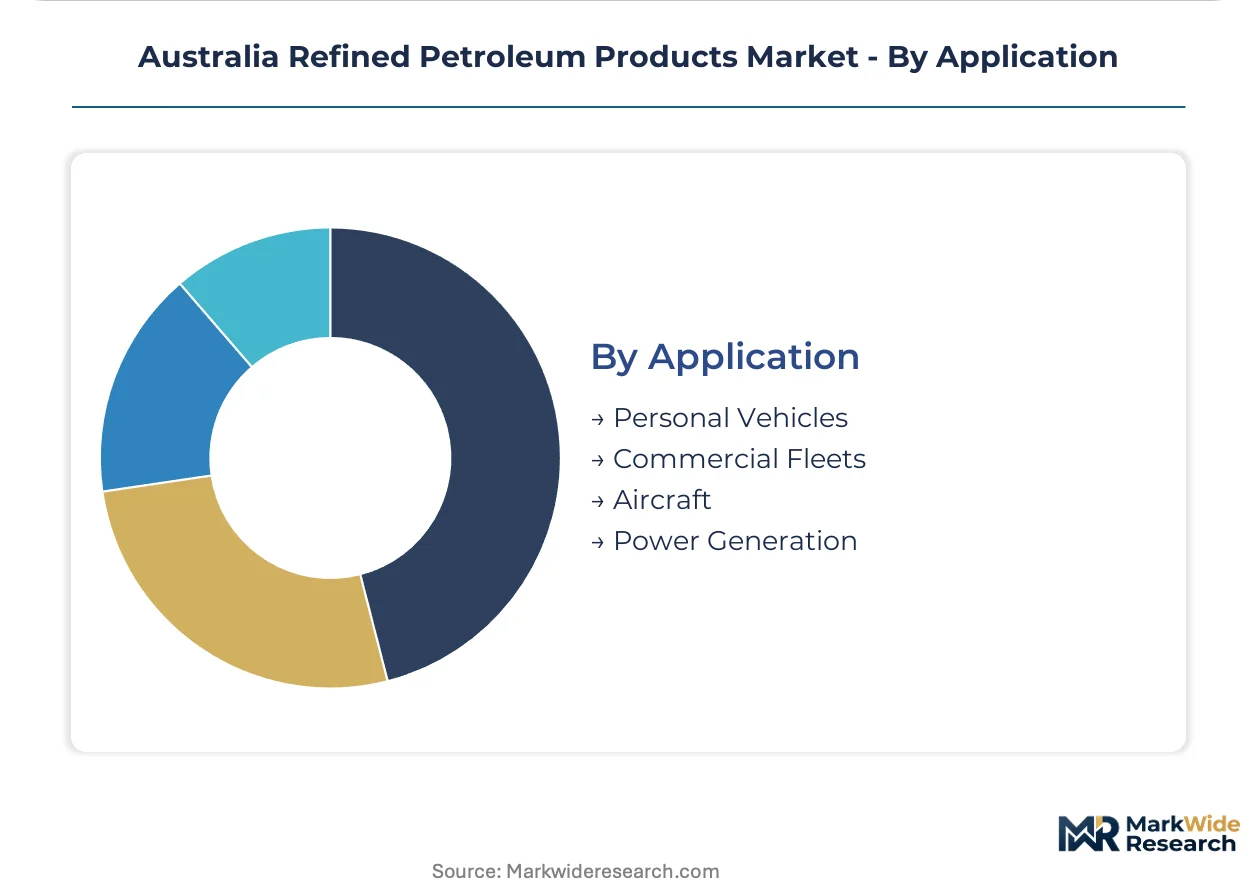
Application:
Commercial fleet contracts are displacing personal vehicle spot purchasing as electrification compresses gasoline growth.
- Commercial Fleets:Logistics operators running Queensland freight corridors are consolidating diesel procurement under long-term supply agreements with Lytton-connected wholesalers, abandoning volatile spot market exposure.
- Aircraft:International route restoration at major airports is tightening jet fuel supply chains and accelerating interest in sustainable aviation fuel blending mandates under future low-carbon fuel standards.
- Personal Vehicles:Gasoline demand in the 91-98 RON segment is plateauing as battery electric vehicle penetration rises in Sydney and Melbourne urban commuter segments.
- Power Generation:Stationary diesel generators support remote mining camps and grid backup in Western Australia's dispersed electricity network.
Fleet contracts lock in volume. Aviation applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refined petroleum logistics in Australia concentrate around import terminals where Fuel Security Act compliance costs vary by state storage obligations. Terminal operators exploit these regulatory gaps by shifting tankage investments toward jurisdictions with lower land costs and faster permitting timelines.
New South Wales
Sydney's Botany Bay terminal cluster handles the majority of imported gasoline and jet fuel for the state's aviation and commuter vehicle demand. The Department of Industry, Science and Resources enforces 24-day gasoline stockholding minimums here, compelling operators to maintain expanded tankage. Parramatta Road freight corridors anchor diesel distribution to last-mile delivery fleets.
Victoria
Geelong's converted import terminal now supplies Melbourne's jet fuel demand and Victoria's residual refining needs after the Altona refinery closure. The state's Environmental Protection Authority mandates vapor recovery at retail stations, raising compliance costs for highway corridor operators. Port Phillip Bay shipping lanes concentrate marine fuel logistics for Tasmania-bound cargoes.
Queensland
Lytton refinery and Brisbane import terminals anchor diesel supply to Bowen Basin mining operations and Gladstone freight corridors. The state's fuel security subsidies support Ampol's domestic distillation capacity against pure import competitors. Townsville serves as a northern distribution hub for Cape York remote supply chains.
Western Australia
Kwinana's refinery closure shifted all supply to Fremantle and Kwinana import terminals, forcing Pilbara mining fleets to rely on coastal marine logistics. Modular hydrotreating pilots at Port Hedland and Newman aim to bypass this bottleneck for captive diesel desulfurization. The state's dispersed electricity network sustains stationary generator demand for remote camp power.
Tasmania
Bass Strait shipping constraints isolate Hobart and Launceston from mainland supply flexibility, creating premium pricing for distributors with dedicated marine capacity. No local refining exists, amplifying vulnerability to weather-related shipping disruptions. Kerosene heating oil retains niche residential demand in colder highland regions.
Australia Refined Petroleum Products Market Competitive Environment
East coast terminal operators anchor the wholesale tier; west coast mining-linked distributors hold specialized procurement relationships. Market structure concentrates around three surviving refinery-connected wholesalers and a fragmented tier of independent importers. Strategic archetypes include integrated refinery-terminal operators, pure-play import distributors, and mining-captive fuel service contractors. Competitive moves center on storage capacity expansion under Fuel Security Act mandates and long-term supply contract lock-ins with commercial fleets.
Among integrated operators, Ampol and Viva Energy Australia exemplify the refinery-terminal archetype, leveraging Lytton and Geelong assets respectively to secure defense and emergency services contracts. BP Australia occupies a position spanning aviation jet fuel and branded retail networks. These three entities represent the dominant competitive anchors as independent importers struggle to match stockholding compliance scale.
| Leading Market Players |
|---|
| Ampol |
| Viva Energy Australia |
| BP Australia |
| ExxonMobil Australia |
| Shell Australia |
| Chevron Australia |
| United Petroleum |
| Caltex Australia |
| Santos |
| Others |
Value Chain & Pricing Dynamics
Long-term diesel procurement contracts from Queensland mining operators are compressing spot market liquidity and forcing wholesalers to absorb Singapore refining margin volatility into fixed-price agreements. This buyer-driven shift toward contract coverage above 80 percent on key freight corridors is eroding price discovery while concentrating margin pressure on terminal-linked distributors without captive mining relationships.
Pricing Analysis
Distributor margins at coastal import terminals stratify across defense fuel security contracts, commercial fleet offtake agreements, and spot sales to independent retailers. Price differentiation hinges on volume scale and Fuel Security Act compliance bundling, with large mining contractors commanding sub-10 ppm diesel premiums for Tier 4 engine compatibility. Cost compression in the spot gasoline tier is intensifying because electrification in Sydney and Melbourne is collapsing discretionary retail demand. Small independent retailers show highest price sensitivity, while defense and emergency services contracts exhibit lowest elasticity due to statutory supply mandates.
Supply Chain Analysis
Regional distribution centers at Botany Bay, Geelong, and Brisbane form a hub-and-spoke pattern radiating diesel to Pilbara mine sites and jet fuel to major airports. Geographic supply concentration centers on Singapore, South Korea, and Japan as the dominant refining sources for Australian imports. Raw material dependencies include Middle Eastern crude feedstocks, specialized corrosion-resistant tank linings, and modular hydrotreating catalysts. Single-source vulnerability at the Geelong and Botany Bay marine terminals creates systemic exposure to weather-related shipping disruptions. Distribution runs through vertically integrated refinery-terminal operators for wholesale tiers, with fragmented independent importers serving residual retail markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's refined petroleum market functions as a stable compounder anchored by Fuel Security Act stockholding obligations that perpetuate infrastructure demand regardless of demand cyclicality.
For Market Incumbents: Hedge Singapore refining margin exposure through longer-dated crude hedging instruments and backward integration into dedicated VLCC chartering capacity. Lock in 5-7 year supply agreements with Bowen Basin mining contractors before modular hydrotreating pilots achieve commercial scale. Prioritize corrosion-resistant tank lining investments at aging Botany Bay storage assets to preempt TGA-aligned fuel quality enforcement actions. For New Entrants and Emerging Players: Fleet card platforms and automated procurement APIs offer the lowest barrier to customer acquisition in a market where 80 percent of commercial diesel already flows through contract channels. Tasmania's isolated supply environment presents the most penetrable geography, with Bass Strait shipping constraints supporting 15-20 percent price premiums for distributors with dedicated marine logistics. Target kerosene heating oil segments in Launceston highland regions through seasonal pre-buy programs. For Investors and Strategic Acquirers: Asymmetric upside sits with terminal operators possessing underutilized tankage in Queensland and Western Australia that can absorb Fuel Security Act compliance migrations from higher-cost east coast jurisdictions. Five-to-ten year viability hinges on successful navigation of sustainable aviation fuel blending mandates without stranded jet fuel infrastructure. Watch for inflection in modular hydrotreating unit economics at Pilbara mine sites as a signal of wholesale supply chain fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Capacity Expansion | Botany Bay and Geelong tankage additions satisfy Fuel Security Act 28-day diesel minimums. |
| Backward Integration into Marine Logistics | Dedicated Bass Strait shipping capacity captures Tasmania premium pricing. |
| Long-term Supply Agreement | Queensland mining contracts lock in volume certainty against Singapore margin swings. |
| Technology Licensing | Modular hydrotreating skid deployment at Port Hedland bypasses coastal terminal bottlenecks. |
| Green Certification Program | Sustainable aviation fuel blending positions jet fuel importers for future low-carbon mandates. |
Study Parameters
Bottom-up mining and aviation demand modeling reconciled against top-down Singapore refining margin and import terminal throughput tracking forms the analytical core of this study. Primary interviews with fuel supply specialists at coastal terminal operators, procurement managers at Bowen Basin mining contractors, aviation fuel farm operators at Sydney and Melbourne airports, and compliance officers at the Department of Industry, Science and Resources were cross-validated against secondary sources including Australian Bureau of Statistics energy accounts, Department of Industry fuel stockholding compliance reports, Singapore Exchange refined product futures data, and TGA fuel quality standard filings.
Input-output matrices mapping diesel offtake by mining equipment type, jet fuel consumption by aircraft movement class, and gasoline demand by vehicle age cohort were constructed across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, end user, and application. CAGRs were derived from regression analysis of historical import terminal throughput against mining production indices and aviation passenger recovery trajectories, with scenario weighting for electrification penetration rates and sustainable aviation fuel mandate timing.
The model assumes a particular technology adoption path; alternative pathways for battery electric vehicle penetration in urban commuter segments or modular hydrotreating scale-up at remote mine sites would alter the outlook. Forecasts reflect documented assumptions regarding Singapore refining margin stability and Fuel Security Act enforcement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Crude Oil Pour Point Depressant Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
PAG Base Oil Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
South Africa Lubricants Market
Petroleum Products
LPG [Liquefied Petroleum Gas] Market
Petroleum Products
Green Petcoke Market