
 Refined Petroleum Products Market | 2026-2036
Refined Petroleum Products Market Size, Share, and Industry Trends Forecast 2026-2036
Refined Petroleum Products Market Intelligence
Multi-source crude procurement is hardening as the dominant supply strategy among integrated refiners seeking to mitigate geopolitical disruption. Chevron leverages its Permian Basin captive production to secure cost-advantaged domestic feedstock. Saudi Aramco anchors massive downstream complexes in Asia with long-term offtake agreements. Exxon Mobil sustains competitive economics through proprietary resid upgrading technology at its Gulf Coast facilities.
Refined petroleum products are hydrocarbon fuels and petrochemical feedstocks produced through fractional distillation, catalytic cracking, and hydrotreating of crude oil, with sulfur content, octane rating, and cetane index serving as critical quality specifications for engine compatibility and emissions compliance. The transportation application dominates absolute volume, with gasoline and diesel commanding the largest share of refinery yield configurations globally. Jet fuel represents the fastest-expanding product type as aviation networks rebuild capacity, while marine applications are shifting toward very low sulfur fuel oil to meet IMO 2020 standards.
The Environmental Protection Agency enforces Tier 3 gasoline sulfur limits in the United States, forcing refiners to operate hydrotreaters at maximum severity. The International Maritime Organization mandates global sulfur caps for bunker fuels, redirecting investment toward residue upgrading and gasoil blending capacity. The European Union's F-Gas Regulation and Fit for 55 package are accelerating refinery decarbonization timelines. Stakeholders must monitor carbon border adjustment mechanisms and alternative fuel mandates that threaten to strand conventional refining assets before the end of their design life.
Market Dynamics
Integrated refiners face a structural squeeze between IMO 2020 marine sulfur mandates and the EPA's Tier 3 gasoline specifications, forcing simultaneous residue upgrading investments and hydrotreater intensification that compress margin recovery windows.
Growth Catalysts
- Aviation Network Rebuild:Commercial airlines are restoring international route density, pulling jet fuel demand above pre-pandemic baselines in Asia-Pacific and Middle Eastern hub airports.
- IMO 2020 Compliance:The International Maritime Organization's sulfur cap is redirecting refinery investment toward very low sulfur fuel oil production and gasoil blending infrastructure.
- Resid Upgrading Technology:Proprietary hydrocracking and coking processes are unlocking value from heavy sour crude slates that conventional refining configurations cannot process profitably.
Market Restraints
- Crude Price Volatility:Feedstock cost swings tied to geopolitical disruption in major exporting regions compress refining margins unpredictably.
- Carbon Border Adjustments:The European Union's emerging carbon border adjustment mechanism threatens to penalize conventional fuel imports, stranding refinery investments before design-life expiration.
- Electrification Substitution:Battery electric vehicle penetration in light-duty transport is compressing long-term gasoline demand projections in OECD markets.
Strategic Opportunities
- India Demand Concentration:The country's transport fuel consumption is expanding faster than domestic refining capacity, creating import dependency that integrated players can capture through coastal storage and distribution infrastructure.
- Sustainable Aviation Fuel Mandates:The EU's ReFuelEU Aviation regulation is creating certified offtake obligations that co-processing investments can satisfy.
- Petrochemical Integration:Steam cracker and aromatics complex co-location is shifting refinery yield configurations toward higher-margin chemical feedstocks.
Industry Challenges
- Skilled Operator Scarcity:Advanced process control and digital twin implementation require automation engineers and data scientists that legacy refinery workforces lack.
- Compliance Timeline Compression:Simultaneous EPA, EU, and IMO regulatory deadlines are forcing parallel capital deployment that strains project management bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refined Petroleum Products Market |
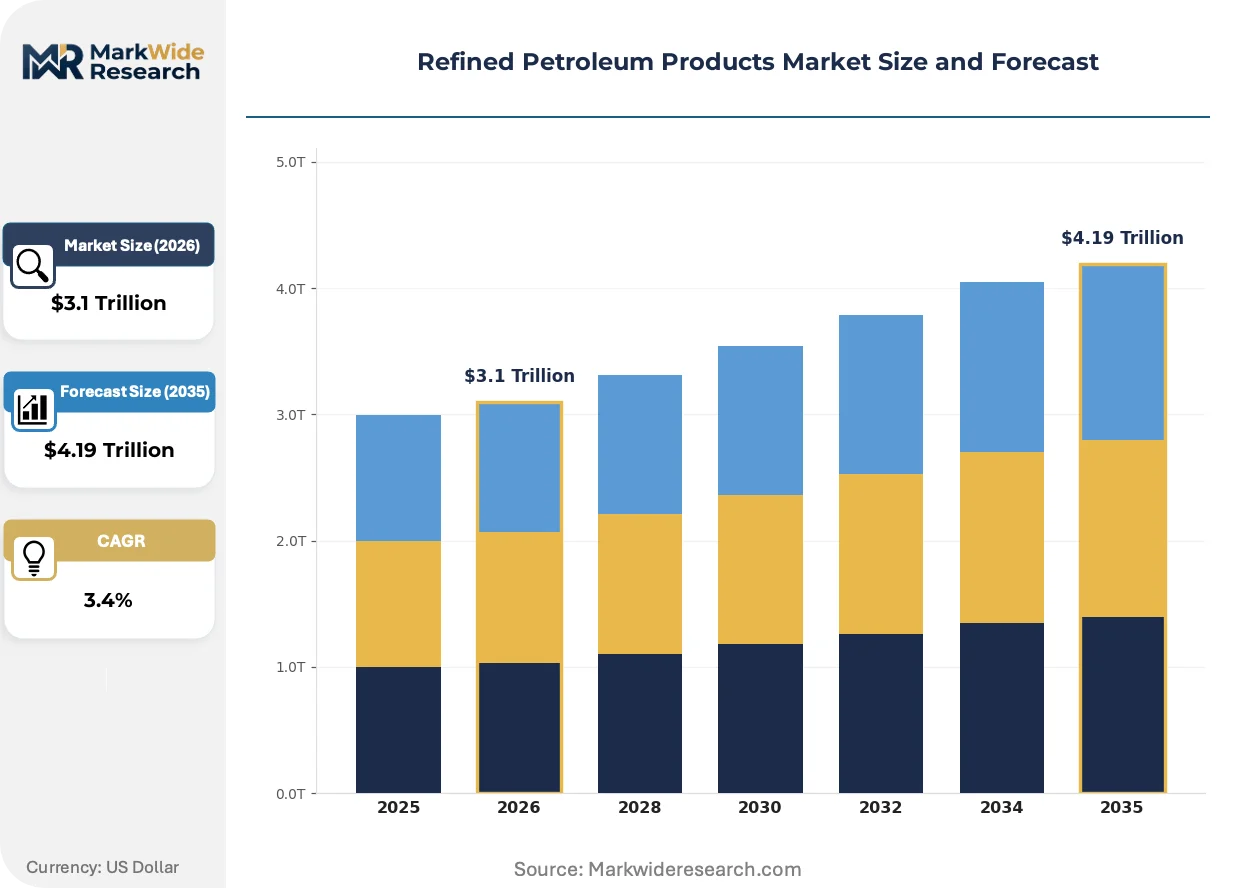
| Market Size in 2026 | $3.1 Trillion |
| Market Size in 2035 | $4.19 Trillion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Kerosene Application: Transportation, Aviation, Industrial, Marine End User: OEMs, Retail Consumers, Businesses, Government Distribution Channel: Direct Sales, Retail Outlets, Wholesalers, Brokers |
| Companies Covered | Chevron, Valero Energy, Saudi Aramco, Phillips 66, Marathon Petroleum, Exxon Mobil, BP, Sinopec, Royal Dutch Shell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refined Petroleum Products Market Strategic Shifts & Innovations
Refining technology is bifurcating between deep decarbonization investments and efficiency maximization of conventional assets, with digital process control emerging as the bridge capability.
Electrolytic hydrogen production integrated with refinery hydrotreaters is electrifying the traditional steam methane reforming pathway for hydrogen supply. European refiners in Rotterdam and Antwerp are piloting 100-megawatt electrolyzer installations to displace grey hydrogen in diesel desulfurization units. This shift is compressing the carbon intensity of finished fuels while exposing refiners to power price volatility they previously avoided.
The EPA's Renewable Fuel Standard and California's Low Carbon Fuel Standard are forcing compliance credit procurement or biorefinery co-investment. Refiners without ethanol blending infrastructure or renewable diesel processing capability face escalating renewable identification number costs. The US Gulf Coast refining cluster is responding with soybean oil and used cooking oil hydrotreating retrofits that produce drop-in diesel substitutes.
Fleet operators and marine charterers are consolidating procurement through long-term offtake contracts that bypass traditional spot-market intermediaries. Major container lines are negotiating direct supply agreements with integrated refiners for IMO 2020-compliant bunkers, disintermediating the independent storage and trading houses that dominated marine fuel distribution. This concentration is most visible in Singapore and Rotterdam, where dedicated bunker supply chains are replacing open-market purchasing.
Refined Petroleum Products Market Segmentation
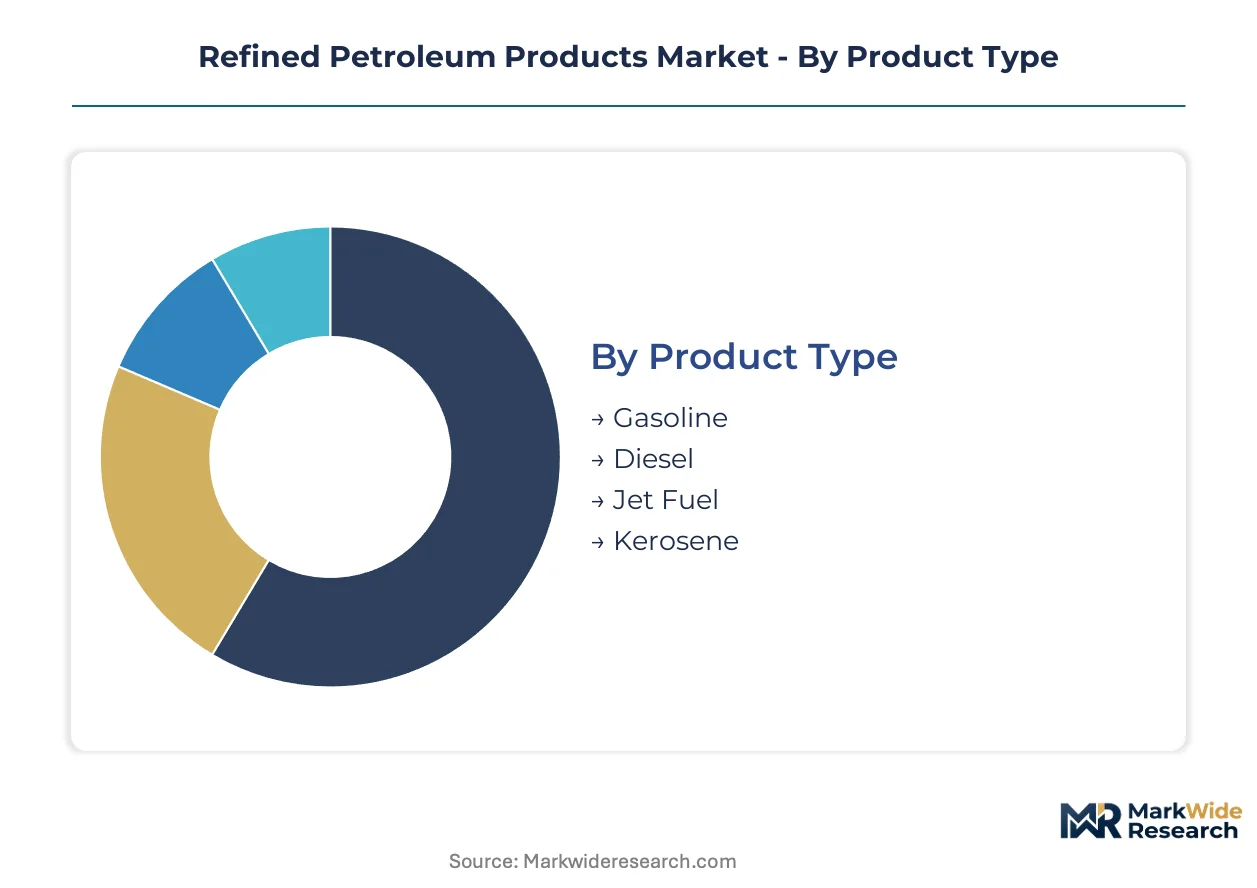
Refined petroleum products span heterogeneous specifications that dictate refinery configuration, margin structure, and regulatory exposure. Each segment carries distinct sulfur limits, octane requirements, and cetane benchmarks enforced by EPA Tier 3, IMO 2020, and EU F-Gas frameworks. Understanding these divisions reveals where capital deployment concentrates and which product slates expose operators to substitution risk.
Product Type:
EPA Tier 3 sulfur mandates, IMO 2020 marine caps, and EU Fit for 55 decarbonization timelines impose divergent certification burdens across fuel grades. Gasoline and diesel face the most stringent road-transport specifications, while marine and aviation products navigate international bunker and turbine-fuel standards.
- Gasoline:A volatile hydrocarbon blend of C4-C12 paraffins, olefins, and aromatics refined to 87-94 octane ratings for spark-ignition engines. Demand concentrates in the United States and China where light-duty vehicle fleets remain dominant, though EPA Tier 3 sulfur limits below 10 parts per million force continuous hydrotreater investment that compresses margin recovery.
- Diesel:A middle-distillate fuel with 40-55 cetane index specifications for compression-ignition engines, requiring deep desulfurization to meet sub-15 ppm sulfur limits in OECD markets. European freight operators and Indian commercial trucking fleets drive absolute volume, with the EU's carbon border adjustment mechanism threatening to penalize high-carbon intensity batches.
- Jet Fuel:Kerosene-range distillate meeting ASTM D1655 or DEF STAN 91-91 specifications for turbine combustion, with freeze point and smoke point controlling refinery cut selection. Asian hub airports and Middle Eastern carriers are restoring international route density above pre-pandemic baselines.
- Kerosene:A light distillate historically used for heating and lighting, now primarily blended into jet fuel or sold for industrial solvent applications. Demand is contracting in developed markets as electrification displaces residential heating oil.
Gasoline sits at the top of the volume ranking, with jet fuel climbing the fastest as aviation networks rebuild capacity.
Application:
Cost tier stratification separates premium-specification fuels from commodity grades, with aviation and marine commanding price premiums over road transport due to specialized handling and certification requirements.
- Transportation:Road-fuel applications for passenger vehicles, commercial trucks, and buses, representing the largest absolute consumption segment. Refiners in the United States and India optimize yield configurations around gasoline and diesel to capture this volume.
- Aviation:Turbine fuel for commercial airlines, cargo operators, and military fleets, requiring strict contamination control and thermal stability. The EU's ReFuelEU Aviation mandate is creating certified sustainable aviation fuel offtake obligations that co-processing investments can satisfy.
- Industrial:Process heating, power generation, and feedstock applications in manufacturing and mining operations. Chinese petrochemical complexes and Indian fertilizer plants anchor residual fuel oil and naphtha demand in this category.
- Marine:Bunker fuels for international shipping, with IMO 2020 sulfur caps forcing a bifurcation between very low sulfur fuel oil and scrubber-equipped high-sulfur residual consumption. Singapore and Rotterdam terminals dominate compliant-bunker supply chain concentration.
Transportation commands the largest revenue pool, with marine applications expanding most quickly as fleet operators consolidate procurement through direct refinery offtake contracts.
End User:
Customer type determines contract structure, with OEMs and government buyers favoring long-term supply agreements while retail consumers and businesses transact through spot and rack markets.
- OEMs:Automakers and equipment manufacturers procuring test fuels, warranty validation batches, and captive fleet supply. Ford, Toyota, and Tata Motors maintain direct refinery relationships for specification-controlled gasoline and diesel.
- Retail Consumers:Individual motorists purchasing through service station networks, with price sensitivity driving brand switching and loyalty program enrollment. Indian and Brazilian markets show the highest retail fragmentation.
- Businesses:Fleet operators, logistics companies, and construction contractors purchasing through commercial cardlock and bulk delivery arrangements. German freight forwarders and American long-haul trucking companies negotiate volume discounts.
- Government:Military, emergency services, and strategic reserve agencies requiring dedicated storage and supply security. The US Defense Logistics Agency and India's strategic petroleum reserve authority represent concentrated public-sector demand.
Retail consumers generate the highest transaction frequency, with government contracts delivering the most stable offtake volumes.
Distribution Channel:
Supply concentration varies dramatically by channel, with direct sales capturing integrated refiner margins and brokers absorbing price volatility for independent marketers.
- Direct Sales:Refinery-to-end-user contracts bypassing intermediaries, common in aviation and marine applications where specification control is critical. Exxon Mobil and Saudi Aramco leverage this channel for Asian bunker and jet fuel supply.
- Retail Outlets:Branded and unbranded service stations selling to motorists, with site economics dictated by throughput volume and non-fuel convenience revenue. Indian Oil and BP operate the largest retail networks across India and the United States.
- Wholesalers:Intermediate distributors supplying independent retailers, commercial fleets, and industrial accounts through terminal rack loading. Gulf Coast and Rotterdam storage terminals anchor wholesale concentration.
- Brokers:Trading houses facilitating spot-market transactions and arbitrage between regional price benchmarks. Trafigura and Vitol dominate marine fuel brokerage in Singapore and Fujairah.
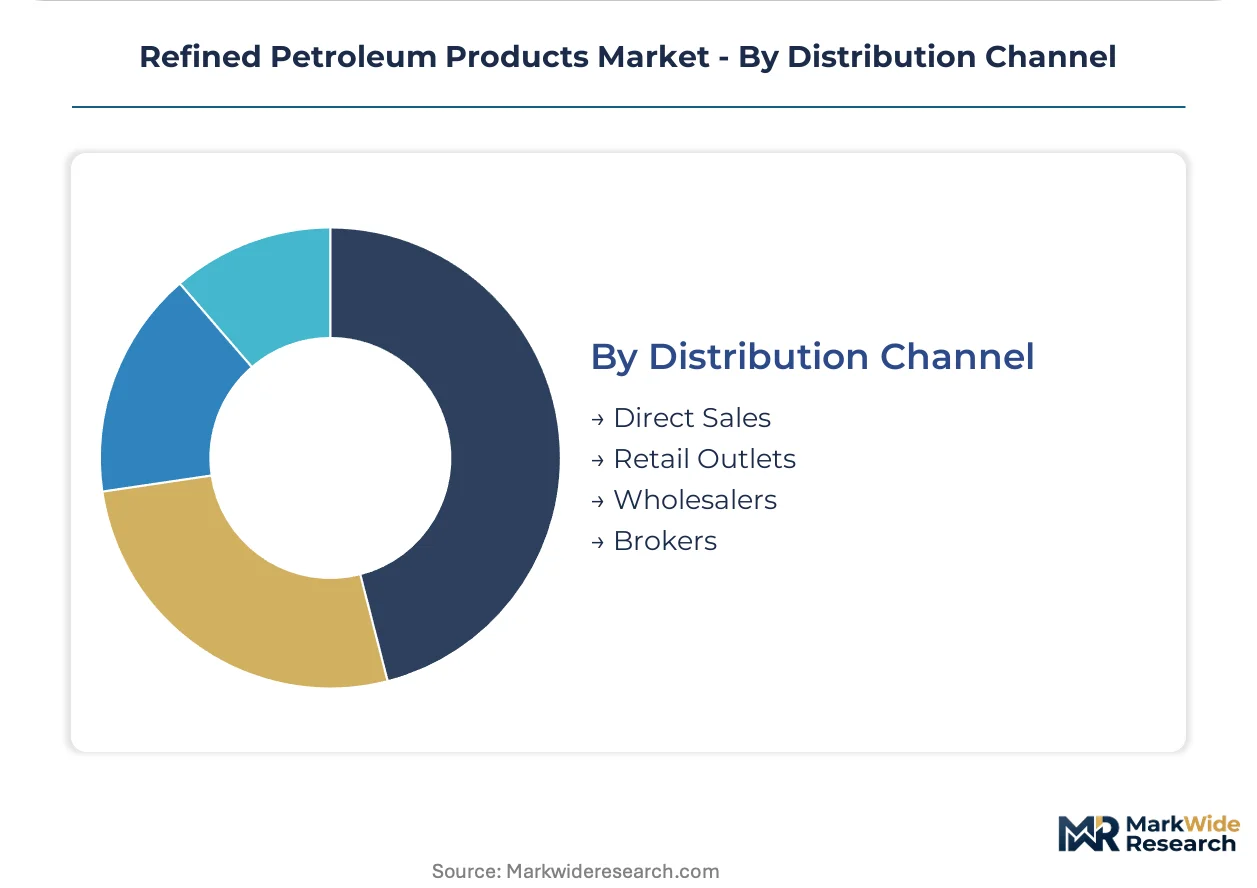
Retail outlets handle the largest absolute volume, with direct sales gaining share fastest as fleet operators disintermediate traditional distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast refining cluster anchors global capacity expansion, with integrated complexes along the Houston Ship Channel processing Permian Basin feedstock. China and India are adding the majority of new distillation units, while European facilities face accelerated decarbonization timelines. Regulatory divergence across these markets is fragmenting investment strategies.
United States
EPA Tier 3 gasoline sulfur mandates force Gulf Coast refiners to operate hydrotreaters at maximum severity, compressing margin recovery windows. The Renewable Fuel Standard and California's Low Carbon Fuel Standard escalate compliance credit costs for facilities lacking renewable diesel processing. Houston and Port Arthur terminals dominate marine fuel supply chains serving IMO 2020-compliant bunker demand.
China
Zhejiang and Shandong provinces are commissioning mega-refineries with integrated petrochemical complexes, shifting yield configurations toward higher-margin chemical feedstocks. The Ministry of Ecology and Environment enforces dual carbon goals that accelerate refinery decarbonization investments. Ningbo-Zhoushan anchors the country's strategic petroleum reserve and coastal import infrastructure.
India
Maharashtra and Gujarat host Reliance Industries' Jamnagar complex, the world's largest refining facility, capturing transport fuel demand expanding faster than domestic capacity additions. The Petroleum Planning and Analysis Cell monitors import dependency as consumption outpaces distillation growth. Mumbai and Kochi terminals concentrate coastal storage and distribution infrastructure for integrated players.
Saudi Arabia
Jazan and Yanbu integrated refining complexes anchor long-term offtake agreements with Asian buyers, securing captive demand for heavy sour crude processing. The Ministry of Energy oversees downstream expansion aligned with Vision 2030 economic diversification targets. Ras Tanura and Jubail industrial cities concentrate residue upgrading and petrochemical integration investments.
Germany
The EU F-Gas Regulation and Fit for 55 package force Rotterdam-Antwerp-Rhine corridor refiners toward electrolytic hydrogen pilots and sustainable aviation fuel co-processing. The Federal Motor Transport Authority enforces road transport emissions standards that compress long-term gasoline demand projections. Leuna and Schwedt facilities represent the remaining inland refining concentration dependent on Russian crude substitution.
Refined Petroleum Products Market Key Industry Players
Global majors compete with regional champions across feedstock access and residue upgrading technology, creating a tiered structure where scale advantages separate integrated players from independent refiners. National oil companies leverage captive crude production to secure cost positions, while merchant refiners concentrate on coastal locations with import flexibility. Three archetypes dominate: vertically integrated majors with upstream control, state-backed champions with domestic market protection, and independent processors optimizing spot-market arbitrage. Competitive moves center on petrochemical integration investments and renewable fuel processing retrofits.
Within the integrated major tier, Chevron and Exxon Mobil exemplify upstream-downstream coordination through Permian Basin captive supply and proprietary resid upgrading technology. Saudi Aramco occupies a position as the state-backed archetype, anchoring massive Asian downstream complexes through long-term offtake structures. Valero Energy represents the independent processor model, optimizing Gulf Coast coastal access for multi-source crude procurement and marine fuel distribution concentration.
| Leading Market Players |
|---|
| Chevron |
| Valero Energy |
| Saudi Aramco |
| Phillips 66 |
| Marathon Petroleum |
| Exxon Mobil |
| BP |
| Sinopec |
| Royal Dutch Shell |
| Others |
Cost & Logistics Intelligence
Marine charterers consolidating bunker procurement through direct refinery offtake contracts command pricing leverage that compresses spot-market premiums and redirects margin capture toward volume-scaled producers with dedicated storage infrastructure.
Pricing Analysis
Crude cost pass-through dominates refined product pricing, with Brent-linked benchmarks setting the baseline for gasoline, diesel, and jet fuel quotations across Singapore, Rotterdam, and Houston trading hubs. Price differentiation rests on sulfur certification tiers—IMO 2020-compliant very low sulfur fuel oil commands premiums over high-sulfur residual grades—and on octane ratings for gasoline blending components. Pricing pressure stems from renewable diesel co-processing investments that raise operating costs for conventional hydrotreating units. Fleet operators exhibit the highest price sensitivity, while aviation fuel buyers accept premium pricing for thermal stability guarantees and contamination control protocols.
Supply Chain Analysis
Single-source vulnerability sits with Middle Eastern crude exporters feeding Asian mega-refineries, where long-term supply agreements concentrate feedstock dependency on Saudi Arabian, Iraqi, and Kuwaiti production streams. Raw material dependencies center on heavy sour crude slates, hydrogen supply for desulfurization units, and catalyst metals including cobalt and molybdenum for hydrocracking operations. Supply chain risk manifests through Strait of Hormuz logistics chokepoint exposure that threatens delivery reliability for refiners lacking diversified procurement. Distribution runs through coastal terminal networks with dedicated pipeline connections to inland demand centers, bypassing traditional wholesale intermediaries for marine and aviation fuel delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in refined petroleum products rests on residue upgrading technology deployment that unlocks value from heavy sour feedstocks conventional configurations cannot process profitably, shifting yield toward higher-margin middle distillates.
For Market Incumbents: Deepen petrochemical integration through steam cracker co-location that captures aromatics and olefins premiums, while accelerating renewable diesel hydrotreating retrofits to hedge against escalating renewable identification number compliance costs. Electrification substitution in light-duty transport threatens gasoline demand baselines, making backward integration into Permian Basin captive supply a critical cost-defense lever. For New Entrants and Emerging Players: Launch via coastal storage and distribution infrastructure in India, where transport fuel consumption outpaces domestic refining capacity additions and import dependency creates white-space for integrated logistics players. Target the sustainable aviation fuel certification gap opened by EU ReFuelEU Aviation mandates, with co-processing investments at existing refineries offering the lowest capital path to certified offtake participation. For Investors and Strategic Acquirers: National oil companies with downstream complexes in Asia represent the most active acquirer in this space, seeking residue upgrading technology and coastal terminal access to anchor long-term offtake structures. Five-to-ten year viability favors integrated refiners with proprietary hydrocracking capabilities and multi-source crude procurement flexibility. Watch electrolytic hydrogen cost curves as the inflection signal determining whether European decarbonization timelines strand conventional assets or enable green hydrogen retrofit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Residue Upgrading Capacity Addition | Proprietary coking and hydrocracking installations unlock value from heavy sour crude slates at Gulf Coast and Jamnagar facilities. |
| Renewable Diesel Hydrotreating Retrofit | Soybean oil and used cooking oil processing capability satisfies California Low Carbon Fuel Standard compliance and captures LCFS credit premiums. |
| Electrolytic Hydrogen Pilot Installation | Rotterdam and Antwerp refiners deploy 100-megawatt electrolyzer capacity to displace grey hydrogen in diesel desulfurization units. |
| Petrochemical Integration Investment | Steam cracker and aromatics complex co-location shifts refinery yield configurations toward higher-margin chemical feedstock production. |
| Direct Marine Bunker Supply Contract | Long-term offtake agreements with container lines disintermediate independent storage houses and capture IMO 2020 compliance premiums. |
Research Approach
Coverage spans the United States, China, India, Saudi Arabia, and Germany, with primary inputs from each market combining structured interviews with refinery operations managers, crude procurement leads at integrated majors, marine fuel supply specialists, and petrochemical complex planners. Secondary validation draws from EIA refinery capacity reports, IEA oil market outlooks, EPA Tier 3 compliance filings, and IMO marine fuel quality data. Bottom-up capacity and utilization modeling triangulates against top-down demand projections across transportation, aviation, industrial, and marine applications.
Granularity-level modeling distinguishes gasoline, diesel, jet fuel, and marine bunker specifications by sulfur content tiers, octane and cetane ratings, and regional regulatory compliance clusters. Product-type, application, and end-user segmentation dimensions were projected across the analysis window with CAGRs derived from historical demand elasticity patterns and announced capacity additions. Forecast inputs include aviation network rebuild trajectories, IMO 2020 compliance investment cycles, and EU carbon border adjustment mechanism implementation timelines.
Several conditions sit outside the modeled scope, including abrupt geopolitical disruption to Middle Eastern crude supply, accelerated battery electric vehicle penetration beyond current OEM platform announcements, and unanticipated renewable diesel feedstock cost spikes. Forecasts reflect assumptions about regulatory enforcement continuity and refinery decarbonization investment pacing that may shift with administrative transitions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Quenching Oil Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
West Africa Refined Petroleum Products Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
North Africa Refined Petroleum Products Market
Petroleum Products
Petroleum Liquid Feedstock Naphtha and Gas Oil Sales Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Global Petroleum Pitch Market
Petroleum Products
Liquefied Petroleum Gas Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Pale Oil Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Nigeria Petrol Station Market