
 Ultra Low Sulphur Fuel Oil (ULSFO) Market | 2026-2036
Ultra Low Sulphur Fuel Oil (ULSFO) Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra Low Sulphur Fuel Oil (ULSFO) Market Insights
Market Overview
Singapore's refining complex is narrowing the supply gap for compliant marine fuels across Asia-Pacific trade lanes. TotalEnergies leverages its integrated European refining network to sustain ULSFO availability at major Mediterranean ports. Chevron anchors North American supply through its Gulf Coast processing assets. Shell competes on global bunkering infrastructure, while ExxonMobil differentiates via proprietary hydrodesulphurization catalyst systems.
Product Definition and Segment Structure
Ultra Low Sulphur Fuel Oil denotes petroleum-derived fuel with sulphur content capped at 0.10% by mass, produced through hydrotreating, vacuum gas oil cracking, or blending low-sulphur distillates with treated residual streams. The product serves primarily as International Maritime Organization-compliant bunker fuel for ocean-going vessels and as industrial boiler feedstock in emission-controlled zones. Marine applications dominate volume offtake, though power generation utilities in coastal regions represent a concentrated margin pool due to strict stack emission rules. Distillate-based ULSFO commands premium pricing in European and North American ports, while blended formulations occupy cost-sensitive Asian bunkering markets where straight-run residuals face tightening MEE standards in China.
Regulatory Environment and Outlook
IMO 2020 sulphur regulations, EU Green Deal maritime provisions, and China's MEE emission standards collectively mandate fuel switching across commercial fleets and stationary combustion sources. The EPA enforces residual fuel sulphur limits for US-flagged vessels and port facilities, while EMA-aligned EU member states impose additional harbour emission controls. Stakeholders must monitor regulatory divergence between IMO global caps and regional low-carbon fuel standards to anticipate product specification shifts.
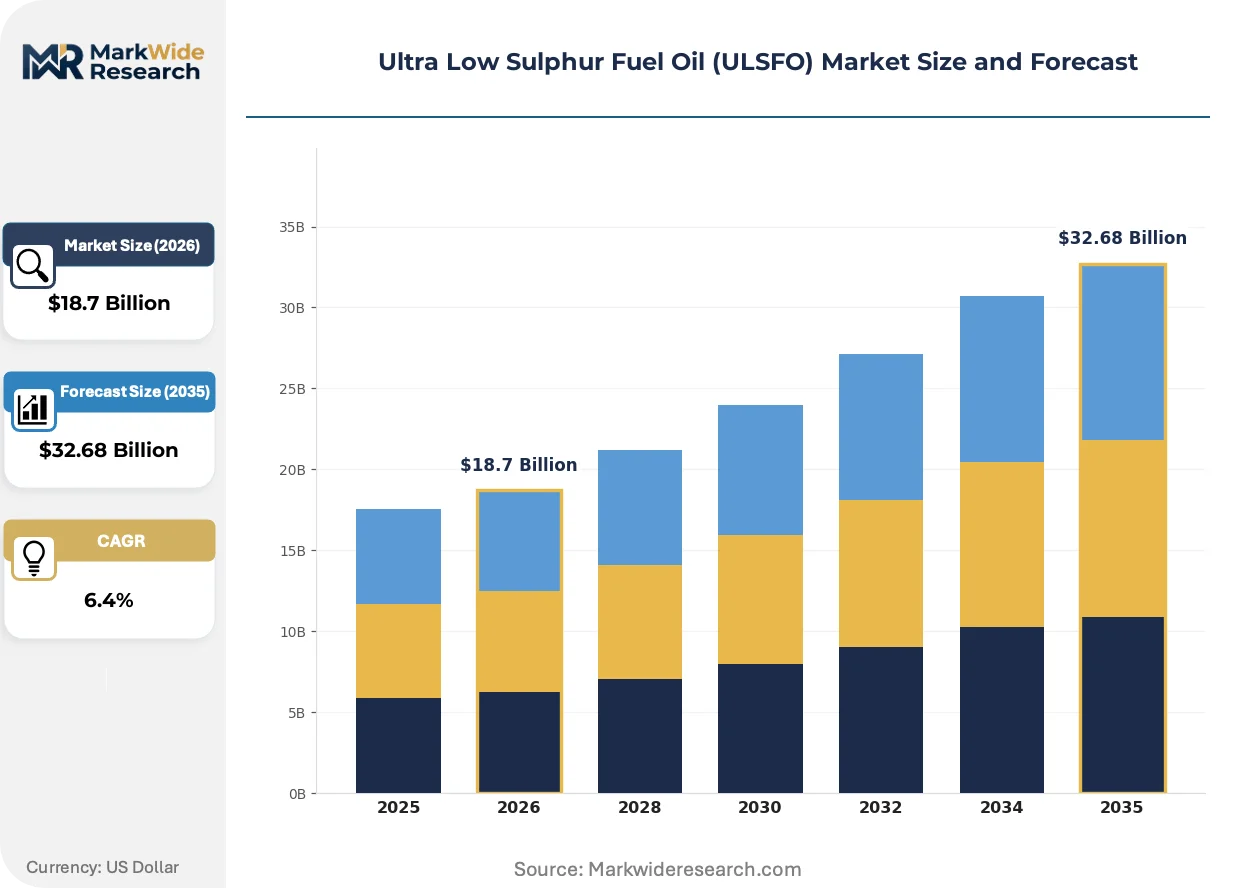
Market Dynamics
IMO 2020 sulphur caps have permanently altered marine fuel procurement patterns, forcing vessel operators to abandon high-sulphur residual streams and redirect demand toward hydrotreated and blended compliant formulations at major bunkering nodes.
Growth Catalysts
- IMO 2020 Enforcement:The International Maritime Organization's global 0.50% sulphur limit on marine fuels has eliminated non-compliant high-sulphur fuel oil from mainstream commercial shipping lanes, redirecting fleet procurement toward ULSFO and marine gasoil alternatives.
- European Emission Control Areas:The EU Green Deal maritime provisions and Baltic Sea SECA regulations mandate 0.10% sulphur limits in coastal waters, compressing demand for distillate-based ULSFO in Rotterdam, Hamburg, and Mediterranean ports.
- Hydrotreating Yield Gains:Residual fluid catalytic cracking and vacuum gas oil hydrodesulphurization advances have improved refinery conversion economics for low-sulphur residual production at complex facilities in Singapore and the US Gulf Coast.
Market Restraints
- Crude Slate Volatility:Medium and heavy sour crude differentials directly compress ULSFO blending margins when high-sulphur feedstock costs spike, squeezing independent blenders without integrated upstream access.
- Asian Supply Concentration:Singapore, South Korea, and Japan together account for the majority of Asia-Pacific ULSFO export availability, creating bunker delivery risk during regional refinery maintenance cycles or geopolitical disruptions.
- Scrubber Retrofit Competition:Vessel operators installing exhaust gas cleaning systems can legally burn cheaper high-sulphur fuel oil, fragmenting demand and capping ULSFO premium pricing power in bulk shipping segments.
Strategic Opportunities
- Indian Coastal Manufacturing:Reliance Industries' Jamnagar complex and emerging private refinery expansions along Gujarat's coast offer underutilized hydrocracking capacity for ULSFO production targeting Middle East and East African bunkering demand.
- Ammonia Co-Firing Infrastructure:Dual-fuel vessel engines capable of burning ammonia-marine fuel oil blends are entering commercial service, creating early-mover positioning for ULSFO suppliers developing low-carbon bunkering terminals.
- China's MEE Standards:The Ministry of Ecology and Environment's tightening industrial boiler emission rules in coastal provinces are forcing power utilities and steel mills to switch from straight-run residuals to compliant ULSFO feedstocks.
Industry Challenges
- Marine Chemist Certification Bottlenecks:The shortage of IMO-certified fuel oil testing laboratories creates compliance verification delays at secondary ports, forcing vessel operators to pre-position fuel samples or divert to major bunkering hubs.
- Legacy Tank Cleaning Costs:Shipowners switching from high-sulphur to ULSFO face substantial tank and fuel line decontamination expenses, slowing adoption among smaller tramp operators with constrained maintenance budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra Low Sulphur Fuel Oil (ULSFO) Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Marine, Industrial, Power Generation, Residential Fuel Type: Distillate, Blended, Straight Run, Residual End User: Shipping Companies, Utilities, Refineries, Commercial Distribution Channel: Direct Sales, Retail, Bunkering, Online |
| Companies Covered | TotalEnergies, Chevron, Shell, Marathon Petroleum, Petrobras, ExxonMobil, Sinopec, Valero Energy, BP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra Low Sulphur Fuel Oil (ULSFO) Market Trends and Innovations
Refinery process intensification and digital fuel quality tracking are compressing specification variance and enabling just-in-time bunkering logistics that reshape how vessel operators manage compliance risk across fragmented port networks.
Membrane-based desulphurization units operating at ambient temperature are entering pilot deployment at European refineries. These systems treat vacuum residue streams without hydrogen consumption, slashing capital intensity for independent processors. The technology is rendering obsolete conventional hydrotreater investments for sub-50,000 barrel-per-day facilities.
The EU's FuelEU Maritime regulation introduces well-to-wake greenhouse gas intensity limits starting in 2025, layering carbon accounting requirements atop existing sulphur caps. This dual-compliance framework forces fuel suppliers to certify lifecycle emissions through accredited verification bodies. Mediterranean and North Sea routes face the steepest compliance gradients, accelerating demand for bio-component blended ULSFO with documented sustainability credentials.
Charterers are consolidating bunker procurement through integrated fuel management platforms that aggregate consumption data across fleets. These systems enable index-linked pricing contracts and automated quality dispute resolution, displacing traditional spot-market purchasing at individual port calls. Greek and Singapore-based shipowners have pioneered this transition, pressuring independent brokers to add technical advisory capabilities or exit the segment.
Ultra Low Sulphur Fuel Oil (ULSFO) Market Segmentation
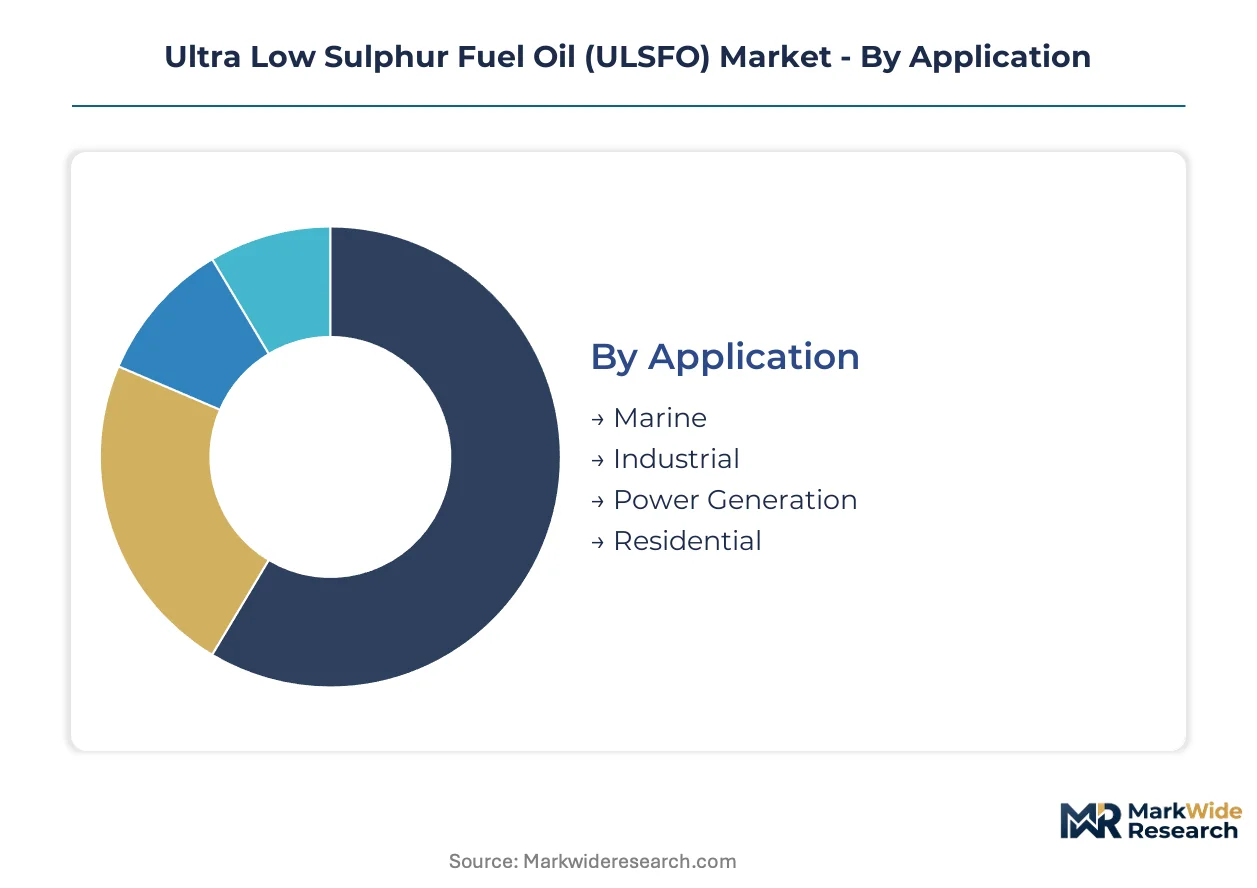
ULSFO procurement patterns diverge sharply across fuel types and end-use applications, with bunker fuel specifications varying by port authority requirements and industrial buyers demanding distinct sulphur thresholds for boiler compliance.
Application:
After-sales service intensity peaks in marine applications, where vessel operators require continuous fuel quality certification and onboard technical support to maintain IMO compliance across bunkering ports.
- Marine:Ocean-going vessels consume ULSFO as primary bunker fuel under IMO 2020 sulphur caps. Container shipping lines operating Singapore-Rotterdam routes drive the largest volume offtake, with charterers demanding ISO 8217-compliant fuel certificates at every port call.
- Industrial:Steel mills and chemical plants in China's coastal provinces substitute ULSFO for high-sulphur residuals to meet MEE emission standards. These facilities require dedicated storage infrastructure and periodic stack monitoring services from fuel suppliers.
- Power Generation:Coastal utilities burn ULSFO in auxiliary boilers during peak demand periods.
- Residential:District heating networks in Northern Europe use ULSFO as backup fuel for combined heat and power plants.
By volume, Marine leads. By growth pace, Industrial is ahead.
Fuel Type:
Cost tier differentiation separates complex refinery products from simpler blending operations, with hydrogen-intensive distillate commanding premium pricing over residual formulations.
- Distillate:Hydrotreated marine gasoil and ultra-low sulphur diesel fractions offer guaranteed 0.10% sulphur compliance without blending uncertainty. European Emission Control Areas mandate these formulations for vessels transiting Baltic and North Sea routes, where port state control inspections enforce strict fuel log verification.
- Blended:Mixtures of low-sulphur distillates with hydrotreated residual streams balance cost and compliance for bulk carriers. Singapore blenders optimize these formulations around fluctuating vacuum gas oil spreads and regional crude slate availability.
- Straight Run:Directly processed low-sulphur crude yields limited commercial volumes.
- Residual:Hydrotreated fuel oil from vacuum residue conversion supplies cost-sensitive Asian bunkering markets.
Distillate captures the highest per-tonne margins. Blended formulations are expanding most quickly in Asia-Pacific bunkering hubs.
End User:
Customer type determines contract structure, with shipping companies negotiating annual supply agreements while utilities procure through tender processes tied to emission compliance deadlines.
- Shipping Companies:Container lines, bulk operators, and tanker fleets purchase ULSFO through integrated fuel management platforms. Greek and Singapore-based shipowners have consolidated procurement across fleets, demanding index-linked pricing and automated quality dispute resolution.
- Utilities:Power generation companies in coastal emission control zones source ULSFO for auxiliary boiler operations. These buyers prioritize supply security over price optimization, maintaining dual-source contracts with regional refiners.
- Refineries:Complex facilities trade ULSFO as intermediate product for external blending.
- Commercial:Industrial distributors serve fragmented manufacturing and heating customers.
Shipping Companies dominate absolute volume. Utilities are gaining share fastest as China's MEE standards tighten.
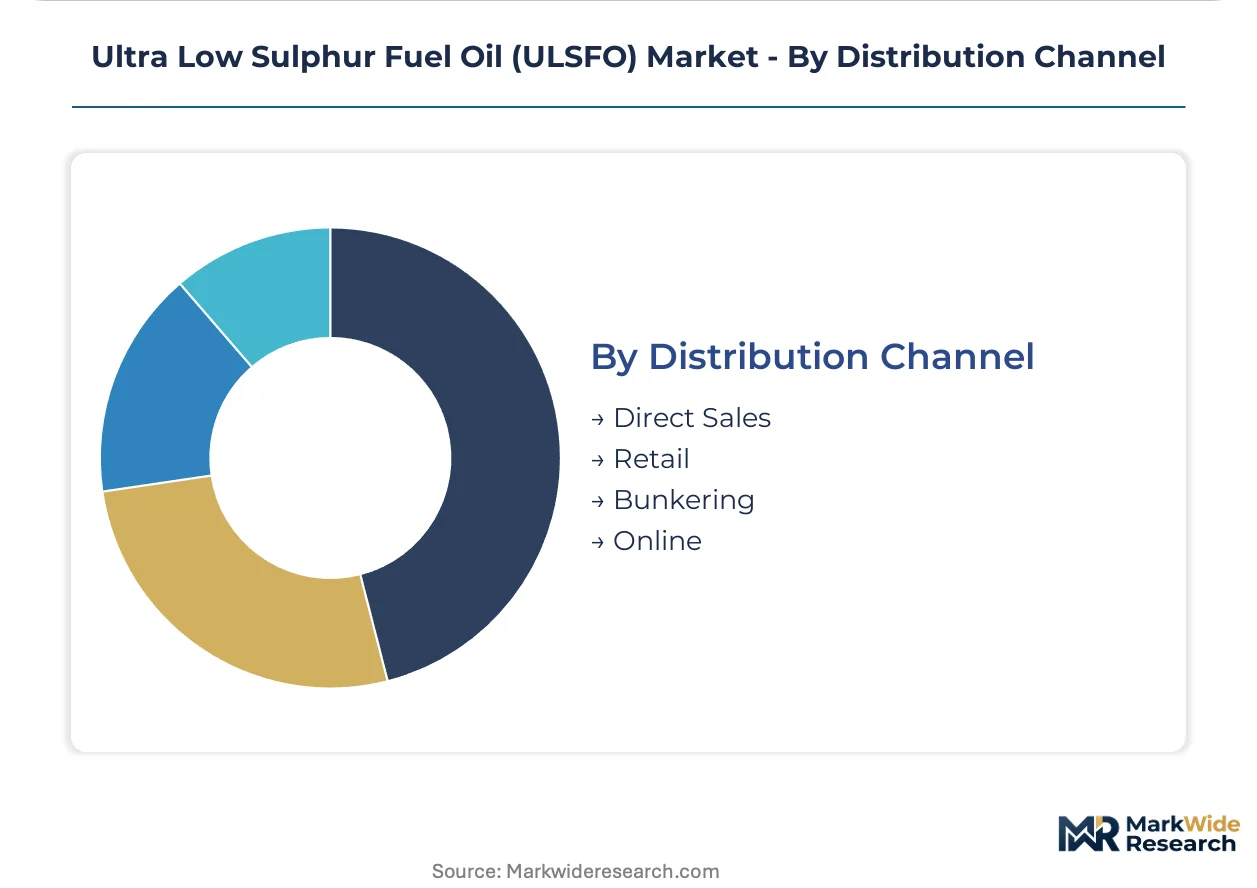
Distribution Channel:
Supply concentration shapes channel selection, with major bunkering hubs favoring direct refinery-vessel delivery while secondary ports rely on layered distribution networks.
- Bunkering:Dedicated marine fuel terminals at Singapore, Rotterdam, and Fujairah deliver ULSFO directly to vessels alongside cargo operations. These facilities account for the majority of marine ULSFO volume, with physical suppliers managing storage, blending, and barge logistics.
- Direct Sales:Refiners contract directly with large industrial consumers and shipping lines. TotalEnergies and Shell leverage this channel to bypass intermediaries and capture full margin on distillate formulations.
- Retail:Local distributors serve small industrial and commercial accounts.
- Online:Digital platforms aggregate spot market pricing for smaller vessel operators.
Bunkering leads by tonnage moved. Direct Sales are climbing the fastest as integrated suppliers deepen relationships with major consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IMO 2020 sulphur caps have concentrated ULSFO procurement at maritime chokepoints where refinery capacity, bunkering infrastructure, and enforcement capacity converge. Singapore, Rotterdam, and Fujairah anchor physical supply, while regulatory divergence between the EU Green Deal and China's MEE standards is fragmenting specification requirements across trade lanes.
Singapore
Container shipping lines operating the Singapore-Rotterdam corridor drive the largest marine ULSFO offtake globally. The Maritime and Port Authority enforces strict fuel log verification through its digital bunkering initiative. Jurong Island's integrated refining complex supplies blended formulations optimized around vacuum gas oil spreads and regional crude availability.
United States
Gulf Coast refineries leverage vacuum gas oil hydrodesulphurization capacity to serve Caribbean and Latin American bunkering demand. The EPA enforces residual fuel sulphur limits for US-flagged vessels under the Clean Air Act. Houston anchors North American supply, with Marathon Petroleum and Valero Energy processing medium-sour crude slates into compliant residual streams.
Netherlands
Rotterdam's bunkering hub faces the steepest FuelEU Maritime compliance gradients starting in 2025. The EU Green Deal maritime provisions mandate well-to-wake greenhouse gas intensity limits alongside existing sulphur caps. The port's independent storage terminals are expanding bio-component blending capacity to certify sustainability credentials for Mediterranean and North Sea routes.
China
Coastal utilities and steel mills in Jiangsu and Shandong provinces are switching from straight-run residuals to ULSFO feedstocks. The Ministry of Ecology and Environment's tightening industrial boiler emission rules compress demand timelines. Qingdao and Ningbo-Zhoushan bunkering hubs face specification pressure as MEE standards diverge from IMO global caps.
United Arab Emirates
Fujairah's marine fuel terminals supply blended ULSFO to vessels transiting the Strait of Hormuz. The UAE's national oil company has expanded hydrocracking capacity to reduce dependence on imported distillate components. The port's storage and blending infrastructure serves as a cost-sensitive alternative to Singapore for bulk carriers operating East African and Indian Ocean routes.
Ultra Low Sulphur Fuel Oil (ULSFO) Market Competitive Landscape
Integrated oil majors and independent refiners split the market between premium distillate formulations and cost-optimized blended products. The vendor base concentrates around complex refining assets with vacuum residue conversion capability, creating tiered supply segmentation. National oil companies and Western supermajors dominate marine bunkering, while regional independents capture industrial boiler feedstock contracts. Competitive moves center on hydrocracking capacity expansion and strategic terminal partnerships at major ports.
Among integrated European suppliers, TotalEnergies and Shell exemplify the supermajor archetype with global bunkering infrastructure and proprietary catalyst systems. BP occupies a position within the premium distillate tier, leveraging North Sea refining assets. Chevron and ExxonMobil anchor North American supply through Gulf Coast processing complexes, with the latter differentiating via hydrodesulphurization technology licensing. Sinopec represents the state-backed refiner archetype, capturing domestic Chinese demand while expanding Middle East terminal partnerships.
| Leading Market Players |
|---|
| TotalEnergies |
| Chevron |
| Shell |
| Marathon Petroleum |
| Petrobras |
| ExxonMobil |
| Sinopec |
| Valero Energy |
| BP |
| Others |
Pricing and Supply Chain Analysis
Jurong Island's integrated refining complex in Singapore sets the benchmark for Asia-Pacific ULSFO pricing, with its vacuum gas oil conversion capacity dictating regional premium spreads against Rotterdam and Houston benchmarks. IMO 2020 enforcement has compressed arbitrage windows between major bunkering hubs, forcing blenders to absorb crude slate volatility rather than pass through costs to container lines with annual contract coverage.
Pricing Analysis
Singapore-Rotterdam price spreads for distillate-based ULSFO typically run wider than blended formulations, reflecting hydrogen intensity and guaranteed 0.10% sulphur compliance. Price differentiation hinges on certification grade and volume scale, with ISO 8217-compliant certificates commanding premiums from charterers operating Baltic Sea SECA routes. Pricing pressure stems from scrubber retrofit competition, as bulk carriers burning high-sulphur fuel oil fragment demand and cap premium capture. Container shipping lines demonstrate lowest price sensitivity due to annual offtake commitments, while tramp operators spot-purchasing at secondary ports drive hardest bargain.
Supply Chain Analysis
Medium and heavy sour crude feedstocks from Middle Eastern and Latin American fields anchor ULSFO production economics at complex refineries. Singapore, South Korea, and the United States together concentrate global hydrocracking capacity for compliant residual streams. The supply chain rests on vacuum gas oil, hydrogen supply, and catalyst systems as critical inputs. Single-source vulnerability concentrates in Singapore's Jurong Island storage and blending cluster, where regional maintenance cycles disrupt bunker delivery schedules. Distribution runs through dedicated marine terminals at major ports, with secondary markets layered through independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ULSFO procurement cycles track vessel ordering and refinery investment waves, positioning the market for cyclical recovery as IMO 2020 enforcement matures and FuelEU Maritime layers carbon intensity rules atop sulphur caps.
For Market Incumbents: Harden terminal partnerships at Fujairah and Rotterdam to lock in bunkering volume ahead of independent storage expansions. Deepen backward integration into hydrogen supply to offset vacuum gas oil spread volatility compressing blending margins. Prioritize bio-component blending certification to capture FuelEU Maritime premiums on Mediterranean routes. For New Entrants and Emerging Players: Pursue industrial boiler feedstock contracts in China's Jiangsu and Shandong provinces, where MEE enforcement outpaces domestic refinery compliance capacity. Target coastal utilities switching from straight-run residuals as the most penetrable segment. Lead with technical advisory services bundling fuel quality certification and stack monitoring to differentiate from commodity distributors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because sulphur caps and carbon intensity rules compound compliance burdens favoring complex refiners with hydrocracking assets. Acquisition targets should screen for vacuum residue conversion capability and IMO-certified testing infrastructure. Watch scrubber retrofit rates in bulk shipping as the inflection signal—accelerating installations fragment ULSFO demand and compress premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocracking Capacity Expansion | Reliance Industries' Jamnagar complex demonstrates scale economics for Middle East bunkering supply. |
| Bio-Component Blending Certification | Rotterdam storage terminals layer sustainability credentials atop sulphur compliance for EU Green Deal routes. |
| Digital Bunkering Platform Integration | Singapore's Maritime and Port Authority initiative automates fuel log verification and quality dispute resolution. |
| Ammonia Co-Firing Infrastructure | Dual-fuel vessel engines entering commercial service create early-mover positioning for low-carbon terminal development. |
| Backward Integration into Hydrogen Supply | Captive hydrogen production insulates blending margins from feedstock cost spikes at independent processors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, refinery capacity disclosures, and regulatory filings from IMO, EPA, and China's MEE. Primary interviews engaged marine fuel procurement managers at container lines, hydrocracking unit operators at Singapore and Gulf Coast refineries, and bunker barge logistics coordinators at Rotterdam and Fujairah. Secondary validation drew from EIA stock data, IEA marine fuel reports, and port authority throughput statistics. Bottom-up vessel consumption estimates triangulated against top-down refinery production capacity assessments.
Forecast inputs incorporate fuel type segmentation across distillate, blended, and residual formulations; application splits between marine bunkering and industrial boiler feedstock; and end-user contract structures distinguishing annual shipping agreements from utility tender processes. Modeled CAGRs reflect historical crude slate volatility, scrubber retrofit penetration curves, and regional regulatory enforcement gradients. Industry-specific inputs include vacuum gas oil spread forecasts and FuelEU Maritime carbon intensity compliance timelines.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, freight rate cycles, or carbon credit pricing would shift the trajectory. Forecasts reflect assumptions about sustained IMO 2020 enforcement and incremental MEE standard tightening, though regulatory delay or scrubber technology breakthroughs would necessitate revision. Cross-checking against IEA marine fuel demand projections and major port authority bunkering volume reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
India White Oil Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Australia Refined Petroleum Products Market
Petroleum Products
Tar Oil Market
Petroleum Products
Europe Ethane Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Quenching Oil Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
Petroleum Benzine Market
Petroleum Products
Oil Storage Sales Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Automotive Oil Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Uganda Petroleum Products Market