
 Hydrocarbon Market | 2026-2036
Hydrocarbon Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocarbon Market Insights
Long-term supply contracts between national oil companies and Asian refiners are reshaping cargo flows across the Atlantic and Pacific basins. Exxon Mobil Corporation leverages its Permian Basin position to anchor US export volumes to European and Asian buyers. Shell plc competes through integrated LNG trading desks that span production, shipping, and regasification terminals. Saudi Arabian Oil Co. controls spare production capacity that allows rapid output adjustments during supply disruptions.
Hydrocarbons comprise organic compounds of hydrogen and carbon atoms, ranging from simple methane molecules to complex aromatic chains, formed through geological heat and pressure acting on ancient biomass over millions of years. These substances serve as the foundational feedstock for combustion fuels, synthetic materials, and industrial chemicals that power modern economies. Crude oil and natural gas dominate value capture, while ethylene and propylene represent the fastest-growing product categories as polymer demand from packaging and construction sectors expands. Fuel production remains the largest application segment by volume, though petrochemicals command superior margin pools due to downstream specialization in plastics and specialty chemicals.
The EPA enforces methane monitoring requirements under the Clean Air Act that increase compliance costs for US onshore operators, while the EU's F-Gas Regulation and CSRD framework compel European majors to accelerate leak detection and emissions reporting across their asset bases. China's MEE implements dual carbon goals that restrict new refinery approvals and favor petrochemical integration over standalone fuel production. Stakeholders must monitor how divergent regulatory stringency between North America, Europe, and Asia reshapes capital allocation toward lower-carbon intensity projects and carbon capture retrofits.
Market Dynamics
Dual carbon mandates from China's MEE are forcing refinery-petrochemical integration over standalone fuel production, while EPA methane rules and EU CSRD disclosure requirements simultaneously reshape capital allocation across upstream and midstream assets worldwide.
Growth Catalysts
- Cracker capacity expansion:Gulf Coast petrochemical complexes are commissioning new ethylene units to serve packaging and construction polymer demand. This feedstock pull accelerates natural gas liquids offtake from Permian Basin production.
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are redirecting industrial refrigerant demand toward hydrocarbon alternatives in commercial cooling systems.
- Integrated refining-petrochemical complexes:Sinopec and PetroChina are commissioning facilities that upgrade residue directly into aromatics and olefins, improving margin capture per barrel processed.
Market Restraints
- Capital intensity of carbon capture retrofits:Post-combustion amine scrubbing systems require substantial upfront investment for existing steam methane reforming facilities, compressing returns on marginal gas fields.
- Permitting bottlenecks:US Federal Energy Regulatory Commission review timelines for new liquefaction capacity extend project completion horizons beyond typical investment committee mandates.
- Bioplastics substitution:Polylactic acid and polyhydroxyalkanoate capacity expansion in European packaging applications threatens polymer-grade propylene demand growth trajectories.
Strategic Opportunities
- Blue hydrogen production hubs:Netherlands and UK North Sea assets can repurpose offshore infrastructure for carbon capture and storage, accessing EU Innovation Fund financing for low-carbon fuel certification.
- Small-scale LNG bunkering:Singapore and Rotterdam port authorities are mandating cleaner marine fuel standards, creating infrastructure demand for containerized liquefaction and cryogenic storage systems.
- Pyrolysis-oil integration:Chemical recycling of mixed plastic waste into synthetic crude feedstock offers circularity credentials that satisfy Extended Producer Responsibility frameworks in France and Germany.
Industry Challenges
- Process control engineering shortage:Distributed control system programming for advanced process control in complex refineries faces talent competition from datacenter and semiconductor sectors.
- Legacy SCADA integration:Cybersecurity hardening of 1990s-vintage refinery automation systems against IEC 62443 standards requires operational downtime that conflicts with utilization targets.
- Measurement and verification protocols:Satellite-based methane leak quantification methods lack standardization between OGMP 2.0 and EPA super-emitter response program requirements, complicating dual-jurisdiction compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocarbon Market |
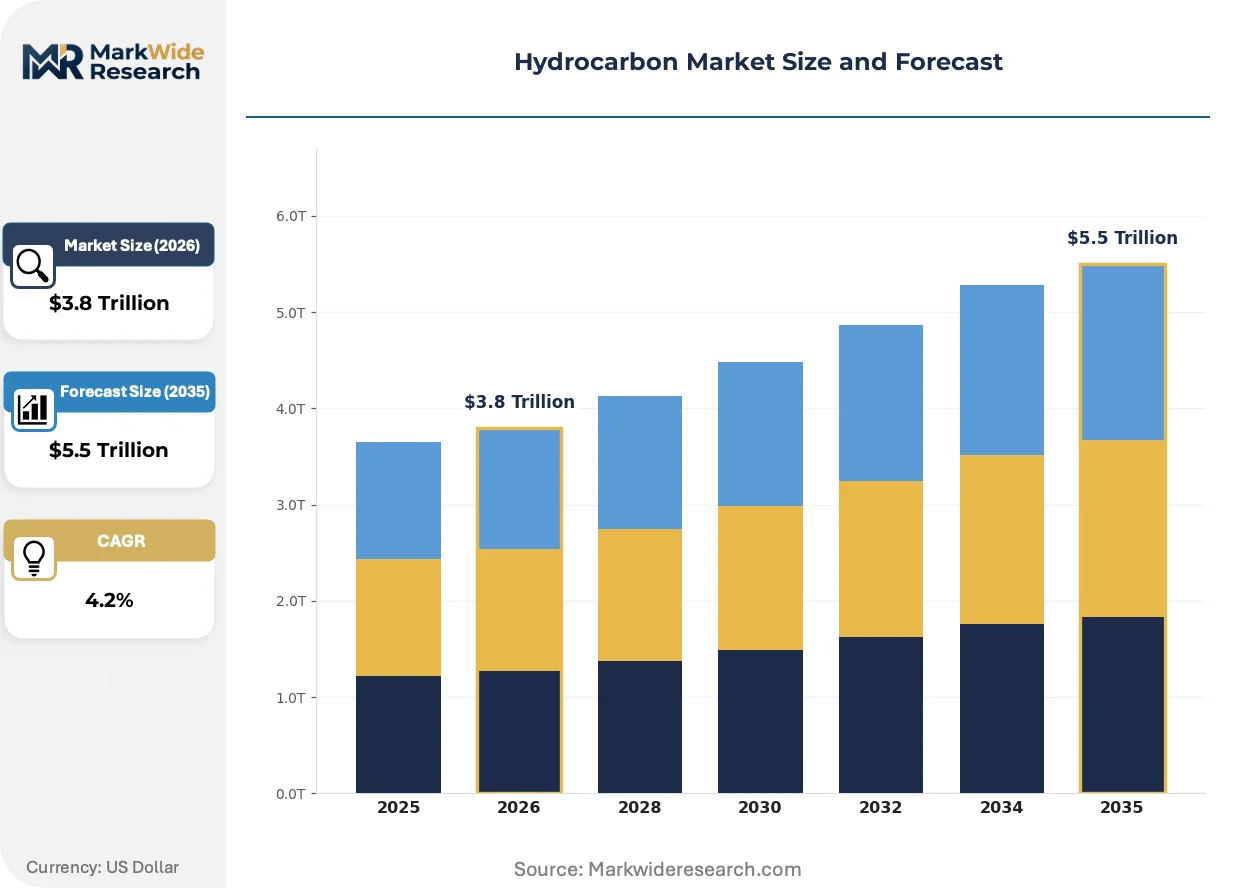
| Market Size in 2026 | $3.8 Trillion |
| Market Size in 2035 | $5.5 Trillion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Ethylene, Propylene Application: Fuel Production, Petrochemicals, Lubricants, Lubricating Oils End User: Automotive, Aerospace, Chemical Industry, Power Generation Processing Technology: Refining, Extraction, Distillation, Cracking |
| Companies Covered | TotalEnergies, BP p.l.c., Exxon Mobil Corporation, Reliance Industries Limited, ConocoPhillips, Saudi Arabian Oil Co., Chevron, PetroChina, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocarbon Market Trends and Innovations
Digital twin deployment across downstream assets is compressing optimization cycles from quarterly to real-time, while regulatory disclosure mandates force emissions data architecture upgrades that enable new trading and certification products.
Advanced process control software is virtualizing unit operations across refinery distillation and reforming trains. European majors are deploying these systems at brownfield sites to squeeze additional yield without mechanical overhaul. This capability is virtualizing the traditional engineering-procurement-construction upgrade cycle into software-defined margin improvement.
EPA's supplemental methane proposal under the Clean Air Act tightens monitoring frequency and repair timelines for pneumatic controllers and compressors. US onshore operators face accelerated capital deployment for optical gas imaging and continuous monitoring networks. Smaller independents without integrated midstream arms are outsourcing compliance to third-party leak detection and repair service providers.
Buyers in Asian chemical manufacturing are consolidating procurement through long-term offtake agreements indexed to regional naphtha benchmarks rather than crude-linked formulas. This shift transfers price volatility risk upstream to integrated producers with spare capacity buffers. The restructuring is most pronounced in South Korean and Taiwanese ethylene derivative operations seeking supply security for export-oriented polymer production.
Hydrocarbon Market Segmentation
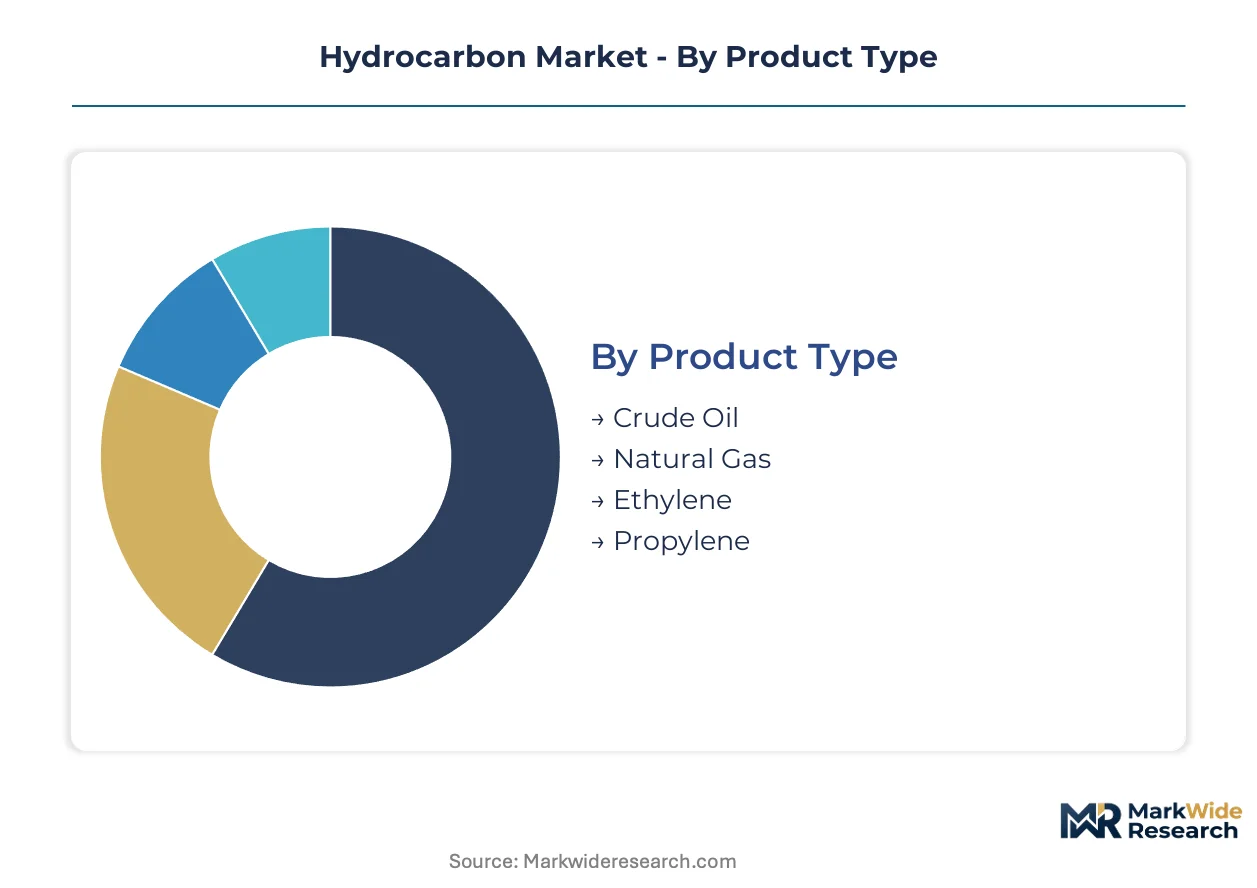
Segmentation in the hydrocarbon market reveals distinct margin pools and capital intensity profiles across product categories and processing pathways. Understanding these divisions enables targeted positioning around regulatory exposure, feedstock access, and end-use demand concentration.
Product Type:
Mature commodity streams dominate revenue tonnage while olefin intermediates concentrate value capture in integrated complexes.
- Crude Oil:Complex mixture of aliphatic and aromatic hydrocarbons graded by API gravity and sulfur content. Refineries in China and the US Gulf Coast are optimizing residue upgrading to maximize light distillate yields under MEE dual carbon constraints.
- Natural Gas:Predominantly methane composition with varying ethane and propane fractions determining processing economics. Permian Basin operators are expanding NGL extraction capacity to serve Gulf Coast cracker demand, though FERC permitting timelines compress project returns.
- Ethylene:Simplest olefin serving as polymer building block for polyethylene production.
- Propylene:Secondary olefin feedstock for polypropylene and acrylonitrile derivatives.
Crude oil handles the majority of throughput; ethylene is the fastest mover on share.
Application:
Volume concentration sits in combustion applications while specialty derivatives command superior margin pools per barrel equivalent.
- Fuel Production:Combustible energy products spanning gasoline, diesel, jet fuel, and marine bunkers. China's MEE restrictions on standalone refinery approvals are forcing integration with petrochemical output to improve carbon efficiency per unit processed.
- Petrochemicals:Intermediate chemicals including olefins, aromatics, and synthetic materials for plastics and fibers. Integrated refining-petrochemical complexes in South Korea and Taiwan are securing long-term naphtha offtake agreements indexed to regional benchmarks rather than crude-linked formulas.
- Lubricants:High-viscosity base oils and additive packages for friction reduction in mechanical systems.
- Lubricating Oils:Refined petroleum fractions formulated for specific equipment thermal and load requirements.
Fuel production maintains the largest volume footprint; petrochemicals are climbing the fastest on value contribution.
End User:
Transportation sectors anchor demand cyclicality while industrial process applications provide more stable offtake profiles.
- Automotive:Internal combustion engine fuels and synthetic rubber feedstocks for tire manufacturing. EPA methane monitoring rules are increasing compliance costs for upstream supply to US refiners serving this segment.
- Aerospace:Jet fuel specifications demanding stringent thermal stability and freeze point characteristics. Singapore and Rotterdam port mandates for cleaner marine fuels are creating parallel infrastructure demand for LNG bunkering alternatives.
- Chemical Industry:Feedstock procurement for polymer and specialty chemical synthesis.
- Power Generation:Natural gas turbine fuel and backup diesel for grid reliability.
Automotive pulls the largest single share of hydrocarbon throughput; aerospace is gaining share fastest on jet fuel recovery.
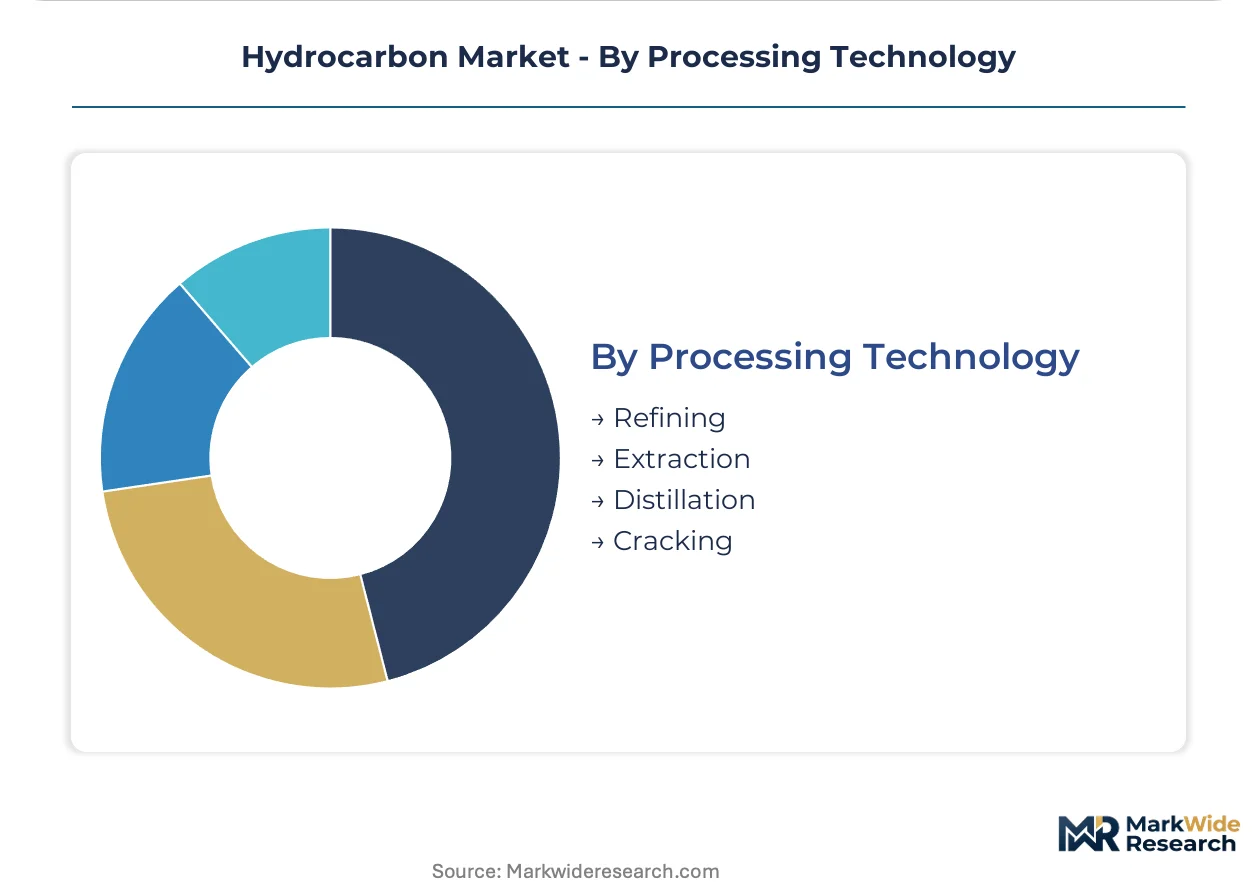
Processing Technology:
Capital deployment intensity varies sharply between upstream extraction and downstream conversion with correspondingly different regulatory exposure profiles.
- Refining:Thermal and catalytic processing of crude into specification products. European majors are deploying advanced process control software at brownfield sites to squeeze additional yield without mechanical overhaul, virtualizing the traditional engineering-procurement-construction upgrade cycle.
- Extraction:Upstream recovery of crude oil and natural gas from subsurface reservoirs. US onshore operators face accelerated capital deployment for optical gas imaging and continuous monitoring networks under EPA supplemental methane proposals.
- Distillation:Thermal separation of crude components by boiling point differential.
- Cracking:Catalytic or steam thermal breaking of heavy fractions into lighter olefins.
Refining handles the majority of installed capacity throughput; extraction is expanding most quickly on capital deployment for methane compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Asian naphtha-indexed contracts while US Gulf Coast operators absorb methane compliance premiums. China's integrated refining complexes capture margin through residue upgrading, and Middle East spare capacity buffers Atlantic basin supply disruptions.
United States
Permian Basin NGL extraction feeds Gulf Coast ethylene crackers expanding for packaging polymer demand. EPA methane monitoring rules under the Clean Air Act accelerate optical gas imaging deployment across Texas and New Mexico wellheads. Houston Ship Channel infrastructure concentrates export liquefaction capacity, though FERC permitting timelines stretch project horizons.
China
Sinopec and PetroChina commission integrated refining-petrochemical complexes converting residue directly into aromatics and olefins. MEE dual carbon goals restrict standalone refinery approvals, favoring carbon-efficient integration over fuel-only production. Yangtze River Delta clusters around Shanghai and Ningbo anchor the country's highest-margin petrochemical processing.
Saudi Arabia
Spare crude production capacity enables rapid output adjustments during Atlantic basin supply disruptions. Saudi Aramco leverages this buffer to secure long-term offtake agreements with Asian refiners seeking supply security. Eastern Province industrial cities Jubail and Yanbu concentrate downstream conversion into high-value synthetic materials and specialty chemicals.
Germany
Chemical manufacturers along the Rhine corridor face EU F-Gas Regulation phase-down schedules redirecting industrial refrigerant demand toward hydrocarbon alternatives. CSRD disclosure mandates compel emissions reporting architecture upgrades across BASF and Bayer supply chains. Ludwigshafen and Leverkusen clusters pioneer pyrolysis-oil integration for plastic waste circularity credentials.
South Korea
Ethylene derivative operations in Ulsan and Yeosu consolidate procurement through long-term naphtha offtake agreements indexed to regional benchmarks rather than crude-linked formulas. This restructuring transfers price volatility risk upstream to integrated producers. Daesan and Yeosu complexes represent the densest concentration of export-oriented polymer production in Northeast Asia.
Hydrocarbon Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and logistics niches. The vendor base organizes around three tiers: national oil companies with sovereign production access, integrated majors with trading-to-retail spans, and independent upstream operators focused on basin-specific extraction. Strategic moves concentrate on methane compliance outsourcing, carbon capture retrofit partnerships, and long-term offtake restructuring toward regional benchmark pricing.
Among state-backed platform operators, Saudi Arabian Oil Co. and PetroChina exemplify the national champion archetype with sovereign production buffers and downstream integration mandates. Exxon Mobil Corporation anchors the integrated major tier, leveraging Permian position to serve Atlantic and Pacific basin demand. Shell plc occupies the trading-optimized position, spanning production, shipping, and regasification terminal access.
| Leading Market Players |
|---|
| TotalEnergies |
| BP p.l.c. |
| Exxon Mobil Corporation |
| Reliance Industries Limited |
| ConocoPhillips |
| Saudi Arabian Oil Co. |
| Chevron |
| PetroChina |
| Shell plc |
| Others |
Pricing and Supply Chain Analysis
Houston Ship Channel infrastructure concentrates Gulf Coast liquefaction capacity, anchoring US export pricing power against Asian naphtha-indexed contracts. China's Yangtze River Delta clusters and Middle East spare capacity buffers create a three-cornered pricing dynamic where regional benchmark shifts transfer volatility risk upstream.
Pricing Analysis
Configured-to-order pricing for specialty olefins and aromatics commands substantial premiums over standard fuel-grade commodities. Contract-based long-term offtake agreements indexed to regional naphtha benchmarks dominate ethylene and propylene procurement, while spot markets handle residual crude and natural gas volumes. Price differentiation rests on carbon intensity certification and vertical integration depth, with integrated refining-petrochemical complexes capturing margin through residue upgrading. Cost compression in standard fuel grades is intensifying because China's MEE dual carbon restrictions constrain standalone refinery approvals, making polymer-grade buyers least price-sensitive and power generation utilities most exposed.
Supply Chain Analysis
Upstream feedstock flows draw from Permian Basin NGL extraction, Saudi Arabian spare crude capacity, and North Sea natural gas production. Raw material dependencies center on methane-rich natural gas, heavy sour crude residues, and polymer-grade ethane fractions. Single-source vulnerability concentrates in Gulf Coast cracker complexes dependent on Texas and New Mexico wellhead supply. Distribution runs through long-haul LNG carriers, transcontinental pipeline networks, and integrated trading desks spanning production through regasification terminal access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrocarbon market operates as a defensive-moat structure where regulatory entrenchment creates durable barriers. Switching costs lock in long-term offtake relationships, while capital intensity and permitting timelines deter rapid competitive entry.
For Market Incumbents: Insulate margin pools through backward integration into Permian Basin NGL extraction and carbon capture retrofit partnerships at Gulf Coast steam methane reforming facilities. EPA methane monitoring mandates threaten smaller independents without integrated midstream arms, creating consolidation leverage for operators with optical gas imaging deployment scale.
For New Entrants and Emerging Players: Pursue small-scale LNG bunkering infrastructure in Singapore and Rotterdam port corridors where regulatory mandates for cleaner marine fuels outpace incumbent buildout. Pyrolysis-oil integration for plastic waste circularity offers white-space entry with Extended Producer Responsibility compliance premiums in France and Germany.
For Investors and Strategic Acquirers: Carve-out targets emerge from national oil company downstream divestiture programs seeking capital discipline focus. Long-term viability favors integrated complexes with residue upgrading capability and regional benchmark pricing exposure. Watch for inflection in satellite-based methane quantification standardization between OGMP 2.0 and EPA super-emitter programs.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | Post-combustion amine scrubbing at Gulf Coast crackers accesses EU Innovation Fund certification. |
| Long-term Naphtha Offtake Agreement | South Korean and Taiwanese ethylene derivatives secure supply security against crude-linked volatility. |
| Small-scale LNG Bunkering Buildout | Singapore and Rotterdam port mandates create infrastructure demand for containerized liquefaction systems. |
| Pyrolysis-oil Integration Joint Venture | Chemical recycling partnerships with BASF and Bayer satisfy German Extended Producer Responsibility frameworks. |
| Advanced Process Control Deployment | Digital twin virtualization at European brownfield sites compresses optimization cycles without mechanical overhaul. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA production data, FERC permitting filings, IEA supply forecasts, and SEC 10-K disclosures from integrated majors. Interviews with Permian Basin operators, Gulf Coast cracker plant managers, Asian petrochemical procurement leads, and European refinery technical directors inform demand and capacity assumptions. Bottom-up unit economics triangulate against top-down trade flow analysis across Atlantic and Pacific basin corridors.
Forecast inputs span crude grade slates, ethylene cracker operating rates, LNG liquefaction capacity additions, and regional regulatory stringency differentials. Segmentation dimensions include product type, processing technology, end-use industry, and geographic production hub clustering. CAGRs derive from capacity utilization trends, feedstock cost trajectories, and margin compression patterns across the projection horizon. Methane compliance cost curves and carbon capture retrofit economics shape upstream investment timing assumptions.
Sensitivities concentrate around EPA supplemental methane proposal implementation timelines, EU F-Gas Regulation phase-down acceleration, and China MEE refinery approval discretion. Forecasts reflect documented assumptions about Permian Basin productivity maintenance and Asian naphtha benchmark stability. Cross-checking against IEA World Energy Outlook supply projections is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
South Africa Refined Petroleum Products Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Petcoke Market
Petroleum Products
Pale Oil Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Europe Refined Petroleum Products Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Pyrolysis Gasoline Market
Petroleum Products
Pyrolysis Oil Market
Petroleum Products
Oil Shale Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Base Oil Market
Petroleum Products
Petroleum Wax Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Africa Refined Petroleum Products Market