
 Automotive Oil Market | 2026-2036
Automotive Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Market Outlook
Specialized lubricant chemist talent is rotating from conventional blending toward additive synthesis and Group III/IV base oil engineering, tightening the labor pool for legacy formulation expertise. ExxonMobil Corporation leverages its integrated base stock production to secure feedstock cost advantages across the Americas. Royal Dutch Shell anchors its position through premium synthetic portfolios aligned with OEM factory-fill specifications. BP competes in emerging markets via localized blending capacity and regional brand equity.
Automotive oil comprises refined petroleum base stocks or synthesized hydrocarbons compounded with detergent, dispersant, anti-wear, and viscosity modifier additives to reduce friction, dissipate heat, and suspend combustion byproducts in internal combustion engines. Manufacturing involves hydrocracking, isomerization, or polyalphaolefin synthesis followed by precise additive dosing to meet SAE viscosity and API service categories. Synthetic oil commands expanding share as OEMs specify 0W-20 and 5W-30 grades for turbocharged direct-injection engines requiring thermal stability. Passenger vehicles sustain the largest end-user revenue pool, while commercial vehicles generate higher per-unit margins through extended-drain premium formulations. Distribution through service stations captures the highest-margin installed base, though online sales channels are gaining share among DIY consumers.
API SP and ILSAC GF-6 standards in the US, ACEA sequences in Europe, and China VI emissions rules collectively force lower-viscosity, lower-ash formulations that raise R&D barriers and reformulation costs. EPA fuel economy regulations and the EU Green Deal's transport decarbonization targets indirectly tighten lubricant performance requirements through engine efficiency mandates. Stakeholders must monitor OEM factory-fill specification evolution and base oil supply tightness as electrification rates vary by region and hybrid architectures prolong ICE lubricant relevance.
Market Dynamics
ICE-to-hybrid powertrain diversification is fragmenting lubricant specification requirements as OEMs demand parallel development tracks for conventional, mild-hybrid, and PHEV architectures within single vehicle platforms.
Growth Catalysts
- EPA fuel economy mandates:Tighter corporate average fuel economy standards force OEMs to specify 0W-16 and 0W-20 grades, expanding synthetic formulation demand across the US passenger vehicle fleet.
- Commercial fleet electrification hesitation:Long-haul operators in Brazil and India delay full electrification timelines, sustaining ICE lubricant volume through extended-drain premium products.
- Group III base oil capacity expansion:Refinery upgrades across the Middle East lower synthetic feedstock costs, enabling wider geographic penetration of API SP-compliant formulations.
Market Restraints
- API SP/ILSAC GF-6 compliance costs:Reformulation to meet lower-ash, lower-phosphorus specifications raises R&D expenditure and compresses margin for mid-tier blenders.
- Base stock supply concentration:Group II/III production clusters in South Korea and Singapore create geographic chokepoints vulnerable to regional refining outages.
- EV drivetrain substitution:Battery electric vehicle sales in Norway and the Netherlands eliminate ICE lubricant demand entirely in premium passenger segments.
Strategic Opportunities
- India two-wheeler synthetic conversion:Rising disposable income in Maharashtra and Tamil Nadu creates first-time synthetic demand among motorcycle owners previously using mineral grades.
- EU Green Deal transport decarbonization:CO2-based vehicle taxation schemes indirectly reward low-viscosity lubricants that contribute to fleet efficiency targets.
- Direct-to-garage digital platforms:Independent repair shops in Mexico and Indonesia bypass traditional distributor tiers through B2B procurement apps, capturing margin compression.
Industry Challenges
- Additive chemist scarcity:Specialized formulators with expertise in molybdenum dithiocarbamate and boron compounds command premium compensation, constraining mid-size blender expansion.
- OEM factory-fill certification timelines:Volkswagen, Toyota, and General Motors require 18-24 month validation cycles for new lubricant approvals, freezing formulation innovation windows.
- Hybrid cooling system integration:Dual-circuit thermal management in PHEVs demands lubricants compatible with both combustion engine and electric motor temperature regimes, complicating specification matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Market |
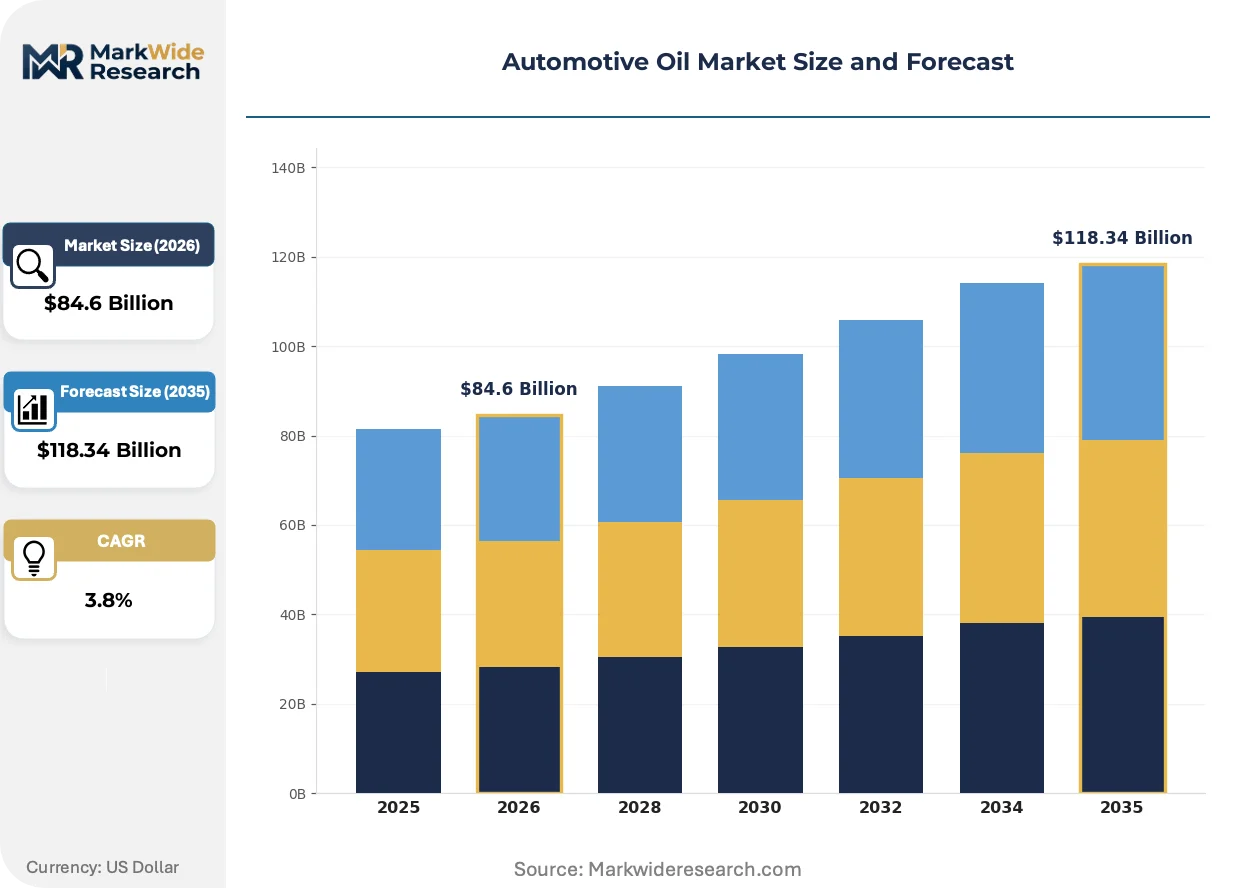
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $118.34 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oil, Conventional Oil, High Mileage Oil, Additives End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Industrial Equipment Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Distribution Channel: Retail Stores, Online Sales, Service Stations, Wholesalers |
| Companies Covered | ExxonMobil Corporation, Royal Dutch Shell, BP, TotalEnergies, Chevron Corporation, Valvoline, Castrol, China National Petroleum Corporation, Sinopec Lubricant Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Market Strategic Shifts
Reformulation priorities are pivoting from friction reduction alone toward multi-physics performance spanning thermal management, electrical conductivity control, and material compatibility with electrified powertrains.
Polyalphaolefin (PAO) and ester-based synthetics are fragmenting the premium segment as OEMs specify divergent chemistries for turbocharged gasoline direct injection versus Atkinson-cycle hybrid applications. Ford and Hyundai have adopted divergent base stock strategies for their respective EcoBoost and Smartstream engine families. This divergence is fragmenting blender R&D budgets across incompatible development tracks.
China's dual carbon goals and corresponding GB 18352.6-2016 emissions standards are forcing domestic lubricant producers toward lower-viscosity, lower-sulfated ash formulations previously dominated by multinational suppliers. Local blenders in Shandong and Guangdong provinces are investing in hydrocracking capacity to capture this specification upgrade. The policy shift is compressing import dependence for high-performance base stocks.
Service stations and quick-lube chains are unbundling oil change intervals from traditional 5,000-kilometer fixed schedules toward condition-based monitoring via onboard oil life algorithms. Jiffy Lube and Valvoline Instant Oil Change in the US have introduced flexible pricing tied to OEM-recommended intervals rather than arbitrary timeframes. This behavioral shift is most visible in California and Texas, where telematics penetration in fleet vehicles exceeds 40 percent.
Automotive Oil Market Segmentation
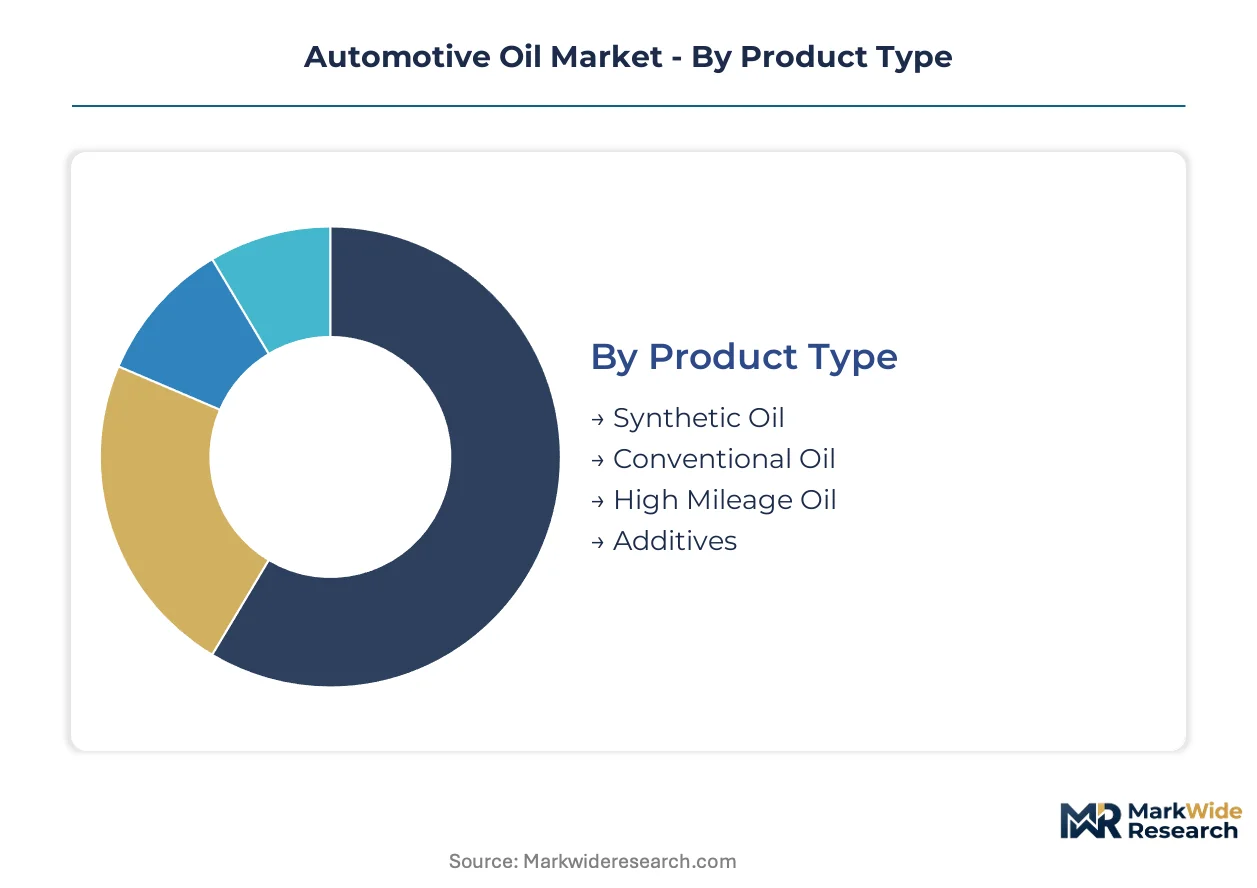
Automotive oil segmentation reveals how formulation chemistry, application severity, and procurement channel intersect to determine margin structure. Channel mix varies sharply across product tiers, with synthetic grades concentrating in OEM-certified service networks while conventional oils flow through retail and wholesale tiers.
Product Type:
Synthetic formulations command premium positioning through authorized dealer and quick-lube channels, while conventional and high-mileage variants distribute more heavily through retail and wholesale tiers.
- Synthetic Oil:Group III/IV base stocks compounded with advanced additive packages deliver thermal stability for turbocharged direct-injection engines. Demand concentrates in US and Japanese OEM factory-fill specifications as EPA fuel economy mandates tighten viscosity requirements. The segment captures the highest per-liter margins through certified service networks.
- Conventional Oil:Refined petroleum base stocks with standard detergent and dispersant additives serve legacy vehicle fleets and price-sensitive maintenance schedules. Volume clusters in emerging markets including India and Brazil where mineral-grade consumption persists among older vehicle parc. Cost-driven procurement through wholesale channels dominates.
- High Mileage Oil:Seal conditioners and anti-wear additives formulated for engines exceeding 120,000 kilometers. DIY consumers in North American retail channels drive volume.
- Additives:Supplementary friction modifiers and detergents sold separately for performance enhancement. Enthusiast segments and independent garages in online channels sustain demand.
By volume, Conventional Oil leads. By growth pace, Synthetic Oil is expanding most quickly.
End User:
Application severity and operating duty cycles create divergent margin profiles, with commercial and industrial segments tolerating premium pricing for extended-drain formulations.
- Passenger Vehicles:Light-duty gasoline and diesel engines in personal transportation applications. Synthetic 0W-20 and 5W-30 grades specified by Toyota, Honda, and Volkswagen for new vehicle warranties. Service station channels capture installed base maintenance.
- Commercial Vehicles:Heavy-duty diesel engines in long-haul trucking and logistics fleets. Extended-drain synthetic formulations reduce downtime for operators in Brazil and India where electrification timelines lag. Per-unit margins exceed passenger segments through volume contracting.
- Motorcycles:Small-displacement engines with high RPM thermal stress. Two-wheeler synthetic conversion accelerates in Maharashtra and Tamil Nadu as disposable income rises.
- Industrial Equipment:Stationary engines and off-highway machinery. Wholesale distributor networks dominate procurement with bulk pricing structures.
Passenger Vehicles generates the largest revenue pool. Commercial Vehicles delivers the steepest margin expansion trajectory.
Viscosity Grade:
Specification tightening by OEMs and regulators is compressing demand toward lower-viscosity grades that flow through certified service channels.
- 0W-20:Ultra-low viscosity synthetic formulations mandatory for latest-generation turbocharged gasoline direct-injection engines. Factory-fill specifications by Ford EcoBoost and Hyundai Smartstream families concentrate demand in US, Japan, and South Korea. Cold-start protection requirements in northern climates sustain volume.
- 5W-30:Mid-range synthetic and synthetic-blend formulations serving broad temperature operating windows. The most widely specified grade across European ACEA sequences and US API SP categories. Balances fuel economy gains with hardware protection for hybrid architectures.
- 10W-40:Higher-viscosity conventional and semi-synthetic grades for older vehicle fleets and high-temperature climates. Residual demand in Middle East and Southeast Asian markets.
- 15W-50:Heavy-duty viscosity grade for performance engines and severe operating conditions. Enthusiast and motorsport applications in niche distribution.
5W-30 dominates current volume. 0W-20 posts the fastest specification migration rate.
Distribution Channel:
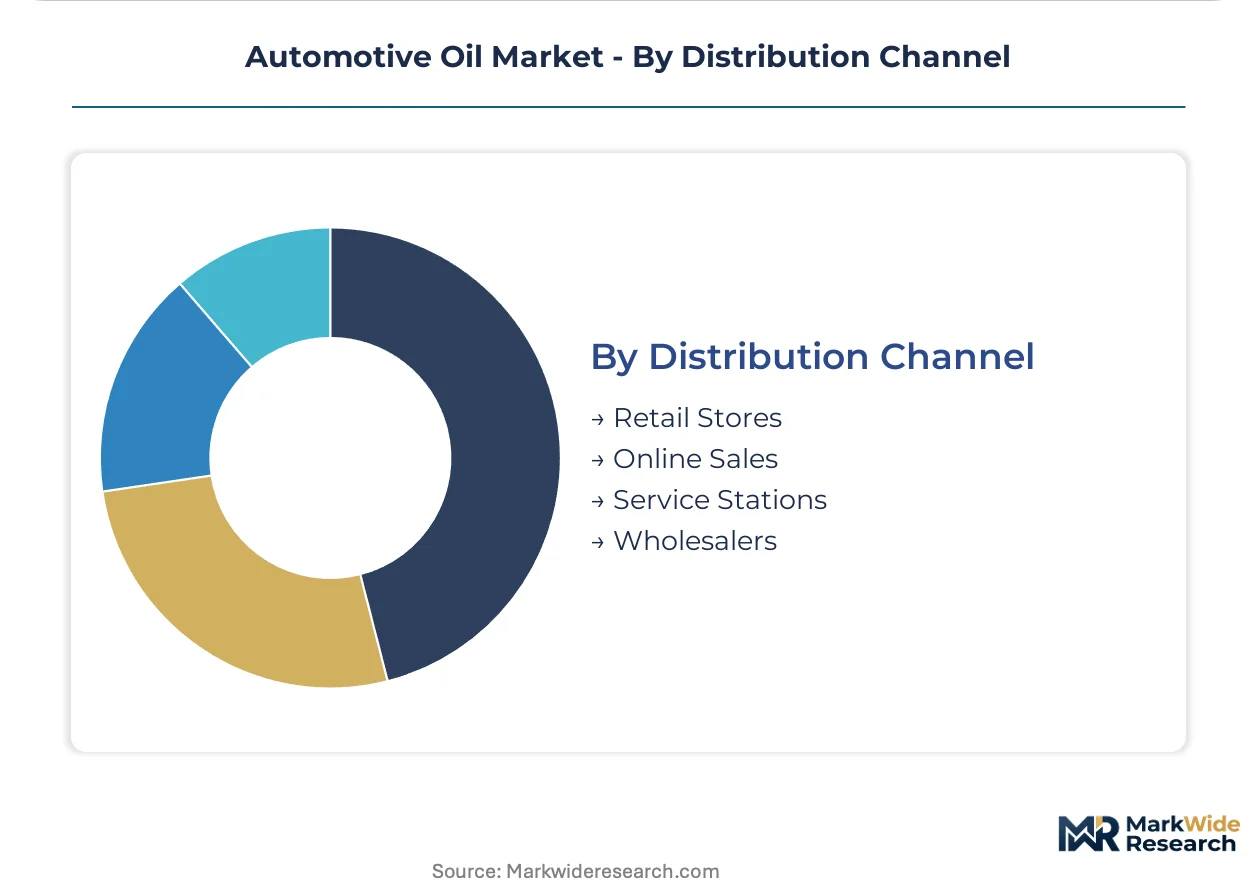
Channel selection directly determines margin capture, with service networks extracting premium pricing through OEM certification while online and wholesale tiers compete on cost.
- Service Stations:Branded quick-lube chains and OEM-authorized facilities. Jiffy Lube and Valvoline Instant Oil Change in California and Texas have introduced condition-based pricing tied to onboard oil life algorithms rather than fixed intervals. Highest-margin channel through installed base lock-in.
- Retail Stores:Mass merchandisers and auto parts chains stocking DIY consumer grades. Walmart and AutoZone in the US, plus equivalent chains in Europe and Asia, compete on private-label and national brand shelf placement. Price transparency compresses margins.
- Online Sales:Direct-to-consumer and B2B platforms gaining share among informed DIY purchasers. Amazon and specialized lubricant e-tailers in Germany and Japan offer subscription replenishment models.
- Wholesalers:Regional distributors supplying independent garages and fleet operators. Mexico and Indonesia see independent repair shops bypassing traditional tiers through B2B procurement apps.
Service Stations command the highest revenue per transaction. Online Sales climbs the fastest in channel mix evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service stations in Germany and the Netherlands extract 15-20% price premiums over comparable channels in Brazil and India, where wholesale distributors dominate procurement. This pricing-power asymmetry reflects specification intensity, certification requirements, and channel concentration rather than base oil cost differentials alone.
United States
EPA fuel economy mandates and NHTSA corporate average fuel economy standards force OEMs to specify 0W-16 and 0W-20 synthetic grades. California and Texas lead condition-based oil change adoption through telematics penetration exceeding 40% in fleet vehicles. Jiffy Lube and Valvoline Instant Oil Change have introduced flexible pricing tied to onboard oil life algorithms.
Germany
ACEA sequences and EU Green Deal transport decarbonization targets reward low-viscosity lubricants contributing to fleet efficiency. KBA type-approval requirements tighten factory-fill certification timelines. The Stuttgart and Munich industrial corridors concentrate additive synthesis and Group III base oil engineering talent.
China
GB 18352.6-2016 emissions standards and dual carbon goals force domestic producers toward lower-viscosity, lower-sulfated ash formulations. Local blenders in Shandong and Guangdong provinces invest in hydrocracking capacity to reduce import dependence for high-performance base stocks. MIIT industrial policy supports this specification upgrade trajectory.
India
Rising disposable income in Maharashtra and Tamil Nadu creates first-time synthetic demand among two-wheeler owners previously using mineral grades. BIS specification evolution lags ACEA and API standards, creating a tiered market structure. Fleet operators in Gujarat delay electrification timelines, sustaining ICE lubricant volume through extended-drain premium products.
Brazil
Long-haul commercial operators sustain ICE lubricant demand through extended-drain formulations as full electrification timelines lag. ANVISA environmental regulations intersect with CONTRAN vehicle safety standards to shape lubricant specifications. The São Paulo industrial corridor concentrates regional blending capacity serving Mercosur markets.
Automotive Oil Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated majors with captive base stock production compete against specialized blenders focused on additive formulation excellence. Three archetypes dominate: upstream-integrated petroleum majors, regional blending specialists with OEM certification relationships, and state-affiliated national champions in emerging markets. Competitive moves center on refinery upgrades for Group III capacity expansion and strategic partnerships for factory-fill specification access.
Among integrated petroleum majors, ExxonMobil Corporation and Royal Dutch Shell occupy positions reflecting upstream base stock control and premium synthetic portfolio breadth. BP sits within the tier emphasizing emerging market localization. State-affiliated representation includes China National Petroleum Corporation and Sinopec Lubricant Company, exemplifying national champion structures serving domestic specification upgrades.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Royal Dutch Shell |
| BP |
| TotalEnergies |
| Chevron Corporation |
| Valvoline |
| Castrol |
| China National Petroleum Corporation |
| Sinopec Lubricant Company |
| Others |
Value Chain & Pricing Dynamics
Group III base oil refinery scale economies in South Korea and Singapore compress unit costs for synthetic formulations while simultaneously concentrating supply-side bargaining power among integrated majors. This concentration elevates price floors for mid-tier blenders lacking captive feedstock production, forcing margin compression or backward integration investments.
Pricing Analysis
The customization-premium spread between OEM-certified factory-fill formulations and standard aftermarket grades spans certification investment recovery and technical service bundling. Three-tier pricing structure across premium synthetic, mid-grade synthetic-blend, and economy mineral tiers segments buyers by specification intensity and channel access. Pricing pressure stems from API SP/ILSAC GF-6 compliance costs raising R&D expenditure for reformulation to lower-ash, lower-phosphorus standards. Fleet operators exhibit highest price sensitivity through volume contracting, while OEM-authorized service networks tolerate premium positioning through installed base lock-in.
Supply Chain Analysis
South Korea, Singapore, and the Middle East anchor Group II/III base stock production through refinery upgrades and hydrocracking capacity expansion. Automotive oil formulation draws from polyalphaolefin synthesis, detergent additive packages, and viscosity modifier compounds as critical inputs. Single-source vulnerability concentrates in geographic chokepoints where regional refining outages disrupt feedstock availability for dependent blenders. Distribution runs through service station networks capturing highest-margin installed base, with wholesale tiers serving price-sensitive emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive oil markets are restructuring around service-attach revenue layers, with condition-based monitoring and flexible interval pricing expanding faster than per-liter product sales. Recurring revenue from telematics-integrated maintenance programs and subscription replenishment models is displacing transactional hardware margins.
For Market Incumbents: Secure additive synthesis talent pools through targeted compensation structures and technical training pipelines, as molybdenum dithiocarbamate and boron compound expertise tightens labor availability. Defend factory-fill certification relationships against 18-24 month OEM validation timelines by pre-positioning next-generation formulations ahead of specification shifts. Capacity addition in Shandong and Guangdong provinces captures domestic specification upgrades as China's dual carbon goals compress import dependence.
For New Entrants and Emerging Players: Direct-to-garage digital platforms represent a service-layer gap where traditional distributor tiers extract margin from independent repair shops in Mexico and Indonesia. First-time synthetic conversion among two-wheeler owners in Maharashtra and Tamil Nadu offers penetrable white-space as disposable income rises above mineral-grade substitution thresholds. B2B procurement apps bypassing wholesale intermediaries provide a go-to-market angle for regional blending specialists seeking channel disintermediation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive formulation specialists with OEM certification relationships over upstream-integrated majors facing electrification volume risk. Long-term viability rests on hybrid architecture persistence prolonging ICE lubricant relevance alongside factory-fill specification access. Acquisition target archetypes include regional blenders with localized capacity and emerging market brand equity. The inflection indicator to monitor is EV sales penetration in Norway and the Netherlands eliminating premium passenger segment demand entirely.
| Strategic Initiative | Industry Significance |
|---|---|
| Group III Base Oil Capacity Expansion | Refinery upgrades in the Middle East lower synthetic feedstock costs for API SP-compliant formulations. |
| OEM Factory-Fill Certification Investment | Eighteen-to-twenty-four month validation cycles with Volkswagen and Toyota freeze competitor innovation windows. |
| Direct-to-Garage Digital Platform Launch | B2B procurement apps in Mexico and Indonesia capture margin compression from traditional distributor tiers. |
| Additive Synthesis Talent Acquisition | Specialized chemist expertise in friction modifier compounds constrains mid-size blender expansion capacity. |
| Condition-Based Monitoring Integration | Telematics penetration exceeding forty percent in California and Texas fleet vehicles enables flexible interval pricing. |
Study Parameters
Operator-level perspectives from lubricant blenders, OEM platform engineers, aftermarket distributors, and commercial fleet procurement managers anchored the qualitative base for this study. Primary interviews with these stakeholders combined with secondary validation from API service category documentation, ACEA sequence publications, EPA fuel economy filings, and customs trade data for base stock flows. Bottom-up volume modeling across viscosity grades and end-use segments triangulated against top-down market sizing from refinery capacity and vehicle parc projections.
Sensitivity analysis framed the analytical approach across the projection horizon, with segmentation dimensions spanning formulation chemistry, vehicle propulsion architecture, operating duty cycle severity, and regional regulatory cluster. CAGRs were derived from modeled volume and value outputs reflecting specification migration rates, electrification pace variation by geography, and hybrid architecture penetration. Industry-specific forecast inputs included OEM factory-fill specification evolution timelines and base oil supply tightness indicators.
Underlying assumptions cover electrification rate variation by region, hybrid architecture persistence, and additive package cost trajectories, with deviation risk concentrated in EV substitution pace in premium passenger segments and refinery outage frequency in Group II/III production clusters. Recalibration cycles align with material shifts in EPA fuel economy mandates, EU Green Deal transport targets, and China VI emissions implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
Hydrocarbon Market
Petroleum Products
Alkylate Gasoline Market
Petroleum Products
Asia Pacific Base Oil Market
Petroleum Products
Petcoke Market
Petroleum Products
Saudi Arabia Refined Petroleum Products Market
Petroleum Products
India White Oil Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
Global Petroleum Coke Market
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Automotive Oil Strainer Market
Petroleum Products
Germany Refined Petroleum Products Market
Petroleum Products
Asia-Pacific Lubricants Market
Petroleum Products
Pale Oil Market
Petroleum Products
Paraffin Oil Market
Petroleum Products
France Refined Petroleum Product Market